
 Window Rain Guards Market | 2026-2036
Window Rain Guards Market Size, Share, and Industry Trends Forecast 2026-2036
Window Rain Guards Market Analytics
Modular bundling of window rain guards with floor liners and mud flaps is repositioning how automotive accessory retailers structure their value propositions. WeatherTech leverages its vertically integrated manufacturing to control quality across bundled SKUs. AVS anchors its market presence through specialized channel relationships with major auto parts distributors. Lund International competes by sustaining broad coverage across domestic and import vehicle applications.
Window rain guards are thermoformed or injection-molded deflectors, typically manufactured from acrylic or polycarbonate, designed to channel airflow around partially open vehicle windows while blocking precipitation entry. Acrylic formulations dominate OEM-adjacent channels due to optical clarity and UV resistance, while polycarbonate variants lead in aftermarket performance segments where impact durability matters. In-Channel Guards capture premium positioning through cleaner aesthetic integration, yet Exterior Mount Guards retain volume leadership in the pickup truck category where door-frame geometry complicates flush installation. Clip-On and No-Drill methods are displacing screw-in alternatives as vehicle lease penetration rises and owners seek non-permanent modifications.
The National Highway Traffic Safety Administration (NHTSA) and Federal Motor Vehicle Safety Standards (FMVSS) govern peripheral visibility and protrusion limits that constrain rain guard dimensional specifications. State-level vehicle equipment codes in California and Texas further fragment compliance requirements for interstate sellers. Stakeholders must monitor how evolving FMVSS interpretations and state inspection protocols treat aftermarket window accessories, as regulatory divergence between jurisdictions could reshape product development priorities and distribution economics.
Market Dynamics
Pickup truck and SUV ownership patterns in the United States are concentrating replacement demand into specific vehicle segments, while lease penetration is forcing manufacturers toward non-permanent installation methods that preserve factory door-frame integrity.
Growth Catalysts
- FMVSS Visibility Standards:Federal Motor Vehicle Safety Standards governing peripheral sightlines create baseline product specifications that streamline aftermarket certification pathways for compliant manufacturers.
- Acrylic Formulation Advances:UV-stabilized acrylic compounds with enhanced optical clarity are expanding OEM-adjacent channel penetration where aesthetic integration commands premium positioning.
- Texas and California State Codes:Divergent vehicle equipment regulations across high-volume states are incentivizing modular product architectures that adapt to regional inspection protocols without full redesign.
Market Restraints
- Polycarbonate Resin Volatility:Engineering-grade polycarbonate feedstock costs fluctuate with benzene derivative markets, compressing margin structures for impact-durable product lines.
- Injection Molding Tooling Concentration:Precision thermoforming and injection mold fabrication capacity clusters in Guangdong province, creating geographic supply risk for North American producers.
- Adhesive Substitution Threat:Automotive-grade 3M VHB tape and similar bonding technologies are reducing mechanical fastener dependency, eroding hardware-inclusive SKU value propositions.
Strategic Opportunities
- Canadian Winter Climate Zones:Extended precipitation seasons and gravel road conditions in Alberta and Saskatchewan sustain above-average replacement frequencies for exterior-mount guard configurations.
- E-Commerce Direct-to-Consumer Channels:Amazon and specialized automotive platforms are capturing share from traditional auto parts distributors, enabling private-label margin expansion for vertically integrated manufacturers.
- EPA Fuel Economy Indirect Effects:Emissions standards shaping vehicle aerodynamics and window geometry are creating specification gaps that aftermarket accessory engineers can exploit with adaptive mounting systems.
Industry Challenges
- Multi-Jurisdictional Compliance Engineering:NHTSA federal standards, California Air Resources Board equipment codes, and Texas Department of Public Safety inspection criteria demand parallel validation protocols that extend product development timelines.
- Lease-Vehicle Installation Training:Rising lease penetration requires technician education on non-invasive clip-on methods that avoid paint damage claims, increasing channel support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Rain Guards Market |
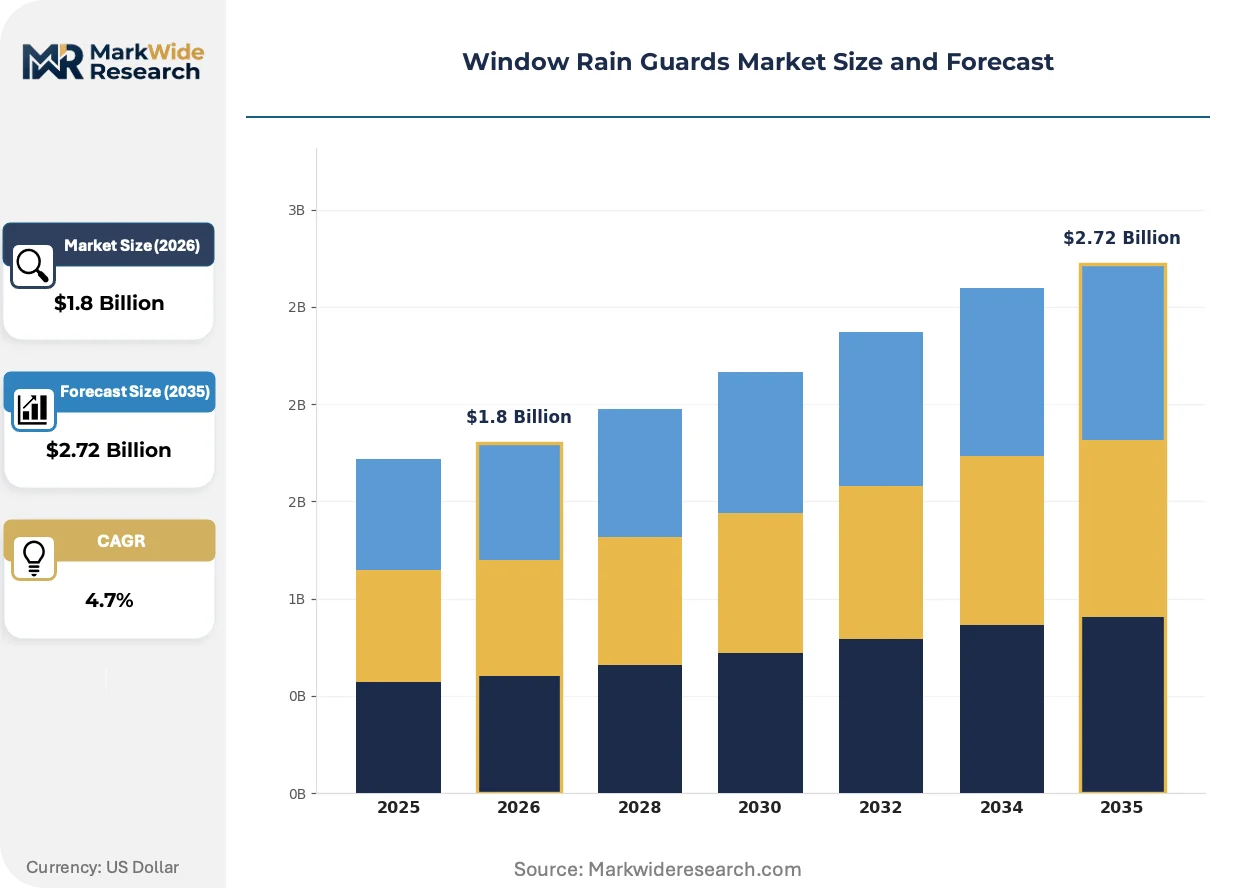
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Channel Guards, Exterior Mount Guards, Clip-On Guards, Adjustable Guards Material: Acrylic, Polycarbonate, Plastic, Rubber Vehicle Type: SUV, Sedan, Pickup Truck, Coupe Installation Method: Adhesive, Clip-On, No-Drill, Screw-In |
| Companies Covered | WeatherTech, AVS, EGR, Stampede, Lund International, GTS, Auto Ventshade, Deflecta-Shield, Husky Liners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Rain Guards Market Evolving Landscape
Material science breakthroughs and installation method evolution are compressing product lifecycles while regulatory fragmentation across North American jurisdictions is forcing adaptive design architectures.
Thermoformed polycarbonate blends with impact-modified additives are overtaking conventional acrylic in aftermarket performance segments. Off-road enthusiasts and commercial fleet operators are adopting these formulations for stone-chip resistance in gravel and construction environments. This material shift is enabling thinner cross-section designs that reduce aerodynamic drag penalties while maintaining structural integrity.
NHTSA interpretations of FMVSS 571.111 regarding driver field of view are tightening dimensional tolerances for window-mounted accessories. Manufacturers must now submit protrusion measurements and optical distortion testing that previously fell outside enforcement scope. Pickup truck applications with extended cab configurations face the most stringent visibility verification requirements, driving investment in computational fluid dynamics simulation for airflow certification.
Subscription-based vehicle access models are compressing ownership tenures and fragmenting upgrade decision authority. Fleet management companies and mobility-as-a-service operators now control accessory specification for pooled vehicle assets, displacing individual owner preferences. This concentration is most visible in urban California markets where car-sharing penetration exceeds national averages by substantial margins.
Window Rain Guards Market Segmentation
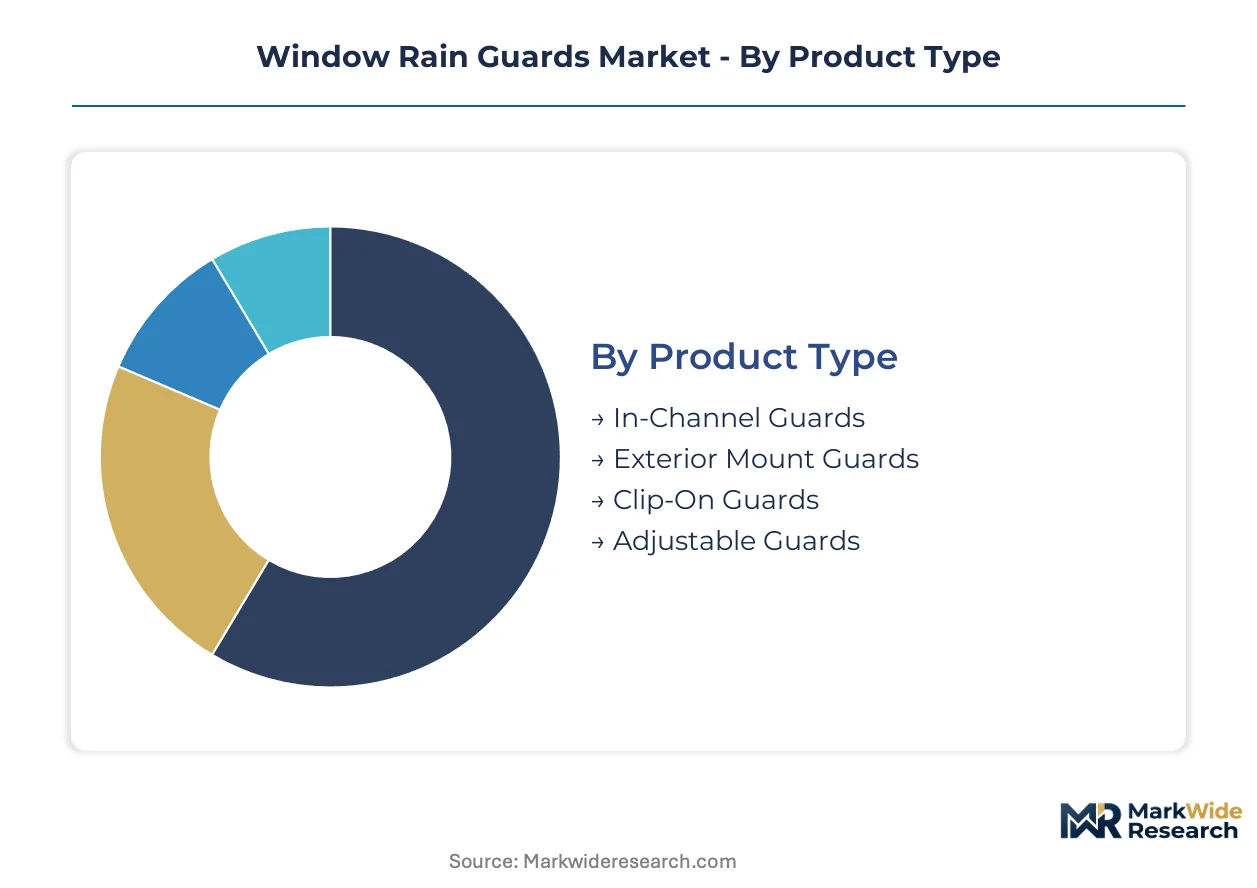
Window rain guard manufacturers engineer product architectures around four distinct axes: mounting geometry, material formulation, vehicle body style, and installation permanence. Each segmentation dimension carries specific regulatory, supply chain, and margin implications that reshape competitive positioning across OEM-adjacent and aftermarket channels.
Product Type:
Thermoforming precision and door-frame geometry compatibility define competitive differentiation across mounting configurations.
- In-Channel Guards:These deflectors seat within the window channel itself, requiring millimeter-tolerance molding to preserve glass sealing integrity. Demand concentrates in premium SUV segments across California and Texas, where owners prioritize factory-integrated aesthetics over cost minimization.
- Exterior Mount Guards:Surface-applied deflectors attach via adhesive or mechanical fasteners to the door frame exterior. Pickup truck owners in Alberta and Saskatchewan sustain replacement cycles due to gravel-road abrasion and extended precipitation seasons.
- Clip-On Guards:Spring-loaded retention systems enable tool-free installation without surface adhesion. Fleet operators favor these for lease-return compliance.
- Adjustable Guards:Modular designs permit width and angle modification across multiple vehicle applications. Aftermarket distributors stock these for inventory flexibility.
Mature deployment sits with Exterior Mount Guards. Newer deployment is concentrated in In-Channel configurations.
Material:
Resin selection trades optical clarity against impact durability while navigating benzene derivative cost volatility.
- Acrylic:UV-stabilized polymethyl methacrylate formulations deliver superior light transmission and weathering resistance. OEM-adjacent channels in the United States specify acrylic for visibility-critical applications where NHTSA optical distortion standards apply.
- Polycarbonate:Engineering-grade aromatic carbonate polymers with impact modifiers withstand stone-chip damage in off-road and construction environments. Aftermarket performance segments in gravel-road regions favor these formulations despite feedstock price volatility.
- Plastic:Commodity thermoplastics serve economy-tier replacement demand through mass-market auto parts retailers.
- Rubber:Elastomeric edge seals and gaskets complement rigid deflector bodies for vibration damping and weather sealing.
Volume leadership belongs to Acrylic. Steepest expansion trajectory is occurring in Polycarbonate blends.
Vehicle Type:
Body style geometry dictates deflector curvature, mounting point locations, and aerodynamic load calculations.
- SUV:Tall greenhouse profiles and vertical rear glass create complex airflow patterns requiring extended deflector lengths. Suburban family ownership patterns in Texas and California sustain steady replacement demand.
- Pickup Truck:Extended cab configurations with vent windows and door-frame protrusions present unique installation challenges. This segment commands specialized product lines due to FMVSS visibility verification requirements for driver field of view.
- Sedan:Lower rooflines and aerodynamic glass angles permit standardized deflector designs across multiple nameplates.
- Coupe:Frameless door glass and minimal window channels limit compatible mounting systems to premium in-channel solutions.
Replacement frequency peaks with Pickup Truck applications. Design complexity concentrates in Coupe configurations.
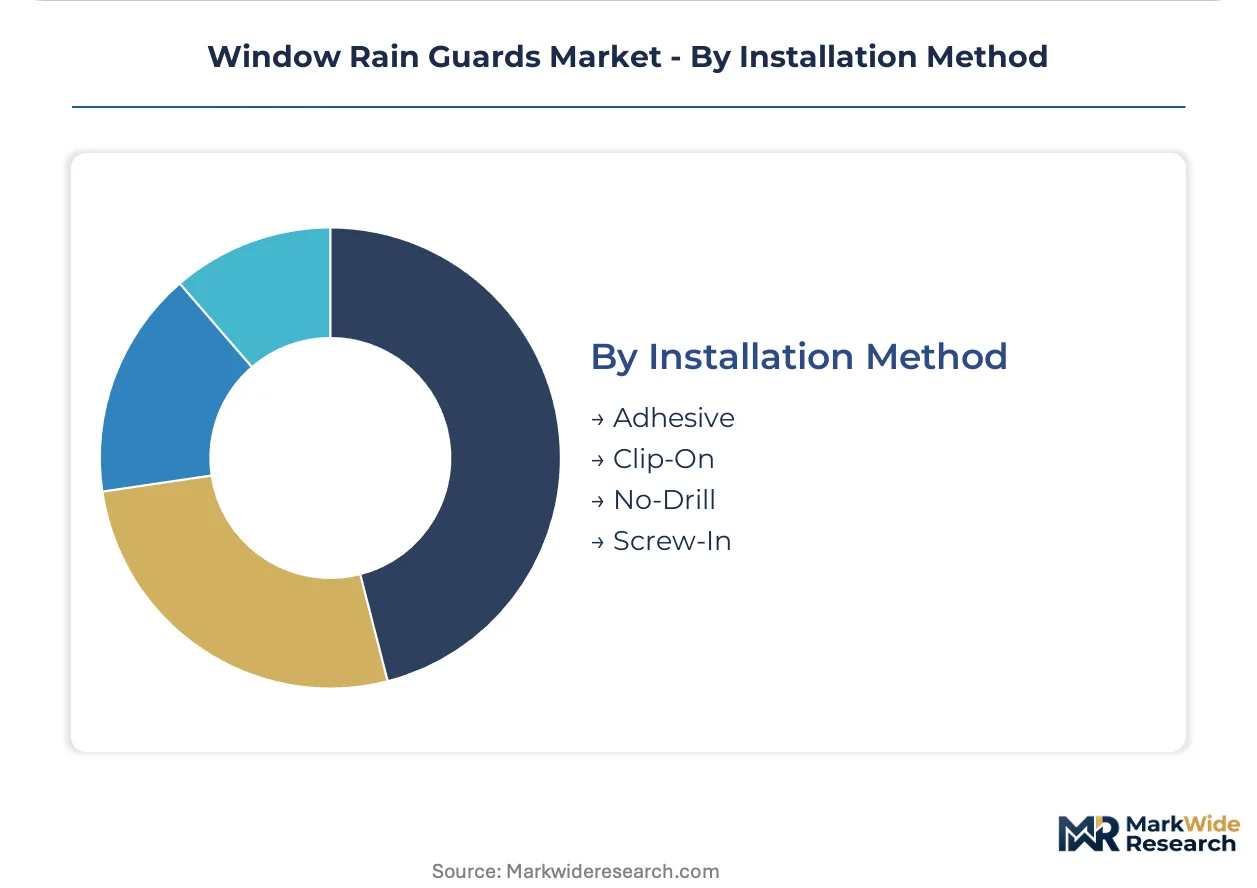
Installation Method:
Permanence preferences are shifting as lease penetration rises and paint damage liability concerns reshape channel economics.
- Adhesive:Automotive-grade bonding tapes eliminate mechanical fasteners while distributing stress across mounting surfaces. E-commerce direct-to-consumer channels favor these for DIY customer satisfaction.
- Clip-On:Spring-steel or polymer retention clips engage factory door-frame edges without surface modification. Fleet management companies specify these for pooled vehicle assets to avoid lease-end damage claims.
- No-Drill:Bracket systems utilize existing door hardware points without new perforations. Technician training programs emphasize these methods for rising lease penetration.
- Screw-In:Traditional mechanical fastening through drilled holes persists in commercial fleet applications where maximum retention strength outweighs reversibility concerns.
Declining share characterizes Screw-In methods. Gaining share fastest are Clip-On and No-Drill alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 74 in El Paso concentrates cross-border manufacturing capacity for automotive accessories serving North American aftermarket channels. This zone structure accelerates component flow between Texas-based thermoforming operations and Mexican assembly plants.
United States
Pickup truck ownership in Texas and California sustains replacement cycles for exterior-mount configurations. NHTSA FMVSS 571.111 visibility standards constrain dimensional specifications for deflector protrusion. Detroit-area automotive suppliers coordinate with Guangdong mold fabricators to manage tooling lead times.
Canada
Extended winter precipitation seasons in Alberta and Saskatchewan drive above-average replacement frequencies for gravel-road abrasion damage. Transport Canada Motor Vehicle Safety Standards align with federal visibility requirements. Toronto-area distributors stock modular clip-on configurations for lease-fleet compliance.
Mexico
Maquiladora operations in Nuevo León and Chihuahua assemble injection-molded components for US aftermarket channels. PROFEPA environmental regulations govern resin processing emissions at border-zone facilities. Tijuana manufacturing clusters specialize in adhesive bonding systems for DIY installation kits.
Germany
Aftermarket demand concentrates in SUV segments where owners prioritize optical clarity for autobahn driving conditions. KBA type-approval requirements for exterior vehicle modifications exceed baseline EU standards. Stuttgart-area automotive suppliers develop computational fluid dynamics simulation for aerodynamic certification.
China
Guangdong province hosts precision thermoforming and injection mold fabrication capacity serving global producers. MIIT automotive component standards and GB/T quality certifications shape export-ready product specifications. Shenzhen industrial clusters manufacture acrylic and polycarbonate resin formulations for OEM-adjacent channels.
Window Rain Guards Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: vertically integrated manufacturers controlling resin-to-retail operations, channel-specialized distributors leveraging auto parts retailer relationships, and private-label suppliers serving mass-market price points. Consolidation pressure intensifies as adhesive substitution and e-commerce disintermediation compress hardware-inclusive margins. Dominant competitive moves include backward integration into captive resin compounding and direct-to-consumer platform expansion.
Within the vertically integrated tier, WeatherTech exemplifies manufacturing control spanning bundled automotive accessory SKUs. AVS anchors channel-specialized positioning through distributor relationships with major auto parts retailers. Lund International occupies the broad-coverage archetype across domestic and import vehicle applications.
| Leading Market Players |
|---|
| WeatherTech |
| AVS |
| EGR |
| Stampede |
| Lund International |
| GTS |
| Auto Ventshade |
| Deflecta-Shield |
| Husky Liners |
| Others |
Value Network & Pricing Analysis
Captive resin compounding in Guangdong province anchors supply positioning for North American producers while insulating WeatherTech and AVS from benzene derivative volatility that compresses margin structures for non-integrated competitors.
Pricing Analysis
Short lead-time premiums command substantial markups for in-channel configurations serving Texas and California SUV owners, while spot inventory of exterior-mount guards for pickup trucks trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels separates OEM-adjacent acrylic formulations from aftermarket polycarbonate blends and commodity thermoplastic replacements. Cost compression in injection-molded SKUs is intensifying because adhesive bonding technologies erode hardware-inclusive value propositions. Fleet operators exhibit highest price sensitivity due to pooled-vehicle procurement scale, while individual lease-vehicle owners prioritize non-permanent installation methods regardless of cost premium.
Supply Chain Analysis
FMVSS 571.111 visibility certification gates access to US aftermarket channels, forcing parallel validation protocols that extend product development timelines for cross-border suppliers. Manufacturing concentrates in Guangdong province, Nuevo León maquiladora zones, and El Paso Foreign Trade Zone 74. Feedstock draws from benzene derivative markets, UV-stabilized acrylic resin formulations, and automotive-grade 3M VHB tape bonding systems. Single-source vulnerability concentrates in precision thermoforming mold fabrication capacity. Distribution runs through Amazon direct-to-consumer platforms, specialized automotive e-commerce sites, and traditional auto parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into captive resin compounding to secure margin control against polycarbonate feedstock volatility.
For Market Incumbents: To counter adhesive substitution technologies eroding hardware-inclusive SKU economics, WeatherTech and AVS should deepen control over captive acrylic resin formulation and expand direct-to-consumer platform presence to capture private-label margin expansion. For New Entrants and Emerging Players: Begin with modular clip-on configurations targeting Canadian fleet operators in Alberta and Saskatchewan, where gravel-road abrasion sustains above-average replacement frequencies and lease-return compliance requirements favor non-invasive installation methods. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified automotive accessory conglomerates seeking bundled SKU expansion. Long-term viability hinges on adaptive mounting system intellectual property and e-commerce fulfillment infrastructure. Watch NHTSA reinterpretations of FMVSS protrusion limits as inflection indicator for product development priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Guangdong-based captive supply of UV-stabilized acrylic insulates WeatherTech from benzene derivative volatility. |
| Direct-to-Consumer Platform Expansion | Amazon and specialized automotive e-commerce channels enable private-label margin expansion for vertically integrated manufacturers. |
| Adaptive Mounting System Development | Non-permanent clip-on and no-drill configurations address rising lease penetration and paint damage liability concerns. |
| Computational Fluid Dynamics Certification Investment | FMVSS 571.111 visibility verification requirements for pickup truck extended cab configurations demand simulation capabilities. |
| Modular Product Architecture Engineering | Regional compliance divergence between California Air Resources Board and Texas Department of Public Safety codes necessitates adaptable designs. |
Research Methodology
Multi-period observation of NHTSA regulatory interpretation shifts, resin feedstock cost trajectories, and e-commerce channel share capture anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, aftermarket distributor operations heads, OEM platform engineers, and automotive accessory retail category buyers. Secondary validation drew from EPA automotive emissions filings, NHTSA FMVSS interpretation bulletins, vehicle production databases, and customs trade records. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic vehicle ownership projections.
Input-output matrices mapped thermoforming capacity utilization, resin formulation cost structures, and channel margin stacks across the projection horizon. Segmentation dimensions modeled include mounting geometry, material formulation, vehicle body style, installation permanence, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation calibrated to historical replacement cycle data. Industry-specific forecast inputs incorporated lease penetration rates and FMVSS compliance verification timelines.
Underlying measurement precision varies by segment; in-channel guard configurations carry tighter precision than exterior-mount alternatives due to concentrated OEM-adjacent channel data availability. Forecasts reflect assumptions regarding regulatory stability and resin supply continuity. A model refresh is warranted upon material change in NHTSA FMVSS interpretation or significant polycarbonate feedstock cost dislocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Robotic Vacuum Cleaner Market
Household Items
Shower Caddies Market
Household Items
United Kingdom Air Purifier Market
Household Items
Pocket Tissues Market
Household Items
Robot Mops Market
Household Items
Deodorizer Bag Market
Household Items
Ultrasonic Diffusers Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Replacement Sheets Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Heated Towel Rail Market
Household Items
Japan Faucets Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Range Hood Cleaning Service Market