
 Industrial Girth Gear Market | 2026-2036
Industrial Girth Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Girth Gear Market Analysis
Multi-source procurement for cast steel ring gear blanks is decoupling from traditional captive foundry models across heavy industry supply chains. Metso Outotec leverages its integrated mill services platform to anchor aftermarket girth gear rebuild programs in mining corridors. DB Santasalo competes through specialized heat-treatment capabilities that extend fatigue life in cement kiln applications. Siemens controls the high-power electric drive interface, positioning its gearless mill drive systems as an alternative to conventional mechanical girth gear arrangements.
An industrial girth gear is a large-diameter ring gear, typically cast from alloyed steel with module ratings exceeding 20 mm and pitch diameters surpassing 10 meters, that transmits rotational torque from a pinion assembly to the drum or shell of rotary kilns, ball mills, and dryers in heavy process industries. The double drive configuration dominates cement industry installations where split-torque requirements reduce individual tooth loading, while gearless drive technology from electrical OEMs displaces mechanical girth gears in greenfield mining mills above 12 MW power draw. Toothed girth gears sustain the largest installed base across steel manufacturing converters, where maintenance providers represent a concentrated margin pool due to recurring tooth flank reconditioning cycles.
ISO 6336 load capacity standards for cylindrical gears govern international design verification, while China's GB/T 10095 precision grades constrain import acceptance for replacement gears in domestic cement plants. India's BIS certification requirements for critical cast steel components add qualification layers for overseas suppliers bidding on OEM and maintenance contracts. Stakeholders must monitor how gearless drive adoption in copper and gold concentrators reshapes the addressable mechanical girth gear universe across project development pipelines.
Market Dynamics
Gearless mill drive technology from electrical OEMs is compressing the addressable mechanical girth gear universe in greenfield mining projects above 12 MW power draw, forcing traditional gear suppliers to defend replacement cycles and aftermarket services in cement and steel rotary equipment.
Growth Catalysts
- Emissions Standards Tightening:China's dual carbon goals under MEE are mandating efficiency upgrades for heavy rotary kilns, accelerating replacement demand for higher-precision girth gear assemblies in domestic cement plants.
- Clinker Capacity Expansion:Cement producers in India's Rajasthan and Karnataka belts are commissioning new kiln lines, driving procurement cycles for large-diameter ring gears in split-torque configurations.
- Cast Steel Sourcing Flexibility:Multi-source procurement for alloyed steel ring gear blanks is decoupling from captive foundry models, reducing lead times for heavy process industry supply chains.
Market Restraints
- Alloyed Steel Input Volatility:Nickel and molybdenum price swings in commodity markets compress margin predictability for cast steel gear blank producers serving heavy rotary equipment OEMs.
- Foundry Capacity Concentration:Specialized heat-treatment capabilities for fatigue-life extension remain concentrated among European and East Asian suppliers, creating geographic supply risk for maintenance providers.
- Gearless Drive Substitution:Electrical drive systems from Siemens and ABB are eliminating mechanical girth gear requirements in new copper and gold concentrator mills above 10,000 kW rated power.
Strategic Opportunities
- Aftermarket Rebuild Services:Tooth flank reconditioning cycles in steel manufacturing converters represent recurring revenue streams for maintenance providers with in-situ machining capabilities.
- Integrated Mill Services Platforms:Mining corridors in Chile and Peru present white space for bundled girth gear inspection, rebuild, and predictive maintenance contracts tied to concentrator throughput guarantees.
- GB/T 10095 Certification Pathways:Overseas suppliers qualifying for China's precision grade standards can access replacement gear contracts in domestic cement plant maintenance tenders.
Industry Challenges
- ISO 6336 Verification Expertise Shortage:Load capacity calculation specialists for cylindrical gear design verification remain scarce, extending engineering timelines for custom girth gear quotations.
- BIS Certification Timelines:India's cast steel component qualification requirements add 6-12 month approval layers for foreign suppliers bidding on critical equipment contracts.
- Legacy Kiln Integration Complexity:Split-torque retrofits in aging cement plants require precise alignment of dual pinion assemblies with existing drum shells, complicating field installation execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Girth Gear Market |
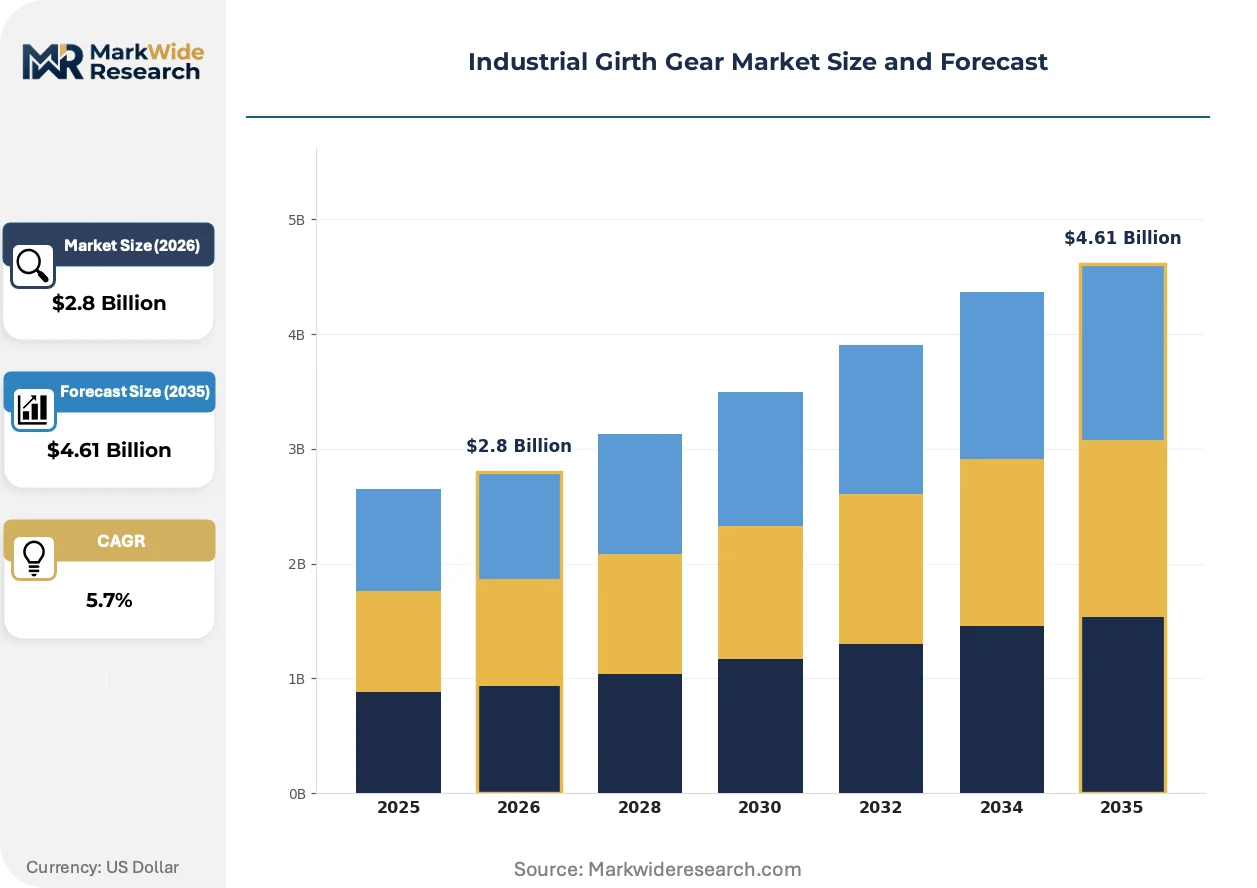
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Drive, Double Drive, Toothed, Gearless Application: Cement Industry, Mining, Power Generation, Steel Manufacturing End User: OEMs, Maintenance Providers, Equipment Manufacturers, Industrial Installers Installation: Onshore, Offshore, Fixed, Mobile |
| Companies Covered | Metso Outotec, DB Santasalo, FLSmidth, Siemens, SEW-EURODRIVE, ThyssenKrupp Industrial Solutions, Andritz, Harcliff Mining Services, SMS group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Girth Gear Market Emerging Trajectories
Digital inspection protocols and predictive maintenance algorithms are redefining how heavy rotary equipment operators manage girth gear lifecycle costs, shifting capital allocation from reactive replacement toward condition-based intervention.
Modular pinion cartridge assemblies with standardized bearing housings and quick-release coupling interfaces are modularizing field replacement procedures in cement kiln applications. Maintenance teams at plants in Brazil and Mexico are adopting these subsystems to compress outage windows from weeks to days. The technology is modularizing supplier ecosystems, enabling regional service providers to compete without full-scale manufacturing capabilities.
China's GB/T 10095 precision grade enforcement through SAMR market surveillance is disqualifying non-compliant imported girth gears from domestic cement plant replacement tenders. The regulation forces overseas suppliers to establish local metrology partnerships or forfeit maintenance contract eligibility. European gear producers are responding by pre-certifying production lines through China's national accreditation body.
Buyers in India's cement sector are unbundling after-sales service contracts from initial equipment procurement, awarding tooth flank reconditioning and alignment verification to specialized third-party providers. This behavior fragments vendor relationships that previously ran through single-source OEM arrangements. The shift is most visible in Rajasthan and Karnataka, where clinker producers prioritize uptime guarantees over brand loyalty in maintenance sourcing.
Industrial Girth Gear Market Segmentation
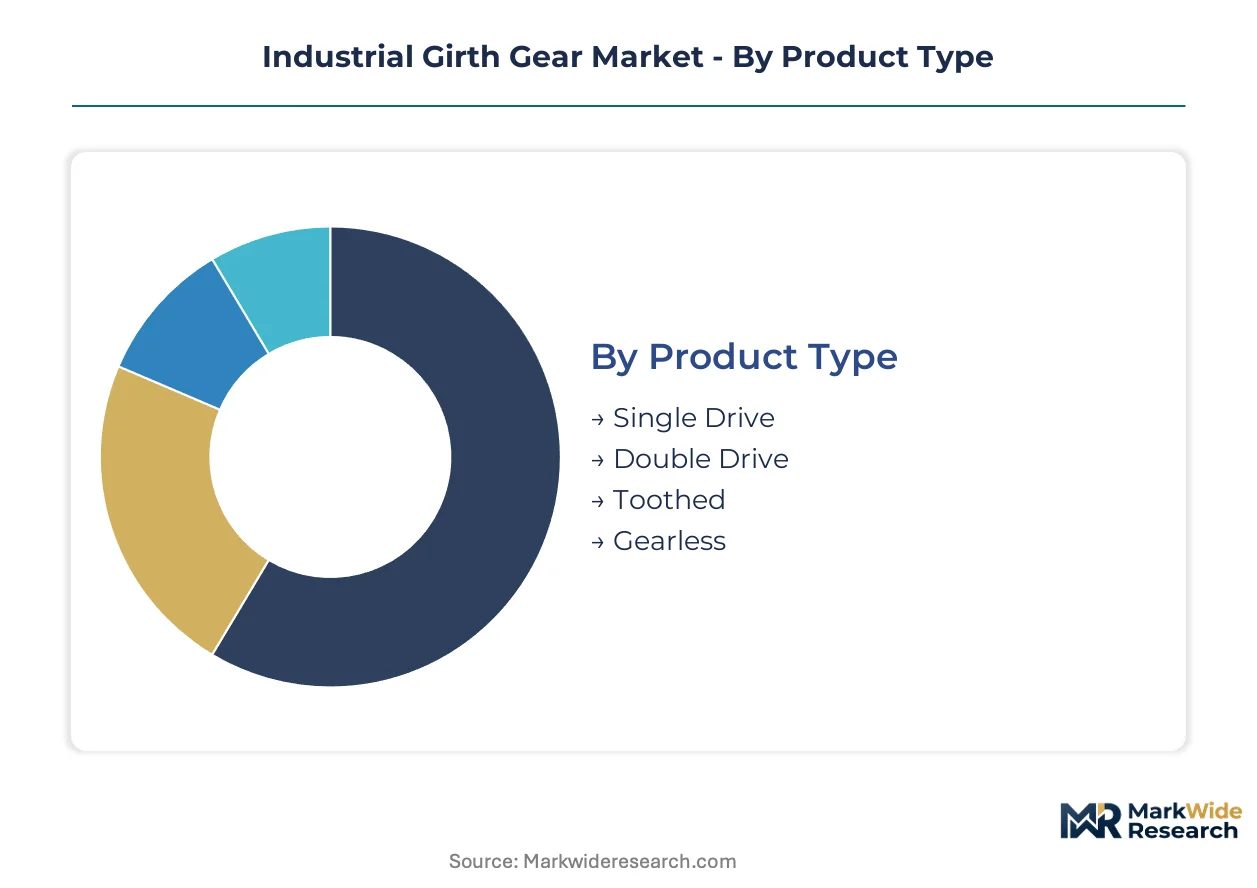
Industrial girth gear procurement patterns diverge sharply across product configurations and end-use applications. Understanding these fault lines clarifies where replacement cycles concentrate versus where gearless technology is displacing mechanical systems entirely.
Product Type:
Upgrade cycles and efficiency mandates are reshaping which drive configurations cement plants and mining operators specify for new installations and retrofits.
- Single Drive:One pinion assembly transmits full torque to the ring gear, common in smaller rotary kilns and dryers under 8 MW power draw. Demand persists in India's Rajasthan cement belt where legacy kiln lines require cost-contained rebuilds rather than full system replacement.
- Double Drive:Split-torque arrangements halve individual tooth loading through dual pinion assemblies, extending fatigue life in large-diameter applications. Rajasthan and Karnataka clinker expansion projects are specifying these configurations for new kiln lines above 10 MW to satisfy uptime guarantees under maintenance outsourcing contracts.
- Toothed:Conventional mechanical girth gears with external tooth profiles sustain the largest installed base across steel manufacturing converters.
- Gearless:Direct-drive electrical systems from Siemens and ABB eliminate mechanical transmission entirely.
Volume placements concentrate in Toothed configurations; the faster expansion belongs to Gearless systems in greenfield mining mills.
Application:
End-use intensity and regulatory exposure determine replacement frequency and precision grade requirements across heavy process industries.
- Cement Industry:Rotary kilns and grinding mills impose continuous tooth flank wear under thermal cycling and dust contamination. India's Karnataka belt is accelerating procurement for split-torque double drive systems as clinker capacity expands under private infrastructure investment.
- Mining:Ball mills and SAG mills in copper and gold concentrators subject girth gears to shock loading from ore variability. Gearless drive substitution is compressing mechanical gear demand in Chilean and Peruvian greenfield projects above 12 MW.
- Power Generation:Coal pulverizers and biomass dryers require girth gears with enhanced corrosion resistance.
- Steel Manufacturing:Converters and rotary furnaces drive recurring aftermarket revenue through tooth flank reconditioning cycles.
Revenue concentration sits with Cement Industry replacements; Mining applications are climbing the fastest as concentrator throughput expands.
End User:
Procurement authority is fragmenting as operators unbundle equipment supply from lifecycle services.
- OEMs:Original equipment manufacturers specify girth gears for new kiln and mill lines, typically under turnkey supply contracts with 15-20 year design life guarantees. Metso Outotec leverages integrated mill services platforms to anchor bundled procurement in mining corridors.
- Maintenance Providers:Third-party specialists with in-situ machining capabilities are capturing tooth flank reconditioning and alignment verification contracts. India's cement sector is awarding these services separately from initial equipment procurement, fragmenting vendor relationships in Rajasthan and Karnataka.
- Equipment Manufacturers:Subsystem suppliers procure ring gear blanks for integration into complete drive assemblies.
- Industrial Installers:Field contractors execute split-torque retrofits and dual pinion alignments in aging plants.
Contract flow concentrates through OEMs for new capacity; Maintenance Providers are gaining share fastest as aftermarket unbundling accelerates.
Installation:
Physical deployment constraints dictate logistics complexity and field service requirements.
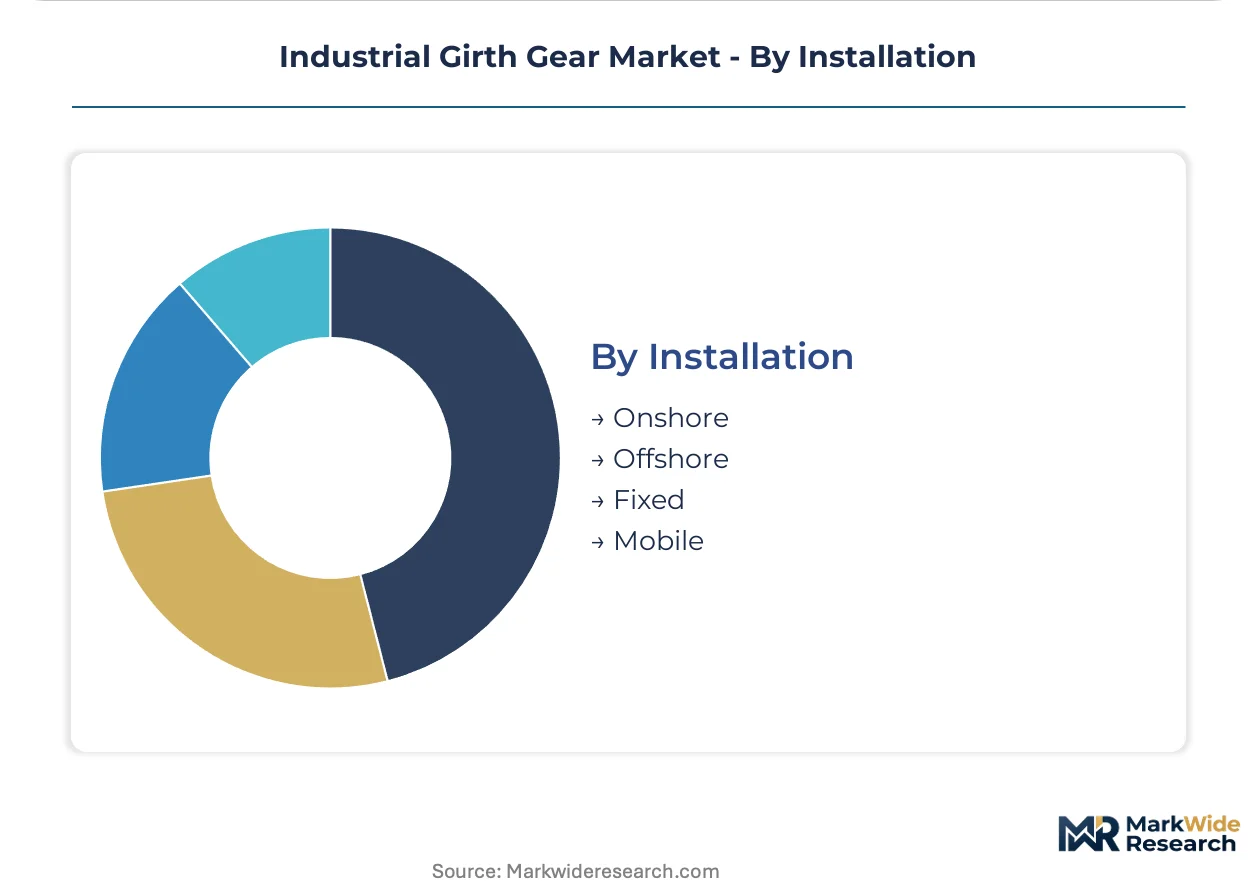
- Onshore:Ground-level installations at cement plants, steel mills, and mining concentrators permit conventional crane rigging and assembly procedures. Brazil's expanding kiln capacity drives replacement cycles for large-diameter gears with accessible maintenance access.
- Offshore:Platform-mounted processing equipment in coastal mineral handling facilities requires corrosion-resistant alloy specifications and specialized logistics.
- Fixed:Permanent foundations at process plants dominate the installed base.
- Mobile:Transportable grinding circuits in temporary mining operations specify lighter-weight gear configurations with quick-assembly interfaces.
Deployment volume clusters in Fixed onshore installations; Mobile configurations are expanding most quickly in remote mining development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alloyed steel foundry capacity in Germany anchors European supply for large-diameter ring gear blanks. Procurement patterns diverge across cement expansion corridors, mining concentrator development, and steel manufacturing maintenance cycles.
China
Domestic cement producers face MEE emissions mandates under dual carbon goals that accelerate kiln efficiency retrofits. SAMR enforces GB/T 10095 precision grades through market surveillance, disqualifying non-compliant imports from replacement tenders. Shandong and Jiangsu provinces concentrate clinker capacity expansion where split-torque double drive configurations dominate new installations.
India
Rajasthan and Karnataka cement belts are commissioning kiln lines above 10 MW that require fatigue-optimized girth gear assemblies. BIS certification requirements for critical cast steel components add qualification layers for overseas suppliers bidding on maintenance contracts. Clinker producers in these states unbundle aftermarket services from initial procurement, fragmenting vendor relationships toward specialized third-party providers.
Germany
Integrated mill services platforms from heavy equipment OEMs anchor aftermarket rebuild programs for mining concentrators in Chile and Peru. REACH compliance governs alloyed steel composition specifications for export-bound ring gear blanks. Ruhr Valley foundries maintain concentrated heat-treatment capabilities that European maintenance providers depend upon for fatigue-life extension services.
Brazil
Cement producers are expanding kiln capacity in Minas Gerais and São Paulo states, driving replacement cycles for large-diameter gears with accessible maintenance access. ANVISA oversight applies indirectly through industrial safety standards for rotary equipment installation. Maintenance teams at plants in these regions adopt modular pinion cartridge assemblies to compress outage windows from weeks to days.
United States
Coal pulverizer and biomass dryer operators in the Midwest and Gulf Coast require girth gears with enhanced corrosion resistance specifications. EPA emissions standards for power generation equipment influence upgrade timelines for rotary drive systems. Ohio and Texas industrial corridors concentrate demand for aftermarket tooth flank reconditioning services in steel manufacturing converters.
Industrial Girth Gear Market Vendor Landscape
Aftermarket service bundling dominates the current landscape as traditional equipment suppliers defend against gearless drive substitution. The vendor base spans integrated mill services platforms, specialized heat-treatment providers, and electrical drive OEMs offering mechanical elimination. Three archetypes define positioning: full-lifecycle service integrators, precision manufacturing specialists, and electrical drive technology providers. Competitive intensity concentrates on M&A to secure foundry capacity and strategic partnerships to embed predictive maintenance algorithms.
Among European-integrated heavy equipment providers, Metso Outotec, DB Santasalo, and FLSmidth occupy positions across the service-integration spectrum. Metso Outotec exemplifies the mill-services platform archetype through bundled inspection and rebuild contracts. DB Santasalo represents specialized heat-treatment capabilities for fatigue-life extension. FLSmidth anchors turnkey supply relationships with cement producers seeking single-source accountability. These three entities illustrate how geographic integration and technical specialization create defendable positions against electrical drive displacement.
| Leading Market Players |
|---|
| Metso Outotec |
| DB Santasalo |
| FLSmidth |
| Siemens |
| SEW-EURODRIVE |
| ThyssenKrupp Industrial Solutions |
| Andritz |
| Harcliff Mining Services |
| SMS group |
| Others |
Supply Flow & Price Mechanics
Cement OEM procurement teams in India and Brazil concentrate demand for large-diameter ring gears, anchoring a contract-based pricing model where turnkey supply agreements bundle 15-20 year design life guarantees with aftermarket service riders. This buyer concentration forces tiered pricing stratification across premium certified, standard industrial, and economy rebuild tiers.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from unbundled aftermarket competitors, with Metso Outotec and FLSmidth commanding price premiums through integrated mill services platforms while third-party maintenance providers compete on tooth flank reconditioning rates. Price differentiation rests on GB/T 10095 certification grade and in-situ machining capability. Cost compression in the economy tier intensifies because Indian clinker producers unbundle service contracts from initial procurement. Maintenance providers exhibit highest price sensitivity; mining operators specifying gearless drives above 12 MW show lowest sensitivity to mechanical gear pricing.
Supply Chain Analysis
Freight costs for single-piece castings exceeding 10-meter pitch diameter constrain sourcing radius, favoring regional foundry partnerships over transoceanic procurement. Supply concentrates in Germany, China, and India, with Ruhr Valley heat-treatment capabilities and Shandong alloyed steel production anchoring upstream capacity. Raw material flows draw from nickel and molybdenum commodity markets, with ring gear blank sourcing tethered to captive foundry decoupling trends. Single-source vulnerability concentrates in specialized fatigue-life extension services. Distribution runs through OEM turnkey contracts for new capacity and fragmented third-party maintenance networks for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial girth gear sector sits in a technology-transition phase as gearless mill drive systems from Siemens and ABB displace mechanical transmissions in greenfield mining concentrators above 12 MW rated power.
For Market Incumbents: Lock in aftermarket revenue streams by acquiring in-situ machining capabilities and predictive maintenance platforms before gearless substitution accelerates in copper and gold concentrators. Defend position by securing BIS and GB/T 10095 certifications to maintain eligibility in Indian and Chinese replacement tenders. Backward integration into heat-treatment capacity insulates margin pressure from European foundry concentration risk. For New Entrants and Emerging Players: Enter via aftermarket service unbundling in India's Rajasthan and Karnataka cement belts, where clinker producers separate tooth flank reconditioning from OEM procurement. Target white space in modular pinion cartridge assemblies for Brazilian kiln operators seeking outage compression. Pursue metrology partnerships with China's national accreditation body to unlock SAMR-compliant replacement gear contracts. For Investors and Strategic Acquirers: The window for entry favors specialized heat-treatment and in-situ machining providers with established mining corridor relationships. Long-term viability hinges on defensible positioning in cement and steel maintenance cycles as mechanical gear addressable markets contract in mining. Watch gearless drive adoption rates in Chilean and Peruvian greenfield concentrators as the primary inflection signal for mechanical gear demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Secures fatigue-life extension capabilities that European maintenance providers depend upon for service differentiation. |
| GB/T 10095 Certification Pathway Investment | Unlocks SAMR-compliant replacement tenders in Shandong and Jiangsu cement plant maintenance contracts. |
| Modular Pinion Cartridge Development | Compresses outage windows for Brazilian kiln operators from weeks to days through standardized quick-release interfaces. |
| Predictive Maintenance Platform Acquisition | Embeds digital inspection protocols that shift cement producer capital allocation from reactive replacement toward condition-based intervention. |
| In-Situ Machining Capability Buildout | Captures unbundled aftermarket contracts in India's Karnataka belt where clinker producers prioritize uptime guarantees over OEM brand loyalty. |
Methodological Framework
Independent corroboration across maintenance director interviews, OEM procurement team consultations, and foundry operations assessments underwrites the qualitative findings in this study. Primary fieldwork engaged plant engineers at cement facilities in Rajasthan and Karnataka, aftermarket service heads in German mining equipment corridors, and metallurgical specialists at Ruhr Valley heat-treatment facilities. Secondary validation drew from customs trade data for alloyed steel ring gear blank flows, SEC filings of integrated heavy equipment providers, and SAMR market surveillance disclosures on GB/T 10095 enforcement. Bottom-up demand modeling across kiln expansion projects and top-down supply assessment from foundry capacity databases were triangulated against maintenance cycle frequency estimates.
Rate-of-change decomposition across the projection horizon isolates gearless drive substitution effects from replacement cycle dynamics in cement and steel rotary equipment. Segmentation dimensions modeled include drive configuration type, end-use application intensity, procurement authority structure, and geographic regulatory cluster. CAGRs were derived from installed base depreciation schedules, clinker capacity expansion pipelines, and concentrator throughput growth trajectories. Industry-specific forecast inputs incorporate MEE emissions mandate compliance timelines and BIS certification approval lag distributions.
Revisions become necessary when gearless drive adoption accelerates beyond modeled substitution rates, alloyed steel commodity volatility disrupts foundry economics, or regulatory precision grade requirements tighten unexpectedly. Forecasts reflect assumptions about maintenance outsourcing propensity and captive foundry model persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Rolling Mill Machine Market