
 Overhead Conveyor Systems Market | 2026-2036
Overhead Conveyor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Conveyor Systems Market Outlook
Skilled automation technicians is redrawing competitive boundaries in overhead conveyor deployment. Daifuku leverages deep integration with automotive paint shop workflows to sustain premium positioning in high-corrosion environments. Siemens anchors European demand through its digital twin-enabled conveyor control architectures. Fives Group competes on thermal process coupling, where its monorail systems integrate directly with curing oven lines.
Overhead conveyor systems suspend loads from ceiling-mounted tracks, utilizing chain, belt, or roller mechanisms with load capacities typically spanning 50 kg to 5,000 kg per carrier, and serve to optimize floor space while enabling continuous material flow through elevated transport paths. Chain conveyors dominate heavy-duty automotive applications where cumulative line loads exceed 10,000 kg, while monorail systems capture expanding share in cleanroom-sensitive aerospace component handling due to reduced contamination exposure from floor-level equipment. Electric technology leads installed base value given precision speed control and IoT connectivity compatibility, though hybrid pneumatic-electric actuation is gaining traction in food and beverage facilities seeking to eliminate hydraulic oil contamination risks.
OSHA fall protection and walking-working surface standards shape U.S. system design through mandatory guardrail and toeboard specifications on elevated maintenance platforms. The EU Machinery Directive and CE marking requirements enforce emergency stop integration and risk assessment documentation for automated overhead installations. Stakeholders must monitor evolving ISO 3691-3 standards for industrial truck safety interfaces, as these will determine interoperability compliance costs for next-generation fleet-integrated conveyor networks.
Market Dynamics
Automotive OEMs are consolidating paint shop and body-in-white operations around single-source overhead conveyor integrators, compressing vendor margins while raising technical barriers for mid-tier suppliers unable to certify corrosion-resistant chain systems.
Growth Catalysts
- EU Machinery Directive emergency-stop mandates:Retrofit requirements across German, Italian, and Spanish automotive plants are accelerating replacement cycles for legacy unguarded monorail installations.
- Food and beverage cleanroom expansion:Pneumatic-electric hybrid actuation eliminates hydraulic contamination risks in dairy and ready-meal processing facilities.
- Aerospace component handling:Monorail systems capture share in cleanroom-sensitive operations where floor-level equipment increases particulate exposure.
Market Restraints
- Specialized steel alloy volatility:High-grade corrosion-resistant chain materials face price instability tied to nickel and chromium supply concentration in specific mining jurisdictions.
- Certified integration engineer scarcity:OSHA fall protection and CE marking compliance requires technicians with dual electrical-mechanical credentials that training pipelines undersupply.
- Floor-based AGV substitution:Autonomous mobile robots with payload capacities exceeding 1,000 kg are capturing intralogistics applications where ceiling height constraints limit overhead deployment.
Strategic Opportunities
- India automotive tier supplier modernization:PLI scheme incentives for component manufacturing are creating first-time demand for paint shop conveyor infrastructure in Pune and Chennai clusters.
- Digital twin convergence:Siemens-style control architectures integrating real-time simulation with physical conveyor operation enable predictive maintenance contracts.
- ISO 3691-3 fleet interoperability:Early compliance with industrial truck safety interface standards positions integrators for next-generation automated warehouse networks.
Industry Challenges
- Legacy PLC integration complexity:Brownfield automotive plants require seamless handshaking between 1990s-era programmable logic controllers and modern IoT-enabled drive systems.
- Multi-jurisdiction certification timelines:Simultaneous OSHA, CE marking, and ISO 3691-3 approvals extend project delivery windows by 4-8 months.
- Skilled automation technician attrition:Retirement waves among technicians trained on mechanical chain systems outpace vocational program output.
Report Scope
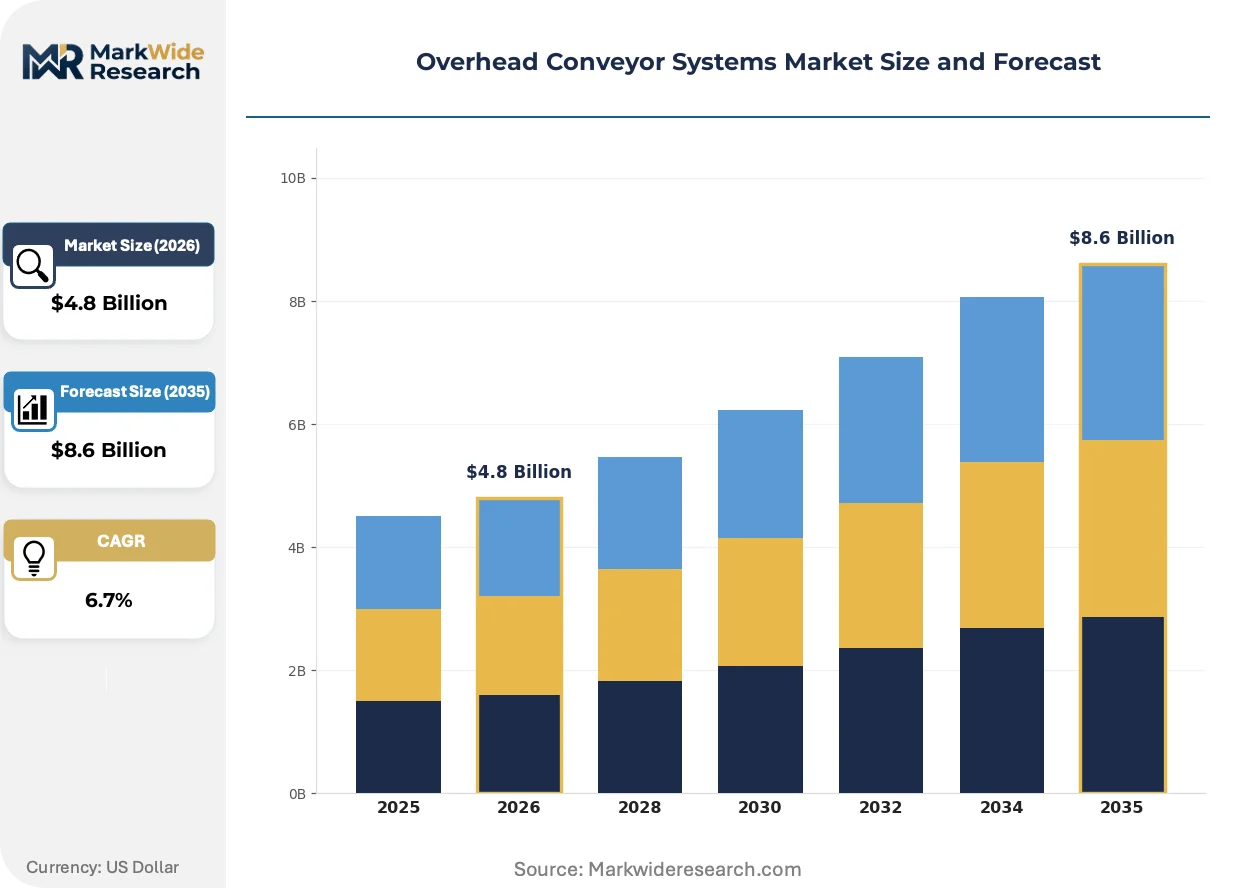
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Conveyor Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powered Roller, Chain Conveyors, Belt Conveyors, Monorail Systems End User: Automotive, Food & Beverage, Aerospace, Manufacturing Technology: Electric, Pneumatic, Mechanical, Hybrid Installation Type: New Installation, Retrofit, Expansion, Custom Solutions |
| Companies Covered | Siemens, Bastian Solutions, Daifuku, SSI SCHÄFER, Hytrol, Interroll, Fives Group, Honeywell Intelligrated, FlexLink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Conveyor Systems Market Strategic Shifts
Overhead conveyor architecture is bifurcating between heavy-duty automotive chain systems and lightweight monorail configurations, with control intelligence migrating from centralized PLCs to edge-mounted drive units.
Magnetic levitation carrier technology is supplanting traditional wheel-based monorail systems in cleanroom aerospace applications. Tier-one suppliers in Toulouse and Hamburg are piloting frictionless transport for satellite component assembly. This shift is compressing maintenance intervals from quarterly to annual while eliminating particulate generation from wheel wear.
OSHA fall protection standards are mandating toeboard and guardrail specifications on all elevated maintenance platforms above 1.2 meters. System designers must now integrate permanent fall arrest anchorage points into track support structures. U.S. automotive retrofit projects are absorbing 8-12% cost premiums for compliance-certified platform packages.
Service contract unbundling is fragmenting traditional turnkey procurement. End-users in German automotive clusters are separating mechanical installation from control system commissioning and predictive maintenance subscriptions. This shift concentrates margin in software-enabled service layers while commoditizing hardware supply.
Overhead Conveyor Systems Market Segmentation
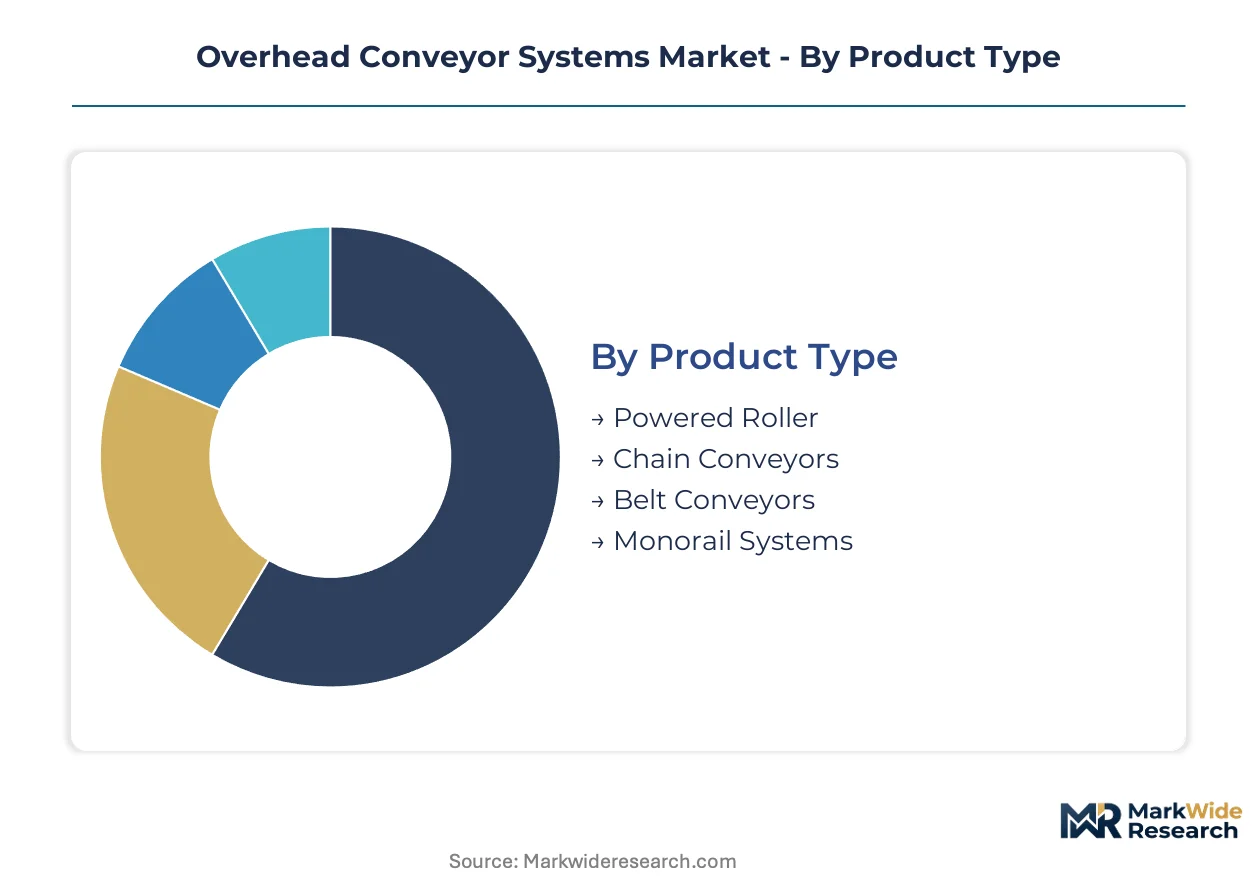
Overhead conveyor procurement channels diverge sharply by segment. Automotive OEMs source through integrated paint shop contractors, while food processors favor direct specification of hygienic monorail systems. Aerospace and general manufacturing split between retrofit specialists and greenfield integrators depending on facility age.
Product Type:
Channel mix varies by load capacity and corrosion exposure. Chain conveyors flow through automotive paint shop integrators. Monorail systems reach aerospace via cleanroom equipment distributors. Belt and roller configurations serve manufacturing through industrial supply houses.
- Chain Conveyors:Heavy-duty chain systems handle cumulative line loads exceeding 10,000 kg in automotive body-in-white and paint shop operations. German OEMs and tier suppliers in Stuttgart and Wolfsburg specify corrosion-resistant variants for phosphate and electrocoat environments where chemical exposure degrades standard steel alloys.
- Monorail Systems:Ceiling-suspended single-rail configurations enable frictionless magnetic levitation in cleanroom aerospace applications. Toulouse and Hamburg satellite assembly facilities pilot these systems to eliminate particulate generation from wheel wear while reducing maintenance intervals.
- Powered Roller:Modular roller sections serve distribution centers and light manufacturing with rapid reconfiguration capability.
- Belt Conveyors:Continuous belt mechanisms handle irregular shapes in baggage handling and parcel sorting operations.
Chain conveyors dominate installed base. Monorail systems are where expansion concentrates.
End User:
Cost tier segmentation separates premium-specification aerospace and automotive from price-sensitive general manufacturing. Food and beverage occupies a middle tier where hygienic certification commands modest premiums over standard industrial grades.
- Automotive:Paint shop and body-in-white operations require corrosion-resistant chain systems with integrated curing oven interfaces. Pune and Chennai automotive clusters under India's PLI scheme are creating first-time demand for paint shop conveyor infrastructure among tier suppliers modernizing legacy facilities.
- Food & Beverage:Dairy and ready-meal processing facilities specify pneumatic-electric hybrid actuation to eliminate hydraulic oil contamination risks in cleanroom environments. FDA and USDA sanitary standards mandate stainless steel construction with washdown-compatible sealing.
- Aerospace:Cleanroom-sensitive component handling favors monorail configurations that reduce particulate exposure from floor-level equipment.
- Manufacturing:General industrial applications span assembly, warehousing, and distribution with flexible configuration requirements.
Automotive anchors revenue concentration. Food and beverage is climbing the fastest.
Technology:
Volume distribution skews toward mature electric installations, though hybrid architectures gain share in contamination-sensitive environments. Pneumatic and mechanical systems retain niche positions where explosive atmospheres or extreme simplicity requirements override precision control needs.
- Electric:Precision speed control and native IoT connectivity compatibility make electric drives the default for new automotive and aerospace installations. Siemens digital twin-enabled architectures integrate real-time simulation with physical conveyor operation to enable predictive maintenance contracts.
- Hybrid:Pneumatic-electric actuation combines electric precision with pneumatic cleanliness in food and beverage facilities eliminating hydraulic contamination. This configuration is gaining traction where both control accuracy and fluid-free operation are mandatory.
- Pneumatic:Compressed air power persists in explosive atmosphere applications and simple material transfer operations.
- Mechanical:Pure mechanical drive systems serve remote locations with unreliable electrical infrastructure or minimal maintenance capability.
Electric systems command installed base value. Hybrid configurations are gaining share fastest.
Installation Type:
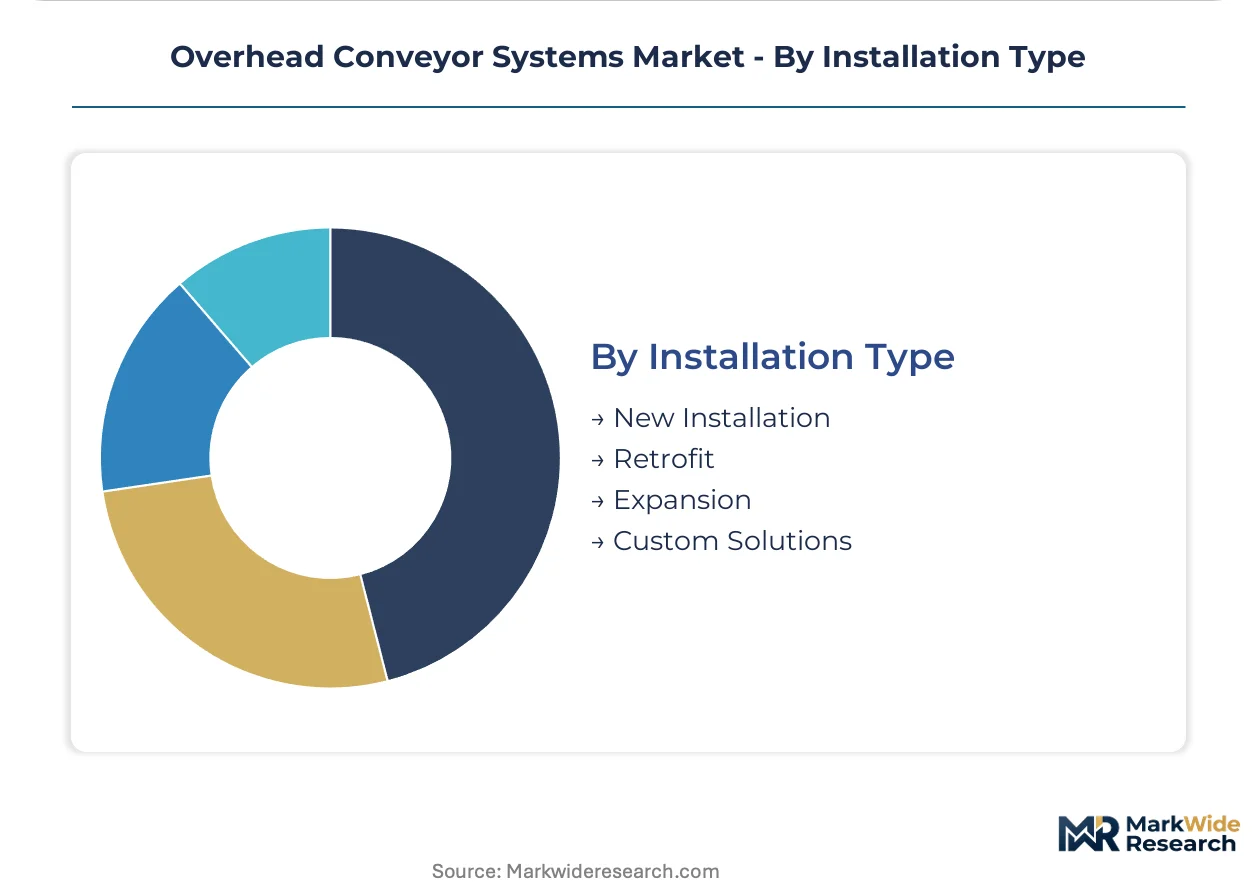
Customer type segmentation separates greenfield automotive plants specifying new installations from brownfield facilities requiring retrofit compatibility with 1990s-era programmable logic controllers. Custom solutions concentrate in aerospace where satellite component dimensions defy standardization.
- Retrofit:Brownfield automotive plants in Germany, Italy, and Spain face EU Machinery Directive emergency-stop mandates accelerating replacement cycles for legacy unguarded monorail installations. OSHA fall protection standards drive simultaneous U.S. automotive retrofit demand with 8-12% cost premiums for compliance-certified platform packages.
- New Installation:Greenfield automotive paint shops and aerospace cleanrooms specify integrated systems with digital twin compatibility from commissioning. These projects absorb extended 4-8 month delivery windows for simultaneous OSHA, CE marking, and ISO 3691-3 approvals.
- Expansion:Existing facility capacity additions require seamless integration with operational conveyor networks without production interruption.
- Custom Solutions:Non-standard load geometries and process-specific thermal profiles demand engineered-to-order track configurations and carrier designs.
Retrofit projects dominate near-term volume. New installations are where margin concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA fall protection standards anchor North American demand through mandatory guardrail and toeboard specifications on elevated maintenance platforms above 1.2 meters. The EU Machinery Directive drives parallel retrofit cycles across German, Italian, and Spanish automotive plants. India's PLI scheme for component manufacturing is creating first-time conveyor infrastructure demand in Pune and Chennai clusters.
Germany
Automotive OEMs and tier suppliers in Stuttgart and Wolfsburg specify corrosion-resistant chain systems for phosphate and electrocoat environments. The EU Machinery Directive enforces emergency-stop integration and CE marking risk assessment documentation for automated installations. Wolfsburg's paint shop modernization programs are consolidating procurement around single-source integrators capable of certifying high-corrosion systems.
United States
U.S. automotive retrofit projects absorb 8-12% cost premiums for OSHA-compliant platform packages with permanent fall arrest anchorage points. OSHA walking-working surface standards mandate toeboard and guardrail specifications on all elevated maintenance access points. Detroit-area assembly plants are replacing legacy unguarded monorail installations to meet tightened enforcement timelines.
India
India's PLI scheme incentives for automotive component manufacturing are triggering first-time paint shop conveyor deployments among tier suppliers. The Bureau of Indian Standards monitors equipment safety compliance for imported industrial machinery. Pune and Chennai automotive clusters are modernizing legacy facilities with corrosion-resistant chain infrastructure previously absent in domestic supply chains.
France
Toulouse satellite assembly facilities are piloting magnetic levitation carrier technology to eliminate particulate generation from wheel wear in cleanroom environments. REACH chemical regulations influence surface treatment specifications for conveyor components exposed to process chemicals. The Occitanie aerospace cluster is compressing maintenance intervals from quarterly to annual through frictionless transport adoption.
Japan
Japanese automotive plants prioritize precision speed control and IoT connectivity compatibility in electric drive specifications. METI industrial standards guide interoperability requirements for automated material handling systems. Nagoya-area OEM facilities are integrating digital twin-enabled control architectures for predictive maintenance contract structures.
Overhead Conveyor Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in overhead conveyor deployment. The upper tier commands premium positioning through deep automotive paint shop integration and corrosion-resistant system certification. Mid-tier competitors face compressing margins as OEMs consolidate procurement around single-source integrators. Strategic moves concentrate on digital twin convergence for predictive maintenance contracts and multi-jurisdiction certification capabilities spanning OSHA, CE marking, and ISO 3691-3 standards.
Among Japanese- and European-based integrated providers, Daifuku and Siemens occupy positions exemplifying divergent competitive vectors. Daifuku represents deep vertical integration into automotive paint shop workflows. Siemens anchors European demand through control architecture specialization. Fives Group sits within the thermal process coupling tier where monorail systems integrate directly with curing oven lines.
| Leading Market Players |
|---|
| Siemens |
| Bastian Solutions |
| Daifuku |
| SSI SCHÄFER |
| Hytrol |
| Interroll |
| Fives Group |
| Honeywell Intelligrated |
| FlexLink |
| Others |
Value Chain & Pricing Dynamics
Four-to-six month delivery windows for corrosion-resistant chain systems concentrate pricing power among German and Japanese suppliers capable of certifying dual OSHA-CE compliance, while inventory buffers at automotive paint shop integrators absorb nickel and chromium alloy volatility. This lead-time band forces tier suppliers into premium contracting positions that hardware commoditization elsewhere cannot offset.
Pricing Analysis
Geographic price spreads of 15-25 percentage points separate German-certified installations from Indian domestic supply, reflecting after-sales service bundling and multi-jurisdiction certification costs. Project-based pricing dominates automotive paint shop procurement, with differentiation anchored in CE marking tier and predictive maintenance subscription depth. Pricing pressure stems from single-source integrator consolidation compressing vendor margins, while tier suppliers in India's PLI clusters prove most price-sensitive against OEMs prioritizing uptime guarantees.
Supply Chain Analysis
Strait of Malacca transit underwrites 60% of high-grade corrosion-resistant steel alloy movement to European automotive hubs, exposing chains to concentrated logistics risk. Supply draws from Germany, Japan, and South Korea for precision drive components, with nickel and chromium sourcing tethered to Indonesian and South African mining jurisdictions. Single-source vulnerability in certified chain forging creates structural risk, while distribution runs through automotive paint shop integrators and aerospace cleanroom equipment distributors rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity because predictive maintenance subscriptions and digital twin commissioning layers expand at multiples exceeding hardware replacement cycles, concentrating lifetime value in software-enabled recurring revenue.
For Market Incumbents: Consolidate around corrosion-resistant chain certification capabilities and multi-jurisdiction compliance engineering to defend against floor-based AGV substitution threatening ceiling-constrained applications. Deepen backward integration into nickel alloy supply through captive sourcing arrangements with Indonesian mining partners, while embedding permanent fall arrest anchorage design as a locked-in specification standard. For New Entrants and Emerging Players: Differentiate on pneumatic-electric hybrid actuation architectures for food and beverage cleanroom penetration, where hydraulic contamination elimination commands modest certification premiums absent entrenched supplier relationships. Target India's Pune and Chennai automotive clusters for first-time paint shop infrastructure deployment under PLI scheme incentives, entering through direct tier supplier specification rather than OEM-integrated channels. For Investors and Strategic Acquirers: Long-term, this sits as a maintenance-contract annuity play because installed base expansion converts to predictable service revenue streams with lower capital intensity than greenfield hardware deployment. Acquire mid-tier integrators possessing ISO 3691-3 pre-certification and existing German automotive relationships, watching magnetic levitation pilot conversions in Toulouse and Hamburg as inflection signals for aerospace segment tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Launch | Captures recurring revenue from Siemens-style digital twin architectures in Stuttgart automotive clusters. |
| Backward Integration into Alloy Supply | Secures nickel and chromium sourcing against South African mining jurisdiction volatility. |
| ISO 3691-3 Pre-Certification Investment | Positions integrators for next-generation automated warehouse fleet interoperability mandates. |
| Magnetic Levitation Technology Licensing | Enables frictionless cleanroom entry for Toulouse satellite assembly facility expansions. |
| India PLI Scheme Channel Partnership | Establishes first-mover presence in Pune and Chennai tier supplier modernization waves. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating plant engineers at Stuttgart and Wolfsburg automotive facilities, aftermarket service heads at cleanroom distributors, and procurement leads at tier suppliers in Pune and Chennai. Secondary validation drew from EU Machinery Directive implementation filings, OSHA enforcement timelines, Bureau of Indian Standards equipment safety registrations, and automotive production databases. Bottom-up segment sizing triangulated against top-down industry value chain estimates.
Across the analysis window, forecasts model product type segmentation by load capacity and corrosion exposure, technology tier by actuation architecture, and installation type by greenfield versus brownfield facility status. CAGRs derive from replacement cycle acceleration tied to EU emergency-stop mandates and OSHA fall protection enforcement expansion. Industry-specific inputs include certified integration engineer supply constraints and magnetic levitation pilot adoption curves in aerospace cleanrooms.
The analysis sits within stated boundaries; outcomes outside sustained automotive capital expenditure levels and nickel alloy price stability would require recalibration. Forecasts reflect assumptions around regulatory enforcement timelines and PLI scheme incentive continuity. Practitioners should keep alternative scenarios live as AGV payload capacity improvements and ceiling height constraint prevalence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Industrial Elevator Market