
 Vertical Reciprocating Conveyor Market | 2026-2036
Vertical Reciprocating Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Reciprocating Conveyor Market Analysis
Equipment leasing and project finance is fragmenting competitive dynamics in vertical reciprocating conveyor procurement. Autoquip leverages its engineering depth to anchor complex custom installations for industrial clients. Wildeck sustains broad manufacturing scale across standard and modular product lines. NERAK Systems specializes in vertical conveying integration for distribution and warehouse automation.
A vertical reciprocating conveyor is a materials handling device that transports goods between fixed vertical levels using mechanical, hydraulic, or electric drive systems, typically rated for loads from hundreds to thousands of pounds and speeds up to several hundred feet per minute. Its primary purpose is to eliminate manual lifting and forklift traffic in multi-floor facilities, improving throughput and reducing injury risk. Hydraulic VRC systems dominate heavy-load industrial applications where durability and lifting capacity outweigh energy efficiency concerns. Electric VRC technology leads in retail and light manufacturing settings where precision, speed, and lower operating costs drive specification. Rack-mounted VRC configurations are gaining share in warehousing as facilities maximize cubic storage density without expanding footprints.
OSHA workplace safety regulations and ASME B20.1 conveyor standards govern installation, operation, and maintenance requirements across the United States, directly influencing product design and inspection protocols. The EU Machinery Directive and CE marking requirements shape market access for European installations, while China's GB standards and SAMR oversight define compliance pathways for domestic and imported equipment. Stakeholders must monitor evolving energy efficiency regulations and automation integration standards as facility modernization cycles accelerate.
Market Dynamics
Warehouse automation investments and stricter ASME B20.1 compliance mandates are compressing replacement cycles for legacy material handling infrastructure across multi-level distribution facilities.
Growth Catalysts
- E-commerce fulfillment density:Rack-mounted VRC configurations enable cubic storage optimization in fulfillment centers where floor space constraints intensify. Third-party logistics operators in the United States specify these units to eliminate forklift traffic between mezzanine levels.
- OSHA workplace safety enforcement:Elevated inspection protocols and injury liability exposure compel facility managers to replace manual lifting operations with mechanical vertical transport. Compliance-driven retrofits accelerate specification of certified hydraulic and electric systems.
- Manufacturing reshoring:Domestic production facility expansions in Germany and the United States require integrated material handling between production floors. VRC installations support lean manufacturing layouts with minimized WIP inventory buffers.
Market Restraints
- Steel input volatility:Structural steel and precision-machined component costs fluctuate with commodity markets, compressing margin visibility for custom-engineered installations. Fabricators face hedging complexity on six-month project timelines.
- Regional supply concentration:Hydraulic system manufacturing clusters in the Midwestern United States create geographic vulnerability to localized labor disruptions. Buyers in Western states encounter extended lead times for specialized drive assemblies.
- Technical ceiling on speed:Current mechanical drive systems face fundamental limits approaching several hundred feet per minute for heavy-load configurations. Applications requiring continuous high-speed vertical transport may specify alternative continuous vertical conveyors.
Strategic Opportunities
- Underpenetrated cold chain logistics:Temperature-controlled food distribution facilities in China lack standardized vertical transport between refrigerated levels. Specialized insulated VRC designs address condensation and thermal bridging challenges.
- EU Machinery Directive alignment:CE marking requirements for integrated safety systems create specification advantages for manufacturers with pre-certified modular platforms. European warehouse automation integrators prioritize compliant suppliers.
- IoT predictive maintenance convergence:Sensor-enabled VRC units combined with cloud analytics platforms enable condition-based service scheduling. Equipment-as-a-service models emerge for fleet operators managing multiple facilities.
Industry Challenges
- Mechatronics technician scarcity:Installation and commissioning of electric drive VRC systems requires cross-trained personnel proficient in both mechanical alignment and programmable logic controller programming. Vocational pipeline gaps extend project timelines.
- ASME B20.1 certification latency:Third-party inspection and documentation for custom installations adds four to eight weeks to project delivery. Engineering firms struggle to parallel-path design approval with fabrication schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Reciprocating Conveyor Market |
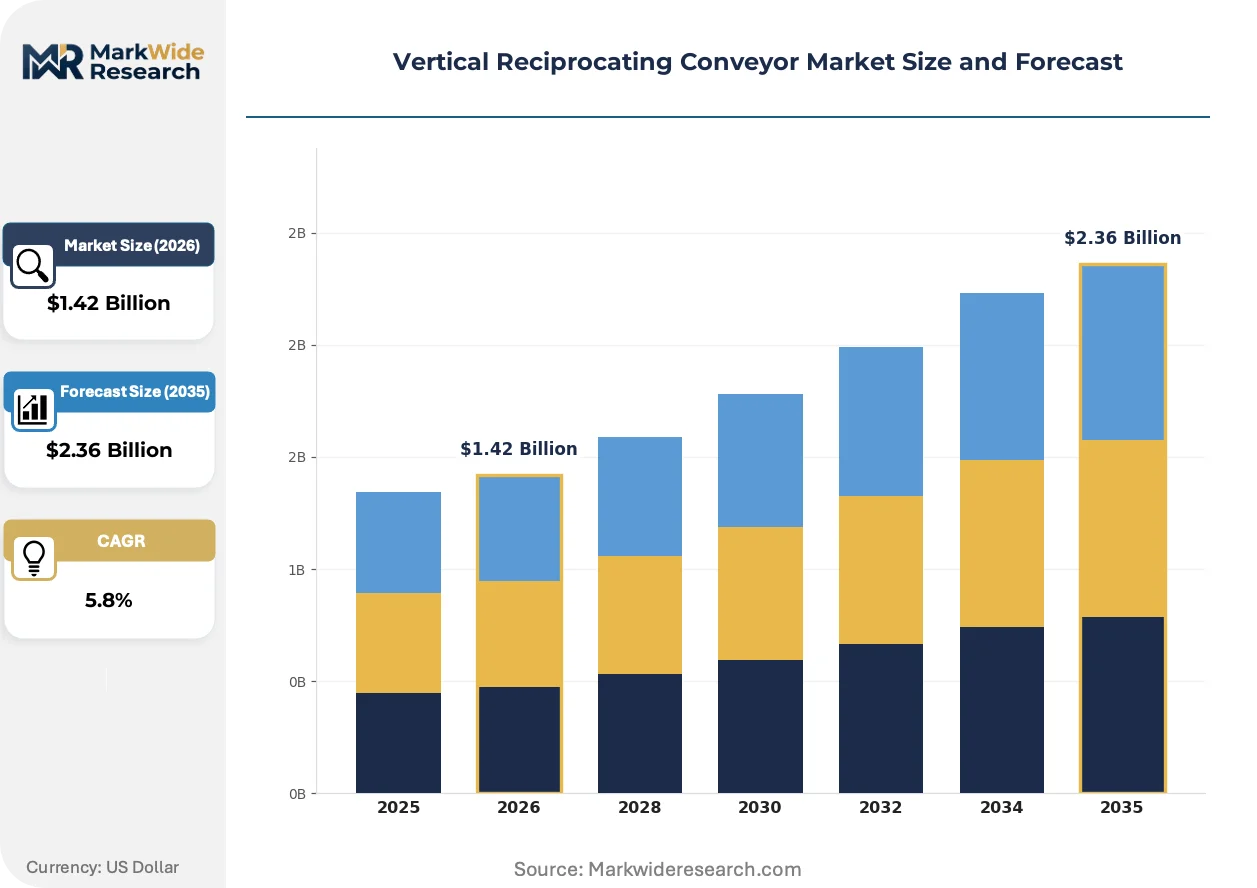
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding VRC, Rack-Mounted VRC, Custom VRC, Hydraulic VRC End User: Manufacturing, Retail, Warehousing, Construction Technology: Hydraulic, Electric, Mechanical, Pneumatic Installation Type: Permanent, Portable, Modular, Custom |
| Companies Covered | PFlow Industries, Autoquip, Wildeck, Advance Lifts, Industrial Kinetics, NERAK Systems, Custom Industrial Products, Beech Design and Manufacturing, Qimarox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Reciprocating Conveyor Market Emerging Trajectories
Sensor integration and predictive analytics are transforming VRC maintenance economics while regulatory harmonization pressures reshape product architecture for multinational facility operators.
Variable frequency drive technology paired with regenerative braking systems is digitizing energy consumption patterns in electric VRC installations. Large retail distribution centers in Germany deploy these systems to capture and reuse descent-phase energy. Real-time power monitoring enables facility managers to allocate vertical transport costs to specific operational zones.
REACH substance restrictions and EU Machinery Directive updates are forcing material substitutions in hydraulic fluid formulations and surface coatings. Manufacturers serving European markets reformulate seal compounds and paint systems to maintain compliance. Chinese exporters to the European Union face additional testing and documentation burdens for component traceability.
Buyer consolidation among national third-party logistics providers concentrates specification authority at headquarters procurement functions. Regional facility managers lose autonomy to select local VRC vendors, with preferred supplier lists narrowing to three to five national accounts. This concentration is most visible in the United States where warehouse automation standardization across fifty-plus facilities drives volume pricing leverage.
Vertical Reciprocating Conveyor Market Segmentation
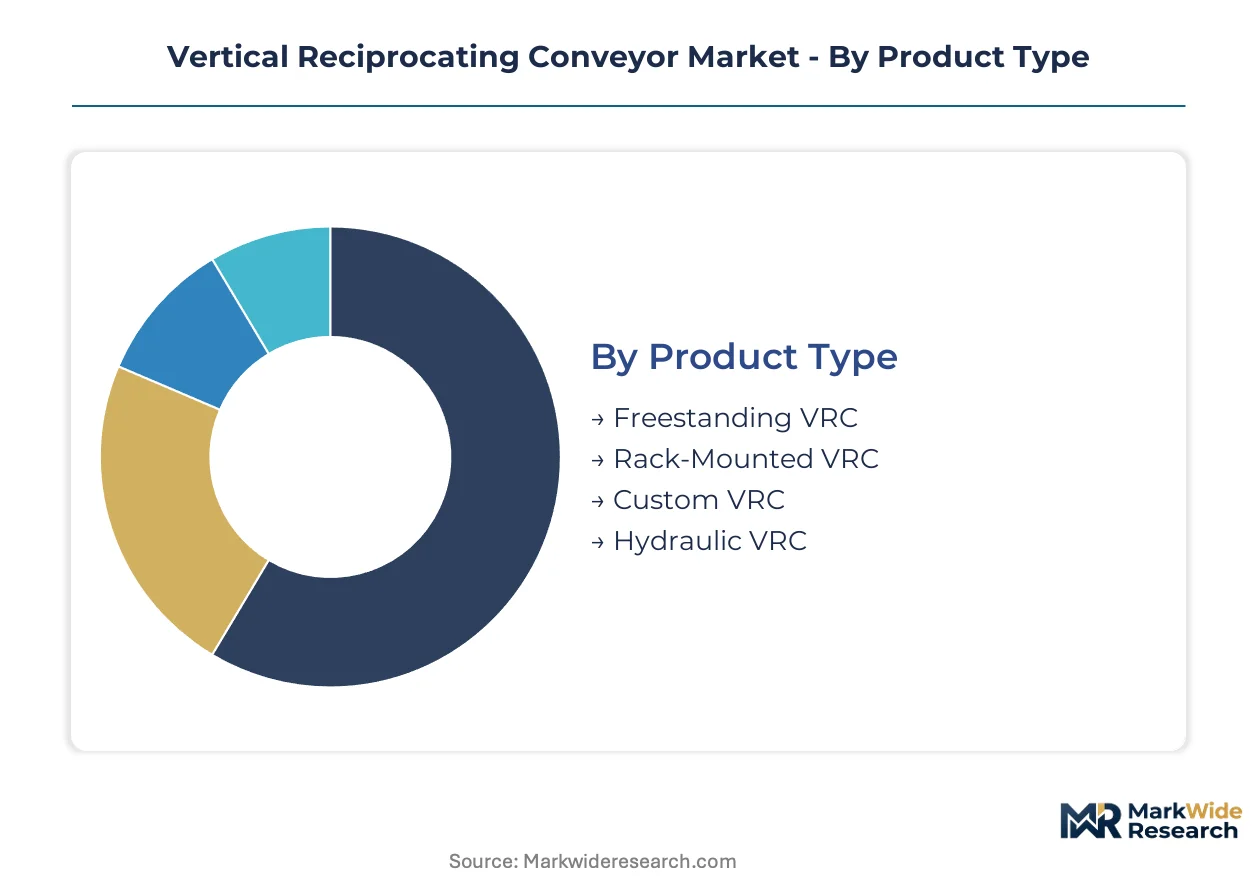
Vertical reciprocating conveyor procurement decisions cascade through four distinct lenses: physical configuration, operational environment, drive technology, and deployment flexibility. Each segmentation axis carries different weight across capital planning cycles, maintenance contracts, and regulatory compliance pathways.
Product Type:
Use-case spectrum spans standardized material transport to engineered integration with facility infrastructure.
- Rack-Mounted VRC:These units attach directly to pallet racking systems, eliminating dedicated floor footprint while enabling vertical pick paths in dense storage environments. E-commerce fulfillment centers in the United States specify rack-mounted configurations to maximize cubic storage density without expanding building envelopes.
- Hydraulic VRC:Heavy-duty lifting platforms powered by fluid pressure systems achieve rated capacities exceeding standard electric alternatives. Industrial manufacturing facilities in Germany deploy hydraulic units for die handling and heavy component movement between production floors.
- Freestanding VRC:Self-supporting structural frames enable installation without building modification, serving leased facilities and temporary operations.
- Custom VRC:Engineered-to-order platforms accommodate non-standard dimensions, extreme temperature ranges, or integration with existing conveyor networks.
Established volume favors hydraulic configurations; emerging adoption favors rack-mounted systems.
End User:
Customer type determines specification priorities across load capacity, duty cycle, and safety certification requirements.
- Warehousing:Third-party logistics operators require ASME B20.1-certified units with high cycle rates and minimal downtime. Multi-tenant distribution facilities in China prioritize standardized platforms to simplify maintenance across heterogeneous tenant requirements.
- Manufacturing:Production floor integration demands precise alignment with work-in-process flow and lean layout principles. Automotive suppliers in the United States specify electric VRC systems for just-in-time component delivery to assembly stations.
- Retail:Back-of-store operations emphasize compact footprints and quiet operation for customer-facing environments.
- Construction:Temporary material hoisting applications favor portable configurations with rapid deployment and decommissioning capabilities.
Manufacturing represents the largest installed base; warehousing exhibits the steepest expansion trajectory.
Technology:
Margin structure varies significantly across drive system architectures and energy consumption profiles.
- Electric:Variable frequency drive systems deliver precise speed control and regenerative braking for energy recovery. German retail distribution centers deploy electric VRC platforms to meet corporate sustainability targets and reduce operating expenditure.
- Hydraulic:Fluid power systems dominate applications requiring sustained lifting force at low speeds. Heavy industrial users in the United States accept higher energy costs for proven durability under shock loading conditions.
- Mechanical:Chain and sprocket drives serve light-duty applications with minimal maintenance infrastructure.
- Pneumatic:Compressed air systems address explosive atmosphere requirements and food-grade sanitary specifications.
Electric systems gain specification share fastest; hydraulic retains dominance in heavy-load segments.
Installation Type:
Supply concentration and lead time exposure differentiate deployment approaches for facility planners.
- Permanent:Fixed structural integration with building systems maximizes load capacity and operational longevity. Greenfield manufacturing facilities in Germany anchor permanent VRC installations during initial construction to minimize later disruption.
- Modular:Prefabricated subassemblies enable phased expansion and reconfiguration as operational requirements evolve. Rapid-growth e-commerce operators in the United States favor modular platforms to preserve capital deployment flexibility.
- Portable:Skid-mounted or caster-equipped units relocate between sites without disassembly.
- Custom:Site-specific engineering addresses unusual vertical travel distances, limited pit depths, or adjacent obstruction constraints.
Permanent installations anchor replacement revenue; modular configurations are climbing the fastest among new specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in vertical reciprocating conveyors tilt toward import dependence in rapidly industrializing economies while established manufacturing bases sustain export competitiveness through engineering specialization and certification depth.
United States
Warehouse automation retrofits and e-commerce fulfillment center expansions drive specification of rack-mounted and hydraulic configurations across the Midwest and Southeast. OSHA workplace safety enforcement and ASME B20.1 certification requirements compel facility upgrades in multi-level distribution networks. The Chicago industrial corridor and Dallas-Fort Worth logistics cluster anchor domestic fabrication capacity and system integration expertise.
Germany
Automotive supplier reshoring and lean manufacturing facility investments sustain demand for precision electric VRC systems with regenerative braking. The EU Machinery Directive and CE marking requirements shape product architecture for integrated safety systems. The Stuttgart industrial region and Bavarian manufacturing belt concentrate specification authority among automation integrators serving automotive and electronics sectors.
China
Cold chain logistics infrastructure gaps and domestic warehouse automation investments create specification opportunities for insulated and standard VRC platforms. GB standards and SAMR oversight define compliance pathways for domestic equipment procurement and imported system validation. The Yangtze River Delta and Pearl River Delta logistics clusters drive volume deployment in third-party distribution facilities serving consumer e-commerce.
Japan
Compact facility footprints and aging workforce demographics accelerate replacement of manual lifting with automated vertical transport in manufacturing and retail back-of-store operations. METI industrial productivity initiatives and JIS standards govern equipment specification in precision manufacturing sectors. The Kanto region around Tokyo and the Chubu industrial zone near Nagoya concentrate demand from automotive and electronics assembly facilities.
India
Third-party logistics expansion and organized retail infrastructure investments introduce multi-level material handling requirements in temperature-controlled and ambient distribution facilities. BIS certification and state-level industrial policy incentives shape procurement decisions in greenfield warehouse developments. The Maharashtra industrial corridor and Delhi-NCR logistics cluster anchor early adoption among national distribution operators.
Vertical Reciprocating Conveyor Market Vendor Landscape
On the supply side, the industry is moderately fragmented with tiered specialization across custom-engineered systems and standardized modular platforms. Engineering-intensive fabricators anchor complex industrial installations requiring site-specific structural integration. Scale-oriented manufacturers sustain broad product lines across hydraulic and electric drive configurations. Competitive dynamics center on ASME B20.1 certification depth and geographic proximity to Midwestern hydraulic component clusters.
Among North American specialists, PFlow Industries, Autoquip, and Wildeck occupy distinct positioning within the competitive structure. PFlow Industries exemplifies the engineering-centric archetype with emphasis on custom-configured vertical transport solutions. Autoquip represents fabrication depth serving industrial clients with complex load and dimensional requirements. Wildeck anchors the scale-driven tier with broad manufacturing coverage across standard and modular product lines serving warehousing and manufacturing segments.
| Leading Market Players |
|---|
| PFlow Industries |
| Autoquip |
| Wildeck |
| Advance Lifts |
| Industrial Kinetics |
| NERAK Systems |
| Custom Industrial Products |
| Beech Design and Manufacturing |
| Qimarox |
| Others |
Supply Flow & Price Mechanics
Midwestern United States hydraulic component manufacturing clusters concentrate supply-side leverage for heavy-load VRC drive assemblies, anchoring margin capture at the precision-machined subsystem tier where fabrication depth differentiates quoting authority.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across the VRC market. Three-tier pricing stratifies across ASME B20.1-certified premium installations, standard modular platforms, and economy-grade mechanical units. Price differentiation rests on certification depth and geographic delivery cost, with certified hydraulic systems commanding substantial premiums over electric alternatives. Cost compression in standard configurations is intensifying because steel input volatility and extended ASME certification timelines compress fabricator margins. Third-party logistics operators exhibit the highest price sensitivity due to volume procurement standardization, while automotive OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Extended payment terms from national distribution operators now stretch to ninety days, forcing tier-two fabricators toward supply-chain finance facilities. Geographic supply concentrates in the United States, Germany, and China, with hydraulic cylinder production anchored in the American Midwest and precision electric drive manufacturing clustering in Baden-Württemberg. Raw material dependencies span structural steel, precision-machined aluminum castings, and specialized hydraulic seal compounds. Single-source vulnerability in ASME-certified inspection services creates chokepoint exposure for custom installations. Distribution runs through direct OEM relationships for large industrial projects and regional integrator networks for standard warehousing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VRC market sits in early-cycle recovery as manufacturing reshoring and warehouse automation retrofits reactivate capital expenditure pipelines delayed by prior interest rate environments.
For Market Incumbents: Build certification moats around ASME B20.1 inspection capabilities and CE marking pre-certification to defend against emerging modular platform specialists. Deepen backward integration into hydraulic cylinder manufacturing to capture margin pools currently concentrated in Midwestern component suppliers. Anchor capacity in the Dallas-Fort Worth logistics corridor to reduce delivery cost exposure on Southeast distribution center projects. For New Entrants and Emerging Players: Cold chain logistics infrastructure in China offers substantial white-space opportunity where insulated VRC designs remain underdeveloped relative to ambient warehousing penetration. Temperature-controlled food distribution facilities in the Yangtze River Delta lack standardized vertical transport between refrigerated levels, creating specification gaps for purpose-engineered platforms. Partner with European automation integrators seeking CE-compliant modular suppliers to bypass direct certification investment requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial fabricators holding strong Midwestern manufacturing positions but lacking IoT predictive maintenance capabilities. The five-to-ten-year viability window favors platforms with sensor-enabled service revenue models over pure equipment manufacturers. Watch for consolidation signals when national third-party logistics providers narrow preferred supplier lists below four vendors, indicating pricing power inflection toward scaled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| ASME B20.1 Certification Investment | Pre-certified platforms accelerate specification with national third-party logistics procurement functions. |
| IoT Predictive Maintenance Integration | Sensor-enabled units enable equipment-as-a-service models for fleet operators managing multi-site facilities. |
| Backward Integration into Hydraulic Components | In-house cylinder production reduces exposure to Midwestern supply concentration and commodity volatility. |
| Cold Chain Specialization Development | Insulated VRC designs address condensation and thermal bridging gaps in Chinese temperature-controlled distribution. |
| CE Marking Pre-Certification | Modular platforms with integrated safety systems capture European warehouse automation integrator preference. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, customs and trade data, ASME certification registries, and industrial equipment procurement databases. Bottom-up triangulation across facility-level specification data and top-down reconciliation with national warehouse automation investment flows anchored volume estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by configuration and drive technology, end-user industry verticals, and installation flexibility tiers. CAGRs were derived from fitted growth curves applied to replacement cycle compression rates and greenfield facility commissioning schedules. Steel price volatility indices and ASME inspection queue durations served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by modular platform specialists or accelerated IoT service rollouts by national accounts would shift outcomes. Macroeconomic deviation in construction and logistics capital expenditure, regulatory acceleration in European energy efficiency standards, or breakthrough developments in continuous vertical conveyor technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Roller Crusher Market