
 Industrial Plate Bending Machines Market | 2026-2036
Industrial Plate Bending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Plate Bending Machines Market Insights
The gap between premium CNC-controlled systems and commodity mechanical units is broadening across industrial metal fabrication. DAVI leverages its Italian engineering heritage to dominate high-tonnage naval and wind-tower applications. FACCIN sustains competitive positioning through captive manufacturing of heavy-duty rolls up to 12,000 tons capacity. Haeusler anchors its reputation in German-speaking markets with precision calibration for nuclear and pressure-vessel sectors.
Industrial plate bending machines are mechanical or hydraulic systems designed to cold-form or hot-form flat metal plates into cylindrical, conical, or complex curved geometries through three- or four-roll configurations, typically handling thicknesses from 1 mm to 300 mm and widths exceeding 12 meters for wind-tower monopiles and ship hull sections. Their primary purpose centers on producing structurally certified curved components for load-bearing infrastructure where weld-seam integrity depends on precise bend radius control and minimal residual stress. CNC bending machines command premium pricing due to programmable repeatability and integration with CAD/CAM workflows, while hydraulic systems retain volume leadership in heavy-plate segments above 50 mm thickness. Electric bending machines represent the fastest-growing technology category as shipyards and automotive stamping operations seek energy efficiency and reduced hydraulic-fluid maintenance.
EU Machinery Directive 2006/42/EC and ISO 12681 standards mandate safety interlocks, residual-stress documentation, and CE marking for plate bending equipment sold within European Economic Area member states, effectively raising engineering barriers for non-compliant imports. In the United States, OSHA machine-guarding regulations and ASME Boiler and Pressure Vessel Code compliance shape procurement specifications for energy and petrochemical fabricators. Stakeholders must monitor how Chinese GB standards and South Korean KOSHA certifications evolve as alternative compliance pathways that could fragment market access requirements.
Market Dynamics
Electric servo-drive architectures are displacing hydraulic power trains across mid-tonnage plate bending applications, compressing energy consumption benchmarks and recalibrating maintenance cost structures for shipbuilders and wind-tower fabricators.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Mandatory CE marking and safety interlock requirements for European Economic Area sales are filtering out non-compliant imports and elevating engineering standards for certified equipment.
- Offshore wind monopile fabrication:South Korean and Japanese shipyards are scaling CNC-controlled four-roll systems to handle 12-meter-plus plate widths for next-generation turbine foundations.
- Hot-forming process automation:Integration of thermal profiling with mechanical bending is enabling thicker plate processing above 150 mm for pressure-vessel applications without post-bend heat treatment.
Market Restraints
- Specialized alloy plate volatility:Nickel and molybdenum price swings directly distort project quoting cycles for nuclear and chemical-sector fabricators.
- Roll manufacturing concentration:Forged steel roll supply concentrates among a handful of European and Japanese specialty foundries, creating bottleneck vulnerability for OEMs above 6,000-ton capacity ratings.
- Residual stress documentation burden:ISO 12681 compliance requires extensive metrology protocols that extend delivery timelines for custom naval contracts.
Strategic Opportunities
- India shipyard modernization:Defense and commercial vessel programs under the PLI scheme are creating first-mover advantage for CNC bending system suppliers with localized service networks.
- Retrofit electric conversion kits:Hydraulic-to-servo retrofit packages are opening installed-base revenue streams among German and Italian metal fabricators with aging mechanical assets.
- Dual carbon alignment:Chinese GB standards and provincial emissions mandates are accelerating replacement demand for energy-intensive hydraulic systems in Yangtze River Delta manufacturing clusters.
Industry Challenges
- CNC programming specialization:Shortage of operators fluent in CAD/CAM workflow integration for complex conical and variable-geometry bending is constraining throughput at advanced facilities.
- ASME Section VIII certification timelines:Pressure-vessel code compliance documentation extends order-to-acceptance cycles by 8-14 months for nuclear and petrochemical projects.
- Legacy control architecture integration:Proprietary CNC protocols from 1990s-era installations resist interoperability with modern MES and digital-twin platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Plate Bending Machines Market |
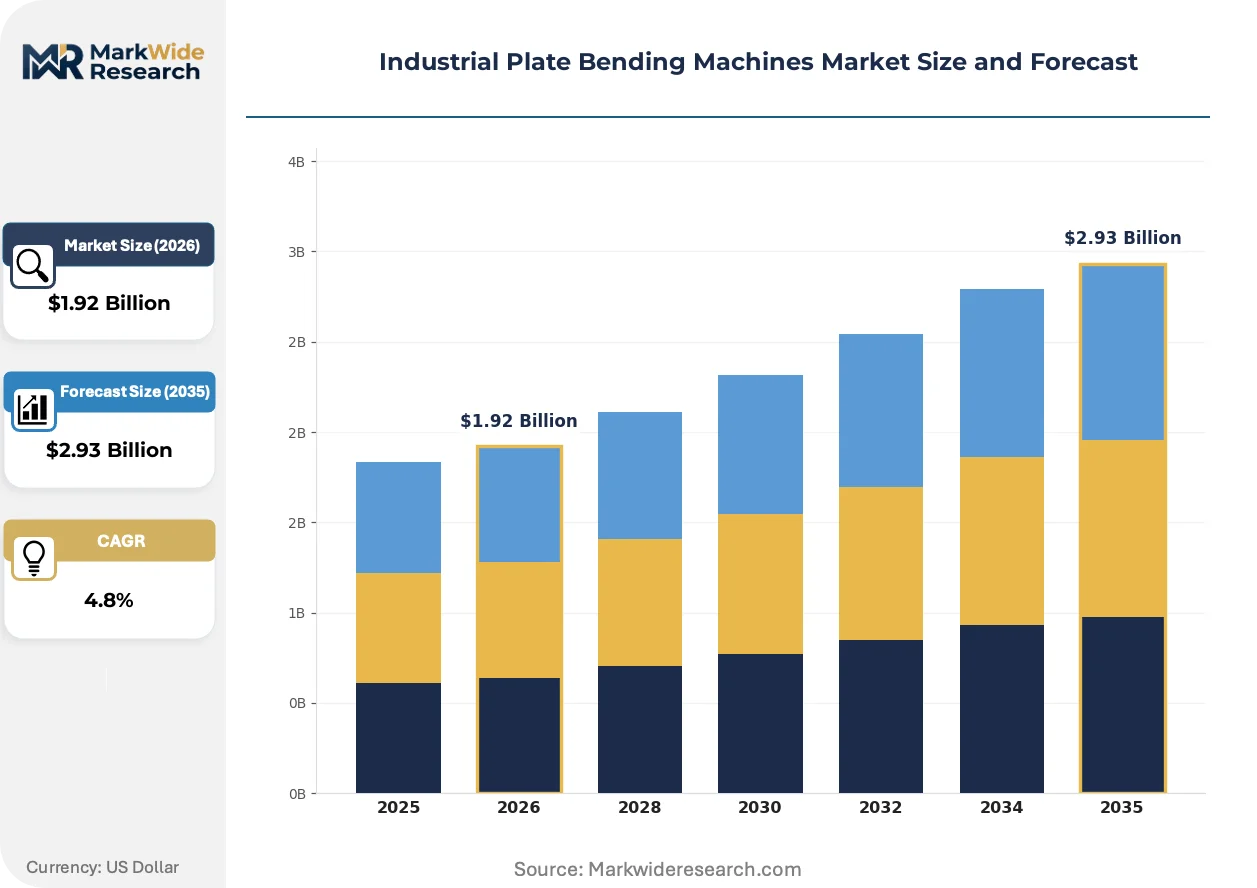
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Bending Machines, Mechanical Bending Machines, CNC Bending Machines, Electric Bending Machines End User: Aerospace, Shipbuilding, Automotive, Construction Technology: Manual, Semi-Automatic, Fully Automatic, Computer Controlled Application: Metal Fabrication, Rail Industry, Architectural Components, Heavy Machinery |
| Companies Covered | DAVI, FACCIN, Haeusler, SweBend, AMB Picot, HARSLE, MIHARMLE, MYT, Himalaya Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Plate Bending Machines Market Trends and Innovations
Real-time roll-force sensing and adaptive crowning algorithms are redefining precision benchmarks for thick-plate forming, enabling first-pass yield improvements that compress material waste and rework labor.
Digital twin simulation platforms are integrating with physical bending sequences to predict springback behavior before plate contact. German automotive stamping operations and South Korean shipyards are deploying these systems for prototype-to-production handoffs. The technology is compressing setup times from hours to minutes for multi-radius hull sections.
OSHA machine-guarding updates and ASME Boiler and Pressure Vessel Code revisions are tightening documentation requirements for residual-stress measurement and traceability. US energy and petrochemical fabricators must now demonstrate compliance through third-party witness testing. This regulatory pressure is elevating procurement specifications toward integrated quality-management systems with automated data logging.
After-sales service unbundling is fragmenting traditional OEM revenue models. Wind-tower fabricators in Denmark and Spain are negotiating performance-based maintenance contracts separate from equipment purchase, transferring operational risk to service providers. This behavioral shift is most pronounced in offshore wind supply chains where uptime guarantees dominate vendor selection criteria.
Industrial Plate Bending Machines Market Segmentation
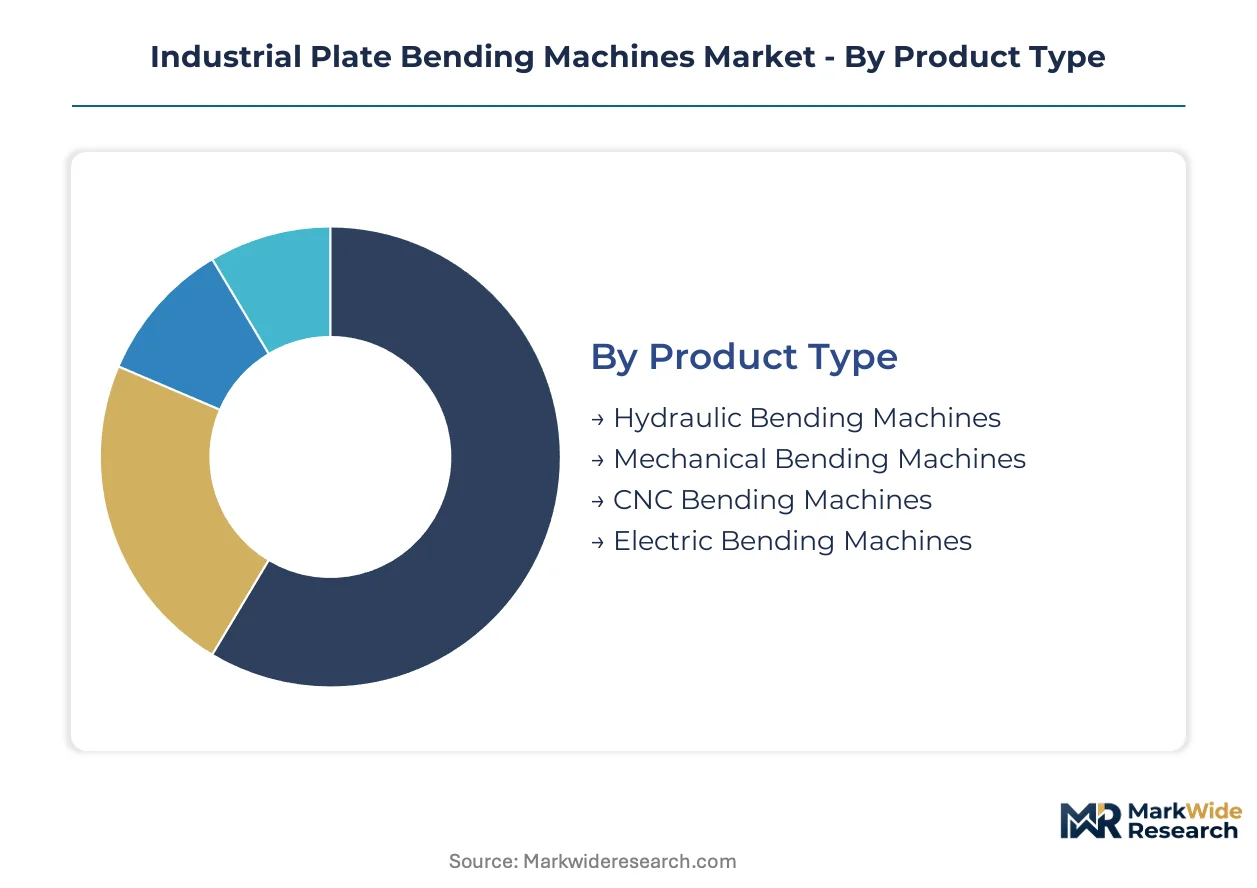
Industrial plate bending machines serve divergent operational requirements across tonnage classes, automation levels, and end-use precision demands. Segmentation reveals how specification trade-offs between throughput, accuracy, and capital intensity shape procurement patterns among shipbuilders, automotive stampers, and heavy fabricators.
Product Type:
Customization intensity varies sharply across this category, from standardized mechanical units to project-engineered CNC systems requiring CAD/CAM integration and site-specific calibration protocols.
- CNC Bending Machines:Programmable multi-axis systems with real-time roll-force feedback and adaptive crowning algorithms. South Korean shipyards and German automotive corridors specify these for 12-meter-plus wind-tower monopiles and precision hull sections where repeatability certifications are mandatory.
- Hydraulic Bending Machines:Fluid-power architectures dominating heavy-plate segments above 50 mm thickness with capacities reaching 12,000 tons. Demand concentrates in nuclear pressure-vessel fabrication and petrochemical storage tank construction where brute forming force outweighs energy efficiency priorities.
- Mechanical Bending Machines:Gear-driven configurations for standardized cylindrical and conical bending in mid-tonnage ranges. Construction and rail fabricators in India and Southeast Asia deploy these for cost-sensitive projects with lower complexity tolerances.
- Electric Bending Machines:Servo-drive systems displacing hydraulic power trains across 10-50 mm thickness applications. Shipyards in Japan and Denmark are adopting these for energy efficiency gains and elimination of hydraulic-fluid maintenance regimes.
Most installed capacity flows through Hydraulic Bending Machines. Expansion is steepest in Electric Bending Machines.
End User:
Margin profiles diverge across this category based on certification burden, contract duration, and aftermarket service attach rates.
- Shipbuilding:The dominant demand source for high-tonnage four-roll systems handling 80-300 mm plate thickness. South Korean and Japanese yards under government fleet modernization programs are specifying CNC-controlled units with integrated thermal profiling for thick-plate forming without post-bend heat treatment.
- Automotive:Precision-focused segment requiring tight bend radius control for structural chassis components and battery enclosure stampings. German and Czech stamping operations are deploying digital-twin-integrated bending cells to compress prototype-to-production handoffs.
- Aerospace:Specialized demand for titanium and aluminum alloy forming with residual-stress documentation per AS9100 and NADCAP requirements. Tier-1 airframe fabricators in France and the United States procure calibrated systems with third-party witness testing protocols.
- Construction:Volume segment for standardized structural steel bending in commercial building and infrastructure projects. Chinese and Indian fabricators prioritize mechanical and semi-hydraulic units for rebar cages, tunnel segments, and stadium roof trusses.
Shipbuilding commands the highest average selling prices per installation. Automotive is gaining share fastest through electrification-driven chassis redesign cycles.
Technology:
Automation depth determines operator skill requirements, throughput consistency, and integration feasibility with upstream cutting and downstream welding cells.
- Computer Controlled:Fully integrated CAD/CAM workflows with automatic springback compensation and production data logging for quality traceability. EU Machinery Directive compliance and ISO 12681 documentation requirements are mandating these configurations for European Economic Area sales.
- Fully Automatic:Programmable cycle execution with minimal operator intervention for repeat batch production. Wind-tower fabricators in Spain and Denmark deploy these for monopile section series production with uptime guarantee contracts.
- Semi-Automatic:Operator-supervised automation with manual setup and inspection checkpoints. Mid-scale metal fabricators in Poland and Turkey favor these for mixed-model production with frequent changeovers.
- Manual:Hand-cranked or lever-actuated systems for low-volume prototype work and maintenance shop applications. Remaining demand concentrates in developing market repair facilities and vocational training institutes.
Computer Controlled systems anchor premium pricing tiers. Fully Automatic configurations are climbing the fastest as offshore wind supply chains scale.
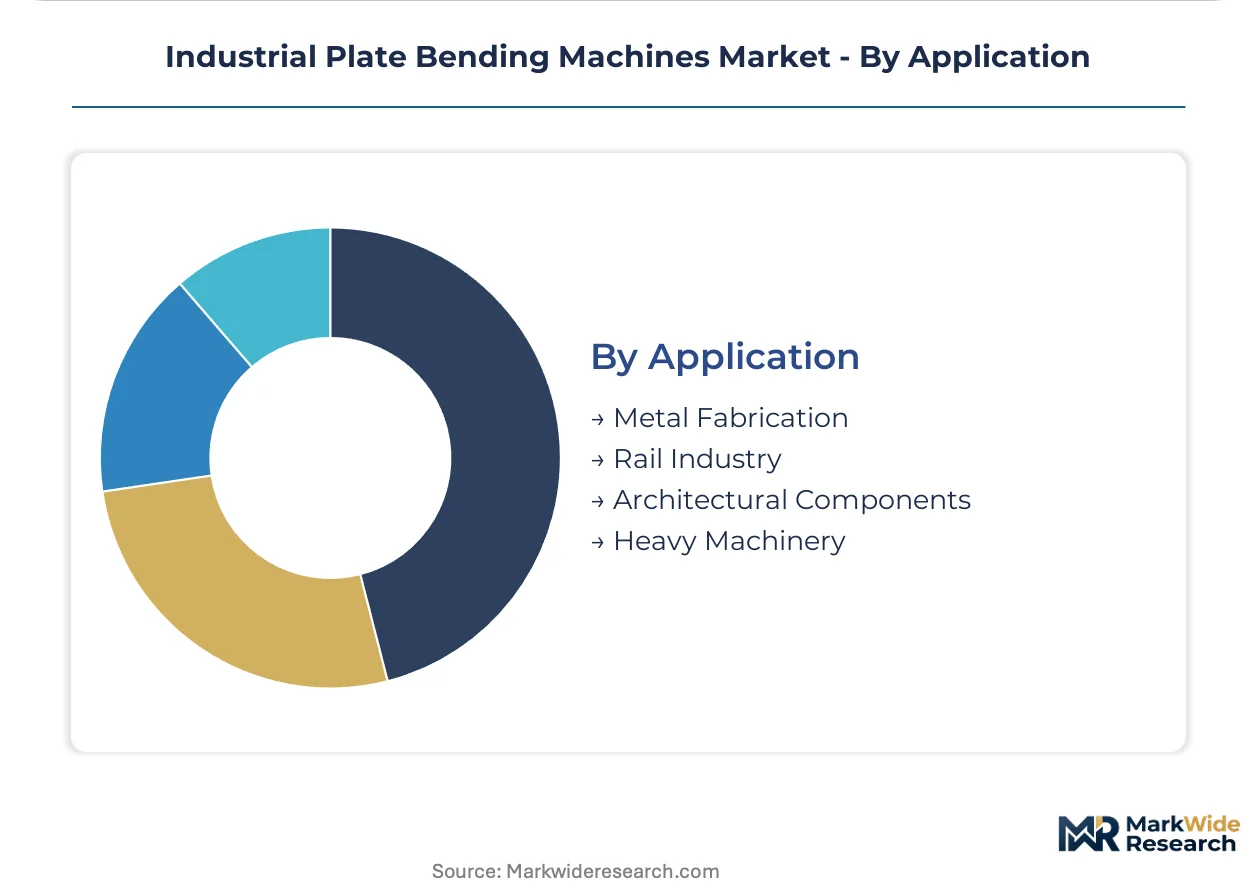
Application:
Geographic clustering of downstream industries shapes regional equipment specifications and service network requirements.
- Metal Fabrication:Broad category encompassing job shops and contract manufacturers serving multiple end-markets. German and Italian metalworking districts concentrate demand for flexible CNC systems with quick-change tooling for mixed-thickness workflows.
- Heavy Machinery:Mining equipment, agricultural machinery, and industrial press frame production requiring extreme thickness capacity above 150 mm. Brazilian and Australian fabricators serving resource extraction sectors specify heavy-duty hydraulic lines with hot-forming integration.
- Rail Industry:Locomotive underframe, tank car, and track component bending with stringent fatigue-life specifications. Chinese and European rail OEMs procure systems with automated residual-stress mapping for weld-seam preparation.
- Architectural Components:Aesthetic metal forming for facades, canopies, and sculptural elements requiring variable-radius and free-form capabilities. UAE and Qatari construction booms are stimulating demand for precision four-roll systems with artistic surface finish preservation.
Metal Fabrication absorbs the largest equipment volume. Heavy Machinery is expanding most quickly through mining capital expenditure recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled CNC operators and calibration specialists cluster around legacy shipbuilding centers and precision metalworking districts, creating geographic moats that reinforce regional supply chain dominance.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive demand for 12-meter-plus four-roll systems under government fleet modernization programs. KOSHA certification requirements mandate safety interlocks and residual-stress documentation for domestic shipyard equipment. Ulsan and Geoje shipbuilding complexes concentrate procurement of CNC-controlled units with integrated thermal profiling for thick-plate forming.
Germany
Automotive stamping operations in Baden-Württemberg and Bavaria specify precision bending cells for electrification-driven chassis redesigns. EU Machinery Directive 2006/42/EC enforces CE marking and automated quality-management systems for equipment sales. The Stuttgart automotive corridor and Ruhr metal fabrication belt anchor demand for digital-twin-integrated bending workflows.
Japan
Imabari Shipbuilding and Japan Marine United scale electric servo-drive systems to eliminate hydraulic-fluid maintenance in clean-room hull assembly. METI industrial efficiency standards accelerate replacement of energy-intensive hydraulic assets. Nagasaki and Kure shipyard clusters prioritize programmable repeatability for naval and commercial vessel programs.
China
Jiangnan Shipyard and CSSC facilities in the Yangtze River Delta expand CNC bending capacity for offshore wind monopile export contracts. GB standards and provincial dual carbon mandates force retirement of hydraulic systems in Shanghai and Jiangsu manufacturing zones. Nantong and Shanghai port industrial zones concentrate heavy-plate fabrication for pressure-vessel and wind-tower exports.
United States
Energy sector fabricators in Texas and Louisiana procure ASME-certified systems for petrochemical storage and pressure-vessel construction. OSHA machine-guarding regulations and ASME Boiler and Pressure Vessel Code compliance shape procurement specifications. Houston's energy corridor and Gulf Coast fabrication yards anchor demand for third-party witness testing and automated residual-stress documentation.
Industrial Plate Bending Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor landscape where forged roll manufacturing concentration creates bottleneck vulnerability above 6,000-ton capacity ratings. The market structures around three archetypes: Italian and German precision engineering houses with naval and nuclear certifications, East Asian scale producers serving cost-sensitive construction segments, and Nordic specialists targeting wind-tower and offshore applications. Strategic moves concentrate on M&A for roll manufacturing capacity and geographic expansion through localized service networks in India and Southeast Asia.
Within the European precision tier, DAVI and FACCIN occupy positions anchored by Italian engineering heritage and captive heavy-roll production capabilities. Haeusler exemplifies German-speaking market dominance through calibration-intensive positioning for nuclear and pressure-vessel sectors. These three represent distinct archetypes: DAVI as naval-wind specialization, FACCIN as maximum-capacity scale, and Haeusler as precision-certification focus.
| Leading Market Players |
|---|
| DAVI |
| FACCIN |
| Haeusler |
| SweBend |
| AMB Picot |
| HARSLE |
| MIHARMLE |
| MYT |
| Himalaya Machinery |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of forged steel rolls above 6,000-ton capacity anchors both supply security and pricing power for European precision OEMs serving nuclear and naval certification tiers. This backward integration choice insulates DAVI, FACCIN, and Haeusler from foundry bottlenecks while supporting premium positioning against Asian scale competitors.
Pricing Analysis
Service bundling unbundling is fragmenting traditional equipment-only transactions. After-sales contracts now separate from capital sales, with performance-based maintenance agreements transferring uptime risk to service providers. Price differentiation rests on CE marking compliance and ISO 12681 documentation depth. Cost compression in mechanical and semi-hydraulic tiers intensifies as Chinese and Indian fabricators scale standardized production. Construction and rail segments exhibit highest price sensitivity; aerospace and nuclear sectors accept premium positioning for third-party witness testing protocols.
Supply Chain Analysis
Dual-sourcing mandates from German automotive stampers and South Korean shipyards require qualified backup suppliers for critical roll forgings. Supply concentrates in Italy, Germany, and Japan for precision-engineered systems above 4,000-ton ratings. Forged steel rolls, CNC control systems, and servo-drive architectures draw from specialty European and Japanese foundries. Single-source vulnerability concentrates in 8,000-ton-plus roll manufacturing where only three qualified suppliers exist. Distribution runs through OEM-direct sales for large naval contracts and specialized industrial distributors for mid-tonnage job shop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Electrification-driven chassis redesigns and offshore wind monopile scaling are forcing procurement specifications toward CNC-controlled, digitally-integrated systems with automated quality documentation.
For Market Incumbents: Anticipate electric servo-drive substitution eroding hydraulic maintenance revenue streams. Defend installed-base relationships by accelerating hydraulic-to-electric retrofit kit deployment in German and Italian metalworking districts. Deepen backward integration into forged roll production above 6,000-ton ratings to eliminate supply bottleneck exposure. Prioritize M&A of regional service networks in India and Southeast Asia before PLI scheme modernization peaks.
For New Entrants and Emerging Players: Mid-scale Polish and Turkish metal fabricators running mixed-model production with frequent changeovers represent the most penetrable buyer archetype. These operators seek semi-automatic configurations with manual setup flexibility at price points below full CNC integration. Target white-space in India's defense and commercial vessel programs under PLI incentives, positioning through localized calibration and spare parts availability. Go-to-market leverage: partnership with established European OEMs for technology licensing with domestic assembly.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists because fragmented aftermarket coverage creates customer churn risk that OEMs will pay to eliminate. Five-to-ten year viability hinges on electric conversion kit attach rates and wind-tower uptime guarantee contract penetration. Acquisition target archetype: CNC programming training institutes and calibration laboratories with captive customer relationships in shipbuilding clusters. Signal to watch: KOSHA and GB standard harmonization creating dual-certification cost barriers that favor consolidated compliance platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Roll Manufacturing | Eliminates bottleneck vulnerability for FACCIN and DAVI above 6,000-ton ratings. |
| Hydraulic-to-Electric Retrofit Kit Development | Opens installed-base revenue among aging German and Italian mechanical assets. |
| Localized Service Network Expansion | Captures PLI scheme demand in Indian defense and commercial shipyard modernization. |
| Digital Twin Platform Integration | Compresses setup times for South Korean shipyards and Stuttgart automotive stampers. |
| Dual Certification Compliance Investment | Positions for KOSHA-GB standard convergence in East Asian export markets. |
Research Methodology
Bottom-up shipbuilding and automotive modeling reconciled against top-down OEM shipment tracking forms the analytical core. Primary interviews with maintenance directors at German automotive stampers, plant engineers at South Korean shipyards, aftermarket service heads at Italian OEMs, and procurement teams at Chinese wind-tower fabricators were cross-validated against secondary sources including EU Machinery Directive implementation reports, KOSHA certification databases, ASME Boiler and Pressure Vessel Code filings, and customs trade records for heavy machinery imports.
Input-output matrices mapped plate thickness requirements, automation depth preferences, and certification burdens across end-use segments. Segmentation dimensions modeled include product type, end user industry, technology tier, and application category, with geographic regulatory cluster as an overlay. CAGRs were derived from equipment replacement cycles, capacity expansion announcements, and efficiency mandate compliance timelines across the projection horizon. Forecast inputs incorporated electric servo-drive adoption curves and residual-stress documentation burden impacts on delivery timelines.
Underlying measurement precision varies by segment; CNC-controlled systems with documented CE marking carry tighter precision than commodity mechanical units in fragmented construction markets. Forecasts reflect assumptions about regulatory harmonization pace, nickel and molybdenum price stability, and shipyard capital commitment durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Turning Tools Market
Tools
Adoption of Benelux Power Tools Market
Tools
Industrial Ladder Market
Tools
Wood Router Market
Tools
Belt File Sander Market
Tools
Hand Tools Market
Tools
Cold and Hot Tool Steel Market
Tools
Hand and Power Tools Market
Tools
Floor Saw Market
Tools
Painting Tools Market
Tools
Structural Wood Screws Market
Tools
Flooring Tools Market
Tools
Machining Centers Market
Tools
Edging Tool Market
Tools
Spray Gun Market
Tools
Cordless Long Neck Grinder Market