
 Reach Trucks Market | 2026-2036
Reach Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Reach Trucks Market Analysis
Asset-light leasing and fleet-as-a-service arrangements is tilting competitive dynamics toward providers with balance-sheet depth. Jungheinrich AG leverages its captive finance arm to bundle maintenance contracts with equipment subscriptions. KION Group AG anchors European market presence through Linde Material Handling's dense service network. Toyota Industries Corporation sustains cost leadership via in-house production of motors and controllers across its forklift divisions.
A reach truck is a narrow-aisle forklift with an extending mast mechanism that positions loads by telescoping the forks forward while the truck body remains stationary, typically operating in aisle widths under 2.5 meters and lifting heights exceeding 12 meters to maximize cubic warehouse utilization. Electric-powered units dominate new orders as lithium-ion battery packs displace lead-acid systems across ride-on and stand-up configurations. The warehousing vertical absorbs the majority of unit volume, while retail-driven order picker demand expands fastest as same-day fulfillment networks proliferate. Load capacity segmentation shows 2000-3000 lbs models capturing the broadest application base, though 4000 lbs variants command premium pricing in cold storage and beverage distribution.
Forklift safety standards from ISO and regional machinery directives shape mast stability requirements and operator protection mandates. OSHA enforces operator certification and inspection protocols in the United States, while the EU Machinery Directive and CE marking govern design conformity across European markets. Stakeholders must weigh total cost of ownership calculations against upfront capital outlays as electrification and automation converge in next-generation fleet procurement decisions.
Market Dynamics
Lithium-ion battery chemistry is restructuring procurement economics across warehouse fleets, compressing total cost of ownership calculations and displacing long-established lead-acid maintenance routines.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery networks in Germany, the Netherlands, and the United Kingdom are mandating high-lift narrow-aisle configurations to maximize cubic storage utilization in urban distribution nodes.
- OSHA operator certification expansion:Stricter enforcement of powered industrial truck training requirements across US distribution centers is accelerating fleet refresh cycles toward equipment with integrated safety interlocks.
- Battery thermal management advances:Liquid-cooled lithium-ion packs are eliminating shift-change battery swaps in cold storage applications, extending continuous operation windows in sub-zero environments.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings are compressing margins on electric unit production and delaying fleet electrification timelines for cost-sensitive buyers.
- Mast assembly supply concentration:Precision welding and telescoping cylinder manufacturing clusters in Baden-Württemberg and Lower Saxony create geographic vulnerability for European OEM delivery schedules.
- Lead-acid infrastructure lock-in:Existing charging room investments and maintenance technician training programs create switching friction for facilities with sunk capital in legacy battery ecosystems.
Strategic Opportunities
- India warehouse automation lag:Organized retail and third-party logistics penetration in Maharashtra and Karnataka remains below saturation, creating first-mover positioning for high-lift equipment providers.
- Fleet-as-a-service bundling:Subscription models integrating maintenance, telematics, and uptime guarantees are capturing mid-market buyers seeking balance-sheet flexibility over capital ownership.
- EU Green Deal procurement mandates:Public sector warehousing tenders increasingly specify zero-emission material handling equipment, directing public investment toward electric reach truck fleets.
Industry Challenges
- High-voltage technician scarcity:Lithium-ion battery service and diagnostics require specialized electrical certification that existing forklift mechanic training programs have not scaled to match fleet electrification velocity.
- Legacy WMS integration friction:Older warehouse management systems lack API architectures for real-time telematics data ingestion, forcing middleware development costs on automation-focused facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reach Trucks Market |
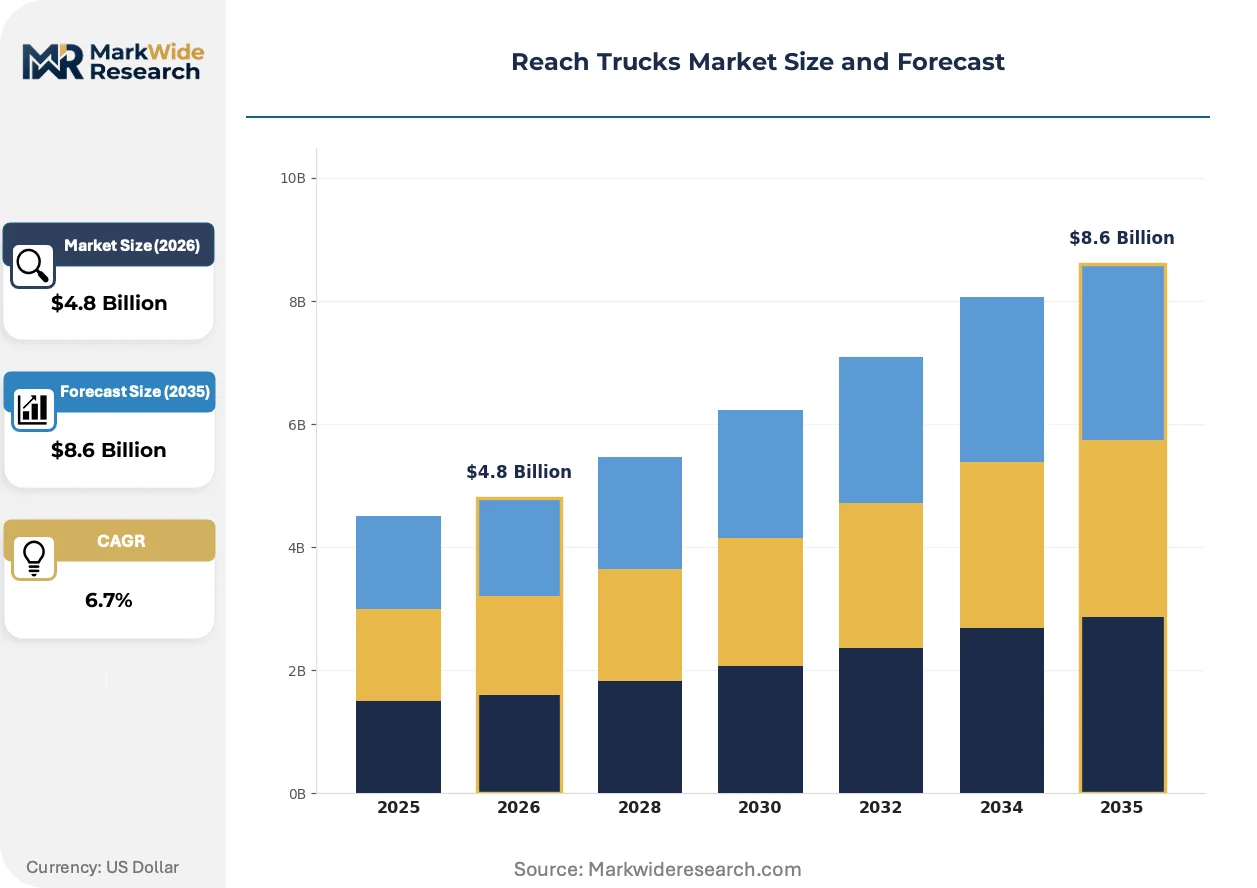
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ride-on, Walkie, Stand-up, Order Picker Industry Vertical: Retail, Warehousing, Logistics, Manufacturing Load Capacity: 1000 lbs, 2000 lbs, 3000 lbs, 4000 lbs Power Source: Electric, Diesel, LPG, Hybrid |
| Companies Covered | Crown Equipment Corporation, Jungheinrich AG, KION Group AG, Toyota Industries Corporation, Hyster-Yale Materials Handling Inc, Mitsubishi Logisnext Co.Ltd, Hangcha Group Co.Ltd, Doosan Corporation, Godrej and Boyce Manufacturing Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reach Trucks Market Emerging Trajectories
Telematics integration and autonomous navigation modules are converging to transform reach trucks from passive lifting equipment into data-generating nodes within warehouse orchestration systems.
Lithium-iron-phosphate battery chemistry is rendering obsolete the multi-battery swap infrastructure and dedicated charging rooms that dominated lead-acid operations. Cold storage distributors in northern Europe are adopting fast-charge configurations that opportunity-charge during picking cycles. This shift is compressing facility footprint requirements and eliminating the productivity losses associated with battery changeovers.
CE marking requirements under the EU Machinery Directive are tightening mast stability testing protocols and operator protection mandates. Manufacturers must now document finite element analysis of mast deflection under rated loads across the full lift height envelope. German engineering centers are absorbing the bulk of compliance certification costs, while facilities in Poland and the Czech Republic face extended approval timelines for non-EU sourced components.
Third-party logistics providers are unbundling maintenance contracts from equipment acquisition, treating uptime guarantees as separately negotiable service line items. Amazon fulfillment networks in the United Kingdom and Germany pioneered this procurement pattern, which is now migrating to mid-sized retail distribution operations. The model transfers operational risk to OEM service organizations while compressing capital deployment for fleet expansion.
Reach Trucks Market Segmentation
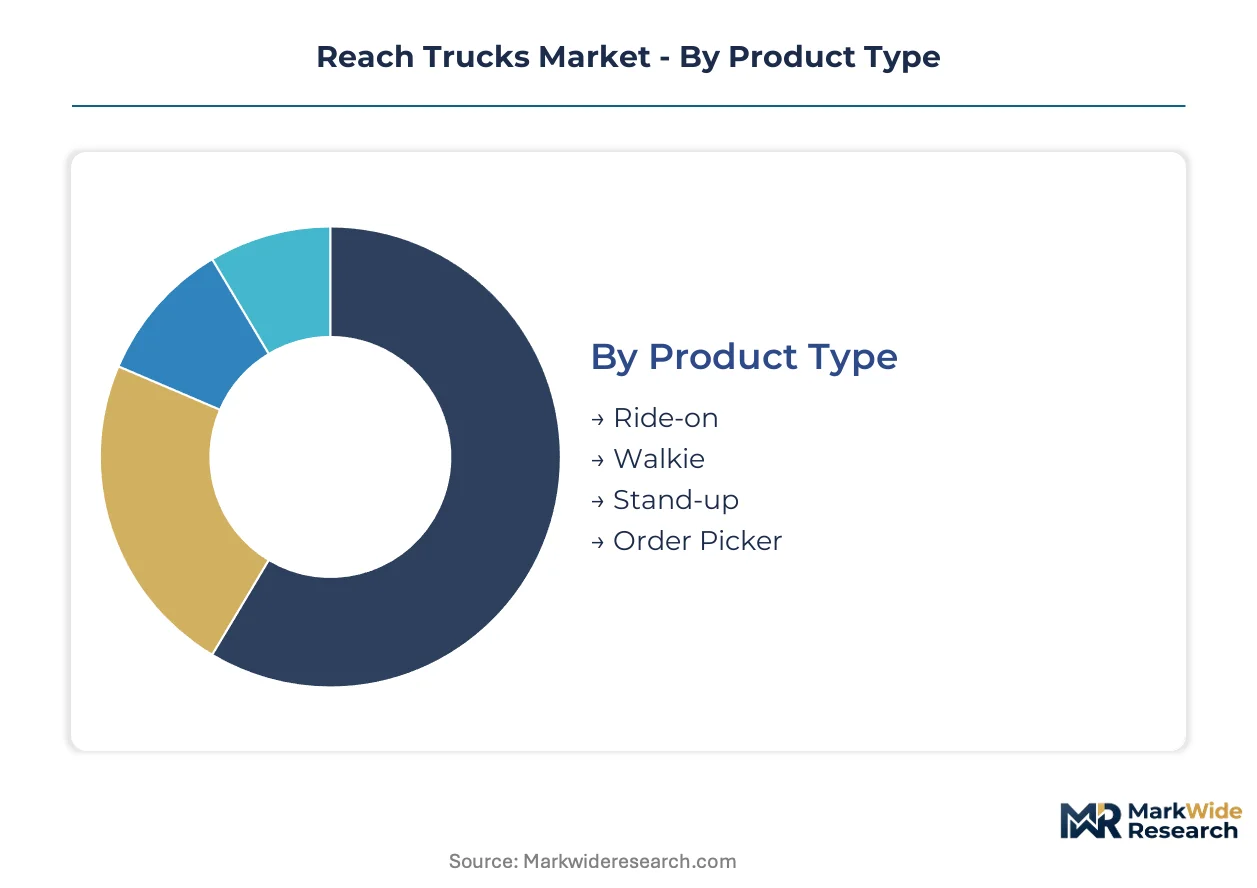
Reach truck procurement decisions cluster around four distinct dimensions: operator positioning configuration, facility application type, rated load capacity, and energy system architecture. Each dimension carries specific technical trade-offs that shape total cost of ownership and facility integration requirements.
Product Type:
Operator positioning configuration determines aisle width compatibility, operator fatigue profiles, and order picking velocity in high-density storage environments.
- Stand-up:Compact chassis design with sideways operator stance enables aisle widths below 2.5 meters. German third-party logistics providers favor this configuration for multi-shift operations in urban distribution nodes where cubic storage efficiency dominates site selection.
- Order Picker:Elevated platform lifts operator with load to enable piece-level selection from rack locations. Same-day fulfillment networks in the Netherlands and United Kingdom are absorbing volume fastest as e-commerce SKU proliferation demands case-level retrieval automation.
- Ride-on:Seated operator position suits extended transport distances across large distribution campuses. Cold storage facilities in northern Europe specify heated cabs for sub-zero continuous operation.
- Walkie:Pedestrian-controlled units serve low-lift, short-distance applications with minimal capital outlay. Small-format retail backrooms and light manufacturing cells deploy these for intermittent material movement.
Stand-up configurations hold installed capacity. Order picker variants are rotating up the share rankings.
Industry Vertical:
Application environment dictates mast stability requirements, corrosion protection specifications, and fleet utilization intensity.
- Warehousing:High-rack storage operations with lift heights exceeding 12 meters demand precision mast control and load sway damping. Battery thermal management and opportunity charging infrastructure absorb significant facility capital in multi-shift deployments.
- Logistics:Cross-dock operations with rapid load turnover prioritize travel speed and acceleration over maximum lift height. Fleet telematics integration enables throughput optimization across distributed node networks.
- Retail:Store-replenishment and backroom operations favor compact footprints with maneuverability in constrained spaces. Seasonal demand volatility drives leasing preference over capital purchase.
- Manufacturing:Work-in-process movement and finished goods staging require integration with production scheduling systems. Just-in-time material flow mandates high equipment availability and preventive maintenance rigor.
Warehousing dominates current fleet deployment. Logistics applications are expanding most quickly as fulfillment network density intensifies.
Load Capacity:
Rated lifting capacity segments procurement economics between standard material handling and specialized heavy-load applications.
- 2000-3000 lbs:Intermediate capacity range captures the broadest application base across general warehousing and distribution. Standardized pallet dimensions and typical SKU weight distributions align equipment specification with operational requirements without capacity overprovisioning.
- 4000 lbs:Heavy-duty variants command premium pricing for beverage distribution, paper products, and dense commodity storage. Reinforced mast construction and counterweight distribution enable stable operation at full rated load across the lift envelope.
- 1000 lbs:Light-capacity units serve specialized applications with dimensional constraints rather than weight limitations. Electronics and pharmaceutical distribution favor these for high-velocity piece picking from narrow aisles.
2000-3000 lbs models anchor the installed base. 4000 lbs variants are gaining share fastest as cold storage and beverage verticals expand fleet orders.
Power Source:
Energy system architecture determines facility infrastructure requirements, maintenance staffing models, and regulatory compliance pathways.
- Electric:Battery-powered units with lithium-ion chemistry displace lead-acid systems across new orders. EU Green Deal procurement mandates direct public sector warehousing investment toward zero-emission fleets.
- LPG:Liquid petroleum gas systems persist in facilities without electrical infrastructure upgrade budgets. Outdoor applications and remote distribution nodes maintain this installed base despite emissions compliance pressure.
- Diesel:Internal combustion variants retain niche deployment in heavy outdoor yard operations. Emissions regulations in Germany and the United Kingdom accelerate retirement timelines for non-electric indoor equipment.
- Hybrid:Dual-power configurations combine electric operation with combustion range extension. Limited commercial traction reflects complexity premiums against pure electric total cost of ownership improvements.
Electric systems command dominant share in new procurement. LPG installations are rotating down as lithium-ion price compression accelerates electrification economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial trade surplus in material handling equipment, exporting precision-engineered mast assemblies and control systems to warehouse automation projects across Europe and North America. Import dependence concentrates in lithium-ion battery cells and rare-earth magnet motors sourced from Asian suppliers.
Germany
Baden-Württemberg and Lower Saxony host precision welding clusters producing telescoping mast cylinders for European OEM delivery schedules. The EU Machinery Directive and CE marking requirements govern mast stability testing protocols and operator protection mandates. Jungheinrich AG leverages its captive finance arm in Hamburg to bundle maintenance contracts with equipment subscriptions across domestic third-party logistics networks.
United States
OSHA enforces operator certification and inspection protocols across distribution centers, accelerating fleet refresh cycles toward equipment with integrated safety interlocks. The Inflation Reduction Act directs investment tax credits toward electrification of material handling fleets in federal procurement. Amazon fulfillment networks in Pennsylvania and Texas pioneered unbundled maintenance contracts, now migrating to mid-sized retail distribution operations.
Netherlands
Same-day delivery networks mandate high-lift narrow-aisle configurations to maximize cubic storage utilization in urban distribution nodes around Rotterdam and Eindhoven. EU Green Deal procurement specifications direct public sector warehousing tenders toward zero-emission reach truck fleets. Cold storage distributors in the northern provinces adopt fast-charge lithium-iron-phosphate configurations that opportunity-charge during picking cycles.
India
Organized retail and third-party logistics penetration in Maharashtra and Karnataka remains below saturation, creating first-mover positioning for high-lift equipment providers. The Production-Linked Incentive scheme for advanced chemistry cell manufacturing reduces import dependence for lithium-ion battery packs. Godrej and Boyce Manufacturing Company Limited anchors domestic assembly capacity in Mumbai for regional distribution across South Asian markets.
United Kingdom
Post-Brexit customs arrangements delay component sourcing from EU mast assembly clusters, extending approval timelines for non-EU sourced subsystems. The Health and Safety Executive enforces LOLER regulations governing lifting equipment inspection and maintenance records. Retail-driven order picker demand expands fastest in Midlands fulfillment corridors as same-day fulfillment networks proliferate.
Reach Trucks Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-engineered mast assemblies and battery management systems. Market structure tilts toward consolidated OEMs with captive finance capabilities and dense service networks. Three archetypes dominate: diversified industrial conglomerates with in-house component production, specialized material handling pure-plays with subscription-based fleet offerings, and regional assemblers serving price-sensitive emerging markets. Competitive moves concentrate on M&A to capture telematics capabilities and strategic partnerships to secure lithium-ion cell supply.
Among Germany-based industrial groups, Jungheinrich AG and KION Group AG exemplify the finance-integrated archetype, bundling equipment subscriptions with maintenance uptime guarantees. Toyota Industries Corporation represents the diversified conglomerate model, sustaining cost leadership through in-house production of motors and controllers. Crown Equipment Corporation anchors the North American specialist tier with dense service network coverage. These three occupy positions across distinct strategic vectors rather than competing head-to-head on identical capability sets.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Jungheinrich AG |
| KION Group AG |
| Toyota Industries Corporation |
| Hyster-Yale Materials Handling Inc |
| Mitsubishi Logisnext Co.Ltd |
| Hangcha Group Co.Ltd |
| Doosan Corporation |
| Godrej and Boyce Manufacturing Company Limited |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container rate volatility feeds directly into mast assembly cost structures, concentrating pricing power among Baden-Württemberg precision welders while forcing downstream buyers into longer-term contract commitments to lock in component access.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation tracks CE certification grade and battery chemistry tier, with lithium-iron-phosphate units commanding premiums over legacy lead-acid configurations. Pricing pressure stems from lithium carbonate input volatility, compressing margins on electric unit production. Leasing-oriented third-party logistics providers exhibit highest price sensitivity, while cold storage distributors with uptime-dependent operations absorb premium positioning.
Supply Chain Analysis
Dual-use technology export controls limiting flows of high-voltage battery management systems and rare-earth magnet motors constrain component sourcing flexibility. Manufacturing gravity centers on Germany, China, and South Korea, with precision mast cylinders drawing from Baden-Württemberg clusters and lithium-ion cells resting on South Korean chemistry expertise. Single-source vulnerability concentrates in telescoping cylinder suppliers, where geographic clustering creates delivery schedule risk. Distribution runs through OEM captive finance arms bundling equipment with maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician availability lags fleet electrification velocity, creating a persistent capability gap that shapes competitive positioning and M&A targeting across the forecast window.
For Market Incumbents: Entrench service network density as the primary defensive moat against fleet-as-a-service disruptors. Expand backward integration into lithium-ion battery pack assembly to capture margin compression from raw material volatility. Prioritize CE marking pre-certification investments to accelerate approval timelines against Polish and Czech competitors facing extended EU Machinery Directive compliance cycles.
For New Entrants and Emerging Players: Pursue warehouse automation lag in Maharashtra and Karnataka as the most penetrable geography, where organized retail penetration remains below saturation. Target mid-market leasing customers seeking balance-sheet flexibility over capital ownership. Lead with subscription-based fleet offerings bundling telematics uptime guarantees to differentiate against incumbent capital-sale positioning.
For Investors and Strategic Acquirers: Battery management system specialists with automotive-grade functional safety certification represent the highest-conviction acquisition archetype. Long-term viability hinges on electrification tailwinds persisting across the analysis window. Watch for inflection signals in EU Green Deal procurement mandate enforcement velocity across public sector warehousing tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Battery Integration | CE marking requirements under EU Machinery Directive accelerate certified pack adoption. |
| Fleet-as-a-Service Bundling | Jungheinrich captive finance arm demonstrates subscription model viability in German logistics networks. |
| Telematics Platform Development | Real-time data ingestion enables throughput optimization across Amazon fulfillment networks. |
| Cold Storage Thermal Management | Liquid-cooled lithium-iron-phosphate configurations eliminate shift-change battery swaps in sub-zero environments. |
| High-Voltage Technician Certification | OSHA enforcement expansion creates compliance-driven training revenue streams for service organizations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across warehouse engineering directors, fleet procurement managers, OEM aftermarket service heads, and third-party logistics operations leads. Secondary validation drew from EU Machinery Directive filings, OSHA enforcement data, customs trade records for mast cylinder imports, and SEC disclosures from listed material handling groups. Bottom-up unit shipment estimates triangulated against top-down facility automation investment flows.
Calibration anchored volume projections to facility square footage expansion in e-commerce fulfillment corridors and battery chemistry transition timelines across the modeling period. Segmentation dimensions spanned operator configuration, load capacity tier, power source architecture, and regional regulatory cluster. CAGRs derived from logistic curve fitting of electrification adoption rates and warehouse automation penetration patterns. Industry-specific inputs included lithium-ion price elasticity coefficients and mast stability testing protocol evolution under CE marking requirements.
Macroeconomic conditions sit as an overlay; deviation in warehouse construction lending rates and lithium carbonate spot pricing would shift the trajectory. Forecasts reflect documented assumptions on battery chemistry cost curves and EU Green Deal enforcement intensity. Material shifts in export control scope for battery management systems or OSHA certification mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Linear Slides Market