
 Hose Pump Market | 2026-2036
Hose Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Hose Pump Market Outlook
ISO 9001 certification cycles for pump manufacturers is collapsing from three-year to annual audit intervals in key procurement frameworks. Watson-Marlow Fluid Technology Solutions leverages captive elastomer compounding to control hose formulation consistency across pharmaceutical contracts. Verder Group anchors its position through dedicated service networks in Scandinavian water treatment markets. NETZSCH Pumps & Systems dominates slurry-transfer specifications with hardened rotor designs that extend mean time between replacements.
A hose pump is a positive-displacement device that compresses a reinforced elastomer tube with a rotating shoe or roller assembly to propel fluid without contamination; operating pressures typically range from 2 to 16 bar depending on tube reinforcement and rotor configuration. Peristaltic pumps lead value capture in biopharmaceutical aseptic filling where single-use tubing eliminates cross-batch contamination risks. Industrial hose pumps command the largest installed base in mining and construction dewatering, though margin pools are thinner due to commodity elastomer specifications. Sanitary hose pumps represent the fastest-growing configuration as food processors replace piston pumps to reduce CIP cycle downtime.
The EPA enforces Clean Water Act discharge limits that mandate zero-leak pump seals in municipal treatment upgrades, while REACH restricts phthalate plasticizers in European-sourced tubing compounds. FDA 21 CFR 177.2600 compliance for repeated food contact shapes material selection for sanitary configurations sold into US dairy processing. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as PTFE-lined hoses face substitution pressure across multiple regulatory jurisdictions simultaneously.
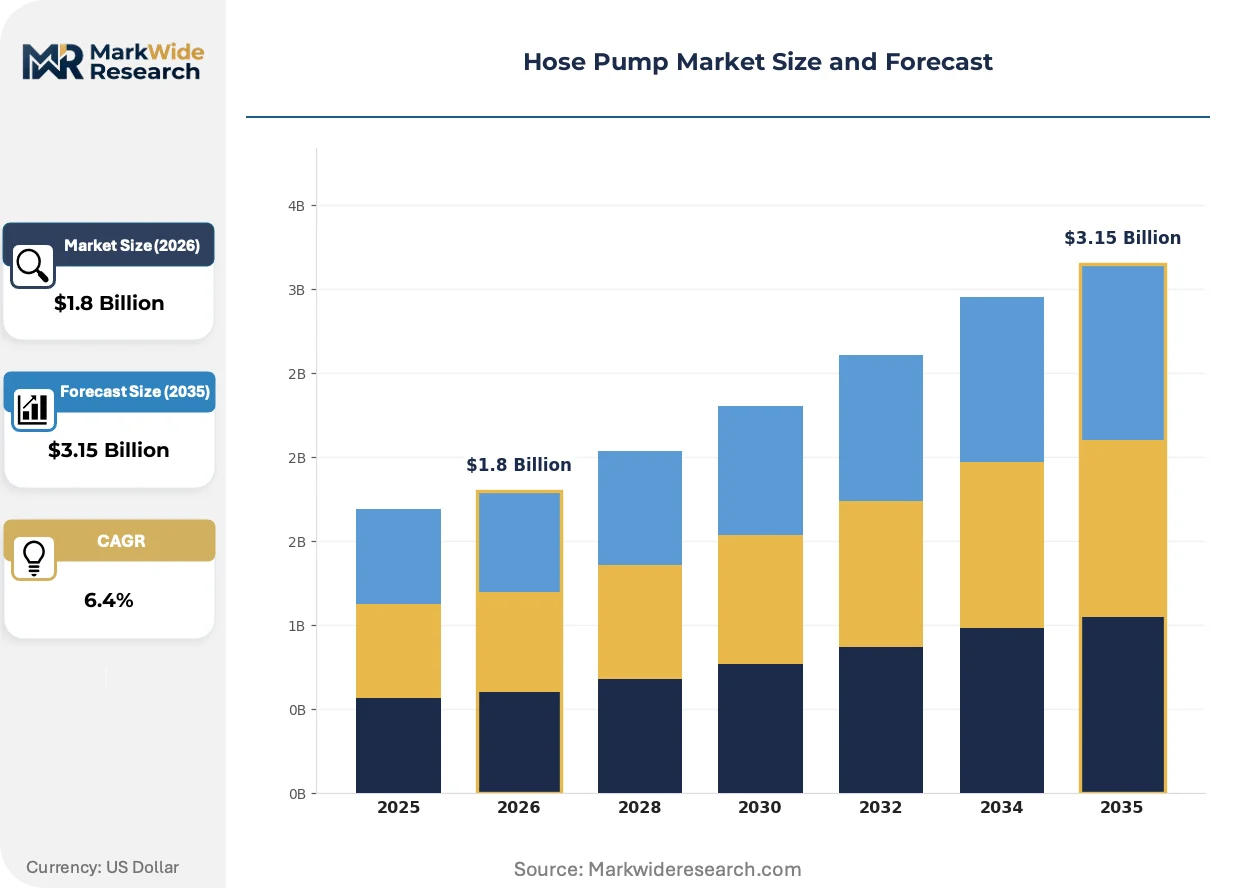
Market Dynamics
REACH phthalate restrictions and EPA zero-leak mandates are compressing elastomer supply chains while forcing simultaneous material reformulation across pharmaceutical and municipal treatment procurement channels.
Growth Catalysts
- Biopharmaceutical single-use tubing:Aseptic filling operations in Germany and Switzerland are eliminating cross-batch contamination risks through disposable peristaltic configurations.
- REACH compliance deadlines:European chemical processors face mandatory phthalate-free hose construction, accelerating specification-intensive procurement cycles.
- Mining dewatering intensity:Australian and Chilean extraction operations deploy industrial hose pumps for abrasive slurry handling in pit dewatering applications.
Market Restraints
- Specialty elastomer concentration:Fluoroelastomer and EPDM compound supply concentrates among three German and Japanese chemical suppliers, creating input cost volatility.
- PTFE substitution pressure:Per- and polyfluoroalkyl substance restrictions across EU member states and US states are forcing premature hose retirement before functional end-of-life.
- Piston pump residual share:Food processing facilities in Southern Europe retain positive-displacement alternatives where CIP cycle frequency remains below threshold replacement economics.
Strategic Opportunities
- Scandinavian water treatment service networks:Municipal utilities in Sweden and Norway seek localized maintenance capabilities for aging peristaltic installations.
- Cell and gene therapy manufacturing:US and German bioprocessing facilities require precision dosing pumps for viral vector production at clinical and commercial scale.
- Digital predictive maintenance convergence:Vibration sensing and elastomer wear algorithms enable condition-based replacement scheduling in continuous pharmaceutical operations.
Industry Challenges
- ISO 9001 audit compression:Annual certification cycles strain quality management resources at mid-cap manufacturers serving specification-intensive German industrial clusters.
- Legacy control system integration:Food processors face protocol translation complexity when retrofitting sanitary hose pumps into existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hose Pump Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peristaltic Pumps, Industrial Hose Pumps, Miniature Hose Pumps, Sanitary Hose Pumps End User: Food & Beverage, Chemical Processing, Water Treatment, Pharmaceutical Installation Type: Fixed, Portable, Mobile, Stationary Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Watson-Marlow Fluid Technology Solutions, Verder Group, Graco Inc., Ingersoll Rand, NETZSCH Pumps & Systems, Bredel Pumps, Albin Pump, ProMinent, PSG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hose Pump Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are simultaneously enabling performance tier differentiation and compressing approved substance lists across hose construction methodologies.
Reinforced thermoplastic elastomer formulations are fragmenting traditional rubber hose architectures in mid-pressure municipal applications. German water utilities are piloting TPE-lined configurations for abrasive grit handling at 8-12 bar operating ranges. This substitution is fragmenting supplier tiers between captive compounders and commodity elastomer distributors.
EPA Clean Water Act enforcement is tightening zero-leak seal requirements in municipal treatment upgrades across US Great Lakes and Chesapeake Bay watersheds. Discharge limit compliance now mandates hose pump configurations for chemical metering and sludge transfer applications. California and New York procurement frameworks are embedding these specifications into RFP technical evaluation criteria.
Specification-intensive buyers in German precision manufacturing clusters are compressing vendor qualification timelines while demanding captive elastomer compounding documentation. Pharmaceutical procurement teams now require batch-level polymer traceability that exceeds ISO 9001 baseline certification. This behavioral shift is most visible in Baden-Württemberg and Bavaria industrial corridors where OEM supply agreements specify annual audit access rights.
Hose Pump Market Segmentation
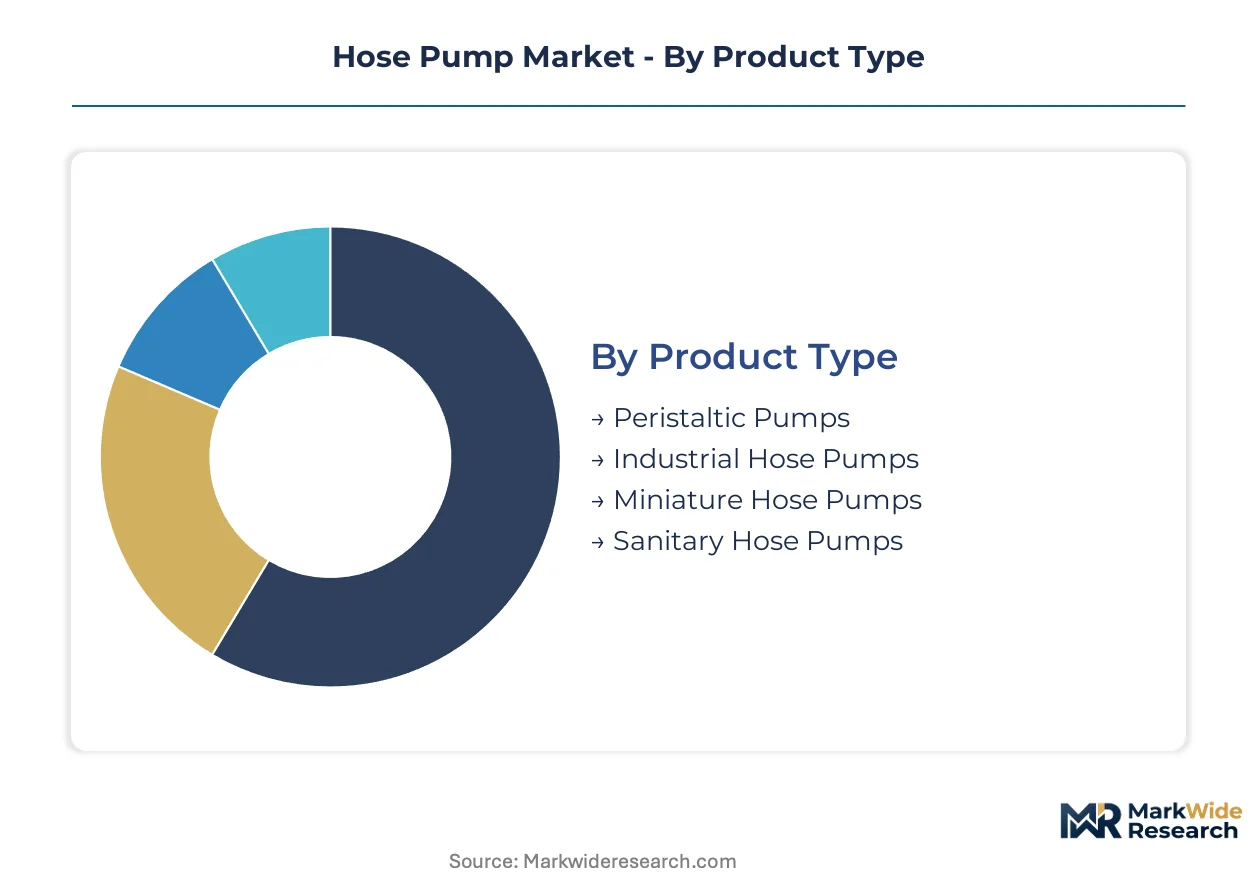
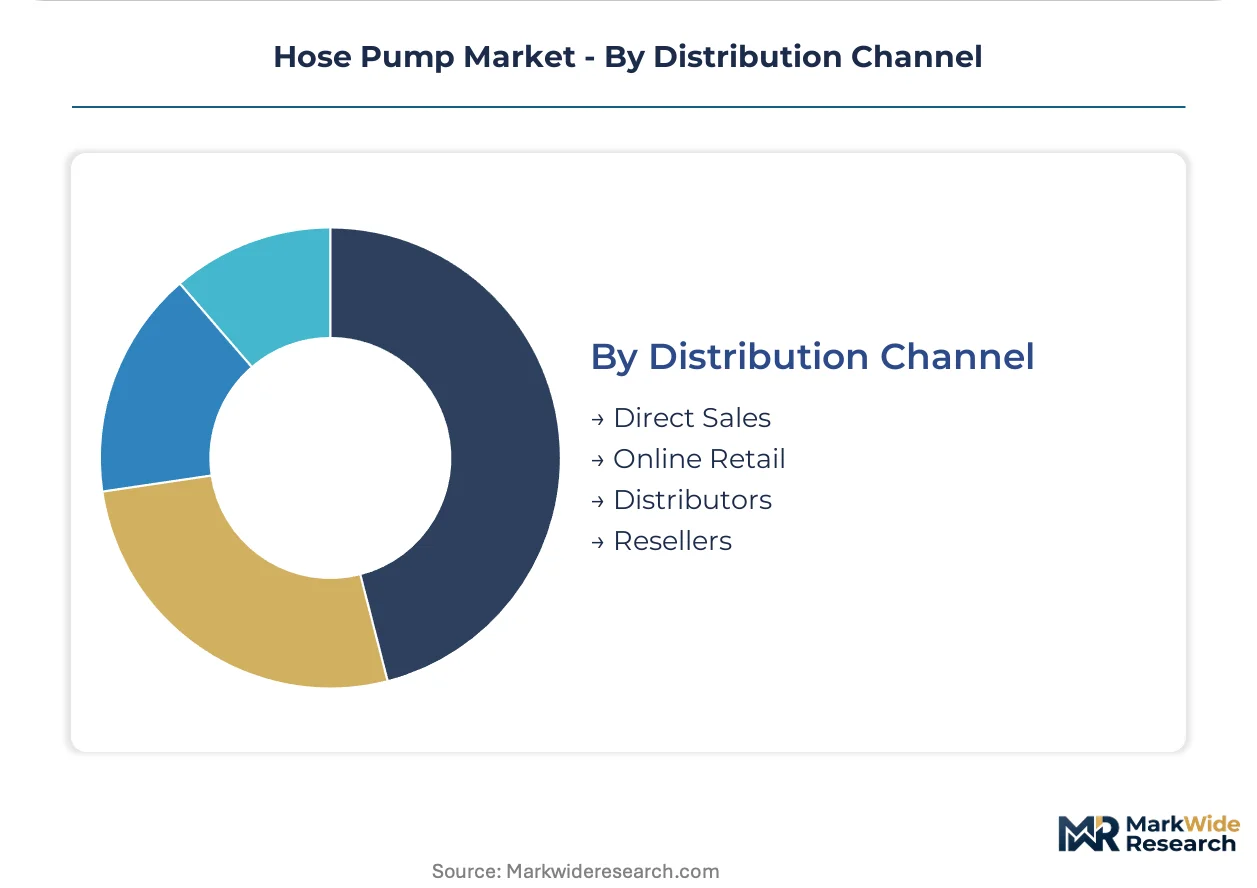
Hose pump procurement channels diverge sharply across application tiers. Pharmaceutical buyers demand specification-intensive direct engagement, while mining and construction operators route volume purchases through distributor networks.
Product Type:
Channel flow separates premium sanitary configurations from commodity industrial units. Direct sales teams capture pharmaceutical and food-grade contracts requiring batch-level documentation. Distributor networks absorb standard industrial pumps for mining and water treatment.
- Peristaltic Pumps:These pumps compress elastomer tubing with rotating rollers or shoes to achieve contamination-free fluid transfer. Demand concentrates in German and Swiss biopharmaceutical aseptic filling lines where single-use tubing eliminates cross-batch contamination risks.
- Industrial Hose Pumps:Reinforced elastomer tubes handle abrasive slurries at elevated pressures in mining dewatering operations. Australian and Chilean extraction sites deploy these units for pit dewatering where rotor hardening extends replacement intervals.
- Miniature Hose Pumps:Compact roller assemblies serve laboratory and analytical instrumentation with precision dosing requirements.
- Sanitary Hose Pumps:FDA 21 CFR 177.2600-compliant construction dominates US dairy processing retrofits, cutting clean-in-place cycle downtime versus legacy piston alternatives.
By volume, Industrial Hose Pumps lead. By growth pace, Sanitary Hose Pumps are climbing the fastest.
End User:
Cost tier stratification shapes procurement behavior across these verticals. Pharmaceutical and food-grade specifications command premium pricing with captive elastomer requirements. Chemical and water treatment applications tolerate standardized compounds at thinner margins.
- Food & Beverage:Sanitary configurations replace piston pumps in US dairy processing to reduce clean-in-place cycle downtime. FDA compliance mandates shape material selection.
- Chemical Processing:REACH phthalate restrictions in Germany and EPA discharge standards in the United States force simultaneous hose reformulation across abrasive slurry handling applications.
- Water Treatment:EPA Clean Water Act enforcement mandates zero-leak configurations in Great Lakes and Chesapeake Bay watershed municipal upgrades.
- Pharmaceutical:German and Swiss aseptic filling operations specify disposable peristaltic tubing with batch-level polymer traceability exceeding ISO 9001 baselines.
Pharmaceutical procurement commands the highest specification density. Water treatment presents the steepest volume expansion trajectory.
Installation Type:
Application mobility requirements determine channel routing. Fixed installations flow through direct sales with engineering support. Portable and mobile units move through distributor and reseller channels with faster turnaround.
- Fixed:Permanent mounting in pharmaceutical cleanrooms and municipal treatment plants demands integration engineering and validation documentation.
- Portable:Skid-mounted configurations serve construction dewatering and temporary chemical processing with rapid deployment requirements.
- Mobile:Trailer-mounted pumps address emergency response and remote mining operations requiring field mobility.
- Stationary:Anchored industrial units in German precision manufacturing clusters specify annual ISO 9001 audit access rights in procurement frameworks.
Fixed installations dominate revenue concentration. Mobile configurations are expanding most quickly in emergency response procurement.
Distribution Channel:
Customer scale and specification intensity fragment channel access. Large pharmaceutical and chemical processors engage manufacturers directly. Mid-scale operators leverage distributor inventory and service networks.
- Direct Sales:Captive elastomer compounding documentation and batch-level traceability requirements drive pharmaceutical and precision manufacturing procurement into manufacturer-direct relationships.
- Online Retail:Standardized spare parts and replacement tubing for established installations migrate to digital channels with specification clarity.
- Distributors:Scandinavian water treatment markets rely on localized inventory and maintenance capabilities for aging peristaltic installations.
- Resellers:Secondary channels absorb surplus and refurbished units in cost-sensitive construction and mining applications.
Direct Sales capture the highest-margin contracts. Distributors maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's central role in precision pump distribution across Central Europe.
Germany
Baden-Württemberg's precision manufacturing clusters drive specification-intensive procurement for peristaltic pumps in pharmaceutical aseptic filling. ECHA REACH phthalate restrictions force simultaneous hose reformulation across chemical processing plants. Bavarian industrial corridors embed annual ISO 9001 audit access rights into OEM supply agreements.
United States
EPA Clean Water Act enforcement mandates zero-leak pump seals in municipal treatment upgrades across Great Lakes and Chesapeake Bay watersheds. FDA 21 CFR 177.2600 compliance shapes material selection for dairy processing retrofits in Wisconsin and California. Greater Boston's biopharmaceutical concentration specifies disposable tubing with batch-level polymer traceability.
Switzerland
Swissmedic regulatory frameworks elevate documentation requirements for pharmaceutical pump installations in Basel and Zurich bioprocessing facilities. Precision dosing specifications for cell and gene therapy manufacturing concentrate demand in the Lake Geneva biotech cluster. Swiss industrial buyers compress vendor qualification timelines while demanding captive elastomer compounding documentation.
Australia
Pit dewatering operations in Western Australia's Pilbara region deploy industrial hose pumps for abrasive slurry handling in iron ore extraction. The country's national environmental regulator enforces discharge standards that accelerate pump replacement cycles in remote mining installations. Queensland's coal seam gas developments specify mobile trailer-mounted configurations for emergency response deployment.
Sweden
Municipal utilities in Stockholm and Gothenburg seek localized maintenance capabilities for aging peristaltic installations in water treatment networks. The Swedish Environmental Protection Agency tightens effluent quality standards that mandate precision chemical metering equipment. Scandinavian service network gaps create procurement opportunities for dedicated technical support contracts.
Hose Pump Market Competitive Environment
Listed leaders compete with private specialists across certification intensity and captive material control. The vendor base stratifies into three tiers: integrated compounders with in-house elastomer production, specification-driven system houses, and volume-oriented fabricators. Strategic moves concentrate on backward integration into polymer formulation and geographic densification of service networks.
Within the integrated compounder tier, Watson-Marlow Fluid Technology Solutions and NETZSCH Pumps & Systems exemplify archetypes that anchor premium positioning through material science control. Verder Group occupies a position among specification-driven specialists with dedicated service infrastructure. These three represent competitive positioning vectors: captive formulation consistency, hardened rotor engineering, and localized maintenance capability.
| Leading Market Players |
|---|
| Watson-Marlow Fluid Technology Solutions |
| Verder Group |
| Graco Inc. |
| Ingersoll Rand |
| NETZSCH Pumps & Systems |
| Bredel Pumps |
| Albin Pump |
| ProMinent |
| PSG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German chemical processors and captive elastomer compounders lock in both supply access and price visibility across specification-intensive procurement cycles. These arrangements insulate pharmaceutical buyers from fluoroelastomer spot-market volatility while embedding annual audit rights into contract frameworks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sanitary configurations with FDA 21 CFR 177.2600 compliance from commodity industrial units and refurbished secondary-market pumps. Price differentiation rests on certification grade and captive compounding documentation, with ISO 9001 annual audit access commanding substantial premiums. Cost compression in commodity elastomer tiers is intensifying because mining and construction buyers consolidate volume through distributor networks. Pharmaceutical procurement teams exhibit the least price sensitivity, while construction dewatering operators in Australia and Chile drive the hardest bargain on replacement intervals.
Supply Chain Analysis
Inventory lead times for specialty fluoroelastomer and EPDM compounds have extended substantially as three German and Japanese chemical suppliers concentrate global production. Raw material sourcing draws from petroleum-based feedstocks, reinforced textile braiding, and precision-machined rotor assemblies. Single-source vulnerability in high-performance elastomer formulation creates exposure to REACH phthalate restriction compliance costs. Distribution runs through manufacturer-direct channels for pharmaceutical contracts and regional distributor networks for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized captive compounding capabilities and hardened rotor engineering represent scarce assets that incumbent vendors have accumulated over decades, creating defensive moats that new entrants cannot replicate through capital expenditure alone.
For Market Incumbents: Secure backward integration into polymer formulation to defend margin position against REACH-driven material substitution costs. Expand dedicated service networks in Scandinavian water treatment markets where localized maintenance capabilities command premium pricing and long-term contract lock-in. For New Entrants and Emerging Players: Differentiate on digital predictive maintenance convergence, targeting mid-cap pharmaceutical manufacturers seeking condition-based replacement scheduling without incumbent service premiums. Penetrate the cell and gene therapy manufacturing segment in US and German bioprocessing facilities where precision dosing specifications outpace established vendor qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specification-driven system houses with captive elastomer compounding and annual audit access rights embedded in OEM supply agreements. Over a multi-year horizon, vertically integrated compounders with in-house polymer production offer superior cash flow stability versus volume-oriented fabricators exposed to commodity elastomer price cycles. Watch for PTFE substitution acceleration across EU member states as an inflection signal requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Watson-Marlow's captive formulation consistency anchors pharmaceutical contract retention against REACH compliance pressures. |
| Geographic Densification of Service Networks | Verder Group's Scandinavian infrastructure captures municipal utility maintenance contracts with localized response capabilities. |
| Hardened Rotor Engineering Investment | NETZSCH's slurry-transfer specifications extend replacement intervals in Australian mining dewatering operations. |
| Digital Predictive Maintenance Platform | Vibration sensing algorithms enable condition-based scheduling in continuous pharmaceutical operations. |
| Single-Use Tubing Disposable Configuration | Peristaltic aseptic filling lines in Basel bioprocessing facilities eliminate cross-batch contamination risks. |
Study Parameters
Cross-validation between maintenance director interviews at German precision manufacturing clusters and distributor inventory data anchors the qualitative findings on procurement behavior shifts. Primary fieldwork engaged plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at compound suppliers. Secondary sources include ECHA REACH substance databases, EPA Clean Water Act enforcement records, FDA 21 CFR guidance documents, and customs trade flows for elastomer imports. Bottom-up unit economics triangulate against top-down market sizing across product configuration tiers.
Sensitivity analysis on fluoroelastomer price volatility and PTFE substitution timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include pump configuration type, end-use industry vertical, installation mobility requirement, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and specification-intensive procurement expansion in biopharmaceutical aseptic filling. Industry-specific inputs incorporate REACH phthalate restriction compliance deadlines and EPA zero-leak mandate enforcement intensity.
Forecasts assume regulatory continuity in ECHA REACH and EPA discharge standard regimes; material policy shifts would require re-modeling of material substitution timelines and compliance cost pass-through. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Industrial Pulley Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Industrial Carts Market