
 Cable Duct Market | 2026-2036
Cable Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Duct Market Outlook
India's manufacturing capacity build-out for electrical infrastructure components is reshaping competitive dynamics across Asia-Pacific supply chains. Atkore leverages vertical integration in steel and PVC resin processing to sustain margin control across metallic and polymer duct lines. Schneider Electric anchors its position through R&D intensity in fire-rated and halogen-free compound formulations. Legrand competes on channel density, with distribution networks spanning both developed and emerging construction markets.
Cable duct denotes a structured raceway system—typically fabricated from galvanized steel, rigid polyvinyl chloride, fiber-reinforced polymer, or aluminum alloys—engineered to protect, route, and organize electrical conductors and fiber optic cables across commercial, industrial, and utility installations. Wall thickness, corrosion resistance ratings, and flame spread indices determine suitability for underground, aerial, or surface-mounted deployments. PVC ducts occupy the largest volume share due to cost efficiency in residential and light commercial construction, while composite ducts represent the fastest-expanding category as offshore wind and rail electrification projects demand lightweight, non-conductive alternatives with superior chemical resistance. Telecommunications end-use is outpacing construction growth in absolute terms, driven by 5G backhaul and data center fiber densification requirements.
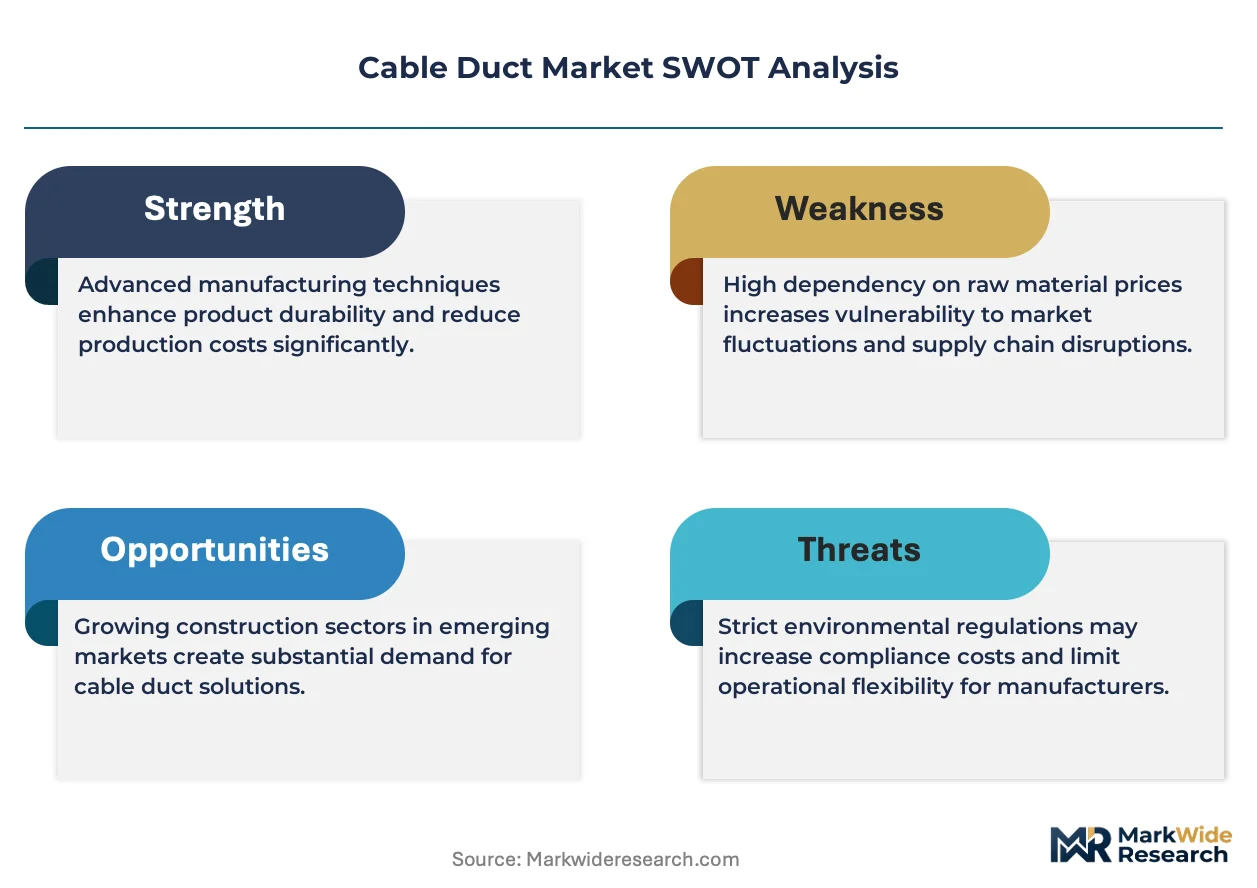
The US National Electrical Code and OSHA installation standards govern raceway fire safety and worker protection protocols, directly influencing product certification requirements for North American market access. India's BIS certification mandates and the EU's CPR (Construction Products Regulation) flame-classification framework create divergent compliance pathways that manufacturers must navigate. Stakeholders should monitor evolving low-smoke zero-halogen mandates and circular-economy material quotas, as these specifications will determine which compound technologies and regional production bases capture premium positioning.
Market Dynamics
The EU F-Gas Regulation and parallel building decarbonization codes are forcing material specification upgrades across electrical raceway systems, compressing demand for legacy PVC formulations while elevating certified halogen-free and low-smoke zero-halogen compounds.
Growth Catalysts
- Telecommunications densification:5G backhaul deployments and hyperscale data center fiber expansion are accelerating procurement of fiber-grade conduit systems rated for high-density cable management.
- REACH compliance evolution:ECHA restrictions on phthalate plasticizers and heavy metal stabilizers are redirecting compound innovation toward bio-based and recycled-content formulations.
- India smart city build-out:Urban corridor projects in Mumbai, Delhi, and Bangalore are mandating integrated cable management infrastructure for intelligent traffic and utility networks.
Market Restraints
- Resin cost volatility:PVC and polypropylene feedstock prices track ethylene and propylene naphtha spreads, compressing margins for non-integrated compounders.
- Galvanized steel supply concentration:Chinese and Indian flat-rolled steel producers control 60%+ of global zinc-coated sheet capacity, creating input price risk for metallic duct manufacturers.
- Halogen-free technical ceiling:Current LSZH compounds exhibit inferior impact resistance versus PVC at sub-zero temperatures, limiting Arctic and high-altitude deployments.
Strategic Opportunities
- Offshore wind electrification:Floating and fixed-bottom turbine arrays require lightweight fiber-reinforced polymer conduits with 25-year salt spray resistance ratings.
- EU Green Deal material quotas:The Circular Economy Action Plan's recycled-content mandates for construction products create certified supply scarcity that first-mover compounders can capture.
- E-commerce channel penetration:Electrical contractor procurement through Amazon Business and specialized B2B platforms is disintermediating traditional distributor markups in mid-market segments.
Industry Challenges
- CPR certification timeline compression:The EU Construction Products Regulation's extended flame-classification testing protocols add 12-18 months to new product launches, straining R&D cadence.
- Multi-standard compliance engineering:Simultaneous BIS, UL, and CE mark requirements force redundant testing regimens that inflate qualification costs for export-oriented manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Duct Market |
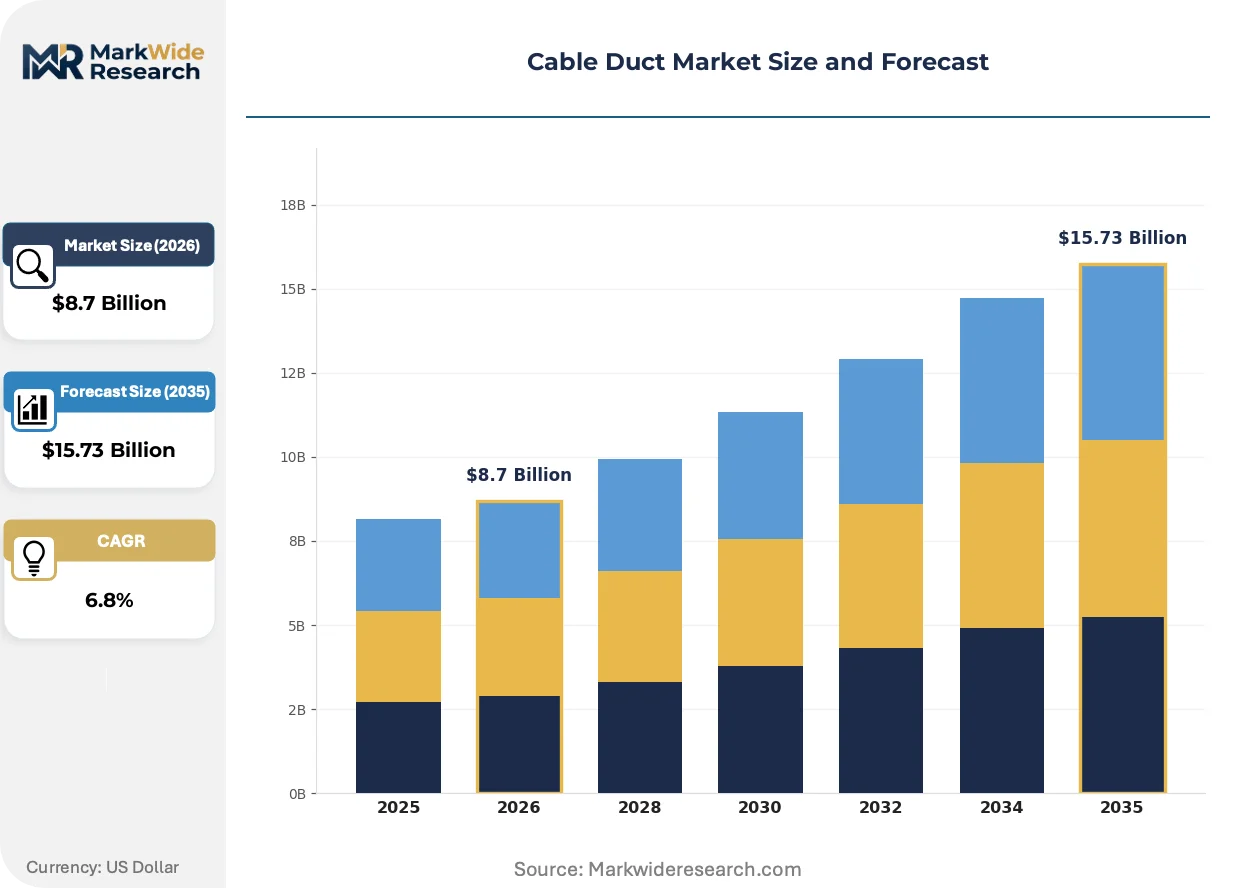
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Ducts, PVC Ducts, Fiber Ducts, Composite Ducts End User: Telecommunications, Construction, Industrial, Utilities Connection Type: Single-Phase, Three-Phase, High Voltage, Low Voltage Installation Method: Underground, Aerial, Surface-Mounted, Concealed |
| Companies Covered | Atkore, Legrand, Schneider Electric, ABB, Aliaxis Group, Eaton, Panduit, HellermannTyton, Barton Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Duct Market Strategic Shifts
Material science advances and procurement digitization are restructuring how cable management systems are specified, sourced, and deployed across construction and utility verticals.
Halogen-free thermoplastic elastomer compounds are migrating from niche rail and tunnel applications into mainstream commercial construction as architects and MEP engineers prioritize smoke toxicity ratings over first-cost economics. Data center operators in Frankfurt, Amsterdam, and Singapore are specifying these materials for mission-critical power distribution. The shift is compressing PVC's historical dominance in premium-specification projects.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is forcing insulation-duct manufacturers to reformulate foamed PVC and polyethylene products with CO2 or hydrocarbon alternatives. Compounders serving the German and French markets are retooling extrusion lines to handle lower-density, higher-temperature processing windows. This regulatory pressure is most acute in fire-rated wall and ceiling penetration assemblies where thermal performance certification is mandatory.
Electrical contractors are consolidating purchase volumes through group purchasing organizations and direct-manufacturer agreements, bypassing traditional two-step distribution. This channel compression is most visible in the US commercial construction sector where Procore-integrated procurement platforms enable real-time material specification and price benchmarking. Distributors are responding with value-added fabrication services and same-day fulfillment guarantees to defend position.
Cable Duct Market Segmentation
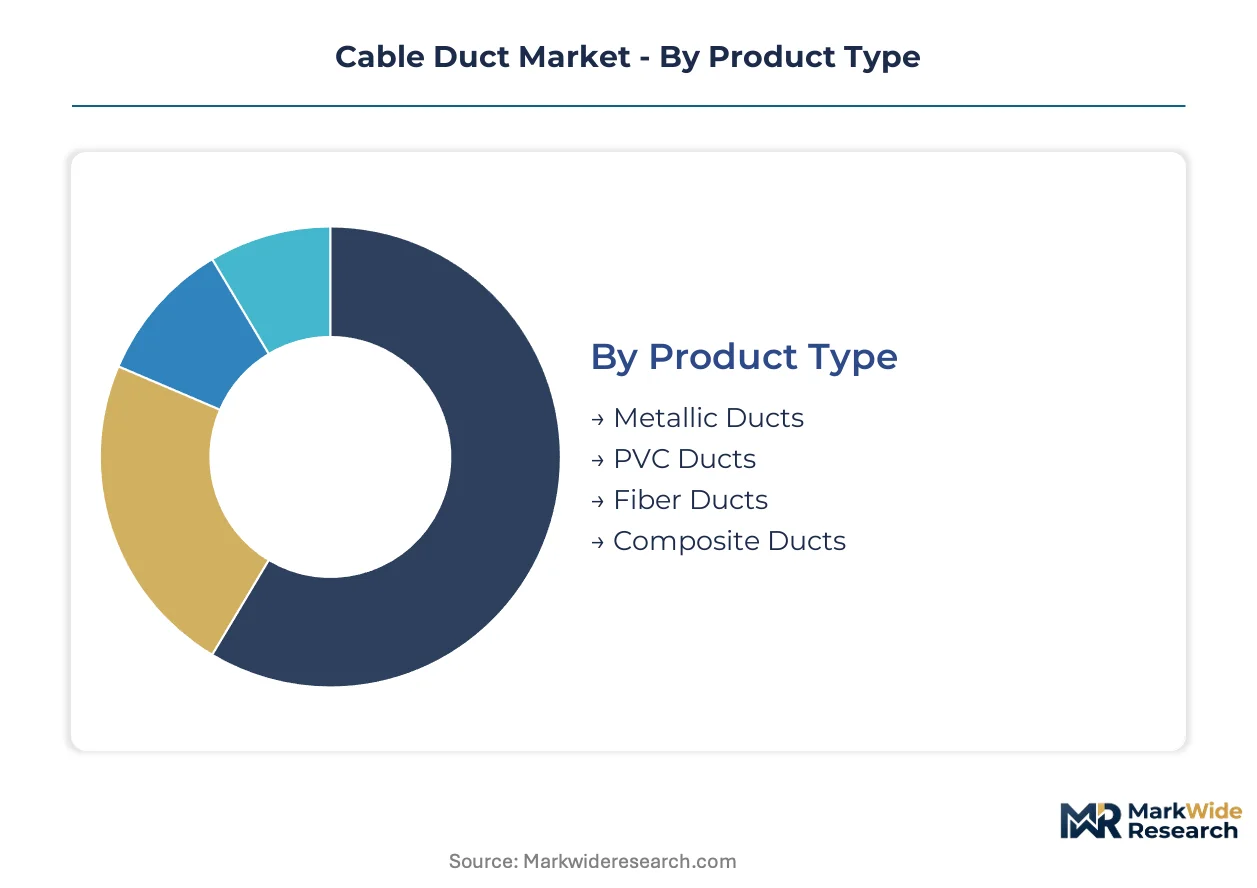
Material composition, voltage classification, and deployment topology each create distinct procurement workflows and margin structures across cable duct categories. Specification engineers weight flame ratings, mechanical load capacity, and environmental exposure differently depending on whether the installation serves data center fiber backbones or industrial power distribution.
Product Type:
Mature metallic formulations coexist with emerging polymer alternatives across specification tiers, with compound chemistry now the primary axis of competitive differentiation.
- PVC Ducts:Rigid polyvinyl chloride extrusions dominate residential and light commercial construction through cost-efficient fabrication and established installation protocols. Demand concentrates in India's urban corridor projects where BIS certification requirements favor domestically compounded formulations with established supply chains.
- Composite Ducts:Fiber-reinforced polymer systems deliver lightweight, non-conductive raceway solutions with superior chemical resistance for harsh environments. Offshore wind arrays in the North Sea and rail electrification corridors in Germany are accelerating procurement of these materials as ECHA restrictions on legacy plasticizers compress PVC's addressable market in premium specifications.
- Metallic Ducts:Galvanized steel and aluminum alloy raceways provide structural rigidity for high-load industrial and utility applications.
- Fiber Ducts:Specialized conduit systems engineered for fiber optic cable protection in telecommunications infrastructure.
PVC ducts handle the majority of throughput; composite ducts are expanding most quickly on share as decarbonization codes tighten material specifications.
End User:
Application-driven specification splits procurement between bandwidth-intensive telecommunications deployments and construction-phase electrical infrastructure.
- Telecommunications:5G backhaul densification and hyperscale data center fiber expansion are driving specification of high-density cable management systems with bend-radius control and rodent-resistant jacketing. Frankfurt, Amsterdam, and Singapore data center clusters are mandating halogen-free compounds for mission-critical power distribution.
- Construction:Commercial and residential building codes govern raceway selection through flame spread indices and smoke toxicity ratings. Mumbai, Delhi, and Bangalore smart city mandates are integrating intelligent traffic and utility network cable management into urban corridor procurement packages.
- Industrial:Manufacturing facilities and process plants require chemical-resistant raceway systems for power and control cable protection.
- Utilities:Grid infrastructure and renewable generation interconnection projects specify heavy-duty duct systems for transmission and distribution networks.
Construction maintains volume leadership across product categories; telecommunications is climbing the fastest as fiber densification outpaces traditional building electrification.
Connection Type:
Voltage tier determines wall thickness, insulation coordination, and regulatory certification pathways across procurement specifications.
- Low Voltage:Power distribution below 1kV represents the foundational specification tier for commercial and residential building electrification.
- High Voltage:Transmission-grade raceway systems require enhanced dielectric spacing and partial discharge resistance for utility-scale deployments.
- Single-Phase:Residential and light commercial branch circuit protection through compact raceway profiles.
- Three-Phase:Industrial motor supply and commercial panel feeders demand balanced conductor accommodation and harmonic current management.
Low voltage commands the widest installation base; high voltage is gaining share fastest as grid modernization and renewable interconnection accelerate.
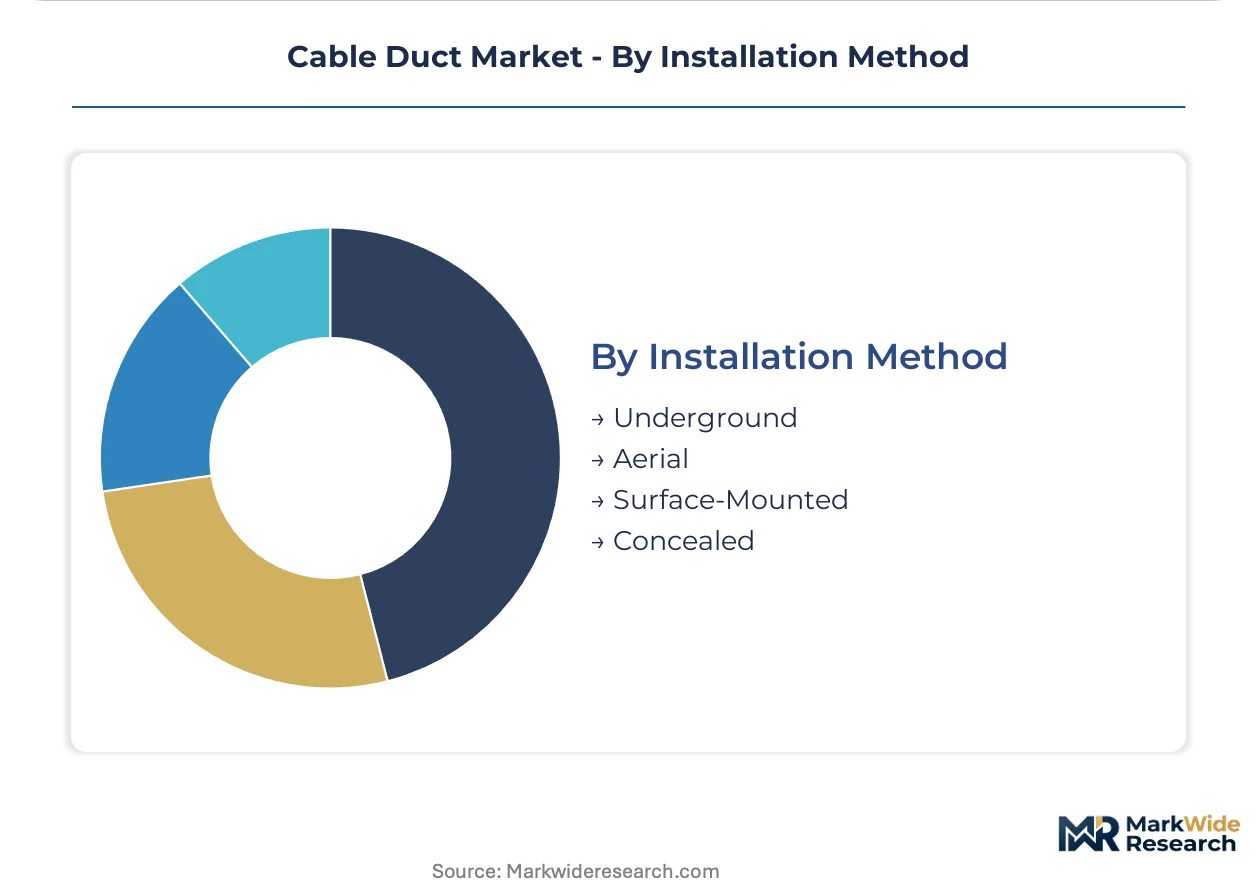
Installation Method:
Deployment topology dictates material selection through mechanical load, environmental exposure, and accessibility constraints.
- Underground:Direct-buried and concrete-encased duct banks require crush-resistant construction and groundwater ingress protection for utility and telecommunications backbone routes.
- Surface-Mounted:Exposed raceway systems in industrial and commercial interiors prioritize impact resistance and rapid installation through snap-fit or screw-fix mounting.
- Aerial:Messenger-supported and self-supporting duct configurations for overhead utility and temporary construction power distribution.
- Concealed:In-wall and in-ceiling raceway systems for aesthetic-sensitive commercial and residential finishes.
Underground methods absorb the largest capital deployment; surface-mounted configurations are expanding fastest as retrofit activity and modular construction techniques proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese and Indian flat-rolled steel producers control the majority of global zinc-coated sheet capacity, concentrating metallic duct supply chains in Asia-Pacific. This concentration creates input price risk for manufacturers dependent on galvanized steel feedstock.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth is accelerating procurement of halogen-free cable management systems. The National Electrical Code and OSHA installation standards govern raceway fire safety certification requirements. Hyperscale operators in Ashburn and Phoenix are mandating low-smoke zero-halogen compounds for mission-critical power distribution infrastructure.
Germany
Offshore wind arrays in the North Sea are driving specification of fiber-reinforced polymer conduits with extended salt spray resistance. The EU F-Gas Regulation and Construction Products Regulation flame-classification framework create stringent compliance pathways. Rail electrification corridors through Bavaria and North Rhine-Westphalia are displacing legacy PVC formulations with certified halogen-free alternatives.
India
Urban corridor projects in Mumbai, Delhi, and Bangalore are mandating integrated cable management for intelligent traffic and utility networks. BIS certification requirements favor domestically compounded PVC formulations with established supply chains. Smart city investments in Maharashtra and Karnataka are concentrating demand for high-density raceway systems in premium commercial construction.
China
5G backhaul densification and hyperscale data center expansion in Shenzhen and Shanghai are propelling fiber-grade conduit procurement. GB standards and MIIT regulations govern telecommunications infrastructure material specifications. The Yangtze River Delta manufacturing cluster is scaling composite duct production for export-oriented renewable energy projects.
Singapore
Tropical data center clusters are specifying advanced cable management systems with superior humidity and corrosion resistance. The country's national building regulator enforces strict fire safety codes for commercial and industrial installations. Mission-critical facilities in Jurong and Changi are adopting halogen-free compounds as standard specification for power distribution raceways.
Cable Duct Market Competitive Environment
Vertically integrated conglomerates and specialized component fabricators split the market across material-grade tiers. The vendor base organizes around three strategic archetypes: steel-and-resin integrators controlling upstream feedstock costs, electrical infrastructure multinationals leveraging R&D scale for certified compound formulations, and regional specialists capturing proximity advantages in high-growth construction corridors. Dominant competitive moves include backward integration into resin compounding and capacity expansion in India and Southeast Asia to serve smart city procurement pipelines.
Within the integrated-manufacturing tier, Atkore exemplifies upstream control over metallic and polymer feedstocks. Schneider Electric and Legrand occupy positions as electrical infrastructure multinationals with channel density spanning developed and emerging construction markets. These three anchors represent contrasting strategic postures: captive supply security, R&D-intensive certification leadership, and distribution network breadth respectively.
| Leading Market Players |
|---|
| Atkore |
| Legrand |
| Schneider Electric |
| ABB |
| Aliaxis Group |
| Eaton |
| Panduit |
| HellermannTyton |
| Barton Engineers |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam container corridor anchors cost dynamics for cable duct imports into Western Europe, with freight rate volatility amplifying price spreads between Asian-manufactured PVC formulations and domestically compounded halogen-free alternatives. This logistics tension concentrates pricing power among resin-integrated compounders while forcing distributors to absorb margin compression on standard-grade metallic raceways.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across cable duct procurement, separating certified low-smoke zero-halogen compounds from legacy PVC formulations through flame-classification premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with BIS-certified Indian PVC commanding mid-tier positioning against European halogen-free premiums. Pricing pressure stems from ethylene-naphtha spread volatility compressing compounder margins on non-integrated production. Electrical contractors through group purchasing organizations exhibit highest price sensitivity, while data center operators prioritize smoke toxicity ratings over first-cost economics.
Supply Chain Analysis
Export-control restrictions on advanced polymer compounding equipment limit technology transfer to emerging production bases, concentrating high-performance halogen-free formulation capacity in Germany, France, and Japan. Raw material flows draw from Chinese and Indian flat-rolled steel for metallic ducts, Saudi and Qatari petrochemical feedstocks for PVC resin, and Belgian specialty additives for flame-retardant compounds. Single-source vulnerability runs through zinc-coated sheet supply where Chinese producers control majority capacity. Distribution runs through electrical wholesale distributors defending position with fabrication services, though Amazon Business and Procore-integrated platforms are disintermediating mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cable duct demand sits in early-cycle expansion as smart city infrastructure mandates and 5G backhaul densification accelerate specification of high-density raceway systems ahead of traditional construction recovery.
For Market Incumbents: Insulate margin structures through backward integration into PVC resin compounding and halogen-free compound formulation, capturing feedstock cost advantages as ethylene price volatility intensifies. Prioritize certification investment for EU CPR flame-classification leadership to defend premium positioning against emerging Asian compounders. Channel control through value-added fabrication services and same-day fulfillment guarantees offsets distributor disintermediation pressure from e-commerce procurement platforms. For New Entrants and Emerging Players: Establish a beachhead in India's urban corridor projects where BIS certification requirements and smart city procurement pipelines favor domestically manufactured PVC formulations with established supply chains. Target composite duct specifications for offshore wind arrays in the North Sea, where fiber-reinforced polymer demand outpaces incumbent capacity and ECHA restrictions on legacy plasticizers compress PVC's addressable market. A go-to-market angle anchored in circular-economy material quotas captures first-mover scarcity for recycled-content certified supply. For Investors and Strategic Acquirers: The EU Green Deal's recycled-content mandates for construction products reshape the acquisition landscape, elevating compounders with certified circular-economy supply chains above commodity PVC extruders. Long-term viability centers on material science capabilities for next-generation halogen-free formulations and geographic positioning in India and Southeast Asia smart city corridors. The signal to watch is CPR certification timeline compression, as extended flame-classification testing protocols strain R&D cadence and create acquisition opportunities for distressed compounders facing qualification backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin control as ethylene-naphtha spreads compress non-integrated compounder economics. |
| Halogen-Free Compound R&D Expansion | Addresses ECHA plasticizer restrictions and EU F-Gas Regulation mandates displacing legacy PVC specifications. |
| India Manufacturing Capacity Buildout | Positions supply chains for Maharashtra and Karnataka smart city procurement pipelines requiring BIS-certified raceway systems. |
| Recycled-Content Certification Investment | Captures scarcity premium under EU Circular Economy Action Plan quotas for construction product material sourcing. |
| E-Commerce Channel Partnership | Defends distributor position against Amazon Business and Procore-integrated procurement platform disintermediation in commercial construction. |
Study Parameters
A standing panel of electrical infrastructure procurement managers, MEP specification engineers, compounder R&D directors, and distribution channel partners provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of listed electrical infrastructure multinationals, BIS certification registries, EU CPR flame-classification databases, and customs trade data for PVC resin and galvanized steel feedstocks. Bottom-up volume modeling across material grades and installation methods triangulated against top-down construction spending and telecommunications capex forecasts.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning material composition, voltage classification, end-use application, and regional regulatory cluster. CAGRs derived from unit economics modeling of compound formulations, installation labor content, and certification cost amortization. Industry-specific forecast inputs included 5G backhaul deployment trajectories and offshore wind turbine array electrification schedules.
Sensitivities concentrate around resin cost volatility, CPR certification timeline delays, and smart city procurement acceleration in India. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Pipe Clamp Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Industrial Fasteners Market