
 Brazil Forklift Market | 2026-2036
Brazil Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Forklift Market Insights
Electrification of motive power is reconfiguring Brazil's forklift procurement priorities as lithium-ion battery systems displace lead-acid architectures in multi-shift operations. Toyota Industries Corporation anchors the premium electric segment through its established Brazilian assembly presence. Hyster Yale leverages its dual-brand distribution network to compete across both IC and electric product lines. Jungheinrich AG specializes in narrow-aisle reach truck configurations for high-density warehousing applications in Greater São Paulo.
A forklift is a powered industrial truck equipped with mast-mounted forks designed to lift, transport, and stack palletized loads typically ranging from one to over ten metric tons, utilizing either electric battery drives or internal combustion engines running on diesel, LPG, or compressed natural gas. Electric forklifts dominate new orders from food and beverage manufacturing facilities seeking zero-emission indoor compliance, while IC forklifts retain strength in outdoor lumber and construction material yards where refueling infrastructure favors liquid fuels. The 3-5 ton capacity bracket captures the bulk of manufacturing and third-party logistics demand, with above-10 ton units serving the Port of Santos container terminal expansion. Telemetry systems embedded in fleet management contracts are creating recurring revenue pools for OEM service divisions.
ANVISA oversees workplace safety equipment standards affecting operator protection systems, while CONMETRO mandates metrological certification for load-weighing forklift attachments used in commercial transactions. The Brazilian Institute of Metrology, Quality and Technology (INMETRO) enforces energy efficiency labeling for electric traction motors, directly influencing procurement specifications in government-tendered fleet replacements. Stakeholders must monitor proposed updates to NR-12 machine safety regulations that would mandate collision-avoidance sensors on all new forklift deployments in food processing environments.
Market Dynamics
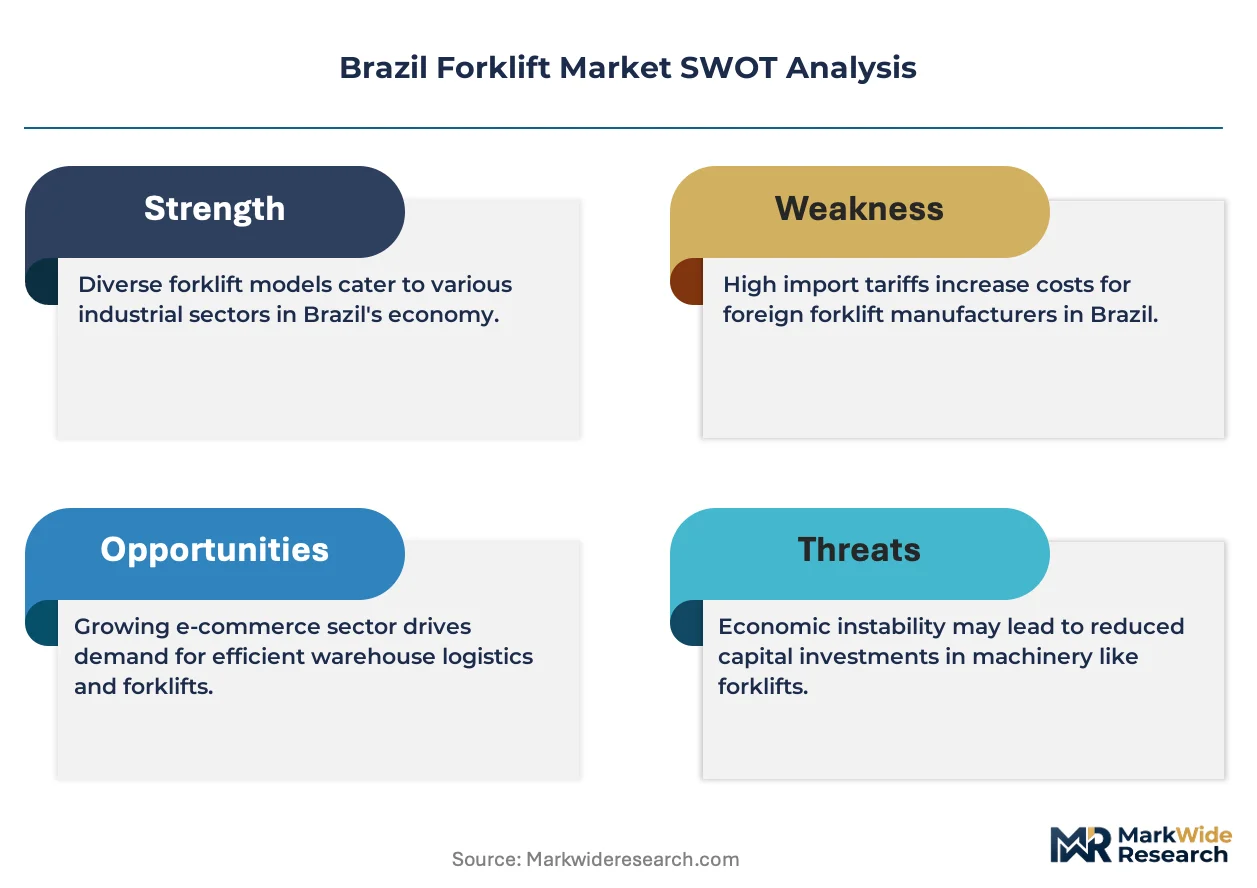
Electrification mandates from São Paulo state environmental regulators are forcing fleet operators to accelerate lithium-ion adoption ahead of CONMETRO certification deadlines, compressing the traditional eight-year equipment replacement cycle to five years.
Growth Catalysts
- E-commerce fulfillment expansion:São Paulo-Guarulhos logistics corridor operators are procuring narrow-aisle reach trucks to maximize cubic meter utilization in automated warehouses.
- Port of Santos container terminal modernization:Above-10 ton capacity forklift orders are accelerating as terminal operators expand intermodal handling capacity.
- NR-12 safety regulation updates:Proposed collision-avoidance sensor mandates for food processing environments are triggering preemptive fleet upgrades.
Market Restraints
- Lithium-ion battery import dependency:Brazil lacks domestic cell manufacturing, exposing procurement costs to currency volatility and international supply concentration.
- LPG refueling infrastructure lock-in:Outdoor lumber yards and construction material distributors retain sunk investment in liquid fuel distribution systems.
- CONMETRO certification timeline friction:Load-weighing attachment approvals extend delivery lead times by four to six months versus uncertified alternatives.
Strategic Opportunities
- Minas Gerais manufacturing belt penetration:Automotive and metalworking clusters outside São Paulo state remain underpenetrated by telemetry-enabled fleet management services.
- Telematics-as-a-service unbundling:OEM service divisions can capture recurring revenue through subscription-based uptime monitoring independent of equipment sales.
- INMETRO energy efficiency labeling:Government-tendered fleet replacements prioritize A-rated electric traction motors, creating specification advantages for compliant suppliers.
Industry Challenges
- Lithium-ion technician certification gaps:High-voltage battery maintenance requires specialized training that vocational institutions have not scaled to match fleet electrification timelines.
- Legacy warehouse management system integration:Real-time telemetry data streams from modern forklifts face protocol incompatibility with decade-old ERP installations common in Brazilian third-party logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Forklift Market |
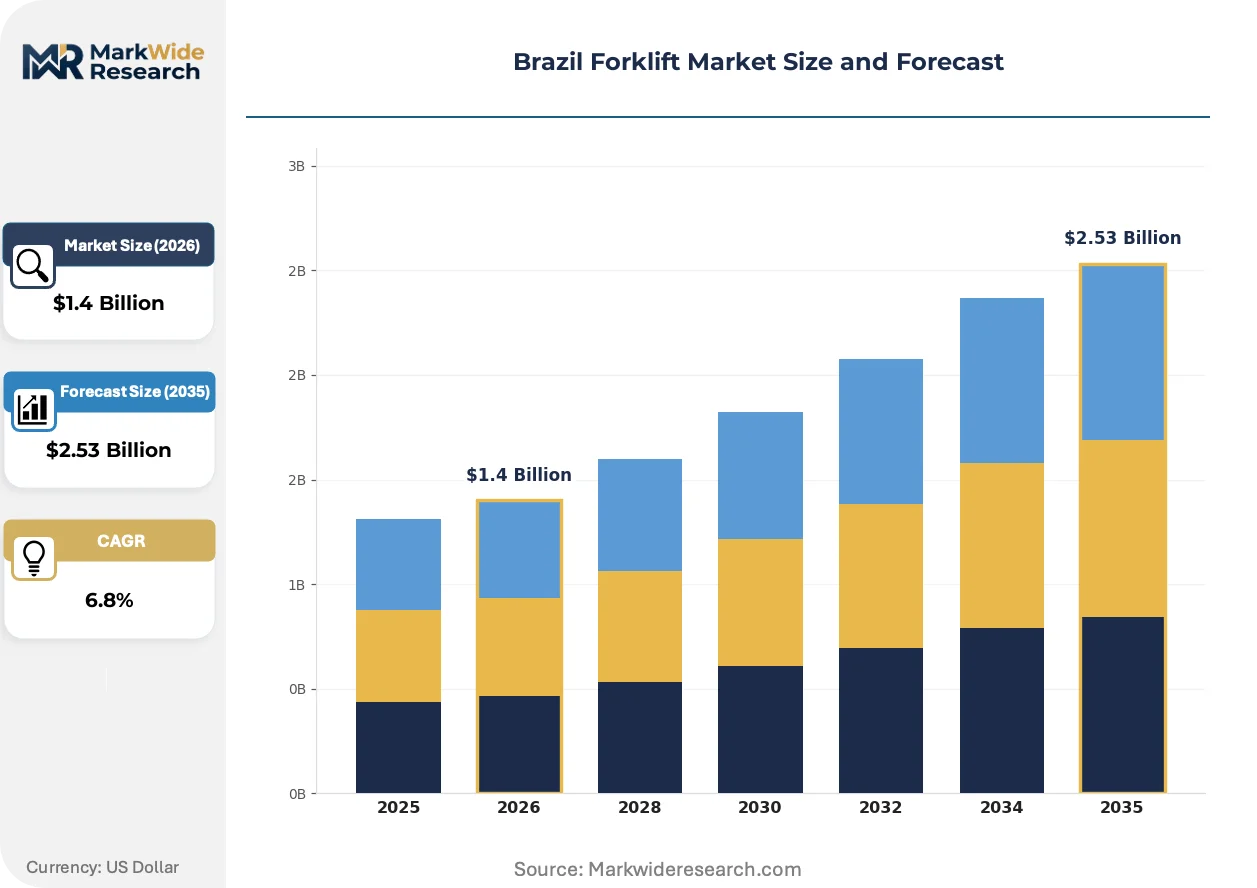
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, IC Forklifts, Reach Trucks, Pallet Jacks Capacity: 1-3 Tons, 3-5 Tons, 5-10 Tons, Above 10 Tons End User: Warehousing, Manufacturing, Retail, Transportation Technology: Automated Guided Vehicles, Telemetry Systems, Advanced Safety Features, Load Stability Systems |
| Companies Covered | Hyster Yale, Komatsu, Mitsubishi Corporation, Hangcha, Clark, Toyota Industries Corporation, KION Group AG, Jungheinrich AG, Doosan Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Forklift Market Trends and Innovations
Brazilian forklift procurement is pivoting from asset ownership toward performance-based uptime guarantees, with telemetry infrastructure enabling this contractual transformation.
Lithium-ion battery systems are collapsing the total cost of ownership advantage that lead-acid architectures held in single-shift applications. Food and beverage manufacturing facilities in Campinas and Sorocaba are adopting fast-charging lithium configurations to eliminate battery changeout labor. This chemistry transition is collapsing the market for traditional charging room infrastructure and associated floor space allocation.
ANVISA workplace safety standards are tightening operator protection system requirements for equipment deployed in pharmaceutical manufacturing environments. The regulator's updated technical specifications mandate ergonomic load-leveling controls and enhanced visibility masts. Pharmaceutical distribution centers in Osasco and Barueri are retrofitting existing fleets to meet these standards ahead of enforcement deadlines.
Third-party logistics operators are consolidating supplier relationships around single-source fleet management contracts that bundle equipment, maintenance, and telemetry analytics. This procurement concentration is displacing the traditional model of separate OEM, dealer, and independent service provider relationships. The shift is most visible among São Paulo-based contract logistics providers serving multinational consumer goods clients.
Brazil Forklift Market Segmentation
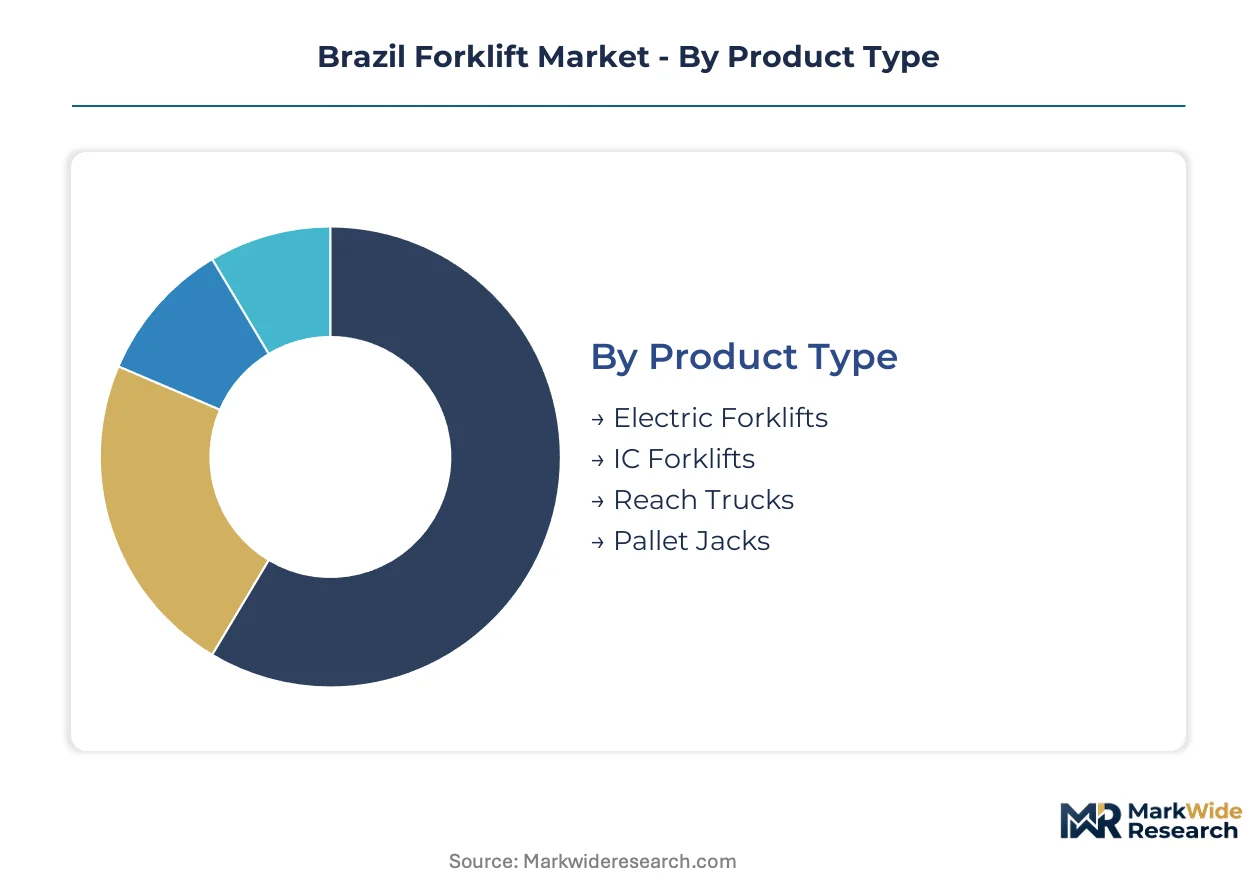
Brazil's forklift market segments reflect divergent maturity levels across powertrain technologies and automation readiness. Procurement patterns in São Paulo state's logistics corridor differ markedly from metalworking belt requirements in Minas Gerais.
Product Type:
Mature internal combustion architectures coexist with rapidly electrifying alternatives as lithium-ion systems penetrate multi-shift operations.
- Electric Forklifts:Battery-powered units utilizing lithium-ion or lead-acid traction systems, delivering zero-emission indoor operation with fast-charging capability. Food and beverage manufacturing facilities in Campinas and Sorocaba are eliminating battery changeout labor through opportunity charging configurations. CONMETRO certification timelines for new battery chemistries compress procurement cycles.
- IC Forklifts:Diesel, LPG, or compressed natural gas engines powering outdoor and heavy-duty applications with rapid refueling advantage. Lumber yards and construction material distributors in Greater São Paulo retain sunk investment in liquid fuel infrastructure despite electrification pressure. ANVISA emissions monitoring in enclosed warehousing accelerates displacement.
- Reach Trucks:Narrow-aisle configurations with extending masts designed for high-density vertical storage beyond standard counterbalance reach. Jungheinrich AG specialization dominates São Paulo-Guarulhos automated warehouse deployments.
- Pallet Jacks:Manual and powered walk-behind units for short-distance horizontal transport of standardized pallet loads. Third-party logistics operators deploy electric walkie units for dock-to-rack staging in Port of Santos container terminals.
IC Forklifts retain volume leadership; Electric Forklifts hold the steepest expansion curve.
Capacity:
Application-driven weight thresholds segment procurement across manufacturing floor density and port intermodal handling requirements.
- 3-5 Tons:Mid-range counterbalance units serving the bulk of manufacturing and third-party logistics demand with versatility across palletized loads. Automotive suppliers in Minas Gerais manufacturing belt specify this bracket for just-in-time component sequencing. Telemetry integration rates run highest in this segment.
- Above 10 Tons:Heavy-duty container handlers and specialized yard trucks engineered for Port of Santos terminal expansion and steel coil transport. Terminal operators are accelerating orders as intermodal capacity expands. CONMETRO load-weighing certification mandates extend delivery timelines.
- 1-3 Tons:Compact electric units optimized for retail backrooms and light manufacturing with constrained aisle widths. Pharmaceutical distribution centers in Osasco prioritize ergonomic specifications in this bracket.
- 5-10 Tons:Heavy manufacturing and construction material handling with diesel or LPG powertrains dominating outdoor yard applications. Paper mills in São Paulo state specify this range for roll handling.
3-5 Tons captures procurement volume concentration; Above 10 Tons is climbing the fastest on port modernization.
End User:
Operational environment dictates equipment specification from ambient warehousing to contamination-controlled pharmaceutical handling.
- Warehousing:E-commerce fulfillment centers and third-party logistics operations driving narrow-aisle reach truck adoption with telemetry-enabled fleet management. São Paulo-based contract logistics providers are consolidating supplier relationships around bundled uptime contracts.
- Manufacturing:Automotive, metalworking, and food processing facilities with specialized requirements for load stability and collision avoidance. NR-12 safety regulation updates are triggering preemptive fleet upgrades in food processing environments.
- Retail:Backroom stocking and cross-dock operations with space-constrained maneuverability requirements. Fast-charging lithium configurations eliminate dedicated battery rooms in hypermarket distribution.
- Transportation:Port terminals, rail yards, and air cargo facilities handling containerized and breakbulk cargo. Port of Santos container terminal modernization is accelerating above-10 ton capacity orders.
Warehousing dominates current installed base; Manufacturing is gaining share fastest on safety mandate compliance.
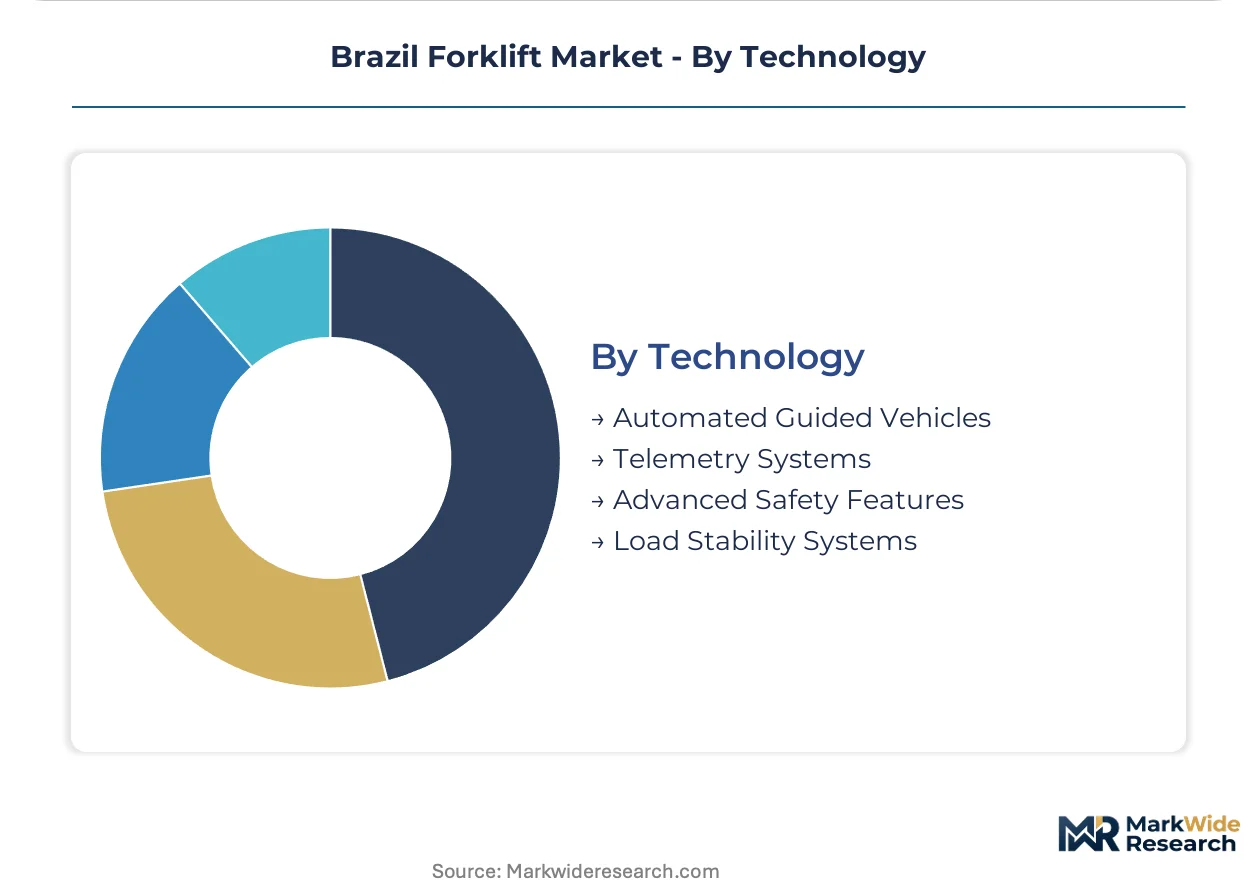
Technology:
Digital and autonomous capabilities are reconfiguring procurement from asset ownership toward performance-based contractual relationships.
- Telemetry Systems:Real-time data acquisition on utilization, battery state, and maintenance intervals enabling subscription-based fleet management. Legacy warehouse management system integration challenges persist in decade-old ERP installations common in Brazilian third-party logistics.
- Automated Guided Vehicles:Laser and vision-guided unmanned units for repetitive horizontal transport in high-volume distribution centers. São Paulo-Guarulhos corridor operators are piloting AGV integration with existing manual fleets.
- Advanced Safety Features:Collision-avoidance sensors, proximity alarms, and operator presence systems mandated by evolving NR-12 regulations. Food processing environments face proposed sensor requirements ahead of enforcement deadlines.
- Load Stability Systems:Active mast damping and automatic load centering for high-bay storage safety in pharmaceutical and food manufacturing. ANVISA workplace safety standards are tightening operator protection requirements.
Telemetry Systems anchor current technology spending; Automated Guided Vehicles represent the steepest expansion trajectory as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators and manufacturing procurement teams concentrate equipment orders in Brazil's industrialized Southeast, while emerging demand from automotive and metalworking belts reshapes geographic priorities. State-level environmental mandates and port modernization programs are redistributing fleet investment across five key sub-regions.
São Paulo
E-commerce fulfillment centers in the Guarulhos corridor drive narrow-aisle reach truck procurement as warehouse automation accelerates. CONMETRO certification requirements for industrial equipment safety tighten compliance standards statewide. Pharmaceutical distribution clusters in Osasco and Barueri retrofit existing fleets to meet ANVISA workplace safety standards ahead of enforcement deadlines.
Minas Gerais
Automotive and metalworking facilities in the manufacturing belt specify 3-5 ton capacity units for just-in-time component sequencing. INMETRO energy efficiency labeling for electric traction motors influences government-tendered fleet replacements. Belo Horizonte industrial parks remain underpenetrated by telemetry-enabled fleet management services relative to São Paulo benchmarks.
Rio de Janeiro
Port terminal operators handling breakbulk cargo maintain demand for above-10 ton capacity handlers alongside containerized freight equipment. ANVISA emissions monitoring in enclosed warehousing accelerates electric forklift displacement of legacy IC units. Duque de Caxias logistics zones serve as staging points for petrochemical supply chain equipment deployment.
Rio Grande do Sul
Paper mills and agricultural processing facilities specify 5-10 ton diesel-powered units for roll handling and bulk commodity operations. LPG refueling infrastructure lock-in sustains internal combustion procurement despite electrification pressure. Porto Alegre manufacturing clusters show emerging interest in lithium-ion fast-charging configurations for multi-shift meatpacking operations.
Paraná
Food and beverage manufacturing facilities adopt fast-charging lithium configurations to eliminate battery changeout labor in refrigerated warehousing. Proposed NR-12 safety regulation updates mandating collision-avoidance sensors trigger preemptive fleet upgrades. Curitiba distribution centers consolidate supplier relationships around bundled uptime contracts with telemetry analytics.
Brazil Forklift Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Brazil's forklift procurement landscape. The market structure reflects moderate consolidation among full-line OEMs with established Brazilian assembly presence, while niche specialists capture premium segments through application-specific configurations. Two strategic archetypes dominate: integrated manufacturers leveraging dual-brand distribution networks, and European engineering-focused specialists concentrating on high-density warehousing solutions. Competitive moves center on fleet management contract bundling and telemetry infrastructure deployment as recurring revenue anchors.
Among the integrated manufacturing tier, Toyota Industries Corporation anchors the premium electric segment through its established Brazilian assembly presence, while Hyster Yale occupies a position exemplifying dual-brand distribution strategy across both powertrain architectures. Within the European specialist archetype, Jungheinrich AG represents narrow-aisle reach truck configuration expertise for automated warehouse deployments in Greater São Paulo. These three companies illustrate the competitive positioning spectrum from scale-driven full-line coverage to application-engineered specialization.
| Leading Market Players |
|---|
| Hyster Yale |
| Komatsu |
| Mitsubishi Corporation |
| Hangcha |
| Clark |
| Toyota Industries Corporation |
| KION Group AG |
| Jungheinrich AG |
| Doosan Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in São Paulo state's lithium-ion battery assembly infrastructure compresses supplier pricing power while elevating procurement premiums for fast-charging configurations. CONMETRO certification bottlenecks extend order-to-delivery intervals, forcing buyers into cost-plus contracts indexed to currency volatility and international cell supply.
Pricing Analysis
Cost-plus contracts with USD-BRL indexation clauses dominate procurement agreements for electric forklift fleets above 3-ton capacity. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates Toyota Industries Corporation positioning from Hangcha value offerings. Pricing pressure stems from lithium cell import dependency and extended CONMETRO approval timelines. Third-party logistics operators exhibit highest price sensitivity due to thin contract margins, while pharmaceutical distribution centers prioritize ANVISA-compliant specifications over acquisition cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese battery manufacturers anchor working capital structures for Brazilian OEM assembly operations. Lithium cell supply concentrates in China, South Korea, and Japan, with manganese and cobalt feedstocks drawing from the DRC and Indonesia. Currency volatility and single-source dependency on Asian cell production constitute primary supply chain risk. Distribution runs through authorized dealer networks with regional service depots in São Paulo, Minas Gerais, and Rio Grande do Sul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates and NR-12 safety sensor proposals are accelerating fleet replacement cycles beyond traditional depreciation schedules, compressing incumbent equipment lifecycles and opening white-space for telemetry-enabled service providers.
For Market Incumbents: Entrench fleet management contract bundling to lock out independent service providers and capture recurring telemetry revenue. Deepen backward integration into lithium battery refurbishment capabilities to offset import cost volatility. Prioritize CONMETRO certification pre-approval for new battery chemistries to compress delivery timelines versus competitors.
For New Entrants and Emerging Players: Pursue underpenetrated Minas Gerais automotive supplier clusters with just-in-time sequencing solutions absent from incumbent portfolios. Target 3-5 ton capacity segment with subscription-based uptime guarantees rather than asset sales. Deploy direct field engineering teams to bypass established dealer networks in Belo Horizonte industrial parks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telemetry-as-a-service sub-segments as software margins displace hardware-dependent returns. Long-term viability favors platform operators with installed base data network effects over pure equipment manufacturers. Monitor INMETRO A-rated motor procurement thresholds as signal for specification advantage consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Enables subscription revenue capture from São Paulo logistics operators seeking uptime guarantees. |
| Lithium Battery Supply Agreement | Secures cell allocation from Chinese manufacturers ahead of currency-driven price adjustments. |
| CONMETRO Certification Pre-Investment | Compresses delivery timelines for load-weighing attachments in Port of Santos terminal procurement. |
| Aftermarket Service Network Expansion | Captures maintenance revenue from aging IC forklift installed base in Rio Grande do Sul lumber yards. |
| Joint Venture for Local Assembly | Reduces import duty exposure and satisfies government-tendered fleet replacement local content requirements. |
Research Methodology
Cross-validation between primary interviews with fleet maintenance directors and secondary trade data anchors the qualitative findings. Plant engineers, OEM procurement teams, aftermarket service heads, and third-party logistics operators provided operational perspective. Customs records, INMETRO certification databases, ANVISA regulatory filings, and CONMETRO equipment registries supplied quantitative validation. Bottom-up equipment shipment tallies triangulate against top-down manufacturing value estimates.
Calibration against historical replacement cycle patterns and port capacity expansion schedules shapes the analytical framework. Segmentation dimensions include powertrain architecture, capacity tier, end-use environment, and telemetry integration level across the modeling period. CAGRs derive from equipment procurement pipeline analysis and fleet age distribution surveys. NR-12 regulatory timeline assumptions and lithium cell price trajectory inputs inform projection sensitivity.
Sensitivities concentrate around CONMETRO approval velocity, BRL exchange rate volatility, and NR-12 sensor mandate enforcement timing. Forecasts reflect documented assumptions regarding electrification adoption curves and port modernization commitment levels. Macroeconomic contraction, regulatory delay, or battery technology substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Scissor Lift Market