
 Global Cardiac Mapping Market | 2026-2036
Global Cardiac Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Mapping Market Foresight
Multi-source procurement of mapping catheters and navigation platforms is expanding as hospital systems diversify supplier relationships beyond single-vendor EP lab contracts. Abbott leverages its integrated portfolio of diagnostic and therapeutic catheters to sustain long-term supply agreements with integrated delivery networks. Boston Scientific Corporation competes through specialized magnetic sensor arrays that occupy the high-precision segment of atrial fibrillation ablation workflows. Medtronic controls extensive distribution infrastructure across North American and European electrophysiology markets.
Cardiac mapping encompasses the real-time acquisition, processing, and spatial visualization of electrical activation patterns within cardiac chambers using multi-electrode catheters, magnetic field tracking, and impedance-based localization with sub-millimeter spatial resolution. These systems enable electrophysiologists to identify arrhythmogenic substrates prior to catheter ablation, reducing procedure time and improving clinical outcomes. Electroanatomical mapping systems lead the product landscape due to their established reimbursement codes and procedural familiarity among trained operators. Catheter-based mapping dominates the technology dimension, though artificial intelligence integration represents the fastest-growing sub-area as machine learning algorithms automate signal annotation and arrhythmia classification.
FDA premarket notification requirements and the EU MDR conformity assessment process govern device safety and clinical performance standards for cardiac mapping platforms entering their respective markets. The EPA regulates disposal pathways for single-use catheter components containing electronic sensors and precious metal electrodes. Stakeholders must monitor evolving FDA guidance on AI-enabled diagnostic features and MDR technical documentation requirements for software-driven mapping algorithms.
Market Dynamics
Catheter-based electroanatomical mapping platforms are consolidating clinical workflows as tertiary cardiac centers standardize on integrated navigation systems that compress procedure times and reduce fluoroscopy exposure.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for software-enhanced mapping algorithms reduce commercialization timelines for new platform entrants.
- Japan's tertiary center consolidation:Government-directed volume concentration into designated arrhythmia treatment hubs expands addressable installed base for navigation systems.
- AI-enabled signal annotation:Machine learning automation of electrogram classification reduces operator cognitive load and enables complex substrate mapping in extended procedures.
Market Restraints
- Precious metal electrode volatility:Platinum and iridium price swings in catheter sensor arrays compress gross margins for disposable mapping catheter manufacturers.
- EU MDR technical documentation burden:Conformity assessment requirements for software-driven algorithms extend certification timelines and increase regulatory compliance costs.
- Single-use electronic waste pathways:EPA disposal regulations for catheter components containing sensors and circuit elements add end-of-life compliance overhead.
Strategic Opportunities
- India's underpenetrated electrophysiology infrastructure:PLI scheme incentives for medical device manufacturing create localized production pathways for mapping catheter assemblies.
- Convergence of magnetic tracking with impedance localization:Hybrid navigation architectures deliver sub-millimeter precision without proprietary hardware lock-in.
- Remote procedural support networks:Real-time cloud connectivity enables expert electrophysiologist guidance across distributed catheterization laboratories.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship program capacity limits specialist availability to operate complex mapping platforms.
- Legacy EMR integration complexity:Proprietary data formats from mapping systems require custom middleware development for hospital IT interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Mapping Market |
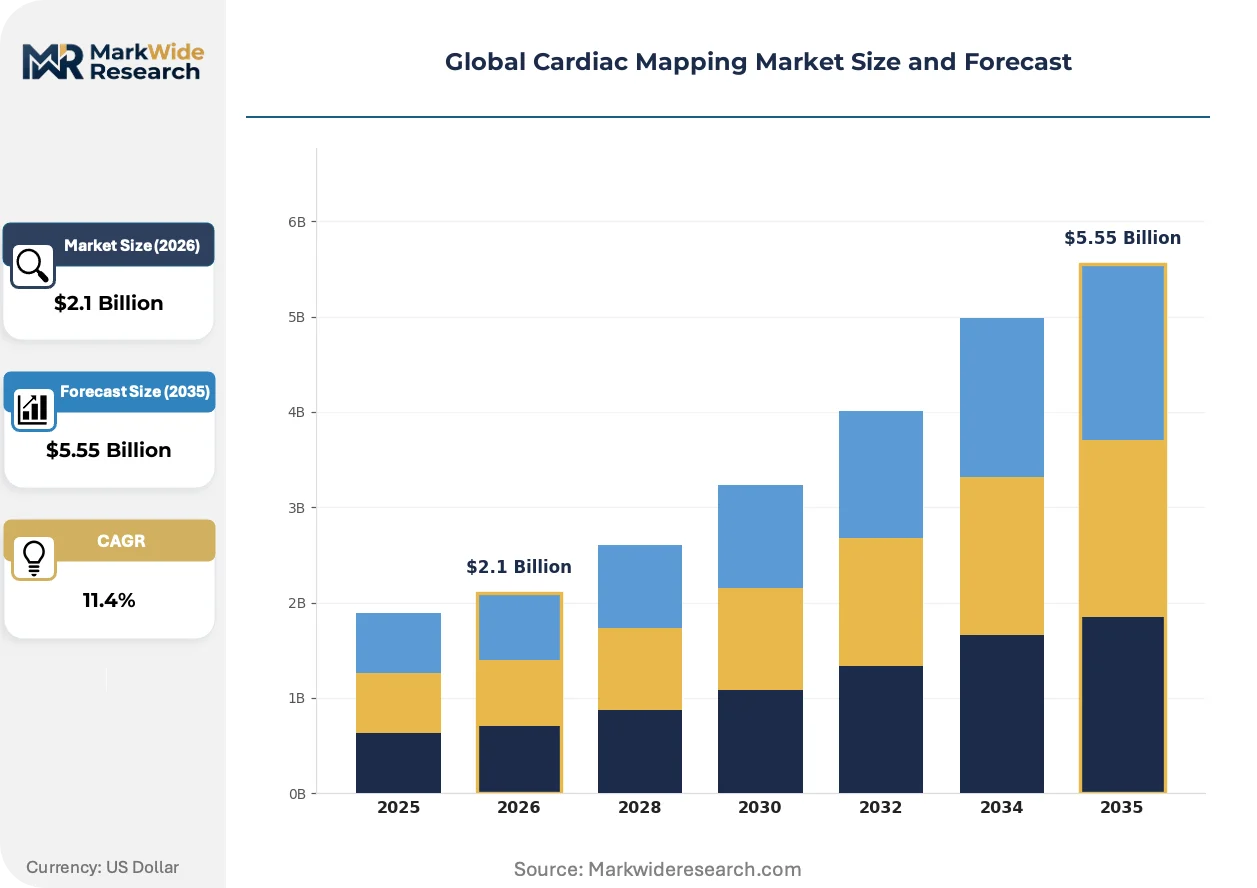
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroanatomical Mapping, Contact Mapping, Non-contact Mapping, Optical Mapping, Magnetic Mapping Technology: 3D Mapping Systems, Catheter-based Mapping, Non-invasive Mapping, Signal Processing Algorithms, Artificial Intelligence Integration Application: Atrial Fibrillation, Ventricular Tachycardia, Supraventricular Tachycardia, Atrial Flutter, Cardiac Arrhythmia Diagnosis End User: Cardiology Clinics, Electrophysiology Labs, Research Institutions, Ambulatory Surgical Centers |
| Companies Covered | Johnson & Johnson, Abbott, Boston Scientific Corporation, Medtronic, Biosense Webster, Koninklijke Philips N.V., BIOTRONIK, MicroPort Scientific Corporation, Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Mapping Market Shifts & Advancements
Artificial intelligence is restructuring competitive differentiation as algorithmic performance replaces hardware specifications as the primary purchasing criterion for electrophysiology laboratories.
Machine learning-based arrhythmia classification is integrating into real-time mapping workflows to automate electrogram annotation and reduce procedural cognitive burden. Tertiary cardiac centers in Germany and Japan are deploying these systems for complex atrial fibrillation cases. The technology is integrating diagnostic and therapeutic decision support into unified platform architectures that compress total procedure duration.
The EU MDR conformity assessment framework is elevating clinical evidence requirements for software-driven mapping algorithms beyond legacy device pathways. Technical documentation for AI-enabled diagnostic features now demands prospective validation datasets. European electrophysiology device manufacturers are responding by restructuring quality management systems and expanding clinical affairs capabilities.
Integrated delivery networks are consolidating supplier relationships around single-vendor EP lab contracts that bundle mapping platforms with therapeutic catheters and ablation systems. Independent hospitals and smaller health systems are losing negotiating leverage as procurement authority centralizes. This concentration is most visible in United States metropolitan markets where IDN-affiliated cardiac centers now dominate arrhythmia procedure volumes.
Global Cardiac Mapping Market Segmentation
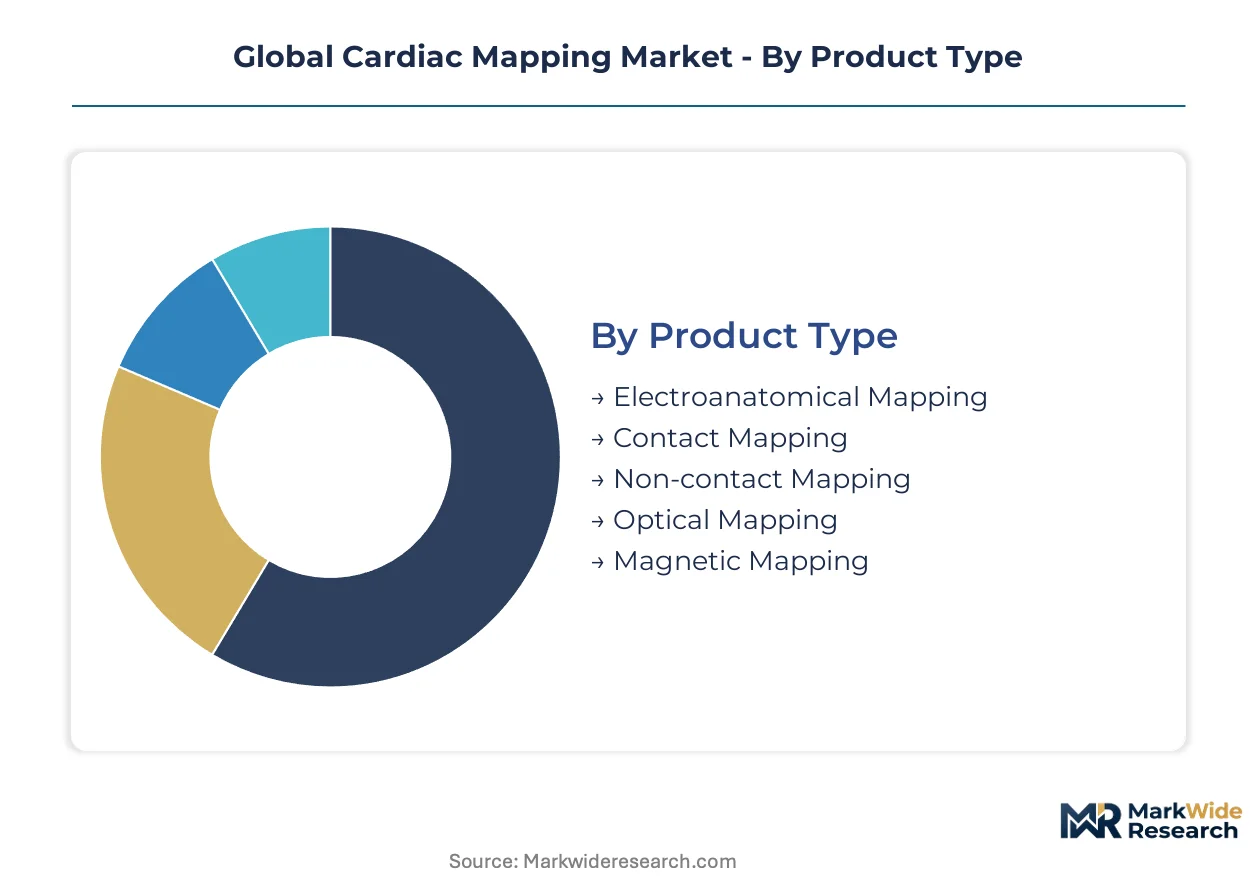
Segmentation in cardiac mapping reveals distinct procurement patterns across integrated delivery networks and independent facilities. Product type and technology choices determine capital expenditure profiles, while application focus shapes disposable catheter volumes. Understanding these divisions exposes where pricing power concentrates and where vendor consolidation pressures operate most intensely.
Product Type:
Integration depth varies sharply: electroanatomical and contact mapping systems typically anchor standalone EP lab installations, while optical and magnetic platforms embed into hybrid surgical suites.
- Electroanatomical Mapping:Multi-electrode catheter arrays generate real-time 3D cardiac chamber reconstructions with voltage and activation timing overlays. Demand concentrates in United States tertiary cardiac centers where established reimbursement codes and operator training familiarity sustain installed base expansion. The technology's procedural workflow integration makes switching costs substantial for existing users.
- Contact Mapping:Direct tissue-electrode interfaces deliver high-fidelity electrogram acquisition for substrate characterization in complex arrhythmia cases. German electrophysiology laboratories prioritize these systems for ventricular tachycardia ablation workflows where signal precision determines procedural success. Operator dependency on tactile catheter feedback sustains preference for contact-based approaches.
- Non-contact Mapping:Balloon-mounted multielectrode arrays reconstruct endocardial activation from intracavitary potentials without direct tissue contact.
- Optical Mapping:Voltage-sensitive fluorescent dyes enable high-resolution activation mapping in research settings and specialized surgical environments.
- Magnetic Mapping:Magnetic field tracking of sensor-equipped catheters provides location data independent of impedance fluctuations.
Electroanatomical mapping leads volumes today; artificial intelligence-enhanced contact mapping configurations are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive 3D navigation installations from software-layer investments that retrofit existing hardware.
- 3D Mapping Systems:Integrated hardware-software platforms combine electromagnetic tracking, catheter localization, and 3D visualization in single-vendor architectures. Japanese designated arrhythmia treatment hubs drive procurement concentration as government-directed volume consolidation expands addressable installed base. These systems command premium pricing but lock hospitals into long-term disposable supply agreements.
- Catheter-based Mapping:Disposable electrode arrays constitute the recurring revenue engine of cardiac mapping economics. United States integrated delivery networks negotiate multi-year supply contracts bundling diagnostic and therapeutic catheter portfolios. Platinum and iridium electrode content exposes manufacturers to precious metal price volatility.
- Non-invasive Mapping:Body surface potential mapping with inverse solution algorithms reconstructs cardiac electrical activity without catheter insertion.
- Signal Processing Algorithms:Digital filtering and activation detection software extracts actionable electrophysiological data from noisy recordings.
- Artificial Intelligence Integration:Machine learning models automate electrogram classification and arrhythmia substrate identification in real-time workflows.
Catheter-based mapping dominates current revenue; artificial intelligence integration is expanding most quickly as algorithmic performance becomes a primary purchasing criterion.
Application:
Procedure volume distribution across arrhythmia types determines catheter consumption rates and mapping system utilization intensity.
- Atrial Fibrillation:The most common sustained arrhythmia in clinical practice drives the majority of cardiac mapping procedure volumes globally. United States electrophysiology laboratories perform complex pulmonary vein isolation procedures requiring extended 3D mapping support. Procedure complexity and recurrence rates sustain demand for advanced substrate characterization capabilities.
- Ventricular Tachycardia:Life-threatening arrhythmias arising from structural heart disease demand precise scar-border zone mapping for ablation targeting. German and Japanese tertiary centers concentrate expertise for these high-risk procedures where mapping precision directly impacts patient survival. Substrate-based ablation approaches extend procedure duration and disposable consumption.
- Supraventricular Tachycardia:Accessory pathway and atrioventricular nodal reentrant tachycardias represent technically straightforward mapping targets.
- Atrial Flutter:Cavotricuspid isthmus-dependent circuits require limited mapping support compared to atrial fibrillation procedures.
- Cardiac Arrhythmia Diagnosis:Unspecified diagnostic mapping procedures support clinical decision-making prior to therapeutic intervention.
Atrial fibrillation procedures generate the highest absolute volumes; ventricular tachycardia mapping is climbing the fastest as structural heart disease prevalence expands.
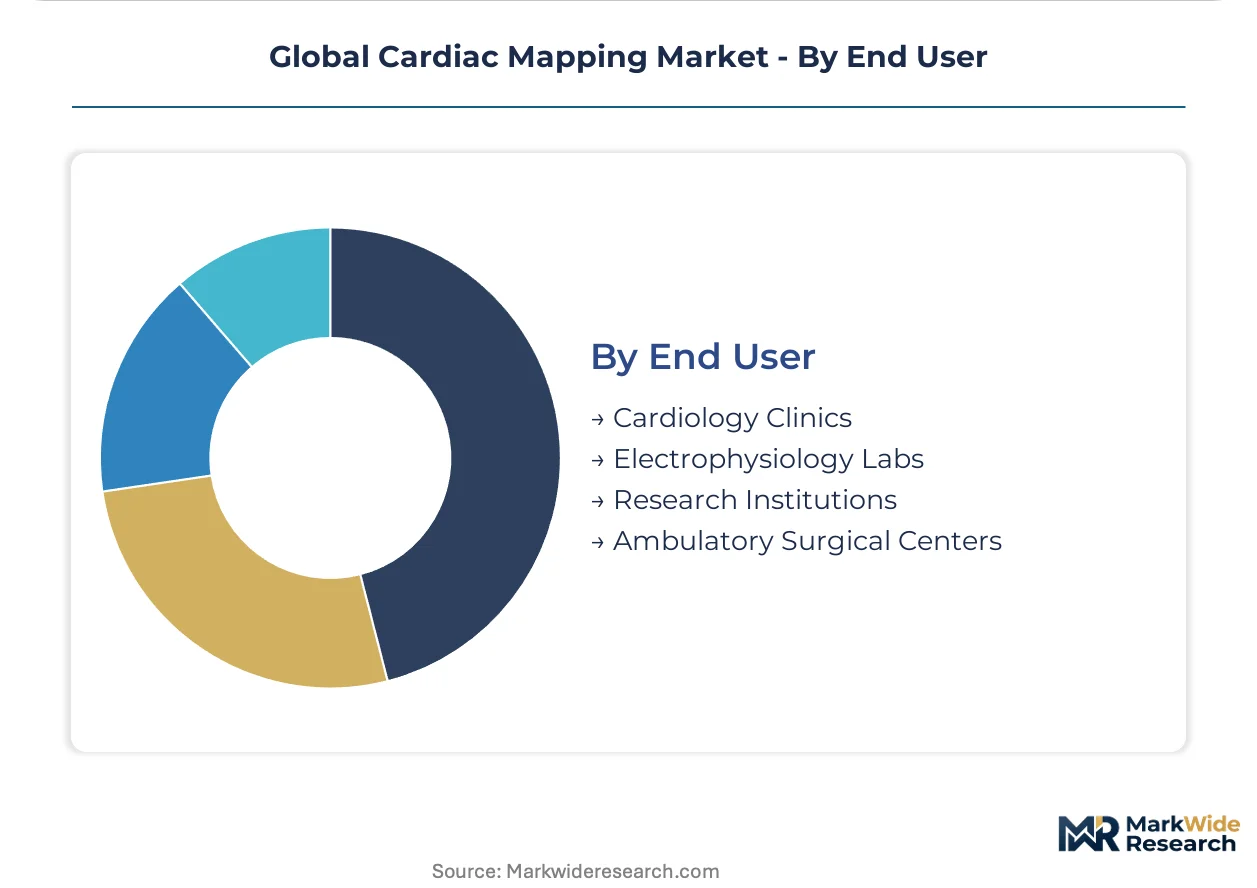
End User:
Customer type segmentation reveals diverging procurement authority between consolidated health systems and fragmented independent providers.
- Electrophysiology Labs:Hospital-based catheterization laboratories constitute the core installed base for advanced mapping platform deployment. United States metropolitan markets exhibit concentration of procedure volumes into IDN-affiliated cardiac centers with centralized procurement authority. These facilities negotiate bundled contracts spanning navigation systems, therapeutic catheters, and ablation technologies.
- Cardiology Clinics:Office-based cardiac practices perform diagnostic electrophysiology studies with limited mapping system requirements. Smaller patient volumes and capital constraints restrict adoption to lower-cost or refurbished equipment platforms. Reimbursement differentials between facility and non-facility settings shape site-of-service economics.
- Research Institutions:Academic medical centers drive early adoption of experimental mapping modalities including optical and high-density electrode approaches.
- Ambulatory Surgical Centers:Freestanding surgical facilities are expanding into electrophysiology procedures as regulatory frameworks evolve.
Electrophysiology labs anchor current platform deployment; ambulatory surgical centers represent the steepest expansion trajectory as procedural migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cleveland Clinic anchors global cardiac mapping procedure innovation. Tertiary cardiac centers in the United States, Germany, and Japan concentrate installed base expansion for electroanatomical navigation platforms. Regulatory pathways in these markets accelerate commercialization timelines for catheter-based mapping technologies.
United States
Integrated delivery networks consolidate procurement authority across metropolitan cardiac centers. FDA 510(k) premarket notification pathways streamline software-enhanced mapping algorithm approvals. The Cleveland Clinic and Mayo Clinic anchor arrhythmia treatment volume concentration in Ohio and Minnesota.
Germany
Designated arrhythmia treatment hubs drive navigation system deployment under government-directed volume consolidation. EU MDR conformity assessment governs software-driven algorithm certification for CE marking. Heidelberg and Hamburg tertiary centers prioritize contact mapping systems for ventricular tachycardia ablation workflows.
Japan
Government-mandated volume concentration into designated cardiac centers expands addressable installed base. PMDA regulatory pathways align with international standards for electrophysiology device approval. Tokyo and Osaka metropolitan clusters concentrate electrophysiologist specialist capacity and complex procedure volumes.
India
Underpenetrated electrophysiology infrastructure creates expansion pathways for mapping catheter assemblies. PLI scheme incentives support localized manufacturing of medical device components. Maharashtra and Karnataka cardiac centers in Mumbai and Bangalore build arrhythmia treatment capacity.
Switzerland
Swissmedic regulatory frameworks maintain alignment with EU MDR standards for device market access. Zurich and Geneva academic medical centers drive early adoption of experimental mapping modalities. Research institutions prioritize optical and high-density electrode approaches in specialized surgical environments.
Global Cardiac Mapping Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled algorithm differentiation. The vendor base concentrates around integrated navigation system architectures that bundle hardware platforms with disposable catheter supply agreements. Three archetypes dominate: diversified medical technology conglomerates with electrophysiology portfolios, specialized catheter manufacturers with sensor array expertise, and algorithm-focused software vendors retrofitting existing hardware. Dominant competitive moves include strategic partnerships for AI integration and geographic expansion into underpenetrated Asian markets.
Among diversified medical technology conglomerates, Johnson & Johnson and Abbott exemplify integrated portfolio strategies that bundle diagnostic and therapeutic catheters with long-term supply agreements. Boston Scientific Corporation occupies a position within the specialized precision segment, representing magnetic sensor array expertise for high-precision ablation workflows. Medtronic anchors the distribution infrastructure archetype across North American and European electrophysiology markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott |
| Boston Scientific Corporation |
| Medtronic |
| Biosense Webster |
| Koninklijke Philips N.V. |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| Acutus Medical |
| Others |
Supply & Pricing Matrix
Platinum and iridium electrode arrays in disposable mapping catheters cascade through three pricing tiers as precious metal volatility compresses margins at the manufacturing layer and forces tiered pass-through to hospital procurement committees in the United States, Germany, and Japan.
Pricing Analysis
Input-cost pass-through from precious metal electrode arrays drives contract-based long-term offtake agreements between catheter manufacturers and integrated delivery networks. Price differentiation separates FDA-cleared premium platforms from standard CE-marked configurations, with customization level for AI-enabled algorithms commanding additional licensing fees. Cost compression in the standard tier is intensifying because platinum spot price volatility erodes manufacturer margins. Independent cardiology clinics exhibit highest price sensitivity due to capital constraints, while tertiary cardiac centers with centralized procurement authority demonstrate lowest sensitivity to per-procedure disposable costs.
Supply Chain Analysis
Regional distribution centers in Minnesota, Ohio, and Massachusetts anchor hub-and-spoke patterns for North American electrophysiology device logistics. Manufacturing concentrates in the United States, Ireland, and Costa Rica for sterile catheter assembly, while sensor array fabrication draws from Japanese and German precision electronics suppliers. Single-source vulnerability in magnetic sensor components creates supply chain risk for hybrid navigation platforms. Distribution runs through GPO-negotiated channels that bundle mapping systems with therapeutic catheter portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac mapping market operates as a regulatory compounder where EU MDR conformity assessment timelines for software-driven algorithms are extending certification windows and concentrating procurement authority among vendors with established clinical affairs infrastructure.
For Market Incumbents: Acquire AI algorithm development capabilities to defend against emerging software vendors retrofitting existing hardware with automated electrogram classification. Priority moves include backward integration into machine learning talent pools and capacity addition in Costa Rica for catheter assembly to offset precious metal cost pressure. Hospital system partnership lock-in through bundled disposable supply agreements remains the critical defensive lever.
For New Entrants and Emerging Players: FDA 510(k) clearance pathway acceleration in the United States opens a window for specialized magnetic sensor array manufacturers to penetrate the high-precision atrial fibrillation segment. White-space targets include India's underpenetrated electrophysiology infrastructure and ambulatory surgical center migration in United States metropolitan markets. Direct-to-EP-lab software licensing models bypass capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Consolidation pressure builds where electrophysiologist training pipeline constraints limit specialist availability to operate complex mapping platforms. Long-term viability favors algorithm-focused software vendors with regulatory clearance momentum over capital-intensive hardware manufacturers tethered to precious metal commodity cycles. Acquisition target archetype: AI-enabled diagnostic platforms with prospective validation datasets. The signal to watch is PMDA alignment with international standards accelerating Japanese market entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates software-enhanced mapping algorithm commercialization timelines. |
| CE Marking Pathway | EU MDR conformity assessment governs software-driven diagnostic feature certification for European market access. |
| Hospital System Partnership | Integrated delivery network bundled contracts consolidate procurement authority for navigation system installations. |
| Software Companion Development | Machine learning automation of electrogram classification reduces operator cognitive load in complex procedures. |
| Reimbursement Strategy | Established CPT codes for electroanatomical mapping sustain procedure economics in United States tertiary centers. |
Research Methodology
Multiple input streams — primary interviews with electrophysiologists and hospital purchasing committees, secondary validation through FDA 510(k) filings and CMS Medicare reimbursement databases, and trade data from medical device customs records — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included catheterization laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary sources encompassed hospital procurement databases, EU MDR technical documentation repositories, and electrophysiology society procedure volume surveys.
Historical procedure volume trajectories were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled included mapping technology type, arrhythmia application, end-user facility tier, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and disposable catheter consumption intensity. Industry-specific forecast inputs incorporated electrophysiologist fellowship program capacity and precious metal price trend assumptions.
Revisions become necessary when FDA guidance on AI-enabled diagnostic features shifts, EU MDR technical documentation requirements expand, or precious metal commodity volatility disrupts catheter manufacturing economics. Forecasts reflect documented assumptions about regulatory pathway timelines and hospital consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Europe ECG Electrodes Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Global Stethoscope Market