
 Electrophysiology Ablation Market | 2026-2036
Electrophysiology Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophysiology Ablation Market Analysis
Pulsed field ablation is reconfiguring the catheter technology stack by enabling non-thermal myocardial tissue destruction with reduced esophageal and phrenic nerve injury risk compared to thermal modalities. Medtronic plc leverages its integrated mapping and ablation platform to sustain procedural workflow control across hospital customers. Abbott Laboratories anchors its competitive position through specialized cryoablation balloon technology for pulmonary vein isolation. Biosense Webster, operating under Johnson & Johnson, dominates the 3D electroanatomic mapping segment that enables complex arrhythmia substrate characterization.
Electrophysiology ablation encompasses catheter-delivered energy application to cardiac tissue for targeted destruction of arrhythmogenic substrates, utilizing radiofrequency, cryothermal, laser, or pulsed electric field modalities at frequencies between 450 and 500 kHz for radiofrequency applications. The primary purpose is restoration of normal cardiac conduction patterns in patients with supraventricular tachycardia, atrial fibrillation, and ventricular tachycardia refractory to pharmacological management. Radiofrequency catheters retain the largest installed base and reimbursement familiarity, though cryoablation catheters command premium positioning for paroxysmal atrial fibrillation cases with favorable single-procedure efficacy data. Three-dimensional mapping systems represent the fastest-growing technology segment as electrophysiologists demand enhanced anatomical visualization for persistent atrial fibrillation and ventricular tachycardia ablations where substrate complexity exceeds conventional fluoroscopic guidance capabilities.
The FDA regulates electrophysiology ablation catheters as Class III medical devices requiring premarket approval or humanitarian device exemption pathways with stringent clinical evidence standards for safety and efficacy endpoints. The European Medical Device Regulation mandates enhanced post-market surveillance and clinical follow-up obligations that extend compliance costs for manufacturers seeking CE marking renewal. Japan's PMDA maintains distinct pharmaceutical and medical device agency review processes that create additional registration timelines for novel energy modalities. Stakeholders must monitor pulsed field ablation long-term durability data and corresponding payer coverage decisions that will determine whether this technology displaces established thermal platforms or segments into specific patient risk categories.
Market Dynamics
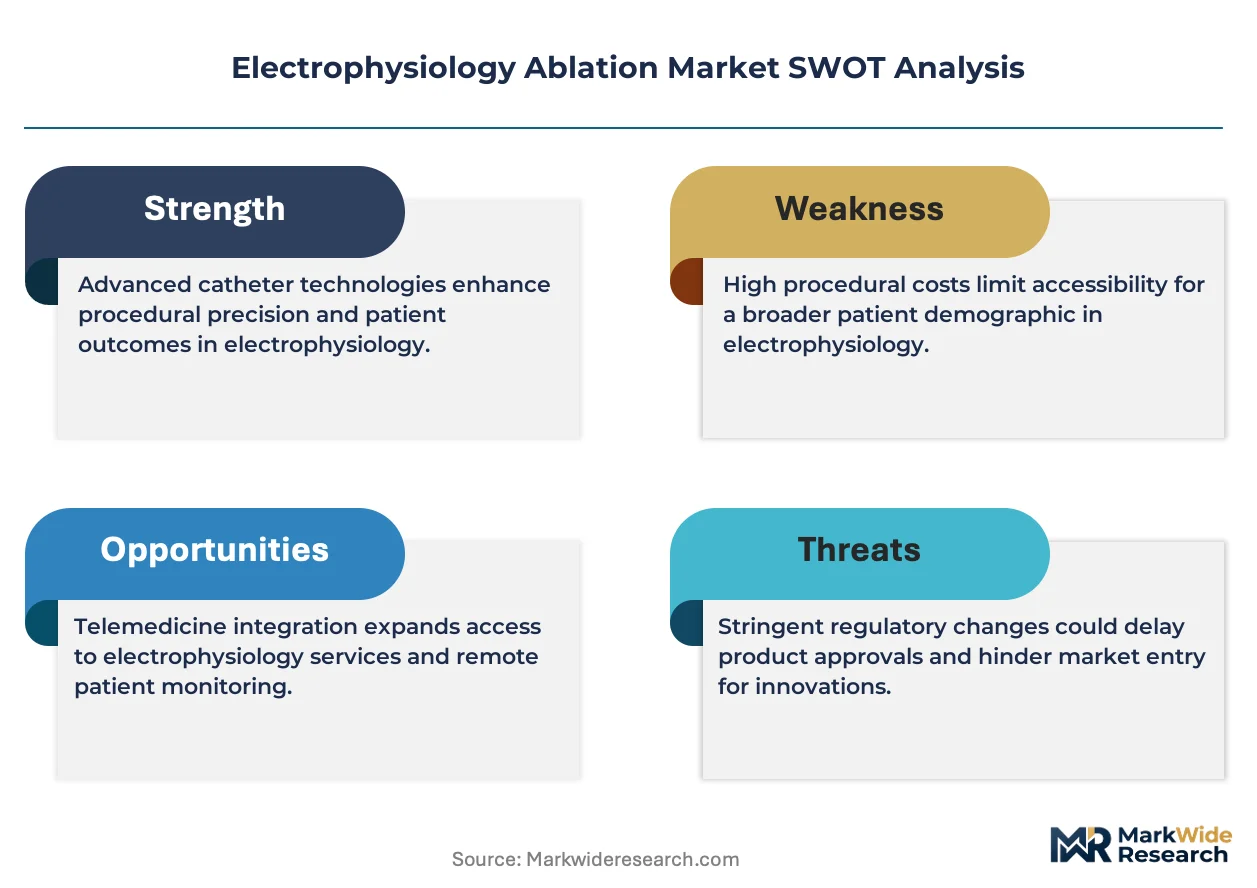
Pulsed field ablation is collapsing the thermal modality hierarchy by delivering irreversible electroporation without collateral thermal damage, forcing catheter manufacturers to reconfigure R&D roadmaps and hospital capital allocation toward non-thermal platforms.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA's accelerated review track for novel ablation technologies compresses commercialization timelines for pulsed field systems, reducing time-to-revenue for manufacturers targeting paroxysmal atrial fibrillation indications.
- Germany's Reimbursement Alignment:German statutory health insurance funds have established favorable DRG codes for complex catheter ablation procedures, incentivizing hospital electrophysiology lab expansion across Bavaria and North Rhine-Westphalia.
- Japan's Aging Demographics:Japan's Ministry of Health, Labour and Welfare reports rising procedural volumes for atrial fibrillation management as the population over 65 expands, creating sustained demand for advanced ablation catheters and mapping systems.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Radiofrequency catheter electrodes depend on platinum-group metal pricing, exposing manufacturers to commodity input swings that compress gross margins on legacy thermal platforms.
- European MDR Compliance Burden:The European Medical Device Regulation mandates enhanced clinical follow-up and post-market surveillance for Class III devices, extending CE marking renewal costs and timelines for ablation catheter manufacturers.
- Fluoroscopy Reduction Mandates:Hospital radiation safety committees are imposing strict fluoroscopy time limits, creating technical friction for electrophysiologists lacking 3D mapping system proficiency or capital access.
Strategic Opportunities
- India's Underpenetrated Electrophysiology Infrastructure:India's CDSCO regulatory framework is streamlining medical device registration, opening access for catheter ablation systems in tertiary cardiac centers across Maharashtra and Tamil Nadu.
- Pulsed Field-Robotic Convergence:Integration of irreversible electroporation catheters with robotic navigation systems enables remote procedure execution, addressing electrophysiologist scarcity in rural and underserved hospital networks.
- US Hospital Outpatient Department Migration:The Centers for Medicare & Medicaid Services site-of-service differentials are shifting complex ablation procedures from inpatient to outpatient settings, creating demand for compact, mobile mapping and ablation platforms.
Industry Challenges
- Electrophysiologist Training Bottleneck:The specialized fellowship pipeline produces insufficient operators to match expanding catheter ablation capacity, particularly for complex persistent atrial fibrillation and ventricular tachycardia substrates requiring advanced 3D mapping interpretation.
- Legacy System Integration Friction:Hospital electrophysiology labs face capital write-down pressures when integrating pulsed field generators with installed base radiofrequency generators and proprietary mapping architectures from competing manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophysiology Ablation Market |
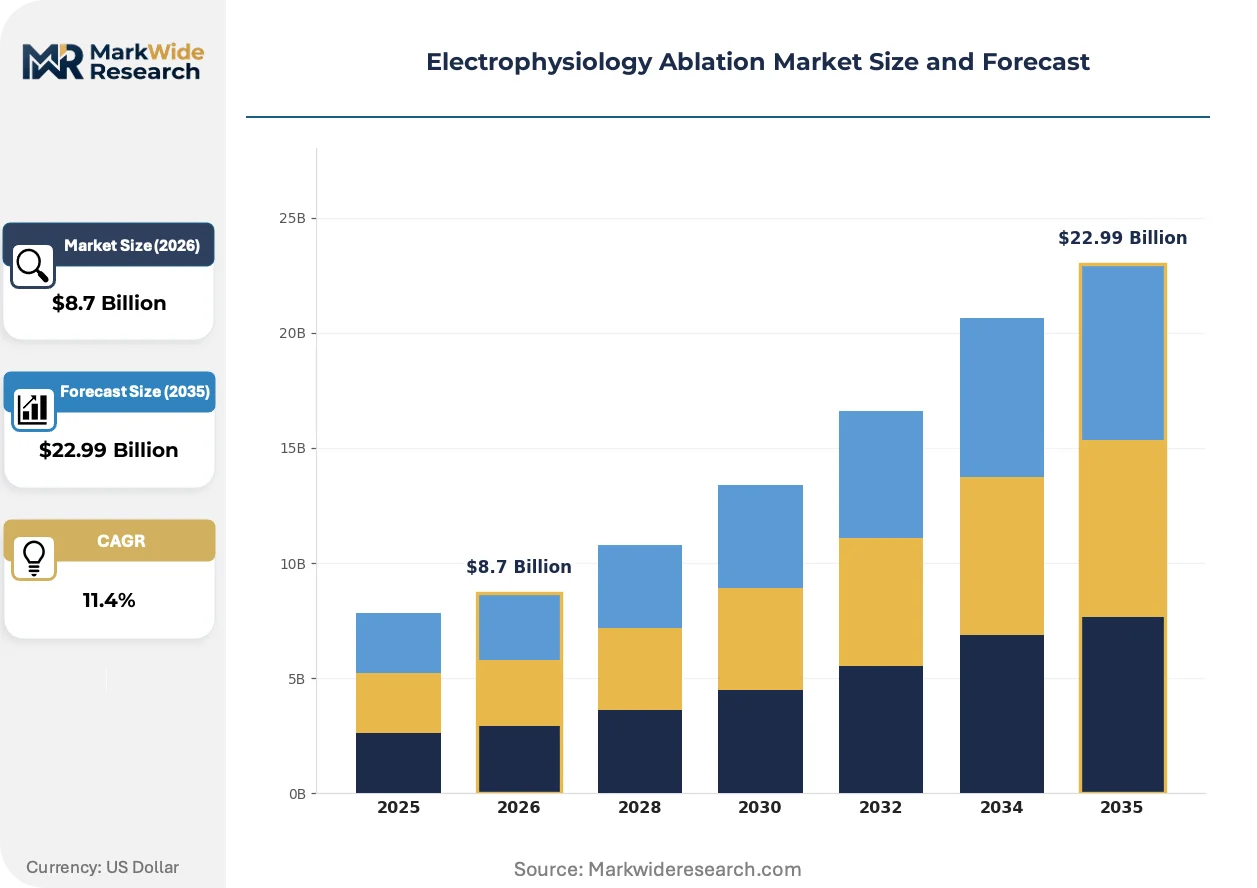
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Atrial Fibrillation, Ventricular Tachycardia, Supraventricular Tachycardia, Atrial Flutter Catheter Type: Radiofrequency Catheters, Cryoablation Catheters, Laser Catheters, Microwave Catheters End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Institutions Technology: 3D Mapping Systems, Electrophysiology Systems, Imaging Systems, Navigation Systems |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, Biosense Webster, Philips Healthcare, Biotronik SE & Co. KG, MicroPort Scientific Corporation, AtriCure, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophysiology Ablation Market Emerging Trajectories
Catheter-based cardiac ablation is undergoing platform-level transformation as energy modalities, regulatory frameworks, and care delivery models simultaneously reconfigure competitive positioning and buyer behavior.
Bipolar radiofrequency ablation is collapsing the unipolar thermal paradigm by delivering focused energy between closely spaced electrodes, eliminating distant tissue heating. Electrophysiologists at high-volume US academic medical centers are adopting bipolar systems for ventricular tachycardia substrate modification. The technology is collapsing procedure times and repeat ablation rates for complex arrhythmias previously refractory to standard approaches.
Japan's PMDA has established distinct review pathways for novel energy modalities that separate pharmaceutical and medical device assessment processes. This bifurcation accelerates pulsed field ablation system approvals while maintaining rigorous safety surveillance. Japanese manufacturers and multinational subsidiaries are responding by prioritizing PMDA pre-submission meetings to align clinical trial designs with post-market study requirements.
Hospital catheter laboratory procurement is consolidating vendor relationships around integrated mapping-ablation platforms rather than discrete device purchasing. Electrophysiology lab directors are negotiating multi-year capital equipment agreements that bundle generator hardware, disposable catheters, and software subscriptions. This pattern is most pronounced in United States integrated delivery networks and German hospital federations seeking to standardize procedural workflows and reduce inter-operator variability.
Electrophysiology Ablation Market Segmentation
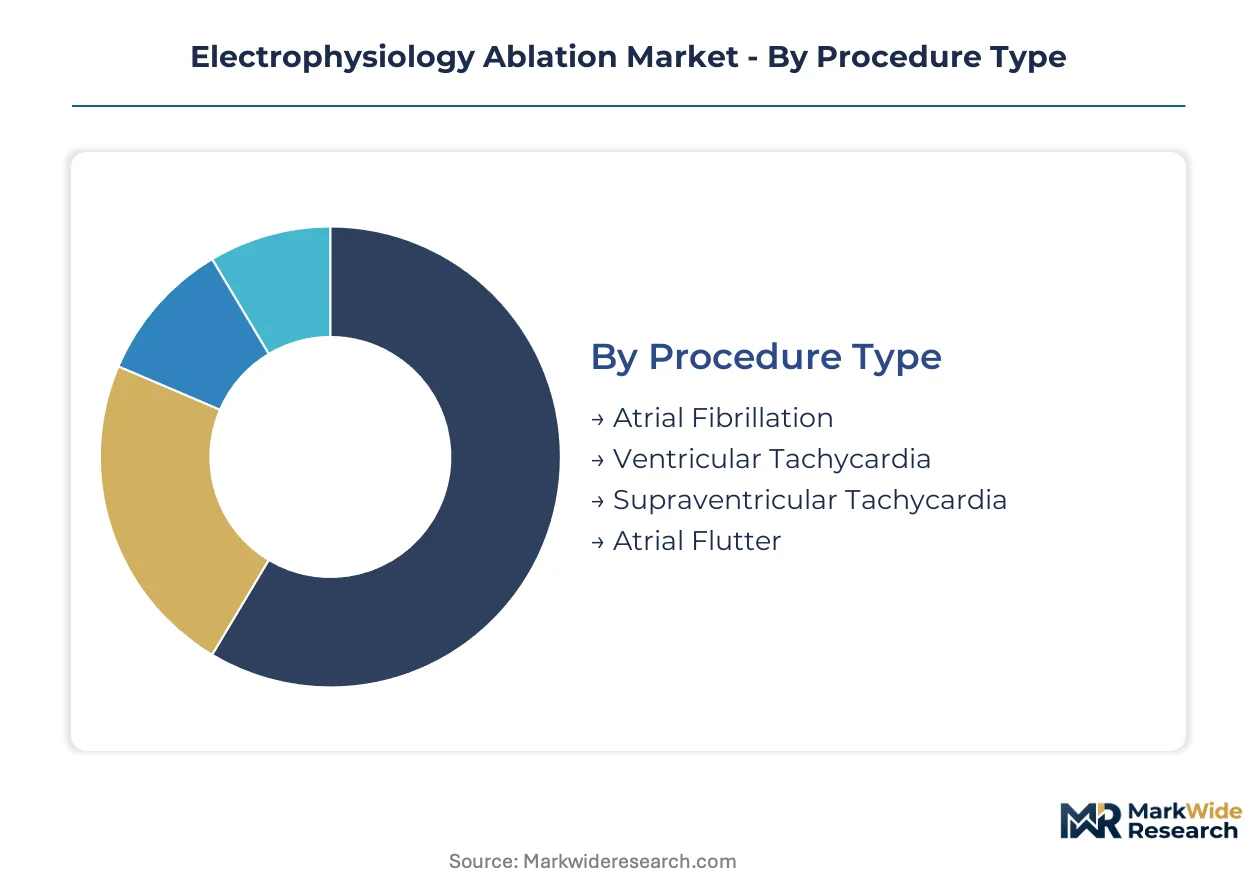
Segmentation in electrophysiology ablation reveals distinct procurement cycles and capital intensity patterns across procedure types, catheter technologies, and care settings. Understanding these structural differences enables manufacturers to align R&D investment with replacement timelines and reimbursement trajectories.
Procedure Type:
Atrial fibrillation procedures turn over catheter inventory fastest due to high procedural volumes, while ventricular tachycardia ablations operate on slower cycles driven by complexity and lower case frequency.
- Atrial Fibrillation:Catheter-based pulmonary vein isolation dominates procedural volume in electrophysiology labs across the United States, Germany, and Japan. German statutory health insurance DRG alignment and Japan's expanding over-65 population sustain demand for repeat ablations and touch-up procedures.
- Ventricular Tachycardia:Substrate modification procedures require advanced 3D electroanatomic mapping and extended fluoroscopy exposure. US academic medical centers concentrate demand for bipolar radiofrequency systems targeting scar-related arrhythmias refractory to antiarrhythmic drugs.
- Supraventricular Tachycardia:Accessory pathway ablation and AV nodal reentrant tachycardia correction represent established indications with mature reimbursement pathways.
- Atrial Flutter:Cavotricuspid isthmus ablation maintains strong efficacy profiles with shorter procedure times than atrial fibrillation interventions.
Atrial fibrillation dominates installed base. Ventricular tachycardia is where expansion concentrates.
Catheter Type:
Radiofrequency platforms anchor the middle cost tier with established reimbursement, while cryoablation commands premium positioning and laser systems occupy emerging technology price bands.
- Radiofrequency Catheters:Unipolar and bipolar electrode configurations deliver thermal energy at 450-500 kHz frequencies with proven durability data. Platinum-iridium electrode cost volatility compresses manufacturer margins on legacy platforms while sustaining hospital familiarity with generator interfaces.
- Cryoablation Catheters:Balloon-based cryothermal delivery achieves pulmonary vein isolation through controlled tissue freezing. Abbott Laboratories' specialized balloon technology captures premium positioning in paroxysmal atrial fibrillation cases with favorable single-procedure efficacy outcomes.
- Laser Catheters:Optical energy delivery enables precise tissue ablation with reduced collateral thermal spread.
- Microwave Catheters:Electromagnetic field heating penetrates deeper tissue layers than conventional radiofrequency approaches.
Radiofrequency catheters represent the largest installed base. Cryoablation catheters are climbing the fastest.
End User:
Hospitals concentrate the highest absolute volume, while ambulatory surgical centers represent the fastest site-of-service migration driven by CMS reimbursement differentials.
- Hospitals:Electrophysiology labs in integrated delivery networks bundle capital equipment, disposable catheters, and software subscriptions through multi-year vendor agreements. US hospital outpatient departments are shifting complex ablation procedures from inpatient settings under CMS site-of-service payment reforms.
- Cardiology Clinics:Specialized cardiac centers concentrate diagnostic electrophysiology studies and straightforward ablation procedures.
- Ambulatory Surgical Centers:Compact mapping and ablation platforms enable same-day discharge for select paroxysmal atrial fibrillation cases.
- Research Institutions:Academic medical centers drive adoption of novel energy modalities including pulsed field ablation systems.
Hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest.
Technology:
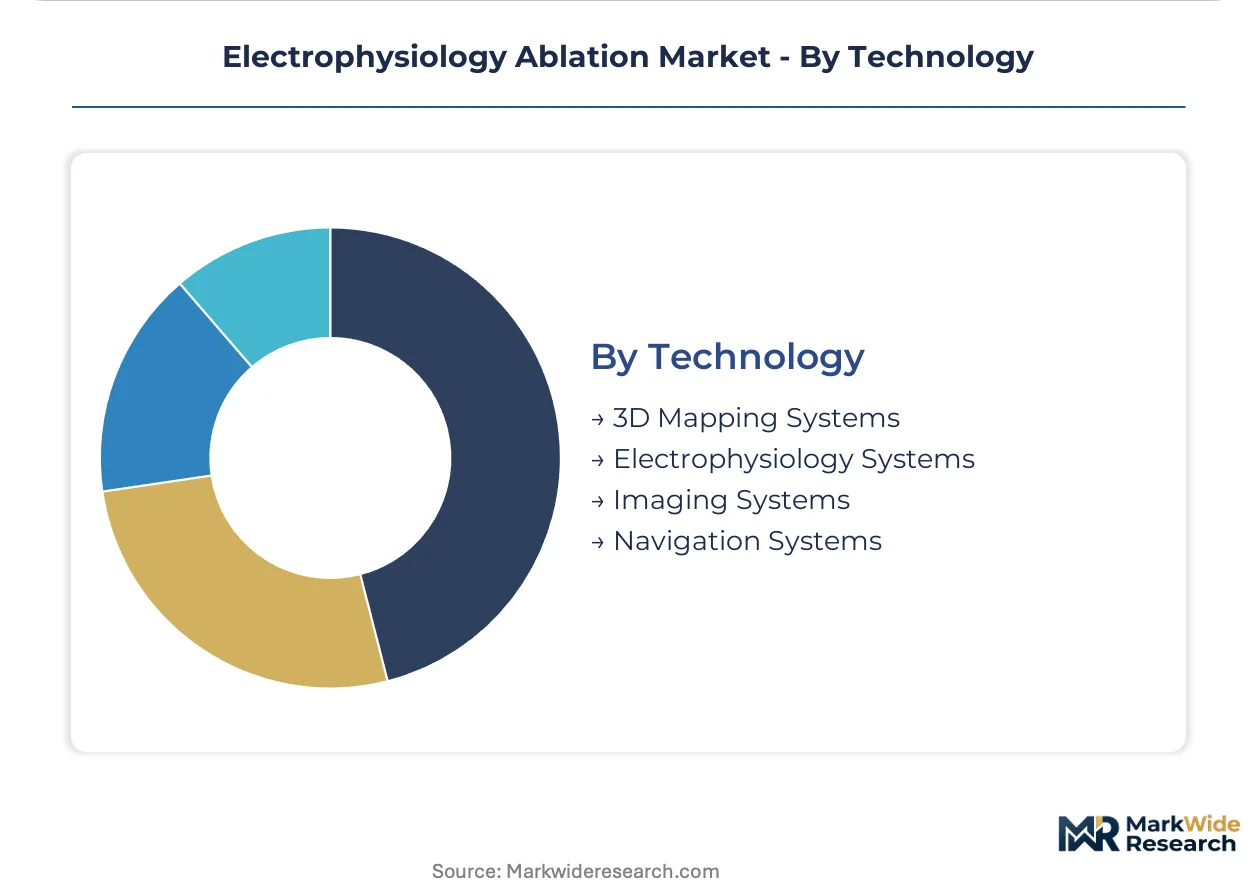
3D mapping systems command the highest capital intensity and fastest replacement cycles, while imaging and navigation platforms follow distinct upgrade timelines tied to software release schedules.
- 3D Mapping Systems:Electroanatomic reconstruction enables complex arrhythmia substrate characterization without prolonged fluoroscopy exposure. Biosense Webster's platform architecture dominates persistent atrial fibrillation and ventricular tachycardia ablations where anatomical precision exceeds conventional guidance capabilities.
- Electrophysiology Systems:Integrated recording and stimulation platforms anchor procedural workflow in high-volume labs.
- Imaging Systems:Intracardiac echocardiography and contact force sensing enhance lesion formation assessment.
- Navigation Systems:Robotic catheter navigation addresses electrophysiologist scarcity in rural hospital networks.
3D mapping systems dominate installed base. Navigation systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital electrophysiology labs in the United States, Germany, and Japan concentrate the highest absolute demand for catheter ablation systems. Integrated delivery networks in these markets bundle capital equipment and disposable purchasing through multi-year vendor agreements.
United States
Medicare site-of-service payment differentials are shifting complex ablation procedures from inpatient to hospital outpatient departments. The FDA's Breakthrough Device Pathway accelerates commercialization timelines for novel pulsed field systems. Academic medical centers in Boston and Cleveland drive adoption of bipolar radiofrequency platforms for ventricular tachycardia substrate modification.
Germany
Statutory health insurance funds have established favorable DRG codes for complex catheter ablation procedures. The European Medical Device Regulation mandates enhanced post-market surveillance for Class III devices. Hospital federations in Bavaria and North Rhine-Westphalia are expanding electrophysiology lab capacity for atrial fibrillation patients.
Japan
The Ministry of Health, Labour and Welfare reports rising procedural volumes as the population over 65 expands. PMDA maintains distinct review pathways for novel energy modalities that separate pharmaceutical and medical device assessment. Tertiary cardiac centers in Tokyo and Osaka concentrate demand for advanced 3D mapping systems.
India
CDSCO regulatory framework streamlines medical device registration for multinational manufacturers. Reimbursement alignment for catheter ablation remains uneven across state-level health insurance schemes. Tertiary cardiac centers in Maharashtra and Tamil Nadu are acquiring compact mapping platforms to address growing atrial fibrillation case loads.
China
NMPA review timelines for Class III cardiovascular devices have compressed through priority review pathways. Provincial health commissions in Jiangsu and Guangdong are incorporating catheter ablation into essential medical insurance catalogs. Domestic manufacturers in the Yangtze River Delta are scaling production of radiofrequency generators for hospital procurement tenders.
Electrophysiology Ablation Market Vendor Landscape
Channel-controlling players compete with product-specialist players across integrated mapping-ablation platforms and discrete catheter technologies. The market exhibits consolidated concentration at the platform level alongside fragmented specialization in energy modalities and procedure-specific tools. Three archetypes dominate: diversified medical technology conglomerates with full-stack electrophysiology portfolios, focused cardiovascular device manufacturers with single-modality excellence, and emerging entrants commercializing pulsed field systems. Competitive moves center on multi-year hospital capital agreements and regulatory pre-submission alignment for novel energy modalities.
Among diversified platform providers, Medtronic plc and Abbott Laboratories anchor distinct technology vectors. Medtronic exemplifies the integrated mapping-ablation archetype through procedural workflow control across hospital customers. Abbott Laboratories occupies premium positioning in cryothermal delivery systems for paroxysmal atrial fibrillation. Johnson & Johnson subsidiary Biosense Webster represents the 3D electroanatomic mapping specialization that enables complex arrhythmia substrate characterization.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Biosense Webster |
| Philips Healthcare |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| AtriCure, Inc. |
| Others |
Supply Flow & Price Mechanics
Air freight corridors connecting Frankfurt, Shanghai, and Memphis carry platinum-iridium electrodes and cryoballoon components with fuel surcharge indexation that amplifies cost differentials between thermal and non-thermal catheter platforms. This logistics architecture concentrates margin pressure on radiofrequency catheter manufacturers while enabling premium pricing for pulsed field systems with shorter supply chains.
Pricing Analysis
Cost-plus contracts with platinum-group metal indexation dominate radiofrequency catheter procurement, exposing Abbott Laboratories and Biosense Webster to commodity volatility that cryoablation and laser platforms avoid through fixed-input structures. Price differentiation rests on CE marking tier and procedural volume commitments, with German hospital federations extracting steeper discounts than US academic medical centers. Pricing pressure stems from platinum-iridium electrode cost swings that compress legacy platform margins. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks prioritize workflow integration over unit cost.
Supply Chain Analysis
Export controls on semiconductor-grade sensors and precision-machined catheter shafts limit flows from US and EU suppliers to Chinese manufacturers, fragmenting component sourcing for 3D mapping systems. Manufacturing concentrates in Ireland, Costa Rica, and Malaysia for sterile catheter assembly, with platinum-iridium electrodes drawing from South African and Russian mining operations. Single-source vulnerability pervades cryoballoon nitinol framework supply. Distribution runs through hospital GPO contracts and direct vendor agreements with electrophysiology lab directors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pulsed field ablation constitutes an imminent substitution threat that thermal platform incumbents must neutralize through R&D redirection and procedural workflow lock-in.
For Market Incumbents: Entrench hospital relationships through multi-year capital bundling of mapping systems with disposable catheter commitments, neutralizing pulsed field entrants' workflow disruption advantage. Accelerate backward integration into platinum-iridium electrode recycling to offset commodity volatility eroding radiofrequency margins. Prioritize FDA breakthrough pathway alignment for bipolar radiofrequency iterations that match non-thermal safety profiles. For New Entrants and Emerging Players: Pursue India's CDSCO-registered catheter platforms for Maharashtra and Tamil Nadu tertiary centers where installed base concentration remains lowest. Target ventricular tachycardia substrate mapping as the penetrable segment where 3D system penetration lags atrial fibrillation adoption. Deploy software-as-a-service mapping subscriptions to circumvent capital equipment barriers in ASC expansion. For Investors and Strategic Acquirers: Single-modality pulsed field specialists with PMDA pre-submission alignment represent the acquisition archetype with highest regulatory optionality. Long-term viability hinges on whether non-thermal durability data sustains reimbursement parity with thermal platforms. Watch for CMS national coverage determination reversals on outpatient pulmonary vein isolation as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Pathway Submission | Accelerates pulsed field system review timelines under FDA's expedited track. |
| Hospital System Partnership | Bundles mapping hardware with catheter disposables across multi-year vendor agreements. |
| CE Marking Pathway Renewal | Navigates MDR enhanced surveillance obligations for Class III device recertification. |
| Software Companion Development | Integrates AI-powered lesion assessment into 3D electroanatomic mapping platforms. |
| Reimbursement Strategy | Aligns pulsed field procedural codes with DRG classifications in Germany and Japan. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA PMA filings, PMDA approval summaries, and CMS Medicare claims data through bottom-up and top-down triangulation. Primary interviews engaged electrophysiologists, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers across US integrated delivery networks and German hospital federations. Secondary validation drew from CE marking databases, Japanese Ministry of Health procedural volume reports, and trade customs records for platinum-group metal flows.
Forecast inputs incorporate catheter shipment data, hospital electrophysiology lab capital expenditure surveys, and regulatory approval timeline distributions across the analysis window. Segmentation modeling spans procedure type, energy modality, end-user setting, and geographic regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns of prior energy modality transitions, with pulsed field ablation penetration rates calibrated against radiofrequency and cryoablation analogues.
Sensitivities concentrate around long-term durability data publication schedules and corresponding payer coverage reversals. Forecasts reflect assumptions on procedural volume elasticity to reimbursement rate changes and electrophysiologist training pipeline expansion. Material shifts in FDA breakthrough pathway eligibility criteria or MDR post-market surveillance enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Knee Walkers Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Global Pupillometer Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Pulmonology Devices Market