
 Mobile Cardiac Telemetry Systems Market | 2026-2036
Mobile Cardiac Telemetry Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Cardiac Telemetry Systems Market Analysis
Silicon-based microelectromechanical systems are pivoting toward polymer flexible substrates in next-generation patch monitors, cutting unit costs and extending wear duration beyond fourteen days. Medtronic plc leverages its vertically integrated sensor foundry to control chip supply for implantable telemetry bridges. iRhythm Technologies sustains category leadership in deep-learning arrhythmia classification through proprietary convolutional neural networks trained on multi-million-patient datasets. BioTelemetry Inc. anchors its competitive position through exclusive partnerships with large cardiology practice networks across the southeastern United States.
Mobile cardiac telemetry systems combine ambulatory electrocardiographic acquisition hardware with cellular or Bluetooth data transmission and cloud-based analytic platforms to enable real-time cardiac event detection outside clinical settings. These systems typically sample at 128–1000 Hz, employ adhesive electrodes or dry-contact sensors, and stream encrypted data to centralized monitoring centers staffed by certified cardiac technicians. Patch monitors command the highest margin pools due to patient compliance advantages and premium reimbursement positioning, while wearable monitors with multi-parameter capability represent the fastest-expanding product category. Cloud computing infrastructure underpins nearly all scalable telemetry services, though wireless communication modules incorporating 5G low-latency protocols are displacing legacy cellular radios in next-generation devices.
FDA premarket notification requirements and subsequent CMS national coverage determinations shape commercial viability timelines for new mobile cardiac telemetry entrants, with breakthrough device designation offering expedited review for AI-diagnostic innovations. HIPAA security rule compliance and state-level telehealth licensing requirements create operational complexity for vendors serving multi-state health systems. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classification for algorithm updates that modify diagnostic sensitivity without new hardware submissions.
Market Dynamics
Hospital systems are consolidating remote cardiac monitoring contracts under value-based care frameworks that penalize readmissions, compressing vendor selection cycles and favoring platforms with predictive analytics capabilities.
Growth Catalysts
- Medicare reimbursement stabilization:CMS national coverage determinations for mobile cardiac telemetry have created predictable revenue streams for cardiology practices in the United States, accelerating program adoption.
- AI-enabled arrhythmia detection:FDA breakthrough device designation pathways are shortening premarket review timelines for algorithmic diagnostic tools, enabling faster commercialization of automated classification systems.
- Polymer flexible substrates:Adhesive patch monitors utilizing these materials now achieve wear durations exceeding fourteen days, improving patient compliance and reducing per-monitoring-event costs.
Market Restraints
- Silicon sensor supply concentration:Foundry capacity for microelectromechanical systems remains concentrated among a limited set of semiconductor manufacturers, creating input vulnerability for device makers.
- HIPAA compliance operational burden:State-level telehealth licensing requirements force vendors to maintain redundant legal and technical infrastructure across multiple jurisdictions, elevating fixed costs.
- Holter monitor substitution:Lower-cost ambulatory electrocardiography alternatives continue capturing price-sensitive segments, limiting premium telemetry penetration in budget-constrained health systems.
Strategic Opportunities
- 5G low-latency protocol integration:Wireless modules incorporating these standards enable real-time streaming with reduced power consumption, opening deployment in rural broadband-limited geographies.
- Software-as-a-medical-device classification:Evolving FDA guidance on algorithm updates without hardware resubmission creates regulatory runway for continuous diagnostic improvement.
- India cardiac monitoring infrastructure:Underpenetrated tertiary care networks and expanding health insurance coverage present white-space demand for cloud-based telemetry platforms.
Industry Challenges
- Certified cardiac technician staffing:Scalable monitoring center operations require specialized labor pools that remain geographically concentrated, constraining service expansion velocity.
- Cloud security architecture validation:HIPAA security rule audits and state data residency mandates demand continuous infrastructure investment, complicating multi-tenant platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Cardiac Telemetry Systems Market |
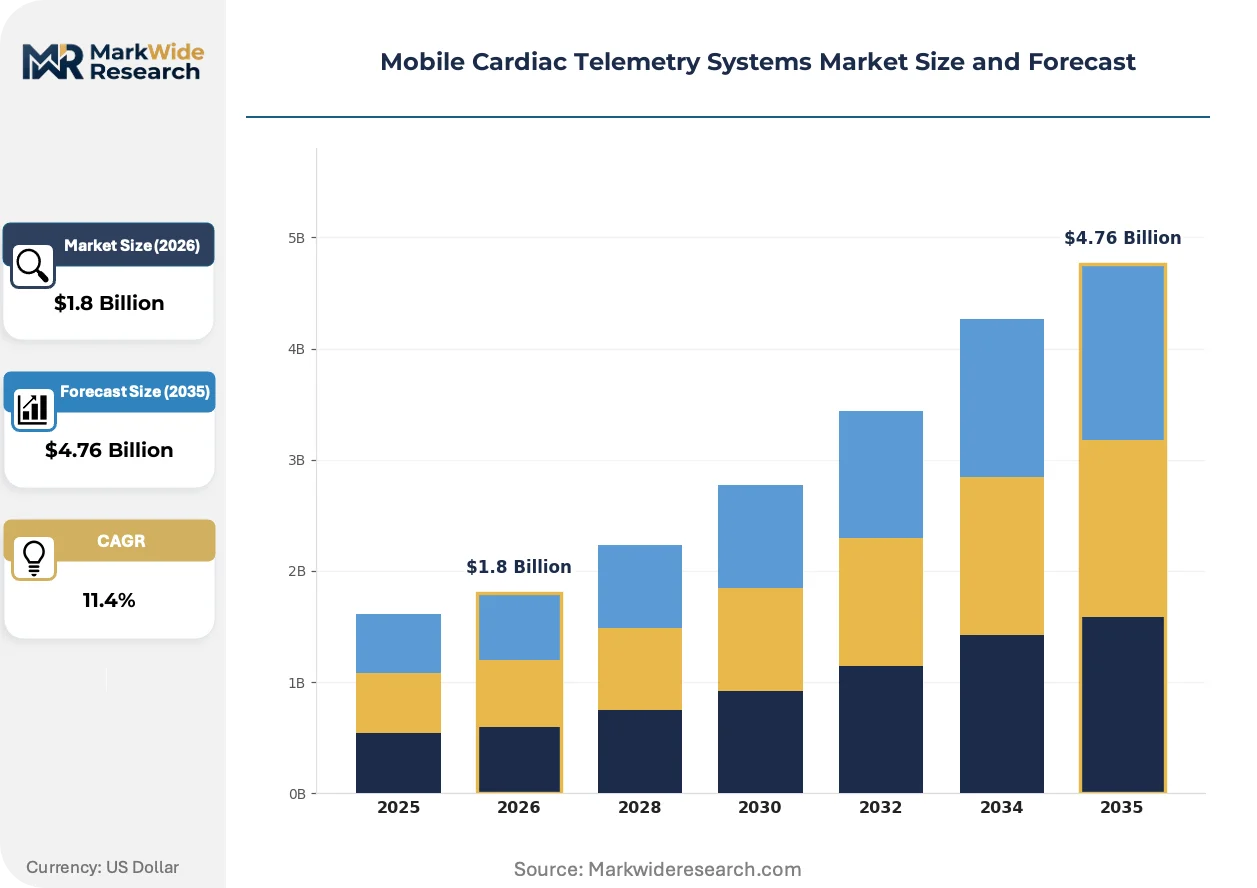
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Mobile ECG Devices, Patch Monitors, Handheld Monitors Technology: Cloud Computing, Wireless Communication, Bluetooth, Remote Sensing End User: Hospitals, Home Care Providers, Ambulatory Surgical Centers, Diagnostic Laboratories Application: Arrhythmia Monitoring, Heart Failure Management, Postoperative Monitoring, Preventive Healthcare |
| Companies Covered | Medtronic plc, iRhythm Technologies, BioTelemetry Inc., Boston Scientific Cardiac Diagnostics, Zoll Medical Corporation, Koninklijke Philips N.V., ScottCare, Biotricity Inc., Medicomp Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Cardiac Telemetry Systems Market Emerging Trajectories
Digital biomarker extraction and edge computing architectures are redefining how cardiac telemetry data generates actionable clinical intelligence outside traditional monitoring center workflows.
Polymer flexible substrates are overtaking silicon-based microelectromechanical systems in next-generation adhesive patch monitors. Cardiology practice networks in the southeastern United States are adopting these devices for extended ambulatory monitoring. The technology is overtaking legacy hardware by cutting unit manufacturing costs while simultaneously extending clinically valid wear duration.
EU Medical Device Regulation (MDR) classification requirements for software-driven diagnostic functions are tightening post-market surveillance obligations for algorithm-based arrhythmia detection systems. Manufacturers must now maintain clinical evidence packages for continuous learning models that update without hardware modification. Patch monitor vendors serving European markets are responding by establishing dedicated regulatory affairs functions and quality management systems aligned with notified body expectations.
Hospital procurement committees are consolidating vendor relationships under long-term remote patient monitoring agreements that bundle hardware, connectivity, and interpretation services. Independent cardiology practices are losing direct contracting leverage as health system centralization accelerates. This concentration is most visible in United States integrated delivery networks, where standardized platform selection now precedes individual physician preference.
Mobile Cardiac Telemetry Systems Market Segmentation
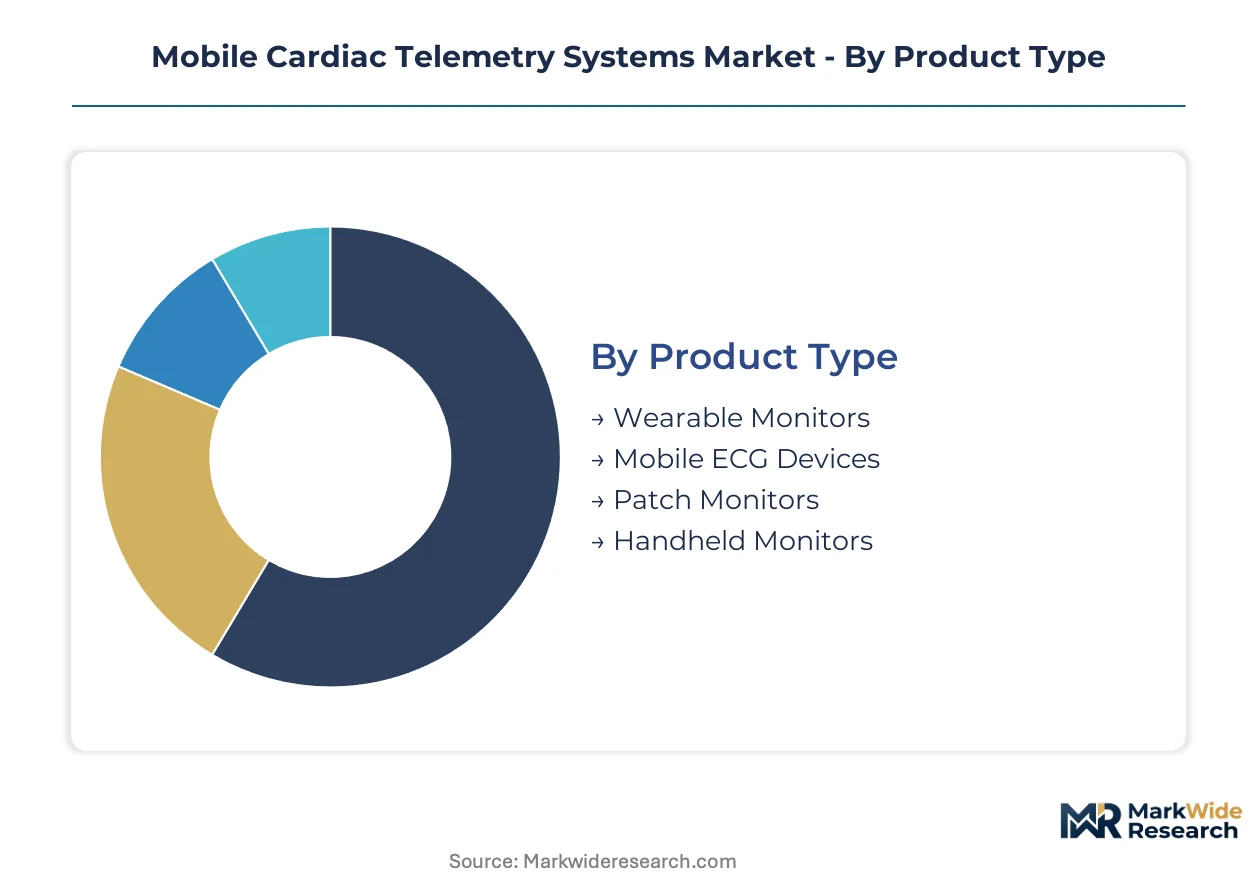
Segmentation in mobile cardiac telemetry reveals how hardware form factors, transmission protocols, care settings, and clinical use cases concentrate margin pools differently. Supply chain control points and reimbursement pathways vary sharply across these dimensions, shaping vendor investment priorities.
Product Type:
Manufacturing scale and component sourcing flexibility cluster around adhesive-based form factors, with polymer substrate supply chains now displacing silicon foundry dependencies for extended-wear devices.
- Patch Monitors:Single-use adhesive electrodes with integrated flexible electronics achieve fourteen-day wear durations through polymer substrate architectures. United States cardiology practices in the southeastern region are consolidating procurement around these devices for ambulatory arrhythmia detection, drawn by premium Medicare reimbursement codes and reduced per-event monitoring costs.
- Wearable Monitors:Multi-parameter wrist or chest-worn devices combine photoplethysmography with single-lead ECG acquisition. Hospital systems expanding remote patient monitoring programs under value-based care frameworks are prioritizing these for heart failure management, leveraging their patient familiarity and lower replacement frequency.
- Mobile ECG Devices:Smartphone-connected handheld units with dry-contact electrodes enable patient-triggered recordings.
- Handheld Monitors:Dedicated portable devices with integrated cellular transmission for acute symptom capture.
Patch monitors absorb the bulk of installed capacity; wearable monitors are expanding most quickly.
Technology:
Cloud infrastructure and wireless module selection determine operational scalability and geographic reach for telemetry service providers, with 5G protocol integration now separating next-generation platforms from legacy cellular architectures.
- Cloud Computing:Centralized data storage and algorithmic processing platforms enable scalable arrhythmia classification across distributed patient populations. HIPAA security rule compliance and state-level data residency mandates in the United States are forcing continuous infrastructure investment, complicating multi-tenant platform economics for vendors serving multi-state health systems.
- Wireless Communication:Cellular and emerging 5G low-latency modules support real-time streaming from patient to monitoring center. Rural broadband-limited geographies in the United States are driving demand for these protocols, where legacy cellular radios fail to maintain consistent connectivity.
- Bluetooth:Short-range protocols for smartphone-tethered data transmission in patient-triggered monitoring workflows.
- Remote Sensing:Edge computing architectures enabling preliminary signal processing at the device level.
Cloud computing anchors current service delivery; wireless communication modules are climbing the fastest as 5G deployment accelerates.
End User:
Procurement authority consolidation under integrated delivery networks is compressing vendor selection cycles and favoring platforms with predictive analytics capabilities across hospital and ambulatory settings.
- Hospitals:Inpatient and outpatient cardiology departments with centralized remote patient monitoring programs. United States hospital systems facing readmission penalties under CMS value-based purchasing programs are expanding telemetry contracts, consolidating vendor relationships under long-term agreements that bundle hardware, connectivity, and interpretation services.
- Home Care Providers:Post-acute and chronic care management services delivering monitoring outside institutional settings. Medicare reimbursement stabilization for mobile cardiac telemetry has created predictable revenue streams for these providers, accelerating program adoption for at-risk cardiac patients.
- Ambulatory Surgical Centers:Same-day procedure facilities requiring post-discharge cardiac surveillance.
- Diagnostic Laboratories:Independent testing facilities offering arrhythmia screening as a service line.
Hospitals command the dominant share of telemetry deployments; home care providers are gaining share fastest as post-acute monitoring expands.
Application:
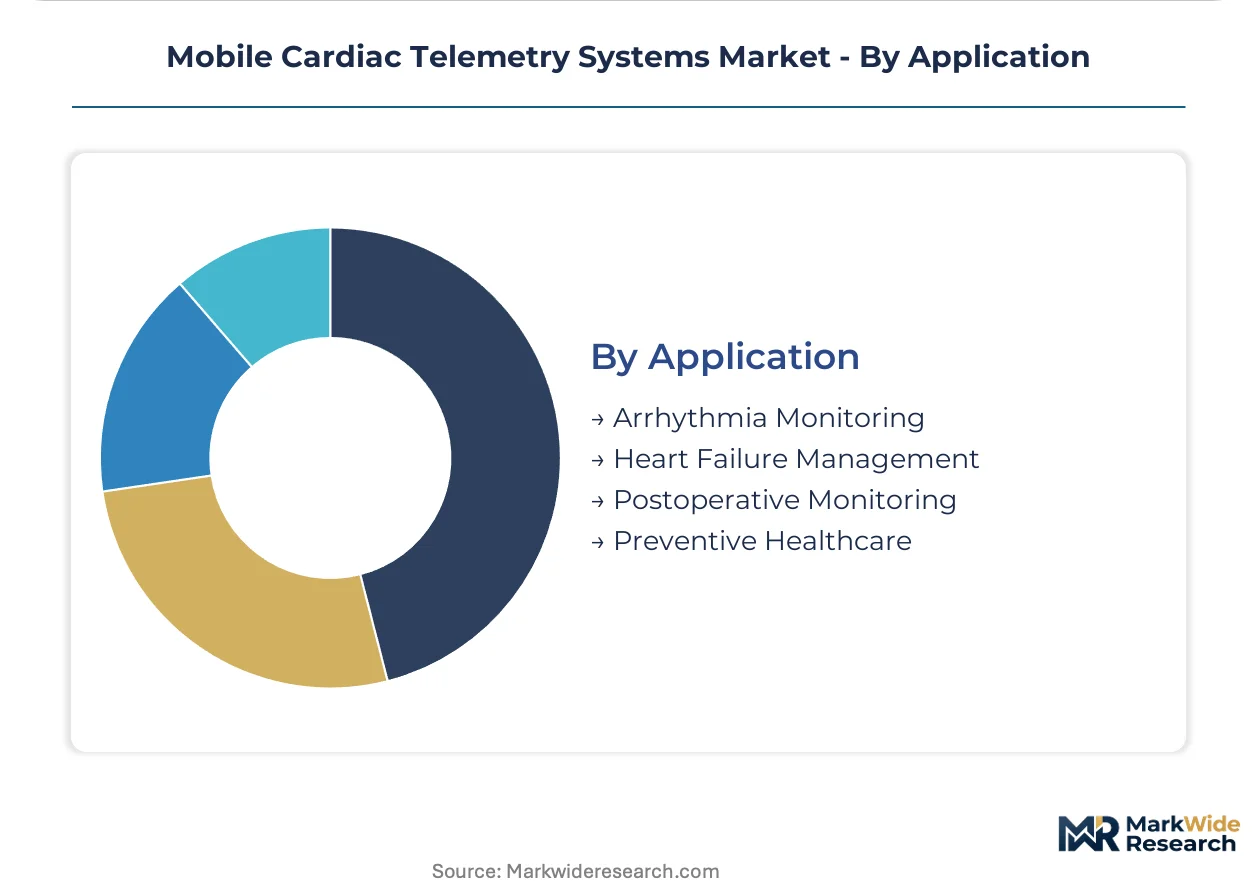
Clinical utility and reimbursement density concentrate in arrhythmia detection, while preventive applications remain nascent pending algorithmic validation for asymptomatic populations.
- Arrhythmia Monitoring:Detection and classification of atrial fibrillation, ventricular tachycardia, and other rhythm disorders through continuous or event-triggered ECG acquisition. FDA breakthrough device designation pathways for AI-enabled detection are shortening premarket review timelines, enabling faster commercialization of automated classification systems in the United States.
- Heart Failure Management:Hemodynamic and rhythm surveillance to guide medication titration and reduce acute decompensation. United States integrated delivery networks are prioritizing these applications under value-based care frameworks that penalize heart failure readmissions, creating concentrated demand for predictive analytics capabilities.
- Postoperative Monitoring:Surveillance following cardiac or major non-cardiac surgery for early complication detection.
- Preventive Healthcare:Screening of asymptomatic at-risk populations for subclinical arrhythmia.
Arrhythmia monitoring absorbs the bulk of clinical utilization; heart failure management is expanding most quickly as value-based contracts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in the United States and tariff-advantaged manufacturing corridors in Southeast Asia concentrate mobile cardiac telemetry production and service delivery.
United States
Medicare reimbursement stabilization and CMS value-based purchasing programs drive hospital system adoption of remote cardiac monitoring. FDA breakthrough device designation pathways compress premarket review timelines for AI-enabled arrhythmia detection. Cardiology practice networks across the southeastern United States consolidate procurement around patch monitor platforms with premium reimbursement positioning.
Germany
EU Medical Device Regulation compliance requirements tighten post-market surveillance obligations for algorithm-based diagnostic systems. Notified body expectations for clinical evidence packages reshape quality management investments. Medical technology clusters in Baden-Württemberg host manufacturers establishing dedicated regulatory affairs functions for software-driven devices.
India
Expanding health insurance coverage and underpenetrated tertiary care networks create white-space demand for cloud-based telemetry platforms. CDSCO medical device registration pathways guide commercialization timelines for foreign entrants. Bangalore and Hyderabad technology corridors attract digital health ventures targeting cardiac monitoring infrastructure gaps.
Japan
PMDA regulatory frameworks govern software-as-a-medical-device classification for algorithm updates without hardware modification. METI initiatives support remote patient monitoring adoption in aging demographics. Tokyo and Osaka metropolitan areas concentrate hospital system procurement authority for integrated telemetry contracts.
United Kingdom
NHS long-term plan commitments to digital-first outpatient services accelerate ambulatory cardiac monitoring deployment. MHRA guidance on AI-enabled medical devices shapes algorithm validation requirements. London and Southeast England cardiology networks pilot predictive analytics platforms for heart failure management.
Mobile Cardiac Telemetry Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated device makers commanding premium positioning in adhesive patch monitors while component suppliers capture value in wearable multi-parameter systems. The market structure concentrates around three to five dominant platforms with established FDA clearances and CMS coverage, supplemented by emerging entrants leveraging polymer substrate innovations. Two strategic archetypes dominate: sensor foundry-integrated manufacturers with captive chip supply, and cloud-native analytics platforms with proprietary algorithm training datasets. Competitive moves center on exclusive cardiology practice network partnerships and 5G-enabled wireless module integration for rural connectivity expansion.
Within the integrated-manufacturing tier, Medtronic plc anchors positioning through upstream control over implantable telemetry component supply. iRhythm Technologies exemplifies the analytics-native archetype with convolutional neural network capabilities trained on extensive patient datasets. BioTelemetry Inc. occupies a position anchored by southeastern United States cardiology network exclusivity. These three represent contrasting strategic bets on hardware integration versus algorithmic differentiation versus channel control.
| Leading Market Players |
|---|
| Medtronic plc |
| iRhythm Technologies |
| BioTelemetry Inc. |
| Boston Scientific Cardiac Diagnostics |
| Zoll Medical Corporation |
| Koninklijke Philips N.V. |
| ScottCare |
| Biotricity Inc. |
| Medicomp Inc. |
| Others |
Supply Flow & Price Mechanics
Polymer flexible substrate costs flow from Southeast Asian chemical processing facilities through three distinct pricing tiers for adhesive patch monitors, with premium positioning commanding shorter lead times from vertically integrated sensor foundries while standard-tier vendors absorb inventory risk from spot-market silicon MEMS procurement.
Pricing Analysis
Lead-time-driven pricing separates premium-tier patch monitors with guaranteed fourteen-day delivery from standard-tier products carrying six-week fulfillment windows. Pricing stratifies across premium, standard, and economy levels based on FDA clearance tier and volume commitment scale. Price erosion runs through economy-tier wearable monitors as Holter monitor substitutes capture budget-constrained health systems. Hospital procurement committees demonstrate lowest price sensitivity due to bundled service contracts, while independent diagnostic laboratories face acute margin pressure from per-test reimbursement compression.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing corridors elevates landed costs for polymer substrate materials destined for United States assembly operations. Supply concentrates in Taiwan for microelectromechanical systems foundry capacity, Malaysia for flexible electronics fabrication, and the United States for final device sterilization and packaging. Raw material dependencies span liquid silicone rubber, conductive silver inks, and lithium-polymer cells. Single-source vulnerability in Taiwan semiconductor foundries threatens production continuity for next-generation 5G wireless modules. Distribution runs through cardiology practice networks under exclusive territorial agreements rather than open-channel medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile cardiac telemetry sits in active technology transition as polymer flexible substrates displace silicon-based microelectromechanical systems in next-generation adhesive patch monitors, compressing unit economics while extending clinically valid wear duration.
For Market Incumbents: Extend algorithmic differentiation through continuous FDA breakthrough device designation pursuit for AI-enabled arrhythmia detection, insulating against cloud-native analytics platforms with proprietary convolutional neural network training datasets. Deepen exclusive cardiology practice network partnerships across the southeastern United States to defend channel control against emerging entrants with 5G-enabled wireless modules. Prioritize backward integration into polymer substrate supply to offset silicon foundry concentration risk.
For New Entrants and Emerging Players: Cardiology practice networks in India's underpenetrated tertiary care corridors offer lowest competitive density for cloud-based telemetry platform deployment. Target post-acute heart failure management applications where predictive analytics capabilities remain nascent among established vendors. Pursue CDSCO registration pathways alongside strategic distribution partnerships with Bangalore and Hyderabad technology corridor digital health ventures.
For Investors and Strategic Acquirers: FDA breakthrough device designation receipt is the leading indicator that algorithm-native platforms will achieve compressed time-to-market versus hardware-centric competitors. Five-to-ten-year viability favors analytics-specialist acquisition targets with multi-million-patient training datasets over capital-intensive sensor foundry operators. Monitor CMS national coverage determination expansions for mobile cardiac telemetry reimbursement codes as the inflection signal for service-provider margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Compresses premarket review timelines for AI-enabled arrhythmia detection algorithms. |
| 5G Low-Latency Wireless Module Integration | Enables real-time streaming in rural broadband-limited geographies previously unserviceable. |
| Exclusive Cardiology Practice Network Partnership | Locks in recurring revenue streams through territorial exclusivity in high-reimbursement regions. |
| Polymer Substrate Supply Integration | Reduces unit manufacturing costs while extending clinically valid wear duration beyond fourteen days. |
| Cloud-Native Algorithm Training Dataset Expansion | Builds proprietary moats in deep-learning arrhythmia classification against hardware-centric competitors. |
Methodological Framework
FDA 510(k) premarket notification filings, CMS national coverage determination documents, and hospital procurement database records formed the secondary backbone of this analysis. Primary interviews with cardiac monitoring center operations directors, biomedical engineers at integrated delivery networks, GPO contracts managers, and regulatory affairs specialists at device manufacturers combined with secondary validation. Bottom-up triangulation across product-type shipment estimates and top-down reconciliation against Medicare reimbursement claims data anchored volume and value outputs.
Historical trendline analysis of patch monitor and wearable monitor adoption trajectories informed growth rate derivation across the projection horizon. Segmentation modeling incorporated hardware form factor, transmission protocol technology, care setting end-user type, and clinical application dimensionality. Forecast inputs included AI-enabled diagnostic algorithm regulatory approval velocity and polymer substrate manufacturing scale-up timelines from Southeast Asian chemical processing facilities.
Caveats apply where FDA software-as-a-medical-device guidance revisions or CMS reimbursement code modifications could materially shift the outlook for algorithm-native platform commercialization. Forecasts reflect assumptions regarding 5G infrastructure deployment pace in rural United States geographies and CDSCO medical device registration pathway efficiency for India market entry. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Smart Stethoscopes Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Global Extra Corporeal Membrane Oxygenation (ECMO) System Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market