
 Intracardiac Imaging Market | 2026-2036
Intracardiac Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Intracardiac Imaging Market Foresight
Germany is narrowing its catheter manufacturing capacity gap through targeted facility upgrades in the Rhine-Main cluster. Boston Scientific Corporation leverages in-house transducer production to secure supply continuity across European channels. Siemens Healthineers anchors its position through deep integration with university hospital networks. Abbott Laboratories differentiates via specialized ICE catheter portfolios for complex ablation workflows.
Intracardiac imaging denotes real-time ultrasound-based visualization of cardiac structures from within the heart chambers, typically employing phased-array transducers operating at 5-10 MHz frequencies to guide electrophysiology and structural interventions. Electrophysiology systems command the largest installed base among product types, though 4D imaging technology captures the fastest upgrade cycle as clinics pursue volumetric data for procedural precision. Hospitals represent the dominant end-user channel by capital commitment, while outpatient centers emerge as a volume growth segment driven by same-day discharge protocols.
FDA 510(k) pathways govern device clearance timelines in the United States, while EU MDR technical documentation requirements extend certification cycles for catheter-based imaging systems. The EU AI Act introduces conformity obligations for algorithm-assisted diagnostic outputs, pressuring vendors to revalidate software modules. Stakeholders must monitor regulatory divergence between FDA and EMA guidance on real-time AI integration during catheter-based procedures.
Market Dynamics
The convergence of 4D volumetric imaging with AI-assisted procedural guidance is compressing upgrade cycles across electrophysiology suites, forcing capital equipment vendors to revalidate software modules under divergent FDA and EU AI Act pathways simultaneously.
Growth Catalysts
- Structural heart procedure volume:Transcatheter valve replacements and left atrial appendage closures in United States hospitals are driving catheter lab retrofit investments. Academic medical centers prioritize same-room imaging upgrades to capture complex case referrals.
- EU MDR compliance deadlines:German cardiology clinics accelerated electrophysiology system procurement ahead of technical documentation requirements. Certification cycle extensions created advance-ordering behavior among Rhine-Main cluster facilities.
- Phased-array transducer miniaturization:Smaller catheter footprints enable pediatric and tortuous anatomy applications previously excluded from intracardiac imaging. Manufacturers report expanded addressable procedure categories.
Market Restraints
- Transducer crystal supply concentration:Piezoelectric material processing capacity clusters in East Asian specialized foundries. Disruption risk elevates raw input cost volatility for catheter manufacturers.
- EU MDR technical documentation burden:Extended certification cycles for catheter-based imaging systems delay new product introductions. Smaller vendors face disproportionate compliance resource strain.
- Substitute visualization modalities:Intracardiac echocardiography competes with transesophageal echo and rotational angiography in specific structural heart procedures. Price-sensitive outpatient centers favor lower-capital alternatives.
Strategic Opportunities
- Outpatient center channel expansion:Same-day discharge protocols in United States ambulatory surgical centers create volume growth potential. Capital-light system configurations address space-constrained environments.
- AI algorithm regulatory tailwind:FDA breakthrough device designation pathways for real-time arrhythmia mapping algorithms accelerate commercialization timelines. Vendors with pre-submission engagement capture first-mover positioning.
- Convergence of ICE with robotic navigation:Integrated catheter positioning and imaging workflows reduce operator radiation exposure. Hybrid system architectures command premium pricing in high-volume electrophysiology programs.
Industry Challenges
- Electrophysiologist training pipeline constraints:Complex ablation procedure growth outpaces fellowship graduation rates. Extended learning curves for 4D imaging interpretation delay technology adoption curves.
- Legacy system integration complexity:Hospital information technology departments struggle with DICOM connectivity between proprietary catheter interfaces and existing PACS infrastructure. Custom middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracardiac Imaging Market |
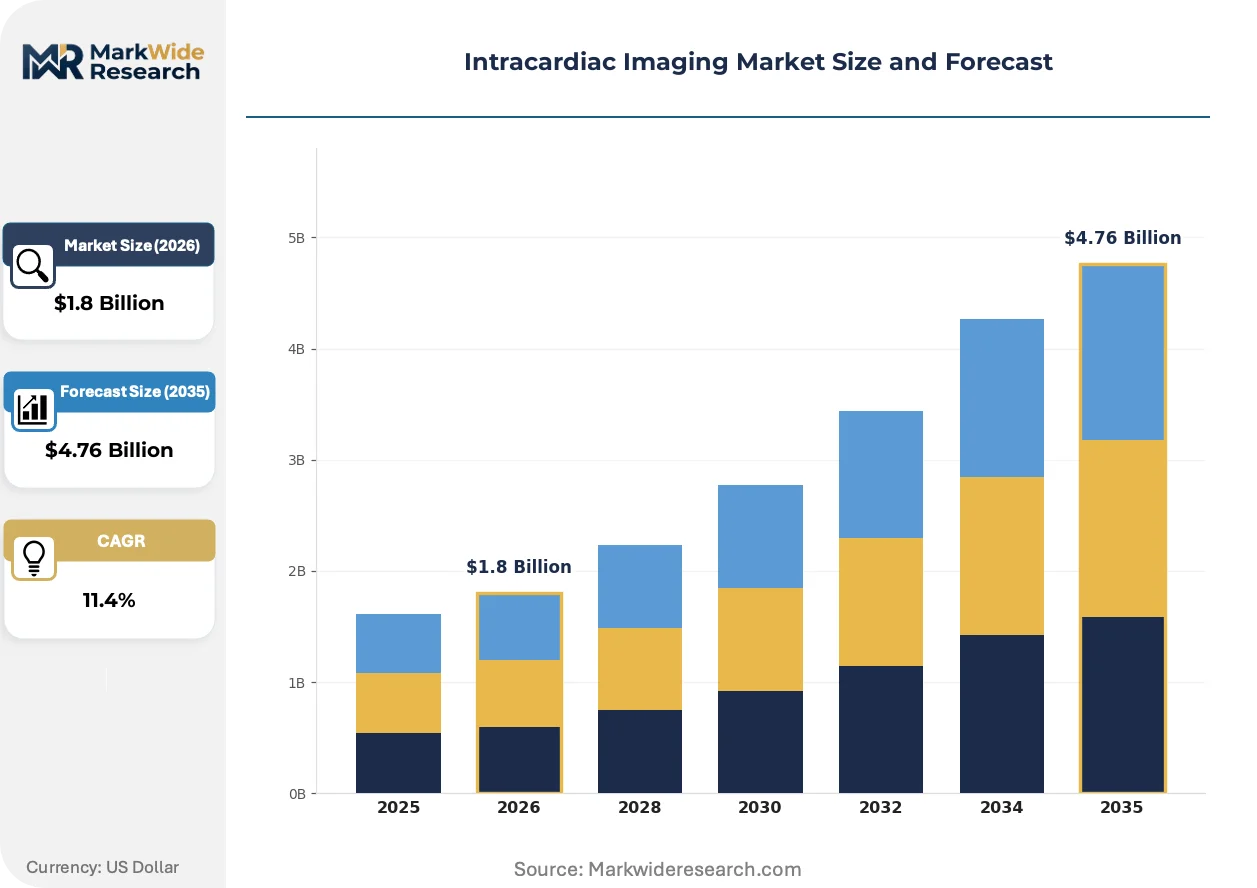
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, CT Scanners, MRI Machines, Electrophysiology Systems End User: Cardiology Clinics, Hospitals, Research Institutions, Outpatient Centers Technology: 3D Imaging, 4D Imaging, Telemedicine, Advanced Robotics Application: Cardiac Monitoring, Arrhythmia Management, Structural Heart Procedures, Myocardial Imaging |
| Companies Covered | Boston Scientific Corporation, Siemens Healthineers, GE Healthcare, Koninklijke Philips, Abbott Laboratories, Medtronic, Johnson & Johnson MedTech, Canon Medical Systems, Stereotaxis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracardiac Imaging Market Shifts & Advancements
Real-time volumetric rendering and machine learning inference at the point of care are redefining procedural workflow economics, compressing the gap between diagnostic imaging and interventional execution.
4D intracardiac echocardiography is hybridizing electrophysiology and structural heart workflows into unified catheter lab platforms. High-volume United States academic centers are consolidating separate ICE and TEE capabilities into single-vendor ecosystems. This convergence is compressing capital budgeting cycles as hospitals defer standalone purchases pending integrated system availability.
The EU AI Act introduces conformity obligations for algorithm-assisted diagnostic outputs that extend beyond traditional CE marking requirements. Vendors must revalidate software modules under new risk-classification frameworks. European electrophysiology system procurement is slowing as hospital legal departments assess liability exposure from real-time AI integration during catheter-based procedures.
Electrophysiology service line directors are unbundling capital acquisition from consumable supply agreements, reversing decade-old bundled contracting norms. United States hospital purchasing committees now separate imaging system decisions from catheter volume commitments. This disintermediation is elevating total cost-of-ownership analysis and extending sales cycle duration for premium-tier vendors.
Intracardiac Imaging Market Segmentation
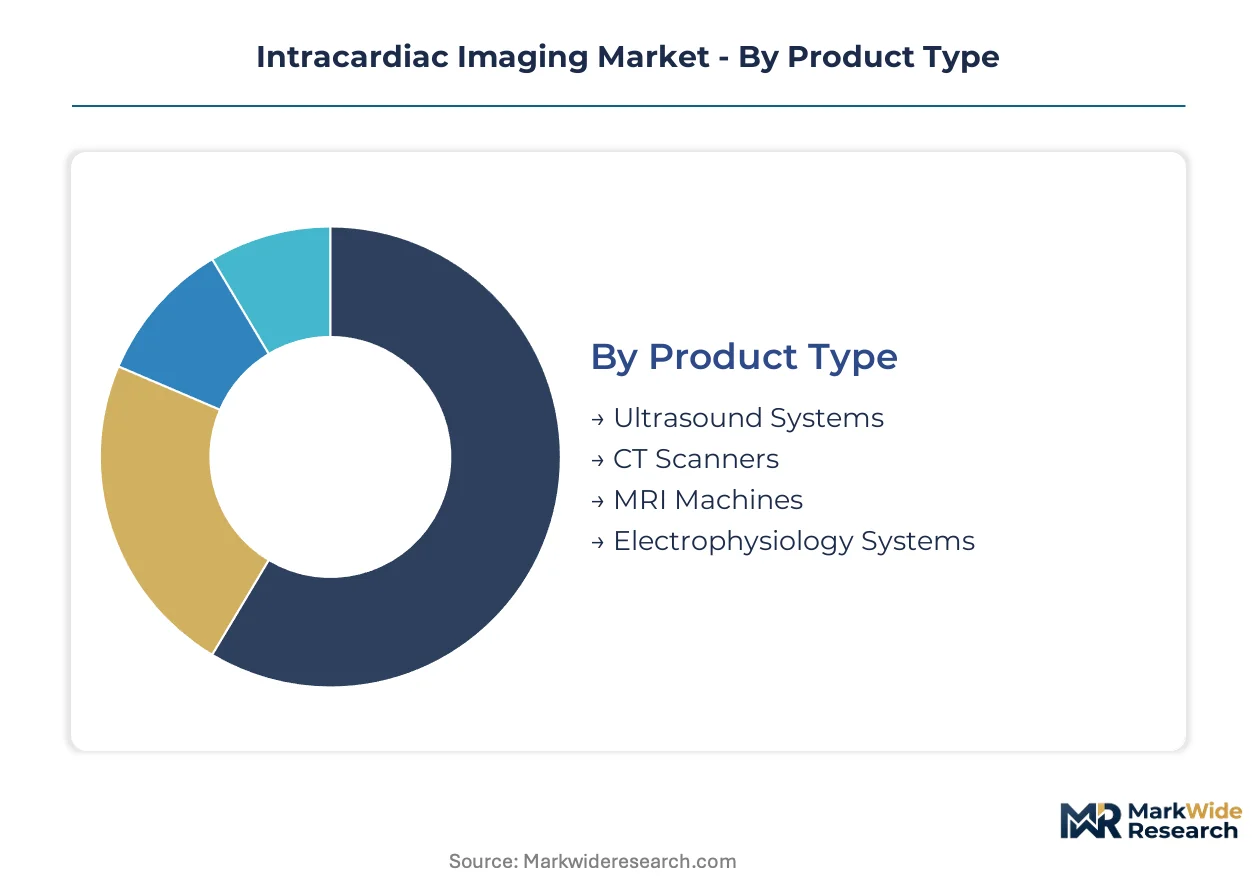
Intracardiac imaging segmentation reveals distinct procurement patterns across product tiers and care settings. Technology differentiation and reimbursement pathways create divergent growth velocities within each category.
Product Type:
Use-case spectrum spans diagnostic confirmation through interventional guidance, with capital intensity varying by procedural integration depth.
- Electrophysiology Systems:Integrated platforms combining mapping navigation with real-time ICE visualization command premium positioning in academic medical centers. United States hospitals prioritize same-room upgrades to capture complex ablation referrals. Phased-array transducer miniaturization expands pediatric applicability.
- Ultrasound Systems:Standalone intracardiac echocardiography consoles serve structural heart programs requiring flexible catheter positioning. German cardiology clinics accelerated procurement ahead of EU MDR deadlines. Portable configurations address space-constrained outpatient environments.
- CT Scanners:Pre-procedural anatomical planning systems support transcatheter valve sizing workflows.
- MRI Machines:Magnetic resonance platforms enable myocardial tissue characterization prior to ablation.
The dominant share belongs to Electrophysiology Systems, while Ultrasound Systems is closing the gap fastest.
End User:
Procurement authority concentrates where capital commitment aligns with procedure volume and reimbursement scale.
- Hospitals:Academic medical centers drive system upgrade cycles through bundled service line investments. United States hospital purchasing committees now separate imaging decisions from catheter supply agreements. Deferred standalone purchases await integrated platform availability.
- Outpatient Centers:Ambulatory surgical centers adopt capital-light configurations under same-day discharge protocols. Space constraints favor compact system footprints with simplified DICOM connectivity.
- Cardiology Clinics:Rhine-Main cluster facilities in Germany demonstrate advance-ordering behavior around regulatory deadlines.
- Research Institutions:University hospital networks anchor vendor ecosystem partnerships for algorithm development.
Hospitals retain procurement leadership, though Outpatient Centers is expanding most quickly.
Technology:
Imaging modality maturity creates tiered upgrade cycles from established volumetric capture through emerging automation layers.
- 4D Imaging:Real-time volumetric rendering compresses diagnostic-interventional workflow gaps. High-volume electrophysiology programs consolidate ICE and TEE capabilities into single-vendor ecosystems. FDA breakthrough device pathways accelerate algorithm-assisted mapping commercialization.
- 3D Imaging:Established volumetric platforms serve baseline structural heart guidance with lower capital thresholds.
- Advanced Robotics:Integrated catheter positioning and imaging architectures command premium pricing in radiation-exposure-sensitive workflows.
- Telemedicine:Remote procedural oversight capabilities extend specialist reach to underserved geographies.
4D Imaging holds technology leadership, while Advanced Robotics is gaining share fastest.
Application:
Clinical indication breadth determines addressable procedure population and corresponding system utilization rates.
- Structural Heart Procedures:Transcatheter valve replacements and left atrial appendage closures drive catheter lab retrofit investments. United States hospital capital expenditure concentrates here. Same-room imaging upgrades capture complex case referrals.
- Arrhythmia Management:Complex ablation growth outpaces electrophysiologist training pipeline capacity. Extended 4D interpretation learning curves delay technology adoption curves.
- Cardiac Monitoring:Continuous hemodynamic assessment applications support critical care integration.
- Myocardial Imaging:Tissue characterization workflows enable targeted ablation strategies.
Structural Heart Procedures commands the dominant share, while Arrhythmia Management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States hospitals prioritize capital-intensive integrated platforms for structural heart workflows, while German clinics emphasize regulatory-compliant electrophysiology procurement, and Asian markets pursue cost-optimized configurations for volume expansion.
United States
Academic medical centers drive catheter lab retrofit investments for transcatheter valve replacements and left atrial appendage closures. FDA 510(k) pathways govern clearance timelines for catheter-based imaging systems. Hospital purchasing committees in major metropolitan clusters now separate imaging system decisions from catheter supply agreements, extending sales cycles.
Germany
Cardiology clinics in the Rhine-Main cluster accelerated electrophysiology system procurement ahead of EU MDR technical documentation deadlines. Certification cycle extensions created advance-ordering behavior among facilities. Bavarian university hospital networks anchor vendor ecosystem partnerships for algorithm development and clinical validation.
Japan
PMDA consultation procedures shape commercialization timelines for phased-array transducer miniaturization technologies. Aging demographics expand structural heart procedure volumes requiring real-time intracardiac guidance. Kansai-region medical device manufacturers concentrate piezoelectric material processing capabilities for regional supply security.
China
NMPA innovation approval pathways accelerate market entry for domestic catheter manufacturers. Provincial hospital procurement reforms favor same-room imaging upgrades that consolidate multiple capabilities. Yangtze River Delta medical technology clusters expand electrophysiology suite installations to capture rising arrhythmia procedure demand.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement eligibility for complex ablation procedures using 4D intracardiac echocardiography. London-based academic centers prioritize integrated platforms that hybridize electrophysiology and structural heart workflows. Midlands hospital networks evaluate capital-light configurations for outpatient center expansion.
Intracardiac Imaging Market Competitive Landscape
Capability concentration sits with specialized catheter technology developers; scale advantage sits with diversified medical technology conglomerates. The market structure exhibits tiered consolidation around transducer manufacturing control and software algorithm differentiation. Three archetypes dominate: integrated platform vendors with captive supply chains, imaging modality specialists leveraging ultrasound expertise, and electrophysiology-focused players with navigation system synergies. Dominant competitive moves include backward integration into piezoelectric material processing and strategic partnerships with university hospital networks for clinical validation.
Among diversified medical technology conglomerates, Boston Scientific Corporation, Siemens Healthineers, and Abbott Laboratories exemplify distinct strategic positioning within the intracardiac imaging ecosystem. Boston Scientific Corporation occupies a position emphasizing in-house transducer production capabilities. Siemens Healthineers represents the integrated diagnostics-to-intervention platform archetype through deep university hospital network integration. Abbott Laboratories exemplifies specialization via dedicated intracardiac echocardiography catheter portfolios designed for complex ablation workflows.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Abbott Laboratories |
| Medtronic |
| Johnson & Johnson MedTech |
| Canon Medical Systems |
| Stereotaxis |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam container freight corridors transmit East Asian piezoelectric crystal cost volatility directly into catheter manufacturer procurement budgets, concentrating pricing power among vendors with captive transducer production while forcing tiered differentiation across integrated platforms, standalone consoles, and portable configurations.
Pricing Analysis
United States academic medical centers pay 40-60% premiums over German cardiology clinics for equivalent electrophysiology system configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated 4D platforms from standalone ultrasound consoles and capital-light outpatient configurations. Pricing pressure stems from outpatient center procurement committees favoring transesophageal echo alternatives for structural heart guidance. Hospital purchasing committees demonstrate lowest price sensitivity; ambulatory surgical centers exhibit highest.
Supply Chain Analysis
Specialized foundries in Japan, South Korea, and China hold concentrated capacity for phased-array transducer crystal processing. Catheter manufacturing draws from piezoelectric ceramics, precision polymer extrusions, and semiconductor components for signal processing. Single-source vulnerability elevates disruption risk for miniaturized transducer supply. Distribution runs through direct vendor-hospital contracting with GPO intermediation for high-volume catheter consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intracardiac echocardiography incumbents face sustained substitution pressure from transesophageal echo and rotational angiography modalities that capture price-sensitive structural heart procedures without equivalent capital commitment.
For Market Incumbents: Harden supply continuity through backward integration into piezoelectric material processing or exclusive offtake agreements with East Asian foundries. Deepen algorithm validation partnerships with FDA breakthrough device pathways to preempt AI-assisted mapping entrants. Lock hospital purchasing committees into integrated platform ecosystems before unbundled procurement norms fully mature. For New Entrants and Emerging Players: Outpatient center channel expansion in United States ambulatory surgical centers represents the most penetrable entry point, where space-constrained environments favor compact system footprints and simplified DICOM connectivity. Capital-light configurations with subscription-based software tiers bypass incumbent bundled contracting advantages. Target same-day discharge protocol adoption curves to time market entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core catheter imaging assets amid portfolio rationalization pressures. Five-to-ten year viability hinges on 4D volumetric platform consolidation and AI algorithm regulatory capture. Monitor FDA breakthrough device designation velocity for real-time arrhythmia mapping as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerated certification cycles restore German clinic procurement momentum ahead of compliance deadlines. |
| FDA 510(k) AI Algorithm Pre-Submission | Breakthrough device designation compresses commercialization timelines for real-time mapping software. |
| University Hospital Network Partnership | Bavarian and Kansai-region academic centers anchor clinical validation ecosystems for algorithm development. |
| Transducer Foundry Capacity Reservation | Exclusive East Asian crystal processing offtake secures supply continuity against single-source disruption. |
| Outpatient Center Channel Configuration | Compact system architectures with simplified DICOM connectivity capture ambulatory surgical center volume. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records preceded structured interviews with electrophysiology service line directors, biomedical engineers, catheter lab managers, and GPO contracts specialists. Secondary validation drew from SEC 10-K segment disclosures, CMS Medicare procedure volume data, and trade customs records for phased-array transducer components. Bottom-up procedure volume modeling and top-down capital equipment expenditure analysis were triangulated against vendor-reported installed base figures.
Assumptions held structural heart procedure volume growth and EU MDR compliance deadline timing fixed across the analysis window, while AI algorithm regulatory pathway velocity and transducer crystal supply availability were treated as sensitivity variables. Segmentation dimensions modeled included product type, end-user channel, technology tier, and application indication. CAGRs were derived from log-linear trend fitting to historical capital expenditure patterns and forward-procedure volume projections. Forecast inputs incorporated electrophysiologist fellowship graduation rates and same-day discharge protocol adoption curves.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device reimbursement rates, or East Asian trade logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and supply chain configuration stability. Quarterly review of FDA breakthrough device designation announcements, EU MDR certification completion rates, and Rhine-Main cluster procurement data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Cardiac Rhythm Management Market
Cardiology Equipment
Mobile Cardiac Telemetry Systems Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Rheumatic-Heart Disease Management Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Smart Electronic Stethoscopes Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market