
 Isopropyl Acetate Market | 2026-2036
Isopropyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Isopropyl Acetate Market Foresight
Pharmaceutical formulation demand is restructuring the isopropyl acetate market as drug manufacturers prioritize high-purity solvents for active ingredient synthesis. Dow Inc. leverages its integrated propylene feedstock chain to secure cost-advantaged supply for North American pharmaceutical customers. BASF SE anchors European demand through REACH-certified production networks that serve coating and adhesive compounders. Seqens Group specializes in pharma-grade fractional distillation, competing on batch consistency and regulatory documentation.
Isopropyl acetate is an ester solvent produced through the esterification of acetic acid with isopropyl alcohol, typically achieving purity grades above 99% with boiling points near 89 degrees Celsius for controlled evaporation in coating applications. The solvent segment dominates volume consumption across paints and coatings applications where fast-dry properties reduce process cycle times. Coating-grade material commands premium positioning in automotive refinish and electronics cleaning end uses where residue specifications are stringent. Intermediate applications for pharmaceutical synthesis represent the fastest-expanding margin pool as batch traceability requirements intensify.
EPA NESHAP standards and REACH registration obligations in Europe compel producers to maintain exhaustive substance documentation and emission control investments. China's MEE enforces VOC discharge limits that favor closed-loop solvent recovery systems in manufacturing zones. FDA oversight of pharmaceutical excipients extends purity validation burdens to suppliers serving drug manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where compliance costs increasingly determine market access eligibility.
Market Dynamics
Pharmaceutical-grade solvent specifications are compressing supply eligibility as batch traceability requirements displace commodity-grade producers from high-margin synthesis applications. REACH registration costs and EPA emission controls are simultaneously raising fixed-cost thresholds for market participation.
Growth Catalysts
- Coating formulation demand:Automotive refinish and electronics cleaning applications require residue-free fast-evaporation solvents. China's Jiangsu and Zhejiang manufacturing clusters are scaling dedicated isopropyl acetate consumption for these precision end uses.
- REACH-certified supply chains:European coating compounders now mandate substance documentation from registered producers. This regulatory pull is consolidating procurement toward ECHA-registered fractional distillation specialists.
- Closed-loop recovery systems:MEE-enforced VOC discharge limits in China's chemical parks favor solvent recyclers with integrated purification. These installations extend effective supply capacity without greenfield production investment.
Market Restraints
- Propylene feedstock volatility:Isopropyl alcohol pricing swings directly transmit to ester production economics. North American producers with captive propylene supply maintain cost insulation unavailable to merchant buyers.
- Acetic acid supply concentration:Three integrated petrochemical complexes control over half of merchant acetic acid volumes. This upstream tightness constrains independent ester producers during turnaround seasons.
- Aqueous cleaning substitution:Semiconductor and precision optics manufacturers are qualifying water-based surfactant systems for legacy solvent degreasing. These formulations eliminate VOC reporting burdens but sacrifice drying speed.
Strategic Opportunities
- Pharmaceutical excipient certification:FDA Type II Drug Master File submission creates defensible positioning for synthesis-grade suppliers. This documentation barrier protects margin pools from commodity competitors.
- Bio-based acetic acid integration:Fermentation-derived acetic acid from agricultural waste streams offers Scope 3 emissions reduction. Early movers in bio-ester production capture sustainability premiums from European formulators.
- Southeast Asia coating expansion:Vietnam and Indonesia automotive assembly growth is outpainting domestic solvent supply. Import substitution opportunities exist for regional fractional distillation investments.
Industry Challenges
- Pharma-grade analytical capability gaps:Batch-specific impurity profiling to parts-per-billion thresholds requires gas chromatography-mass spectrometry investment. Mid-scale producers face six-figure capital decisions to retain pharmaceutical customer eligibility.
- Multi-jurisdiction registration synchronization:Maintaining concurrent REACH, EPA TSCA, and China IECSC substance inventories demands dedicated regulatory affairs staffing. Documentation drift between filings creates shipment holds at customs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isopropyl Acetate Market |
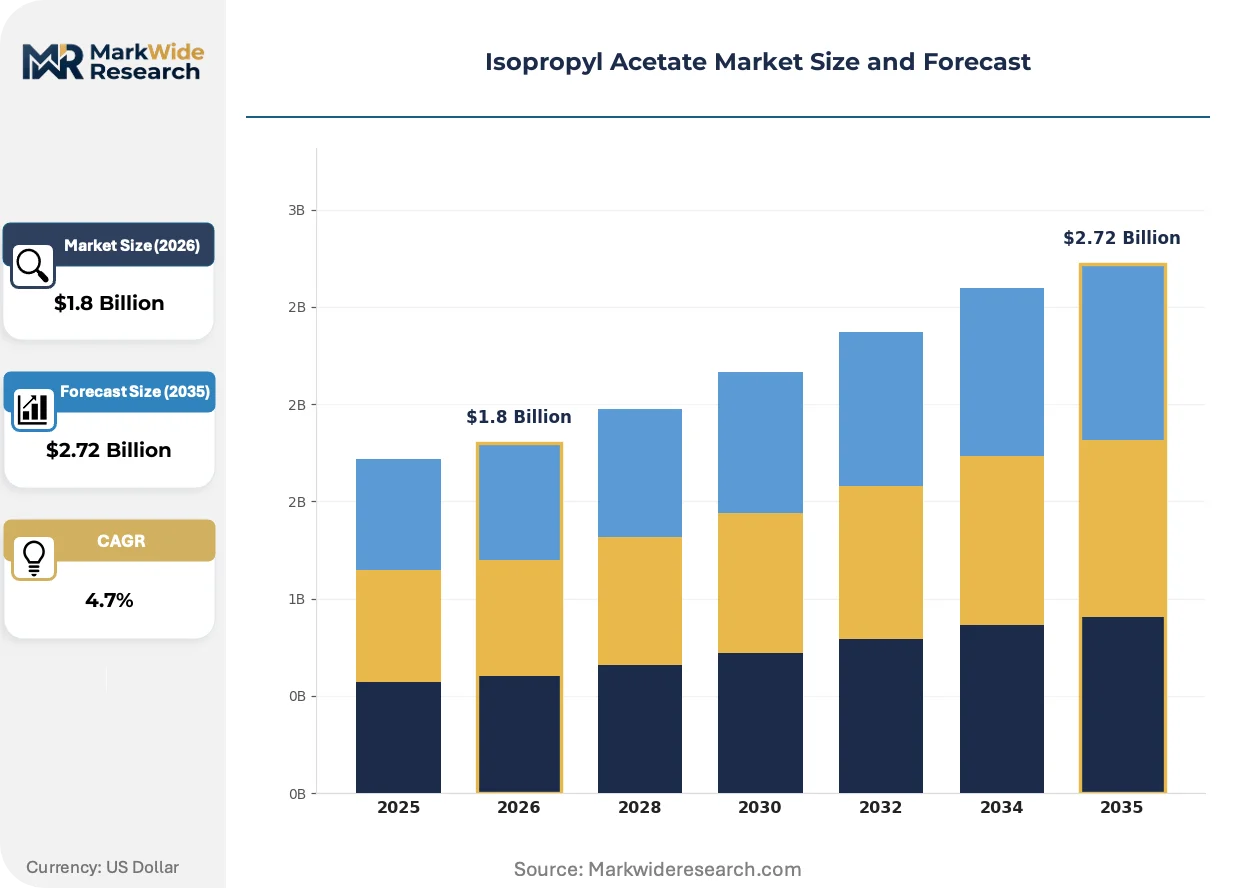
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Coating, Adjuvant, Intermediate Application: Paints, Coatings, Adhesives, Inks End User: Automotive, Pharmaceuticals, Food & Beverage, Electronics Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Dow Inc., Eastman Chemical Company, BASF SE, INEOS Group, Solvay S.A., Mitsubishi Chemical Corporation, Seqens Group, ExxonMobil Chemical, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isopropyl Acetate Market Shifts & Advancements
Digital batch tracking and predictive purity analytics are reconfiguring how solvent specifications are verified and transmitted through coating and pharmaceutical supply chains. These capabilities are compressing quality assurance cycles while raising documentation expectations.
Membrane separation technology is integrating into fractional distillation trains for final-stage moisture and trace impurity removal. Pharmaceutical manufacturers in Germany and Switzerland are specifying membrane-polished material for active ingredient crystallization. This purification step is integrating real-time conductivity monitoring that eliminates offline laboratory confirmation delays.
EPA NESHAP Subpart HHHH is tightening emission factors for miscellaneous organic chemical manufacturing. Surface coating operations in the US Midwest are retrofitting carbon adsorption systems to capture fugitive isopropyl acetate losses. The regulation is forcing automotive refinish shops toward enclosed spray booths with solvent recovery, accelerating equipment replacement cycles.
Consolidated distributor networks are displacing direct mill relationships for mid-volume coating compounders. Regional chemical distributors in China's Pearl River Delta now stock pharmaceutical-grade material with certificate-of-analysis documentation. This channel shift is most visible among electronics contract manufacturers sourcing small-lot high-purity solvents without long-term supply agreements.
Isopropyl Acetate Market Segmentation
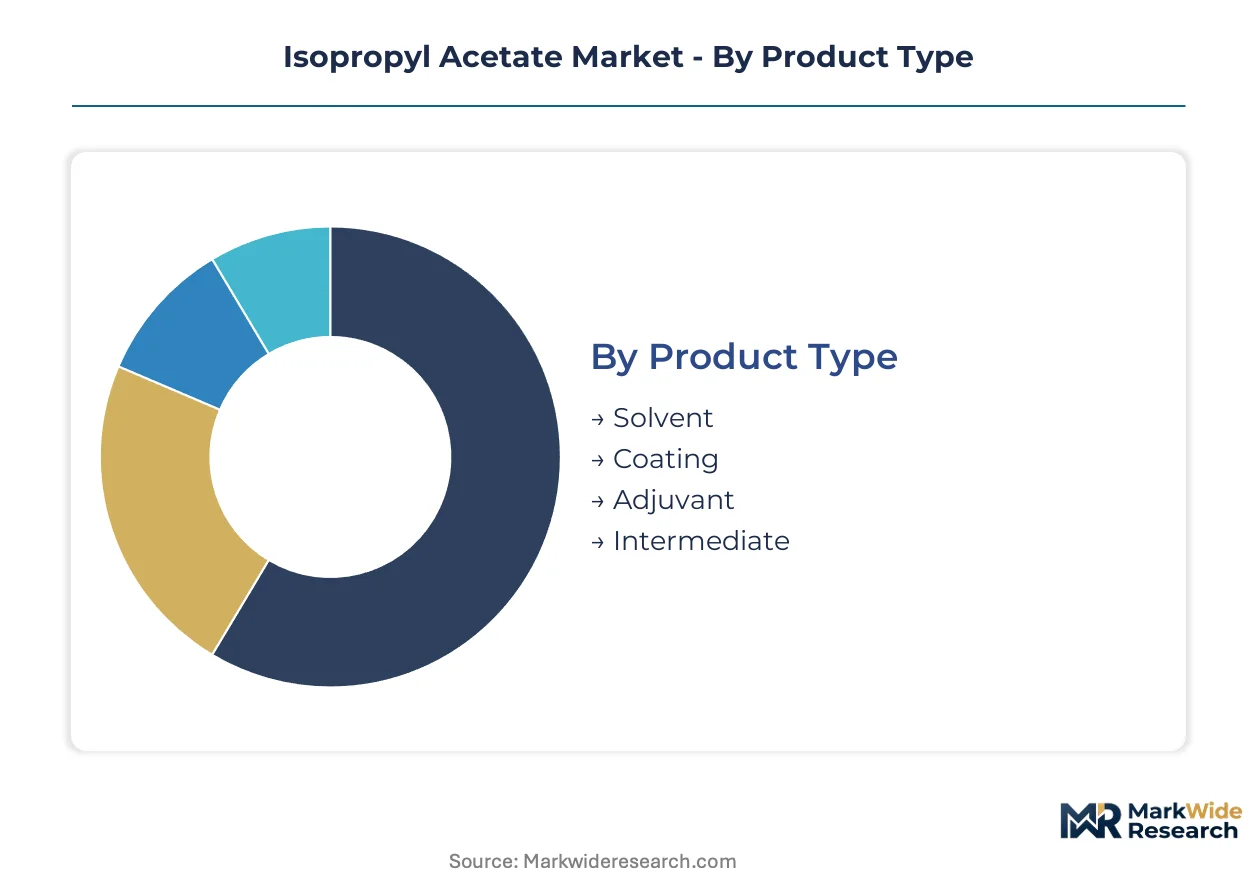
Isopropyl acetate specifications diverge sharply across end-use requirements, with pharmaceutical synthesis demanding parts-per-billion impurity thresholds while coating applications prioritize controlled evaporation rates. Procurement patterns track these technical boundaries, creating distinct margin pools that reshape competitive positioning.
Product Type:
Customization intensity spans from commodity solvent grades to certificate-backed pharmaceutical intermediates, with regulatory documentation burden increasing steeply across this spectrum.
- Solvent:Technical grades above 99% purity serve industrial degreasing and general formulation. Demand concentrates in China's Jiangsu province where electronics contract manufacturers specify fast-dry properties for printed circuit board cleaning. EPA NESHAP emission factors are pushing Midwest US metal fabricators toward enclosed vapor degreasing systems.
- Intermediate:Synthesis-grade material undergoes fractional distillation with batch-specific impurity profiling to serve active ingredient crystallization. German and Swiss pharmaceutical manufacturers specify membrane-polished material with real-time conductivity verification. FDA Type II Drug Master File documentation creates procurement stickiness that protects margin pools from commodity competitors.
- Coating:Automotive refinish applications require residue-free evaporation for clear-coat compatibility. BASF SE anchors European supply through REACH-certified production networks.
- Adjuvant:Food-grade specifications meet FSSAI purity benchmarks for flavor carrier applications in India. BIS certification requirements filter supplier eligibility.
Most installed capacity flows through Solvent. Expansion is steepest in Intermediate.
Application:
Volume scale inversely correlates with purity premium, with architectural paints consuming bulk tonnage while specialty electronics coatings command price multiples.
- Paints:Architectural and industrial formulations consume standard-grade material for viscosity reduction and flow control. China's coastal chemical provinces scale dedicated consumption as construction activity drives coating production.
- Coatings:Automotive refinish and electronics applications specify ultra-low residue grades. Zhejiang manufacturing clusters source certificate-of-analysis documented material for precision end uses where contamination voids warranty coverage.
- Adhesives:Pressure-sensitive and structural bonding formulations leverage fast-tack properties. REACH registration obligations compel European compounders toward ECHA-registered suppliers exclusively.
- Inks:Gravure and flexographic printing applications balance drying speed with substrate compatibility. Southeast Asia packaging expansion is outpacing regional solvent supply.
Paints absorbs the largest volume share. Coatings climbs fastest on electronics demand.
End User:
Regulatory oversight intensity segments this category, with pharmaceutical and food applications subject to excipient validation burdens absent from industrial uses.
- Pharmaceuticals:Active ingredient synthesis and excipient applications require exhaustive batch traceability. Seqens Group specializes in pharma-grade fractional distillation, competing on regulatory documentation depth. CDSCO oversight in India extends purity validation requirements to imported material.
- Electronics:Semiconductor and display manufacturing specify ultra-high purity for cleaning and photoresist stripping. Water-based surfactant substitution is qualifying in precision optics, eliminating VOC reporting but sacrificing drying speed.
- Automotive:OEM and refinish coatings drive fast-evaporation solvent consumption. Enclosed spray booth mandates under EPA NESHAP Subpart HHHH accelerate equipment replacement cycles.
- Food & Beverage:Flavor extraction and carrier applications meet stringent migration limits. FSSAI enforcement of residual solvent standards filters supplier pools in India.
Automotive commands the deepest volume. Pharmaceuticals expands most quickly on synthesis-grade premiums.
Distribution Channel:
Customer scale and documentation requirements determine channel selection, with bulk consumers maintaining direct mill relationships while fragmented buyers consolidate through intermediaries.
- Distributors:Regional chemical distributors in China's Pearl River Delta now stock pharmaceutical-grade material with certificate-of-analysis documentation. This channel shift serves electronics contract manufacturers sourcing small-lot high-purity solvents without long-term supply agreements.
- Direct Sales:Volume coating compounders and pharmaceutical manufacturers negotiate frame contracts with registered producers. Dow Inc. leverages integrated propylene feedstock chains to secure cost-advantaged supply for North American pharmaceutical customers.
- E-commerce:Laboratory-scale and pilot-plant quantities move through specialized chemical marketplaces with digital batch tracking. Real-time inventory visibility compresses procurement cycles for R&D facilities.
- Retail:Consumer-grade solvent blends for DIY and maintenance applications carry minimal regulatory documentation. This channel captures residual demand from non-industrial users.
Distributors intermediate the largest transaction volume. Direct Sales captures the steepest margin expansion on pharma-grade contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting isopropyl acetate production toward jurisdictions with manageable compliance costs. Producers in China and India capture coating-grade volume as REACH-registered European suppliers withdraw from commoditized segments. This geographic sorting intensifies as pharmaceutical-grade premiums justify documentation investments in Germany and Switzerland.
China
Coating and adhesive production in Jiangsu and Zhejiang provinces drives concentrated solvent consumption. MEE-enforced VOC discharge limits favor closed-loop recovery systems in designated chemical parks. The Yangtze River Delta hosts expanding fractional distillation capacity serving electronics contract manufacturers.
United States
Pharmaceutical synthesis demand anchors high-purity procurement from integrated propylene producers. EPA NESHAP Subpart HHHH tightens emission factors for surface coating operations. Midwest automotive refinish shops retrofit carbon adsorption systems to capture fugitive solvent losses.
Germany
REACH-certified supply chains consolidate procurement toward ECHA-registered fractional distillation specialists. BASF SE anchors European coating compounder relationships through documented substance inventories. The Rhine-Ruhr chemical corridor maintains pharma-grade analytical capabilities for batch-specific impurity profiling.
India
Food-grade adjuvant applications expand under FSSAI enforcement of residual solvent standards. CDSCO oversight extends purity validation requirements to imported pharmaceutical excipients. Gujarat's chemical manufacturing zones scale technical-grade production for regional coating formulators.
Switzerland
Pharmaceutical manufacturers specify membrane-polished material for active ingredient crystallization. Swissmedic oversight maintains exhaustive batch traceability requirements for synthesis-grade suppliers. Basel's pharmaceutical cluster drives premium positioning for certificate-backed intermediates.
Isopropyl Acetate Market Competitive Landscape
Capacity expansion dominates the current landscape as producers add fractional distillation trains to capture pharmaceutical-grade premiums. The market structures around three tiers: integrated petrochemical majors with captive feedstock, regional fractional distillation specialists with regulatory certifications, and merchant compounders serving coating formulators. Strategic archetypes include REACH-registered documentation leaders, propylene-backward integrated producers, and membrane-polishing technology adopters. Competitive moves concentrate on M&A for regulatory asset accumulation and geographic expansion into Southeast Asian coating markets.
Among integrated chemical majors, Dow Inc. and BASF SE exemplify divergent geographic anchoring strategies. Dow leverages North American propylene integration to serve pharmaceutical customers with cost-advantaged supply. BASF occupies a position as the documentation-heavy European anchor through REACH-certified production networks. Seqens Group represents the specialist archetype, competing as a fractional distillation pure-play with pharma-grade batch consistency capabilities.
| Leading Market Players |
|---|
| Dow Inc. |
| Eastman Chemical Company |
| BASF SE |
| INEOS Group |
| Solvay S.A. |
| Mitsubishi Chemical Corporation |
| Seqens Group |
| ExxonMobil Chemical |
| Huntsman Corporation |
| Others |
Supply & Pricing Matrix
Captive propylene integration at Dow Inc. and ExxonMobil Chemical anchors both supply security and pricing power across North American pharmaceutical-grade supply. This upstream control buffers integrated producers from feedstock volatility that compresses margins at merchant ester compounders serving coating formulators.
Pricing Analysis
Distributor margins of 8-12 percent separate bulk pharmaceutical contracts from spot coating-grade transactions. Three-tier pricing structure across pharmaceutical synthesis, precision coating, and technical solvent grades reflects certification burden and batch documentation depth. Cost compression in commodity solvent tiers is intensifying because Jiangsu province capacity additions outpace regional demand growth. Electronics contract manufacturers sourcing through Pearl River Delta distributors exhibit highest price sensitivity; FDA-registered pharmaceutical customers show lowest sensitivity due to excipient validation switching costs.
Supply Chain Analysis
Isopropyl acetate supply rests on concentrated acetic acid production in the United States, China, and Germany where integrated petrochemical complexes control merchant volumes. Propylene feedstock draws from regional steam cracker and refinery operations; isopropyl alcohol availability hinges on acetone hydrogenation economics. Single-source vulnerability runs through acetic acid supply during petrochemical complex turnaround seasons. Distribution runs through direct mill relationships for pharmaceutical and automotive OEM volumes, with regional distributors capturing fragmented electronics and maintenance chemical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isopropyl acetate functions as a stable compounder where pharmaceutical synthesis-grade premiums compound steadily against coating-grade commoditization pressures.
For Market Incumbents: To counter aqueous cleaning substitution in semiconductor degreasing, anchor coating-grade positioning through REACH certification maintenance and carbon adsorption system partnerships with automotive refinish chains. Capacity addition in Vietnam and Indonesia captures Southeast Asia automotive assembly growth before regional supply matures. For New Entrants and Emerging Players: Enter via bio-based acetic acid fermentation partnerships that unlock Scope 3 emissions premiums from European formulators. White-space concentrates in Southeast Asia coating expansion and Indian food-grade adjuvant certification under FSSAI enforcement. Lead with sustainability documentation rather than cost parity. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs and pharma-grade analytical capability gaps strand mid-scale fractional distillation operators. Long-term viability favors specialists with concurrent FDA Type II Drug Master File and ECHA registration assets. Watch membrane-polishing technology adoption rates in German and Swiss pharmaceutical clusters as margin compression indicator for commodity-grade exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Captive supply insulates North American producers from merchant IPA price volatility. |
| Pharmaceutical Excipient Certification | FDA Type II DMF submission creates procurement stickiness protecting synthesis-grade margins. |
| Membrane Polishing Technology Adoption | Real-time conductivity verification meets Swissmedic batch traceability requirements for crystallization-grade supply. |
| Southeast Asia Distillation Capacity Buildout | Vietnam and Indonesia automotive assembly growth outpaces domestic solvent supply availability. |
| Closed-Loop Solvent Recovery Systems | MEE VOC discharge limits in China's chemical parks favor recyclers with integrated purification trains. |
Research Methodology
Bottom-up pharmaceutical and coating formulation modeling reconciled against top-down propylene feedstock and acetic acid supply tracking forms the analytical core. Primary interviews with plant managers at fractional distillation facilities, procurement leads at pharmaceutical manufacturers, distribution channel partners in China's Pearl River Delta, and technical R&D directors at coating compounders combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and EPA NESHAP regulatory filings.
Historical trendline analysis across pharmaceutical synthesis, coating, adhesive, and ink applications established baseline consumption patterns. Segmentation modeling incorporated grade tier, end-use industry, regional production hub, and regulatory certification cluster dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs included propylene derivative pricing correlations and REACH registration cost trajectories.
Inputs from ECHA substance inventories and FDA Drug Master File databases were available through the study window; gaps in real-time Chinese provincial capacity utilization introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution technology maturation. A small set of triggers—bio-based acetic acid cost parity, aqueous surfactant qualification rates in precision optics, and MEE enforcement variability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Epoxy Type Stabilizers Market
Additives
North America Paints and Coatings Additives Market
Additives
Triazine UV Absorber Market
Additives
Inorganic Rheology Modifiers Market
Additives
Calcium Acetate Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Asia Pacific Plastic Additives Market
Additives
Polysorbate-80 Market
Additives
Binding Agents Market
Additives
Sodium Stearyl Fumarate Market
Additives
Global Scale Inhibitors Market
Additives
Calcium Stearate Market
Additives
Global Asphalt Additives Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
North America Pectin Market
Additives
Automotive Additives Market