
 Tartaric Acid Market | 2026-2036
Tartaric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Tartaric Acid Market Analysis
Pharmaceutical companies are redrawing tartaric acid procurement priorities as chiral intermediate demand outpaces traditional wine-sector offtake. Merck sustains pharmaceutical-grade production leadership through stringent USP and EP certification protocols. Thirumalai Chemicals anchors Asian supply through integrated tartaric acid and derivative manufacturing in Tamil Nadu. ATP Group differentiates via grape-derived natural acid sourcing from Italian and Spanish wine cooperatives.
Tartaric acid is a dicarboxylic acid (C₄H₆O₆) existing as three stereoisomers, with L-(+)-tartaric acid dominating commercial production through either natural recovery from wine lees or synthetic maleic anhydride processing; it functions primarily as an acidulant, chelating agent, and chiral resolution auxiliary across food, pharmaceutical, and industrial applications. Natural tartaric acid commands premium positioning in organic-labeled food and beverage formulations where clean-label credentials justify higher input costs. Synthetic tartaric acid occupies volume-driven segments including industrial metal finishing and standard pharmaceutical excipient grades where cost efficiency outweighs provenance requirements. Pharmaceutical applications represent the fastest-expanding consumption pool, driven by asymmetric synthesis demand for single-enantiomer drug production.
REACH registration requirements and EFSA food additive specifications govern European market access, while FDA excipient guidelines and USP monographs define pharmaceutical-grade standards in the United States. China's SAMR food safety standards and NMPA pharmaceutical excipient regulations are converging toward international purity benchmarks, reshaping import and domestic production requirements. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and food-grade specifications, as tightening chiral purity thresholds in drug applications threaten to fragment supply chain fungibility across end-use segments.
Market Dynamics
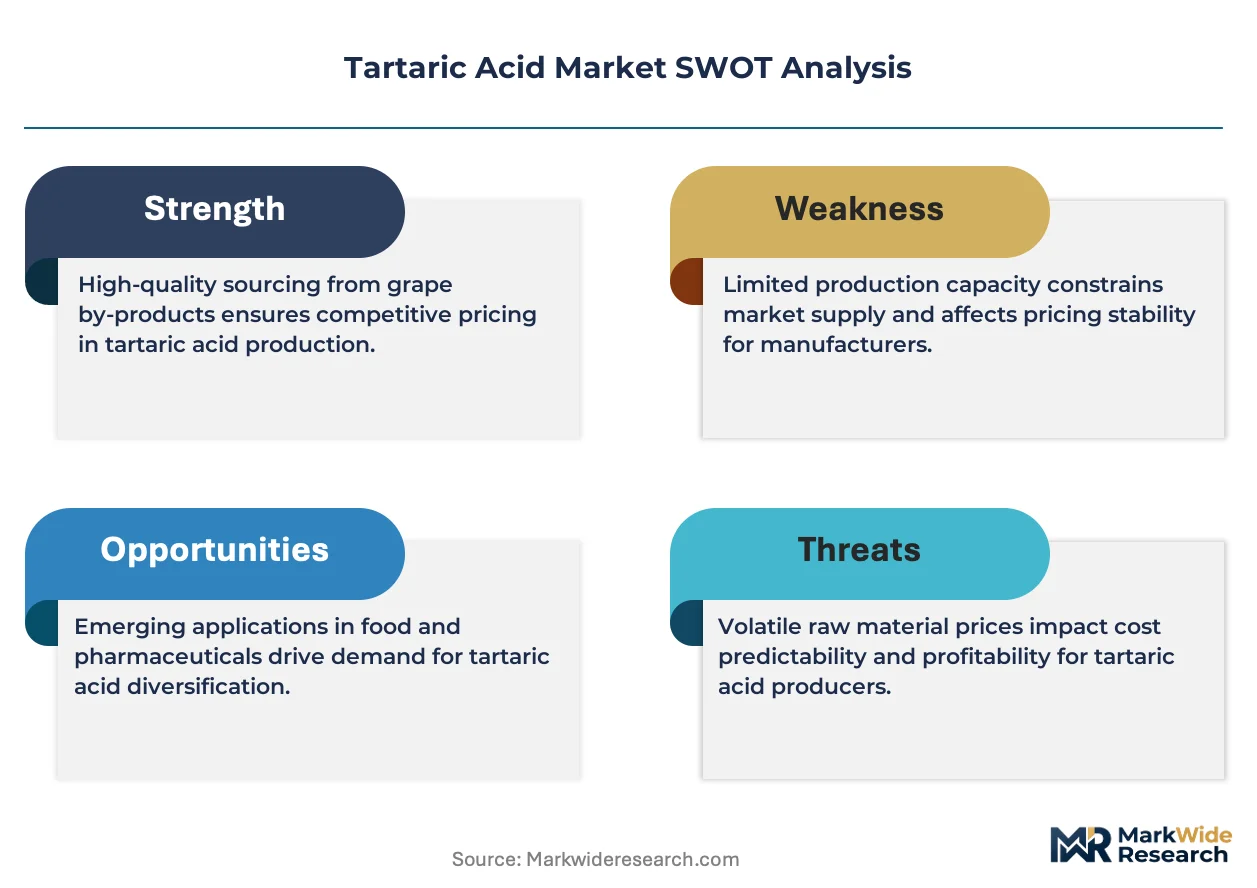
Chiral purity thresholds in pharmaceutical applications are fragmenting supply chain fungibility, forcing producers to segregate food-grade and pharmaceutical-grade tartaric acid streams through dedicated processing lines and certification protocols.
Growth Catalysts
- Asymmetric synthesis demand:Single-enantiomer drug production requires L-(+)-tartaric acid as a chiral resolution auxiliary, pulling volume from traditional wine-sector applications into pharmaceutical manufacturing.
- REACH registration:European ECHA compliance mandates are consolidating supplier bases toward certified producers capable of documenting stereochemical purity across production batches.
- Clean-label food migration:Organic-labeled beverage and confectionery formulations specify grape-derived natural tartaric acid, creating premium pricing tiers separate from synthetic maleic anhydride routes.
Market Restraints
- Input cost volatility:Maleic anhydride feedstock prices fluctuate with petrochemical cycles, compressing margins on synthetic tartaric acid production during crude oil spikes.
- Supply concentration risk:Tamil Nadu and Zhejiang province house the majority of Asian tartaric acid capacity, exposing buyers to regional logistics disruptions and trade policy shifts.
- Technical limitation:Natural recovery from wine lees cannot scale beyond vintage-dependent grape processing volumes, capping organic-certified supply regardless of price premiums.
Strategic Opportunities
- Brazil pharmaceutical expansion:ANVISA regulatory convergence toward USP and EP standards creates import substitution potential for certified tartaric acid producers establishing local blending operations.
- Biocatalytic resolution:Enzymatic chiral separation technologies are reducing solvent intensity in tartaric acid derivative production, opening cost advantages in ester and salt manufacturing.
- EU Green Deal alignment:Carbon border adjustment mechanisms favor lower-carbon-intensity natural tartaric acid routes over maleic anhydride-derived synthetic alternatives in European import markets.
Industry Challenges
- Chiral analytical capability gaps:Food-grade producers lack polarimetry and HPLC infrastructure to verify enantiomeric excess for pharmaceutical customers, requiring capital deployment or third-party testing partnerships.
- Dual certification timelines:Simultaneous USP, EP, and ChP (Chinese Pharmacopoeia) qualification stretches 18-24 months, delaying market entry for new pharmaceutical-grade suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tartaric Acid Market |
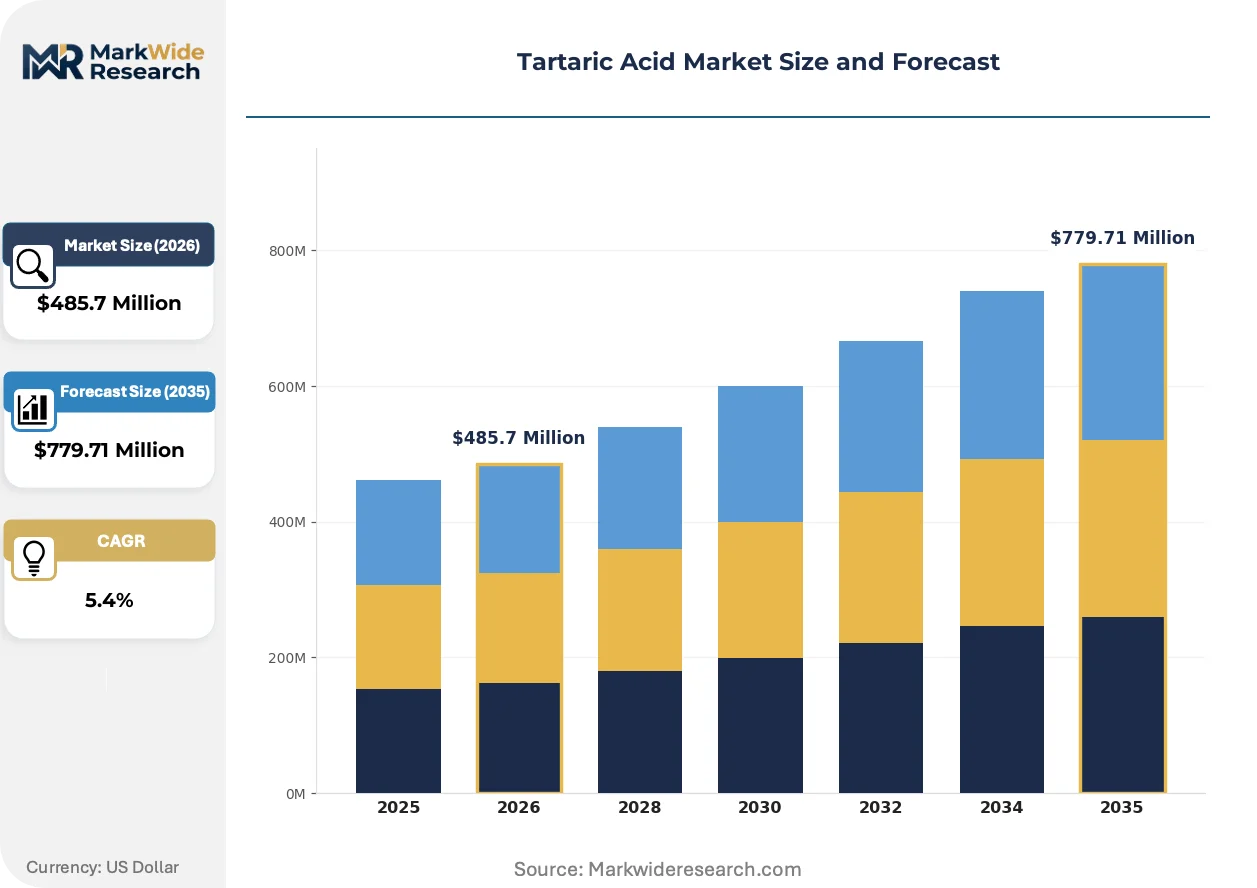
| Market Size in 2026 | $485.7 Million |
| Market Size in 2035 | $779.71 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Tartaric Acid, Synthetic Tartaric Acid, Cream of Tartar, L-(+)-Tartaric Acid Application: Food and Beverage, Pharmaceuticals, Cosmetics, Biochemical End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Research Laboratories Distribution Channel: Retail, E-commerce, Wholesalers, Direct Sales |
| Companies Covered | Caviro Group, Merck, ATP Group, Tarac Technologies, Laffort, Distillerie Mazzari S.p.A., Essecso Group, Oenobrands, Thirumalai Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tartaric Acid Market Emerging Trajectories
Continuous processing technologies and biocatalytic methods are displacing batch-wise chemical synthesis in tartaric acid derivative manufacturing, while regulatory data integrity requirements reshape how producers document stereochemical specifications across supply chains.
Membrane filtration recovery systems are supplanting traditional crystallization sequences in natural tartaric acid extraction from wine lees. Italian and Spanish cooperatives are retrofitting facilities with ceramic membrane cascades that reduce water consumption and thermal energy inputs. This technology compression is enabling smaller-batch organic certification without sacrificing unit economics.
EFSA food additive specifications are tightening residual solvent limits in tartaric acid esters used as emulsifiers. The industrial consequence is accelerated validation of supercritical CO2 extraction methods for derivative purification. Bakery and confectionery multinationals sourcing from European suppliers are now requiring third-party solvent residue testing beyond standard certificate of analysis documentation.
Pharmaceutical buyers are consolidating tartaric acid suppliers toward single-source contracts with dedicated chiral specification guarantees. Large-scale generic drug manufacturers in India and China are replacing spot-market purchasing with 24-36 month supply agreements that lock stereochemical purity thresholds and audit rights. This contracting shift is most visible among CDMOs serving US and EU innovator pharmaceutical companies facing FDA and EMA data integrity inspections.
Tartaric Acid Market Segmentation
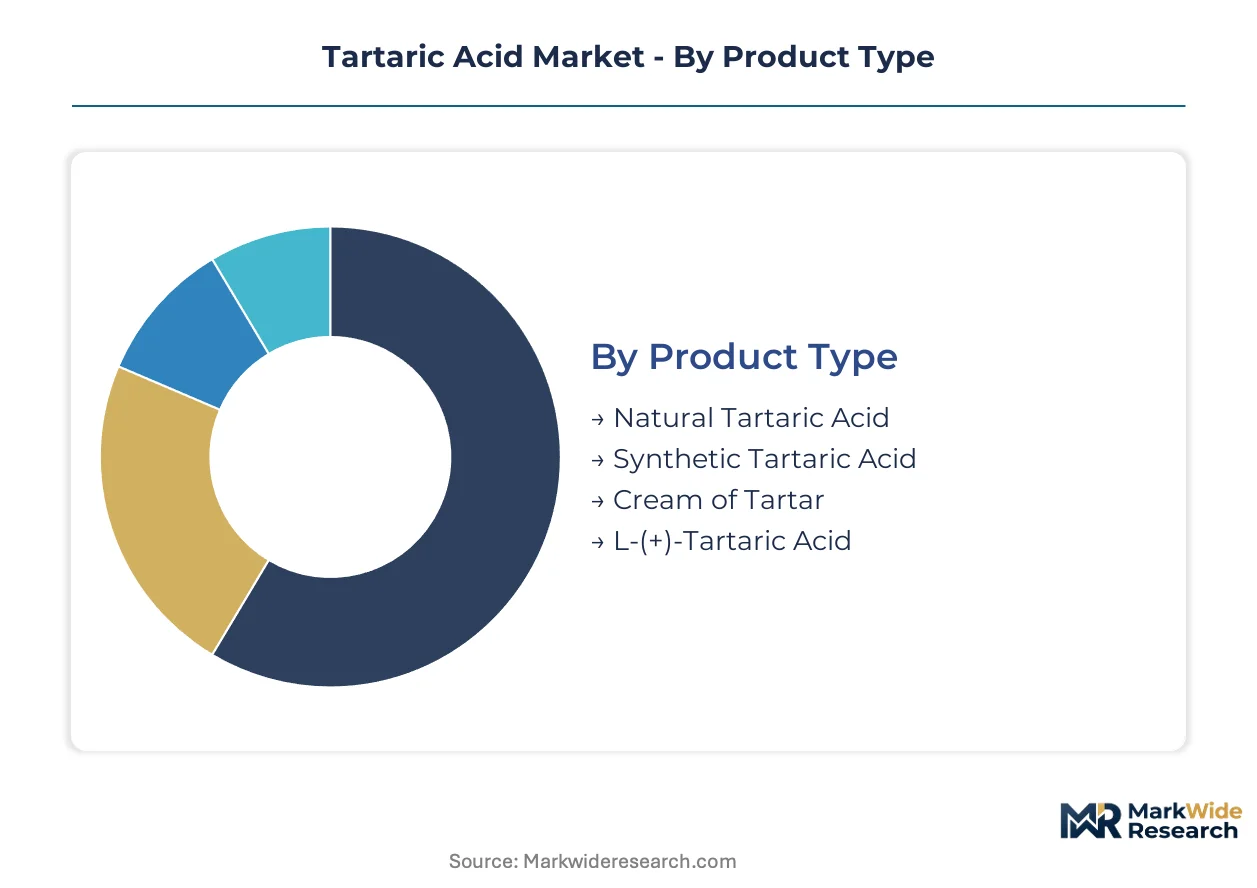
Tartaric acid segmentation reflects divergent purity requirements across regulated industries. Pharmaceutical-grade specifications command premium positioning against commodity food-grade volumes, while natural versus synthetic sourcing creates distinct supply chain architectures.
Product Type:
Regulatory differentiation separates pharmaceutical-grade streams from commodity food-grade production, with certification protocols governing permissible synthetic routes and natural recovery methods.
- L-(+)-Tartaric Acid:The dominant commercial stereoisomer serves as the chiral resolution auxiliary of choice for asymmetric synthesis in pharmaceutical manufacturing. FDA and EMA inspections of CDMOs in India and China are consolidating procurement toward producers with documented enantiomeric excess above 99.5 percent.
- Natural Tartaric Acid:Grape-derived recovery from Italian and Spanish wine lees carries organic certification eligible for EU Green Deal carbon border adjustments. Vintage-dependent supply caps prevent scaling regardless of clean-label price premiums in beverage applications.
- Synthetic Tartaric Acid:Maleic anhydride-derived production supplies volume-driven industrial metal finishing and standard pharmaceutical excipient grades where cost efficiency outweighs provenance requirements.
- Cream of Tartar:The potassium acid salt of tartaric acid functions as a stabilizing agent in baking powder formulations and confectionery aeration.
L-(+)-Tartaric Acid handles the majority of throughput; Natural Tartaric Acid is expanding most quickly on share.
Application:
Cost tier stratification places pharmaceutical chiral intermediates at premium pricing against commoditized food acidulant volumes.
- Pharmaceuticals:Single-enantiomer drug production consumes L-(+)-tartaric acid as a chiral auxiliary for resolution of racemic mixtures. ANVISA regulatory convergence in Brazil toward USP and EP standards is creating import substitution opportunities for certified producers.
- Food and Beverage:Acidulant, stabilizer, and chelating agent functions span wine, soft drinks, and confectionery. EFSA specifications tightening residual solvent limits in tartaric acid esters are accelerating supercritical CO2 extraction validation.
- Cosmetics:pH adjustment and antioxidant properties support formulation in skincare and haircare products.
- Biochemical:Research and industrial bioprocessing applications utilize tartaric acid derivatives as complexing agents.
Food and Beverage retains volume leadership; Pharmaceuticals climbs the fastest on value contribution.
End User:
Customer type determines contracting structure, with pharmaceutical manufacturers replacing spot purchasing against long-term supply agreements.
- Pharmaceutical Companies:Large-scale generic manufacturers in India and China are locking 24-36 month supply agreements with stereochemical purity guarantees and audit rights. FDA and EMA data integrity inspections drive supplier consolidation toward single-source contracts.
- Food Manufacturers:Bakery and confectionery multinationals sourcing from European suppliers now require third-party solvent residue testing beyond standard certificate of analysis documentation.
- Cosmetic Brands:Clean-label positioning drives specification of natural-derived tartaric acid in premium skincare formulations.
- Research Laboratories:Biochemical and analytical applications demand high-purity grades with documented batch consistency.
Pharmaceutical Companies command the steepest expansion trajectory; Food Manufacturers anchor current volume.
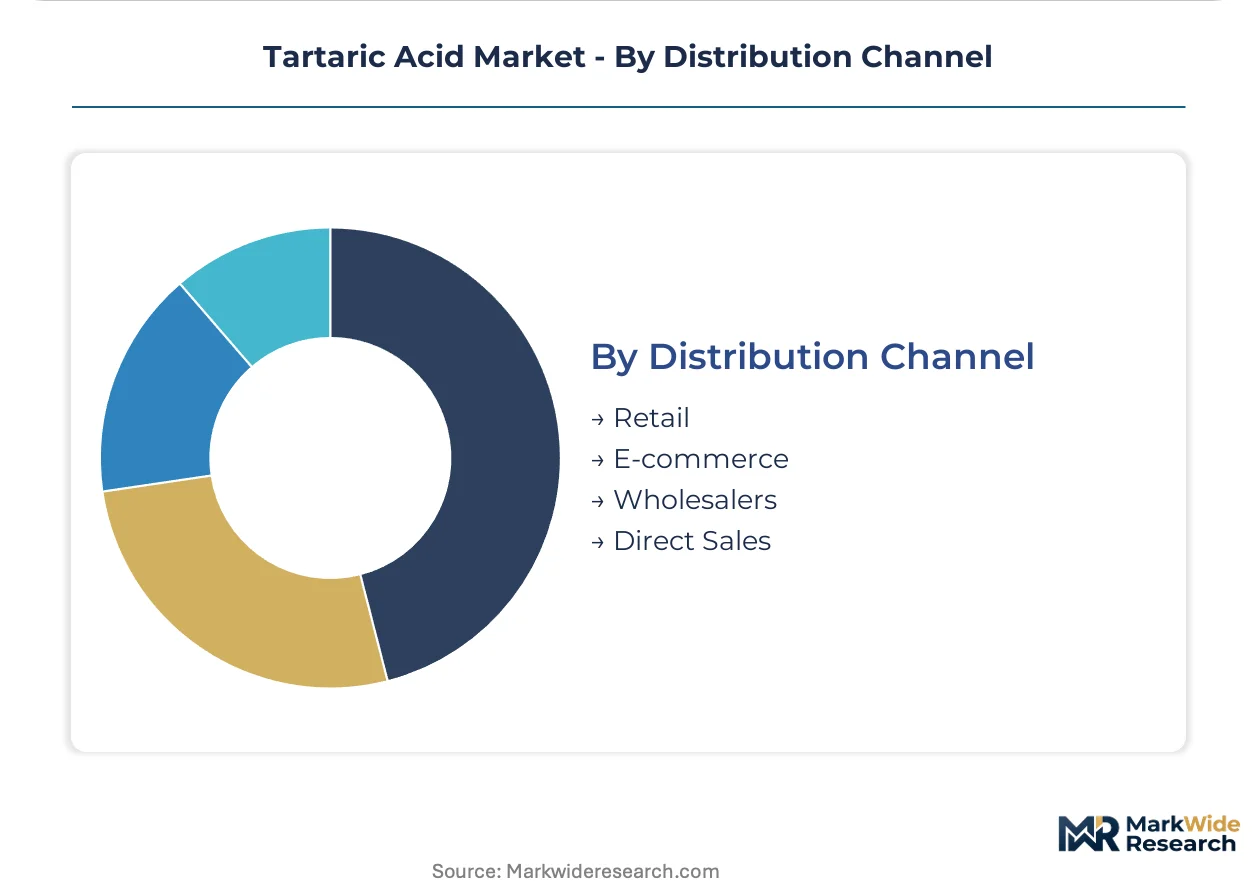
Distribution Channel:
Supply concentration shapes channel selection, with certified pharmaceutical grades flowing through audited direct relationships.
- Direct Sales:Pharmaceutical-grade tartaric acid moves through producer-direct contracts with embedded quality agreements and regulatory documentation packages. Thirumalai Chemicals and Merck maintain dedicated account structures for CDMO and innovator pharmaceutical customers.
- Wholesalers:Food-grade and industrial volumes distribute through regional chemical distributors serving fragmented food manufacturer bases.
- E-commerce:Specialty and research-grade quantities reach smaller cosmetic brands and laboratories through validated online platforms.
- Retail:Consumer-packaged cream of tartar reaches household bakers through grocery and specialty store channels.
Direct Sales captures the fastest-growing channel share; Wholesalers handle baseline food-grade throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites Asia's tartaric acid trade flows, connecting Zhejiang province manufacturing clusters to pharmaceutical buyers in Europe and the Americas. Rotterdam's Maasvlakte terminals serve as the primary European entry point for certified pharmaceutical grades, with dedicated cold-chain warehousing for temperature-sensitive chiral intermediates.
China
Zhejiang and Jiangsu provinces host concentrated maleic anhydride-derived synthetic capacity serving both domestic food additive demand and export pharmaceutical orders. SAMR food safety standards and NMPA pharmaceutical excipient regulations are converging toward USP and EP purity benchmarks, forcing domestic producers to upgrade quality systems. Ningbo-Zhoushan port logistics hubs are expanding dedicated chemical storage for tartaric acid derivatives bound for Indian and Brazilian pharmaceutical manufacturers.
United States
FDA excipient guideline revisions and USP monograph updates are tightening chiral purity documentation requirements for imported tartaric acid. New Jersey and Pennsylvania pharmaceutical manufacturing corridors source heavily from certified Asian suppliers via long-term supply agreements with embedded audit rights. Houston petrochemical complexes provide maleic anhydride feedstock for domestic synthetic production, though volumes remain below pharmaceutical-grade certification thresholds.
Italy
Emilia-Romagna and Veneto wine cooperatives anchor European natural tartaric acid recovery from vintage-dependent lees processing. EU Green Deal carbon border adjustment mechanisms favor lower-carbon-intensity grape-derived routes over maleic anhydride alternatives in import markets. Ravenna port facilities are retrofitting with ceramic membrane filtration systems to reduce water consumption in organic-certified extraction operations.
India
Tamil Nadu's integrated tartaric acid and derivative manufacturing cluster supplies both domestic pharmaceutical formulation growth and export orders to Southeast Asian markets. CDSCO pharmaceutical regulations and FSSAI food additive standards are aligning with international purity benchmarks, reshaping import substitution strategies. Chennai port pharmaceutical-grade cold storage capacity is expanding to handle growing chiral intermediate volumes for contract drug manufacturing organizations.
Brazil
ANVISA regulatory convergence toward USP and EP standards is creating import substitution opportunities for certified tartaric acid producers establishing local blending operations. São Paulo state pharmaceutical manufacturing growth is pulling volume from traditional Argentine and European suppliers into direct Asian procurement relationships. Santos port chemical terminal operators are investing in segregated storage infrastructure to prevent cross-contamination between food-grade and pharmaceutical-grade streams.
Tartaric Acid Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and end-market focus, producing a tiered structure where pharmaceutical-grade capabilities separate premium positioning from commodity food-grade supply. Publicly traded chemical conglomerates anchor scale-driven synthetic production, while family-owned wine-sector cooperatives dominate natural recovery with organic certification advantages. Three archetypes define competitive positioning: integrated pharmaceutical-grade specialists with multi-pharmacopoeia qualifications, regional food-grade volume producers serving fragmented bakery and confectionery bases, and natural-source premium suppliers leveraging vintage-provenance storytelling. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers seeking to secure maleic anhydride feedstock contracts or wine lees offtake agreements.
Within the pharmaceutical-grade tier, Merck and Thirumalai Chemicals exemplify divergent geographic anchoring strategies for certified production. Merck occupies a position reflecting European regulatory leadership through EMA-aligned quality systems, while Thirumalai Chemicals represents Asian supply integration serving both domestic Indian pharmaceutical growth and export markets. ATP Group sits within the natural-source premium archetype, leveraging Mediterranean wine cooperative networks for organic-certified supply chains that command clean-label price premiums in European and North American beverage markets.
| Leading Market Players |
|---|
| Caviro Group |
| Merck |
| ATP Group |
| Tarac Technologies |
| Laffort |
| Distillerie Mazzari S.p.A. |
| Essecso Group |
| Oenobrands |
| Thirumalai Chemicals |
| Others |
Supply Flow & Price Mechanics
Maleic anhydride substitution for grape-derived feedstock is simultaneously shifting production geography toward Zhejiang province petrochemical clusters and compressing synthetic-grade pricing economics against vintage-capped natural recovery premiums. This input substitution dynamic fragments pricing power across pharmaceutical-grade certification holders and commodity food-grade volume producers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade L-(+)-tartaric acid with USP/EP/ChP certification from standard food-grade and industrial metal-finishing volumes. Price differentiation rests on chiral purity thresholds and dual pharmacopoeia qualification timelines stretching 18-24 months. Cost compression in synthetic maleic anhydride routes is intensifying because petrochemical feedstock volatility compresses margins during crude oil spikes. Food manufacturers exhibit highest price sensitivity, while CDMOs serving FDA-inspected innovators accept premium positioning for documented enantiomeric excess above 99.5 percent.
Supply Chain Analysis
Tamil Nadu port congestion and Ningbo-Zhoushan customs clearance delays create chokepoints threatening just-in-time pharmaceutical intermediate deliveries. Geographic supply concentration centers on China, India, and Italy, with maleic anhydride, wine lees, and potassium carbonate as critical input dependencies. Single-source vulnerability runs through Zhejiang province synthetic capacity serving both domestic SAMR-regulated food additive demand and export pharmaceutical orders. Distribution runs through producer-direct audited relationships for pharmaceutical grades and regional chemical wholesalers for commodity food volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tartaric acid demand cycles with pharmaceutical capital expenditure waves and wine vintage variability, positioning the current window as an asymmetric synthesis-driven recovery phase. CDMO procurement consolidation toward single-source contracts signals sustained pricing power for certified producers.
For Market Incumbents: Compound certification depth through simultaneous USP, EP, and ChP qualification to lock CDMO relationships before new entrants complete 18-24 month approval timelines. Defend against Brazilian ANVISA convergence opportunities by establishing local blending operations ahead of import substitution shifts. Prioritize backward integration into maleic anhydride feedstock contracts or wine lees offtake agreements to secure margin control.
For New Entrants and Emerging Players: Lead with biocatalytic resolution capabilities targeting solvent-intense ester and salt manufacturing where enzymatic separation opens cost advantages. Brazil pharmaceutical manufacturing growth represents the most penetrable geography given ANVISA regulatory convergence toward USP and EP standards. Pursue white-label pharmaceutical-grade toll manufacturing for Indian and Chinese generic drug producers seeking audit-ready second sources.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European natural tartaric acid specialists holding organic certification and EU Green Deal carbon border adjustment eligibility. Long-term viability favors producers with demonstrated multi-pharmacopoeia qualification infrastructure and captive wine cooperative networks. Watch FDA data integrity inspection frequency at Indian and Chinese CDMOs as the inflection signal for accelerated supplier consolidation toward certified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Pharmacopoeia Certification Investment | Simultaneous USP, EP, and ChP qualification locks CDMO single-source contracts ahead of competitor timelines. |
| Backward Integration into Maleic Anhydride | Captive petrochemical feedstock supply insulates synthetic production margins from crude oil volatility cycles. |
| Wine Cooperative Network Expansion | Organic-certified grape lees offtake agreements secure EU Green Deal carbon border adjustment advantages. |
| Biocatalytic Resolution Technology Deployment | Enzymatic chiral separation reduces solvent intensity and opens cost advantages in derivative manufacturing. |
| Brazil Local Blending Operation Establishment | ANVISA regulatory convergence creates import substitution potential ahead of São Paulo pharmaceutical manufacturing growth. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical procurement managers, CDMO quality assurance directors, food manufacturer R&D leads, and wine cooperative processing managers and refined through secondary validation against customs trade data, FDA warning letter databases, EFSA food additive specifications, and SEC 10-K chemical segment disclosures. Bottom-up volume modeling across grade tiers and top-down macroeconomic anchoring were triangulated to converge estimates.
Variance-decomposition framing separated volume drivers by pharmaceutical chiral auxiliary demand, food acidulant substitution patterns, and industrial metal finishing cyclicality across the analysis window. Segmentation dimensions modeled included product grade tier, end-use industry application, natural versus synthetic sourcing route, and regional regulatory cluster. CAGRs were derived from regression-adjusted trend extrapolation incorporating maleic anhydride feedstock price elasticity and vintage-dependent wine lees recovery constraints.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical capital expenditure growth or prolonged petrochemical feedstock volatility would require recalibration. Forecasts reflect documented assumptions about regulatory convergence timelines and chiral purity threshold evolution. Practitioners should keep alternative scenarios live as FDA data integrity inspection intensity and EU carbon border adjustment implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ammonium Phosphatide Market
Additives
Anti-Slip Additives Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Allura Red AC Market
Additives
Butyrate Additives Market
Additives
Performance Minerals Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Saudi Arabia Feed Additives Market
Additives
Tamarind Gum Derivatives Market
Additives
Hydroxyethyl Cellulose Market
Additives
Mycotoxin Binders Market
Additives
North America Potassium Nitrate Market
Additives
Sorbitan Laurate Market
Additives
China Sodium Reduction Ingredient Market