
 Microcrystalline Cellulose (MCC) Market | 2026-2036
Microcrystalline Cellulose (MCC) Market Size, Share, and Industry Trends Forecast 2026-2036
Microcrystalline Cellulose (MCC) Market Analysis
Pharmaceutical buyer concentration is pivoting toward large contract manufacturers and integrated generics houses that internalize excipient sourcing. Roquette Frères leverages its multi-regional plant network to sustain supply continuity for European and Asian formulators. J. Rettenmaier & Söhne GmbH + Co KG anchors its position through specialized wood-pulp sourcing and proprietary fibrillation technology. Sigachi Industries Limited competes on cost-optimized production from its Indian base, serving both domestic and export markets.
Microcrystalline cellulose is a purified, partially depolymerized cellulose produced by treating alpha-cellulose with mineral acids, yielding particles with crystalline regions of 80-120 micrometers and moisture content typically below 5%. It functions primarily as a binder, diluent, and disintegrant in tablet formulations across pharmaceutical, food, and cosmetic applications. Pharmaceutical grade commands the deepest margin pool due to stringent pharmacopeial compliance, while food grade extends volume through clean-label anti-caking and texturizing applications. Powder form dominates current offtake, though granules are gaining traction in high-speed direct compression lines where flowability determines throughput.
The US FDA, EMA, and Indian CDSCO enforce escalating purity and documentation standards for excipient-grade MCC, pushing suppliers toward dedicated GMP facilities and supply chain traceability. REACH registration in Europe and evolving USP-NF monographs further segment market access between compliant and non-compliant producers. Stakeholders must monitor regulatory divergence across FDA, EMA, and CDSCO pathways, as misalignment in impurity limits or change-control notification rules will reshape supplier qualification timelines and capital deployment priorities.
Market Dynamics
Pharmaceutical formulators are consolidating excipient procurement around suppliers with dedicated GMP facilities and multi-regional plant networks, compressing qualification timelines and elevating compliance costs for mid-tier producers.
Growth Catalysts
- Direct compression expansion:Tablet manufacturers are migrating from wet granulation to direct compression to cut processing steps, driving MCC demand for its binding and flow properties.
- REACH registration compliance:European suppliers completing REACH dossiers are securing preferential access to EMA-regulated formulators, creating a regulatory moat against non-compliant imports.
- India's API manufacturing scale-up:Domestic finished-dose producers in India are expanding capacity under CDSCO oversight, concentrating regional MCC offtake.
Market Restraints
- Wood-pulp input volatility:Specialized alpha-cellulose feedstock costs fluctuate with forestry harvest cycles and pulp commodity markets, squeezing margin predictability.
- Supplier concentration risk:A limited cohort of European and Indian producers controls pharmaceutical-grade fibrillation technology, exposing buyers to single-source vulnerability.
- Silicified MCC substitution:Co-processed excipients combining MCC with colloidal silicon dioxide are displacing standard grades in high-speed lines.
Strategic Opportunities
- Food-grade clean-label penetration:Anti-caking and texturizing applications in plant-based meat and dairy alternatives remain underdeveloped relative to pharmaceutical use.
- Granule format adoption:High-speed direct compression lines in North American contract manufacturing organizations are switching from powder to granule MCC for flowability gains.
- CDSCO GMP harmonization:India's alignment with ICH Q3D elemental impurity guidelines is accelerating supplier qualification for export-oriented formulators.
Industry Challenges
- Pharmacopeial change-control complexity:USP-NF monograph updates require extensive revalidation, extending supplier notification timelines and freezing formulation adjustments.
- Traceability system capex:Batch-level digital tracking from wood-pulp source to finished excipient demands significant IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcrystalline Cellulose (MCC) Market |
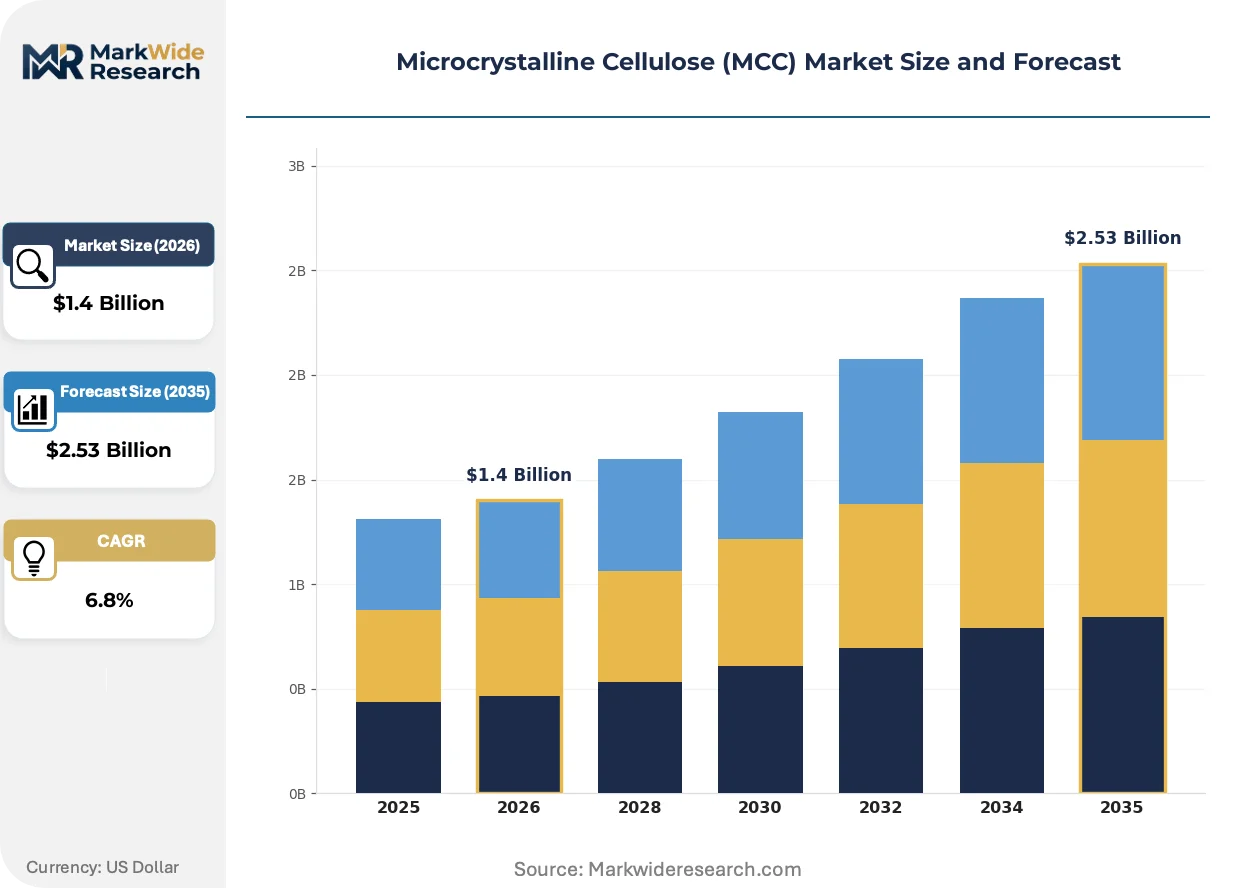
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Form: Powder, Granules, Tablets, Capsules Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Asahi Kasei Corporation, Roquette Frères, DFE Pharma, Rayonier Advanced Materials, J. Rettenmaier & Söhne GmbH + Co KG, Sigachi Industries Limited, International Flavors & Fragrances Inc., Nitika Pharmaceutical Specialities Pvt. Ltd., Ankit Pulps and Boards Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcrystalline Cellulose (MCC) Market Emerging Trajectories
Excipient engineering and regulatory digitization are converging to reshape how pharmaceutical-grade MCC is specified, qualified, and supplied to formulators.
Co-processed excipient platforms combining MCC with functionalized silicates or superdisintegrants are rewriting the performance benchmark for high-speed tablet manufacturing. Multinational generics houses are specifying these grades in new product filings to compress development cycles. The shift is marginalizing standalone MCC powders in premium direct-compression applications.
EMA's intensified focus on excipient GMP through the IPEC-PQG certification framework is forcing suppliers to segregate pharmaceutical-dedicated production lines. Manufacturers without segregated facilities face exclusion from European qualification lists. Indian exporters are responding by building standalone GMP plants with EU QP release capabilities.
Formulator procurement teams are consolidating supplier panels from twelve-plus vendors to three or four strategic partners with multi-regional coverage. This concentration is most visible among large contract manufacturing organizations in the United States, where supply assurance now outweighs unit cost in vendor scoring. The shift is compressing mid-tier MCC producers into commodity food-grade markets.
Microcrystalline Cellulose (MCC) Market Segmentation
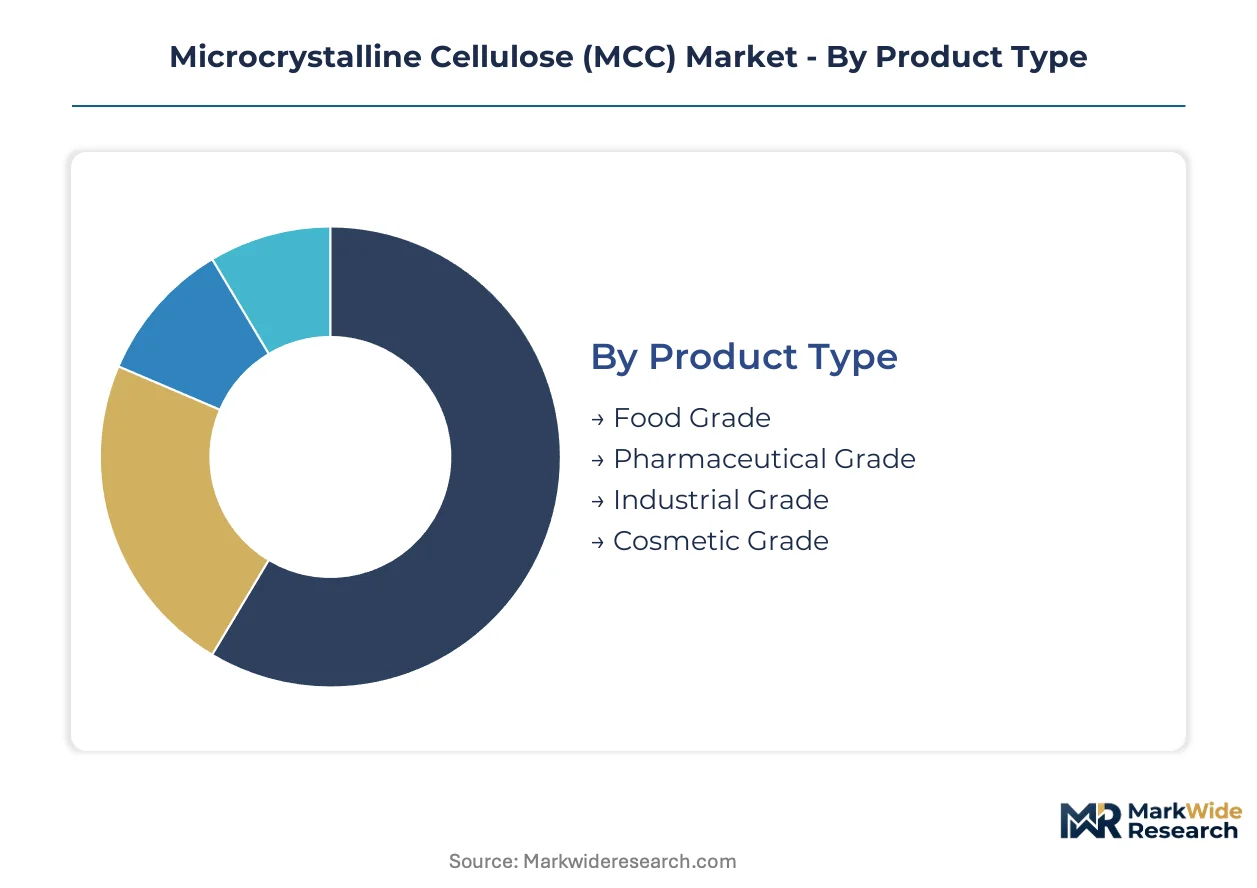
Segmentation in the Microcrystalline Cellulose market reveals how purity standards and formulation requirements fragment demand across discrete customer clusters. Pharmaceutical-grade specifications command the deepest compliance investment, while food-grade applications extend volume through clean-label positioning. Understanding these divides illuminates where suppliers must deploy dedicated GMP assets versus shared production lines.
Product Type:
Integration depth varies sharply across grades, with pharmaceutical specifications requiring standalone manufacturing suites while food and industrial grades tolerate co-located production.
- Pharmaceutical Grade:Purified to USP-NF and EP monograph standards with crystalline regions of 80-120 micrometers and moisture below 5%. Formulators in Germany and the United States are consolidating procurement around suppliers with IPEC-PQG certification and EU QP release capabilities, compressing qualification timelines for mid-tier producers.
- Food Grade:Functions as an anti-caking agent and texturizer in plant-based meat and dairy alternatives under FDA GRAS and EFSA food additive frameworks. Clean-label demand from North American and European CPG manufacturers is expanding volume faster than pharmaceutical applications, though at thinner margins.
- Industrial Grade:Serves construction and polymer composite applications with relaxed purity benchmarks.
- Cosmetic Grade:Deployed in pressed powders and skincare formulations with intermediate purity requirements.
Volume placements concentrate in Food Grade; the faster expansion belongs to Pharmaceutical Grade.
End Use Industry:
Application maturity determines margin structure, with established pharmaceutical use cases supporting premium pricing against nascent food and personal care segments.
- Pharmaceuticals:Dominates value capture through direct compression tablet manufacturing where MCC serves as binder, diluent, and disintegrant. Indian CDSCO-registered formulators are scaling capacity under ICH Q3D elemental impurity guidelines, concentrating regional offtake.
- Food & Beverage:Clean-label anti-caking in plant-based proteins and texturizing in reduced-fat dairy alternatives drives adoption. European EFSA approvals and US FDA GRAS status enable cross-border formulation, though penetration remains underdeveloped relative to pharmaceutical use.
- Cosmetics:Pressed powder applications in color cosmetics utilize MCC for oil absorption and skin-feel modification.
- Personal Care:Oral care and topical formulations employ lower-specification grades with minimal regulatory burden.
Revenue concentration sits with Pharmaceuticals; Food & Beverage is climbing the fastest.
Form:
Processing speed requirements are reshaping physical specification preferences across high-volume manufacturing lines.
- Powder:Retains dominant installed base across wet granulation and early direct compression platforms. Legacy equipment in Indian and Chinese contract manufacturing organizations sustates volume, though flowability limitations constrain throughput on high-speed lines.
- Granules:Engineered for superior flow properties in continuous manufacturing and high-speed direct compression. North American contract manufacturing organizations are switching formats to maximize line utilization, displacing standard powder in premium applications.
- Tablets:Pre-compressed excipient formats for specialized dissolution profiles.
- Capsules:Filler applications in hard-shell gelatin and HPMC capsule formulations.
Installed base favors Powder; Granules are gaining share fastest.
Distribution Channel:
Customer scale and regulatory documentation needs fragment procurement pathways between direct and intermediated supply.
- Direct Sales:Large multinational generics houses and contract manufacturing organizations source through dedicated account structures with audit rights and batch-level traceability. EMA's intensified excipient GMP focus has elevated direct relationships with European suppliers possessing segregated pharmaceutical lines.
- Distributors:Regional chemical distributors serve mid-tier formulators and compounders with consolidated logistics and local inventory. Indian domestic API manufacturers leverage distributor networks for standard-grade MCC with CDSCO documentation packages.
- Online Retail:Limited to laboratory-scale and R&D quantities with minimal regulatory packaging.
- Wholesalers:Bulk commodity movement for industrial and food-grade applications with simplified documentation.
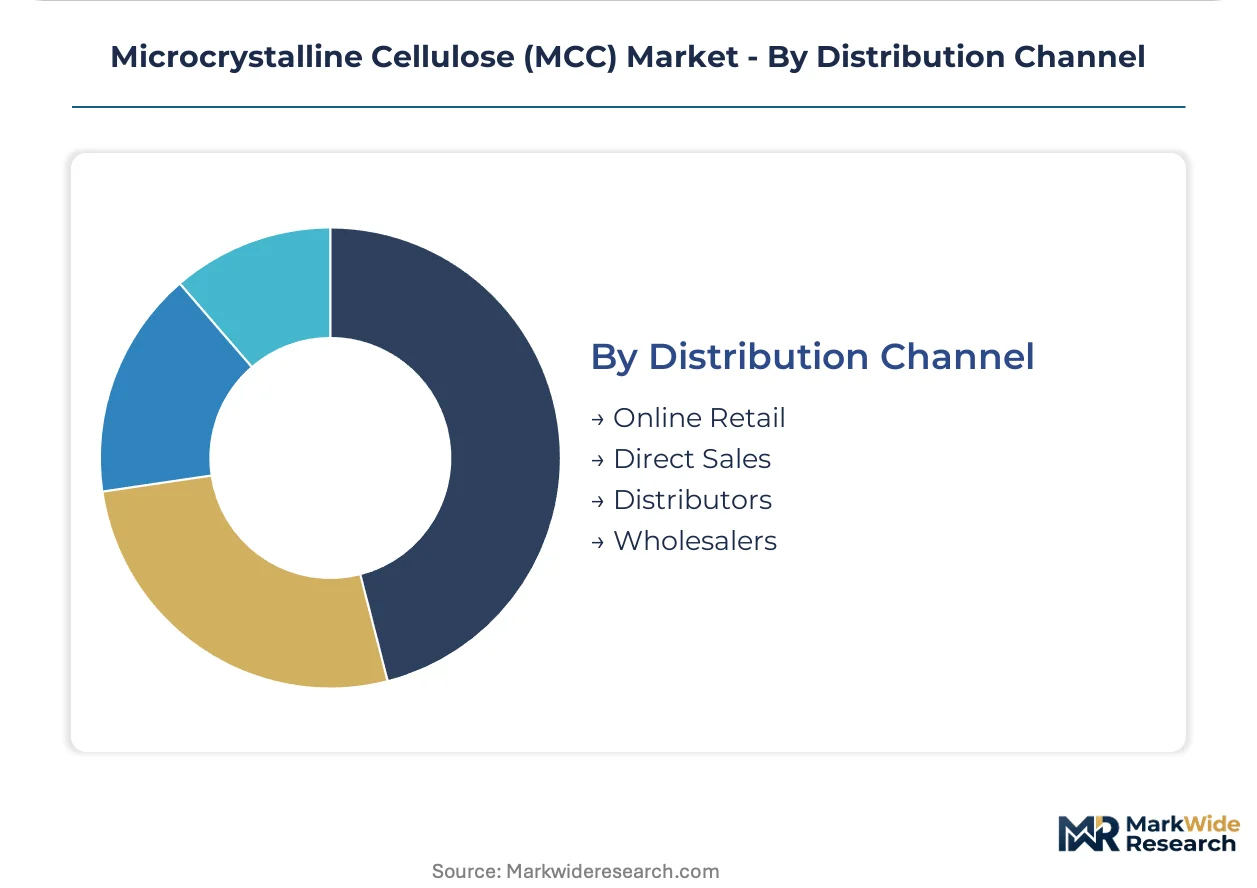
Transaction volume clusters with Distributors; Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pharmaceutical-grade microcrystalline cellulose concentrates in India, Germany, the United States, Japan, and China, where contract manufacturers and generics houses are consolidating excipient procurement around qualified suppliers with dedicated GMP facilities.
India
Domestic API and finished-dose manufacturers are scaling capacity under CDSCO oversight, driving concentrated MCC offtake in Hyderabad and Ahmedabad clusters. The regulator's alignment with ICH Q3D elemental impurity guidelines is accelerating supplier qualification timelines for export-oriented formulators. Gujarat and Telangana host expanding pharmaceutical manufacturing zones where domestic excipient producers compete on cost-optimized production.
Germany
EMA's intensified excipient GMP focus through the IPEC-PQG certification framework is forcing suppliers to segregate pharmaceutical-dedicated production lines. German formulators are consolidating procurement around European suppliers with EU QP release capabilities. The Frankfurt-Rhine-Main corridor anchors continental excipient distribution, with qualified suppliers securing preferential access to EMA-regulated manufacturers.
United States
Large contract manufacturing organizations are compressing supplier panels from twelve-plus vendors to three or four strategic partners with multi-regional coverage. FDA tightening of excipient purity benchmarks elevates compliance costs for mid-tier producers. The New Jersey-Pennsylvania pharmaceutical corridor and Research Triangle Park in North Carolina concentrate high-speed direct compression lines switching to granule MCC formats.
Japan
PMDA enforcement of pharmacopeial standards maintains rigorous entry barriers for imported excipients, sustaining domestic producer advantages. Japanese generics manufacturers are qualifying suppliers with batch-level traceability systems from wood-pulp source to finished excipient. The Kanto region around Tokyo hosts formulation R&D centers specifying co-processed excipient platforms for high-speed tablet manufacturing.
China
NMPA implementation of updated excipient registration requirements is segmenting market access between compliant and non-compliant producers. Domestic formulators are building captive supply relationships with qualified local MCC manufacturers. The Yangtze River Delta pharmaceutical cluster in Jiangsu and Zhejiang provinces is scaling direct compression capacity, driving demand for flow-optimized granule grades.
Microcrystalline Cellulose (MCC) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue food-grade clean-label applications and regional contract manufacturing partnerships. The vendor base stratifies between European specialists with proprietary fibrillation technology and Indian cost-optimized producers serving domestic and export markets. Three archetypes dominate: integrated wood-pulp processors with captive alpha-cellulose supply, pharmaceutical-dedicated GMP specialists with multi-regional plant networks, and regional compounders focusing on food and industrial grades. Capacity expansion and supply chain traceability investments constitute the primary competitive moves, with suppliers building standalone GMP facilities and batch-level digital tracking systems.
Among European specialists, Roquette Frères and J. Rettenmaier & Söhne GmbH + Co KG exemplify the premium-tier archetype through multi-regional manufacturing footprints and proprietary processing capabilities. Sigachi Industries Limited occupies a position within the cost-optimized tier, representing Indian producers competing on production efficiency from a domestic base. These three companies illustrate the structural divide between compliance-heavy pharmaceutical supply and volume-driven food-grade markets.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Roquette Frères |
| DFE Pharma |
| Rayonier Advanced Materials |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Sigachi Industries Limited |
| International Flavors & Fragrances Inc. |
| Nitika Pharmaceutical Specialities Pvt. Ltd. |
| Ankit Pulps and Boards Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Direct compression migration across pharmaceutical manufacturing lines simultaneously compresses unit economics and concentrates supply power among qualified excipient producers. The shift from wet granulation eliminates processing steps for formulators but elevates performance requirements for MCC grades, widening the cost-performance gap between certified pharmaceutical supply and commodity alternatives.
Pricing Analysis
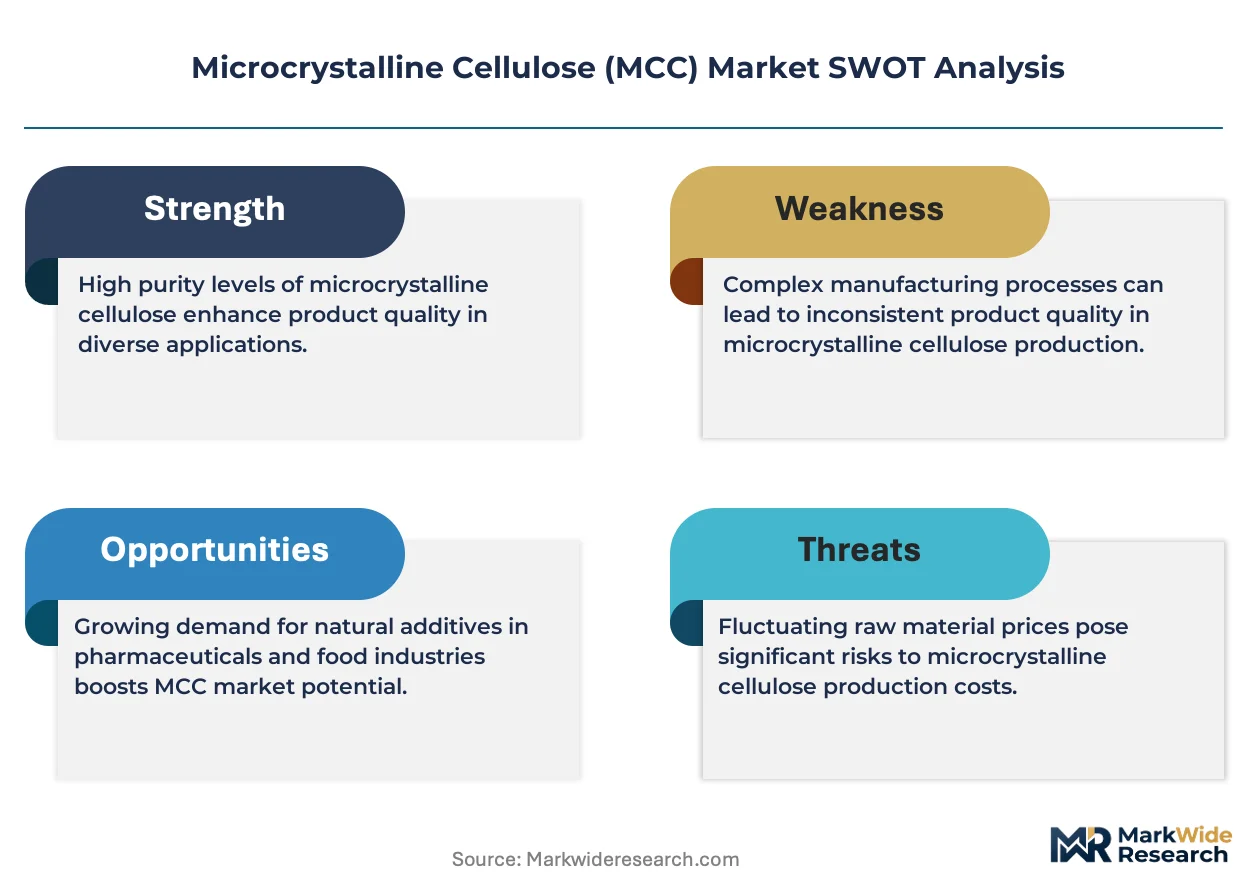
Volume placements concentrate in food-grade anti-caking applications at thinner margins, while pharmaceutical-grade specifications capture value through USP-NF compliance premiums. Price differentiation separates IPEC-PQG certified supply from standard grades, with EU QP release capabilities commanding additional premiums in EMA-regulated markets. Pricing pressure stems from silicified MCC substitution in high-speed tablet lines, eroding standalone powder margins. Contract manufacturing organizations exhibit lowest price sensitivity due to supply assurance priorities, while domestic Indian formulators drive hardest unit-cost negotiations.
Supply Chain Analysis
IPEC-PQG certification and EU QP release capabilities gate supplier access to European pharmaceutical formulators, fragmenting qualified supply between Germany, India, and the United States. Specialized alpha-cellulose feedstock draws from forestry harvest cycles in North America and Nordic regions, exposing producers to pulp commodity volatility. Single-source vulnerability concentrates in proprietary fibrillation technology holders, particularly European specialists controlling pharmaceutical-grade particle engineering. Distribution runs through direct account structures for large generics houses and regional chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade MCC operates as a supply-constrained market where segregated GMP facility scarcity props pricing power for qualified producers. Dedicated manufacturing line availability, not raw material access, functions as the binding capacity constraint.
For Market Incumbents: Cement multi-regional plant network advantages by completing REACH dossier updates and securing IPEC-PQG recertification ahead of EMA enforcement waves. Add segregated pharmaceutical capacity in Hyderabad or Ahmedabad clusters to capture Indian CDSCO alignment with ICH Q3D guidelines. Co-processed excipient platforms from DFE Pharma and Roquette Frères threaten standalone MCC positioning in premium direct-compression applications.
For New Entrants and Emerging Players: Begin with food-grade clean-label positioning in plant-based meat and dairy alternative formulations, where EFSA and FDA GRAS pathways offer lower regulatory barriers than pharmaceutical qualification. Target North American CPG manufacturers seeking anti-caking and texturizing solutions with volume-driven pricing. Establish toll manufacturing partnerships with existing alpha-cellulose processors rather than building captive pulp supply.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated excipient houses seeking regional manufacturing footprints, with strategic value hinging on IPEC-PQG certification status and EU QP release infrastructure. Long-term viability favors producers with backward integration into specialized wood-pulp supply and proprietary fibrillation IP. Watch CDSCO GMP harmonization progress as the inflection signal for Indian export-oriented capacity valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Segregated GMP Facility Buildout | IPEC-PQG certification unlocks EMA-regulated formulator procurement panels in Germany and France. |
| REACH Dossier Completion | Regulatory moat against non-compliant imports secures preferential access to European generics houses. |
| Co-Processed Excipient Development | MCC-silicate platforms displace standalone grades in high-speed direct compression lines. |
| Batch-Level Traceability Implementation | Digital tracking from wood-pulp source meets FDA and EMA escalating documentation requirements. |
| Food-Grade Clean-Label Positioning | Plant-based protein texturizing applications extend volume through EFSA-approved anti-caking deployment. |
Methodological Framework
Independent corroboration across excipient procurement directors, pharmaceutical plant managers, regulatory affairs leads, and CDSCO compliance officers underwrites the qualitative findings in this study. Primary interviews with formulation scientists at contract manufacturing organizations and generics houses combined with secondary validation from USP-NF monograph updates, EMA IPEC-PQG certification records, and Indian CDSCO GMP inspection reports. Bottom-up demand modeling from tablet production volumes and top-down supply analysis from wood-pulp processing capacity triangulate market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth in direct compression adoption from value capture in pharmaceutical-grade certification premiums. The analytical framework models grade tier, end-use industry, physical form, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from installed base transitions in tablet manufacturing equipment and qualification timeline compression for export-oriented Indian formulators.
Underlying measurement precision varies by segment; pharmaceutical-grade specifications carry tighter precision than food-grade volume estimates due to pharmacopeial documentation density. Forecasts reflect assumptions regarding CDSCO-EMA regulatory alignment pace and silicified MCC substitution rates in high-speed lines. A model refresh is warranted upon material change in ICH Q3D elemental impurity guideline enforcement timelines or REACH registration compliance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Hydroxyethyl Cellulose Market
Additives
Monocalcium Phosphate Market
Additives
Grease Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Canada Anti-Caking Market
Additives
Plastic Antioxidants Market
Additives
Caustic Sulphite Caramel Market
Additives
Americas Coating Additives Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Middle East Feed Additives Market
Additives
Dipotassium Guanylate Market
Additives
Anti Crystallizing Agents Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Disodium Inosinate Market
Additives
Ammonium Phosphatide Market
Additives
Tocopheryl Acetate Market