

Material Shrinkage-reducing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Material Shrinkage-reducing Agents Market Insights
Infrastructure developers are collapsing the once-dominant share held by general construction firms in shrinkage-reducing agent procurement. Sika AG leverages its European manufacturing footprint to sustain supply continuity for precast fabrication clients. MUHU (China) Construction Materials Co., Ltd. anchors its position through backward integration into polyether raw materials. BASF SE differentiates via R&D intensity in glycol-based formulations for ultra-high-performance concrete.
Material shrinkage-reducing agents are chemical admixtures—typically comprising polyether compounds, shrinkage-compensating polymers, or glycol derivatives—blended at 0.5-2.0% by weight of cementitious content to mitigate drying shrinkage and autogenous volume change in hardened concrete. Their primary commercial purpose is to extend service life of structural elements by reducing crack width below 0.3mm thresholds specified in durability codes. Liquid agents dominate volume flows due to ease of batching integration at ready-mix plants, while powder agents command margin pools in remote jobsites lacking liquid handling infrastructure. The concrete industry application segment leads absolute consumption, though precast fabrication exhibits the fastest specification growth as factory-cured elements demand tighter dimensional tolerances.
The EPA governs VOC emissions from concrete admixture production facilities under Clean Air Act Title V permitting, while ASTM C494 sets chemical uniformity and performance benchmarks for shrinkage-reducing products in the US market. REACH registration requirements in Europe compel suppliers to submit toxicological dossiers for polyether active ingredients, raising compliance costs for import-dependent formulators. China's SAMR enforces GB 8076 standards governing concrete admixture performance consistency across provincial construction markets. Stakeholders must monitor evolving low-carbon building codes that increasingly credit crack-resistant concrete formulations toward embodied carbon reduction targets.
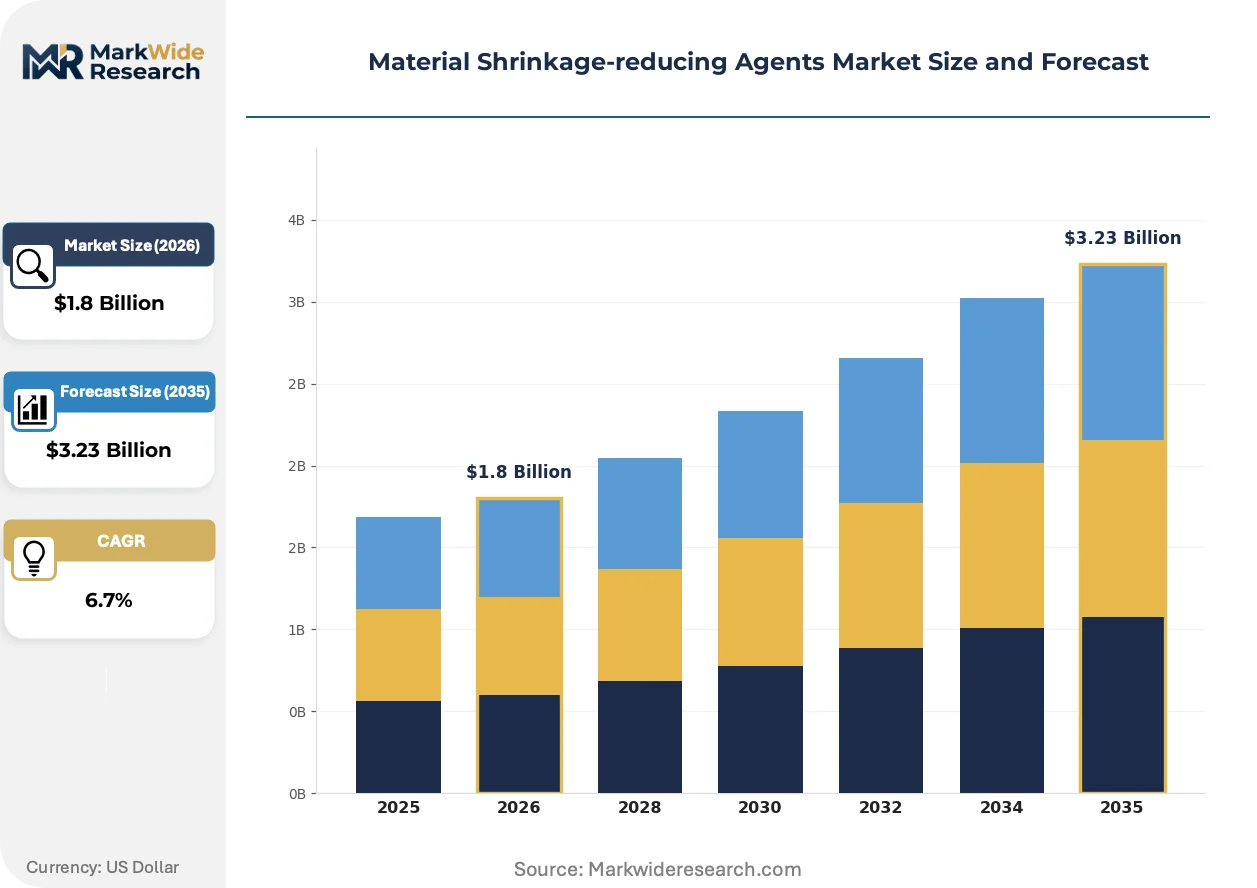
Market Dynamics
Infrastructure procurement concentration is restructuring competitive access in the shrinkage-reducing agent sector. Mega-project developers now specify admixture performance directly, bypassing traditional contractor intermediaries and compressing margin pools for undifferentiated suppliers.
Growth Catalysts
- China's Yangtze River Delta cluster:High-speed rail and port expansion in this megacity region drives bulk additive consumption at scale unmatched elsewhere.
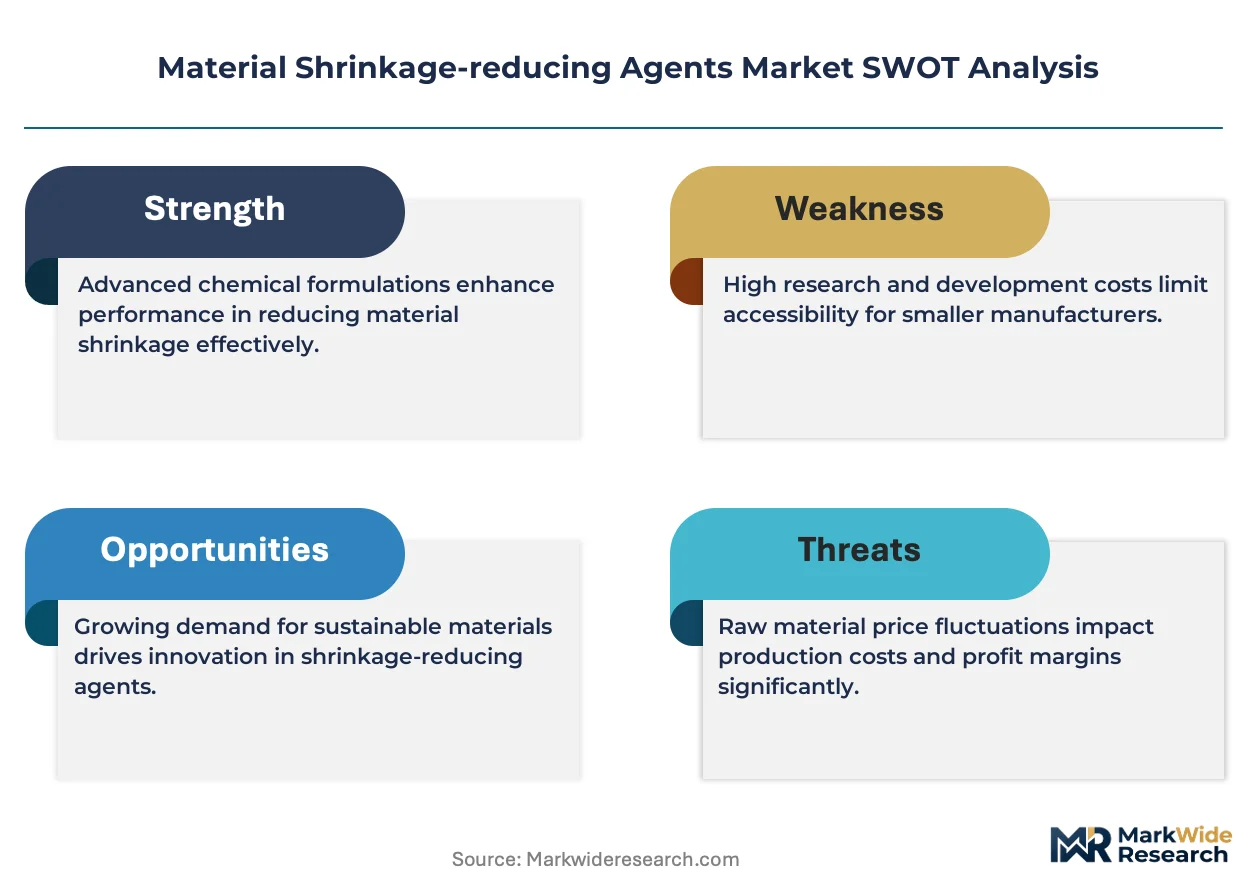
- EU F-Gas Regulation:Tightening thresholds on construction chemicals force product reformulation toward lower-emission glycol and polyether compounds.
- Precast fabrication automation:Factory-cured concrete elements demand dimensional tolerances below 0.3mm crack-width thresholds, mandating shrinkage-reducing admixtures.
Market Restraints
- Polyether raw material concentration:Backward integration into polyether supply chains remains limited to a handful of Asian chemical producers, creating input bottlenecks.
- REACH registration burdens:European toxicological dossier requirements for polyether active ingredients raise fixed compliance costs for import-dependent formulators.
- Performance variability in field conditions:Liquid agent efficacy degrades in extreme temperature batching environments, limiting specification confidence in remote jobsites.
Strategic Opportunities
- India's low-carbon building codes:Emerging credit systems for crack-resistant concrete formulations create new specification pathways for durability-focused admixtures.
- Powder agent distribution networks:Remote construction corridors lacking liquid handling infrastructure present margin expansion potential for dry-blend product lines.
- Ultra-high-performance concrete convergence:Glycol-based formulations meeting UHPC strength requirements open specification in seismic-resistant structural applications.
Industry Challenges
- Batching integration complexity:Ready-mix plant operators face calibration challenges when blending shrinkage-reducing agents at 0.5-2.0% cementitious weight ratios.
- GB 8076 compliance timelines:China's provincial enforcement variations create certification lag for multi-province suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Shrinkage-reducing Agents Market Trends and Innovations
Formulation chemistry and procurement protocols are undergoing parallel transformation. The sector is moving beyond commodity admixture supply toward performance-guaranteed systems integration.
Biopolymer-derived shrinkage-reducing compounds are supplanting petroleum-based polyethers in premium specification tiers. European precast fabricators have accelerated adoption of these bio-glycol formulations for carbon-accounted concrete projects. The shift is compressing conventional polyether margins while opening certification-driven premium pricing pools.
REACH registration requirements are tightening toxicological scrutiny on polyether active ingredients across European construction chemical markets. Formulators dependent on Asian polyether imports face extended dossier preparation cycles and elevated testing expenditures. Mid-tier suppliers are responding by consolidating active ingredient sourcing through established registrants.
Direct specification by infrastructure developers is displacing contractor-mediated procurement in mega-project channels. Owner-engineer agreements now embed admixture performance guarantees that bypass traditional ready-mix plant discretion. This pattern is most visible in China's high-speed rail procurement corridors and Nordic tunneling contracts.
Material Shrinkage-reducing Agents Market Segmentation
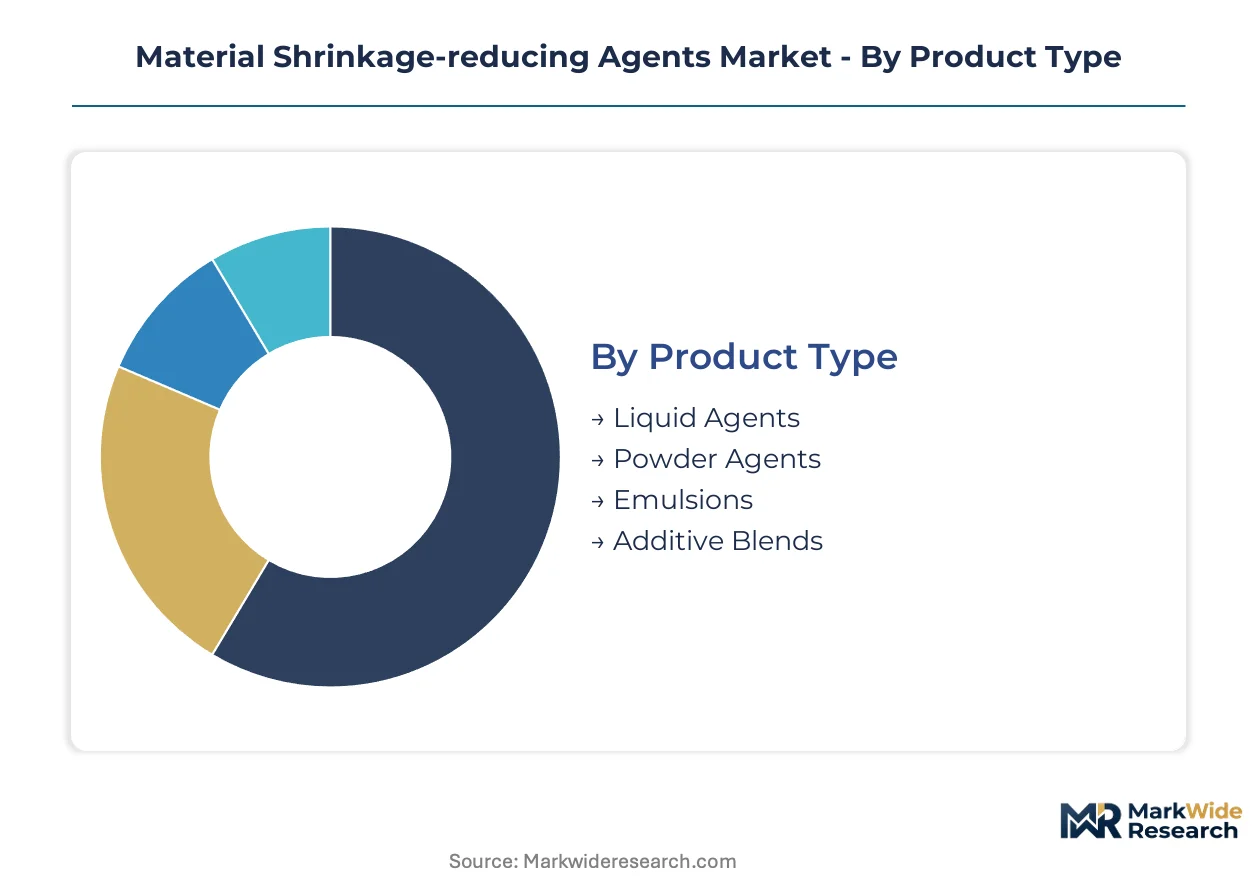
Segmentation in the shrinkage-reducing agent market reveals how formulation chemistry, application environment, and procurement channel intersect to determine margin capture. Suppliers must align product architecture with specific batching infrastructure and durability specifications to avoid commoditization.
Product Type:
Liquid agents command the deepest margin pools due to seamless integration with automated ready-mix batching systems, though powder formulations extract premium pricing in remote construction corridors lacking liquid handling infrastructure.
- Liquid Agents:Glycol and polyether solutions blended at 0.5-2.0% cementitious weight enable precise dosing through plant-mounted metering pumps. Demand concentrates in China's Yangtze River Delta megacity cluster where high-speed rail projects require continuous bulk supply chains.
- Powder Agents:Spray-dried formulations containing shrinkage-compensating polymers allow dry-blend compatibility with bagged cement distribution. Precast fabricators in Nordic tunneling contracts specify these for jobsites with intermittent liquid storage capacity.
- Emulsions:Water-based dispersions of active compounds stabilize polyether ingredients for extended shelf life in tropical climates.
- Additive Blends:Pre-formulated combinations with plasticizers or retarders reduce on-site batching complexity for small-scale contractors.
The dominant share belongs to liquid agents, while powder agents are closing the gap fastest as remote infrastructure corridors expand.
Application:
Volume flows concentrate in cast-in-place concrete, yet specification intensity and pricing power cluster in factory-controlled curing environments where dimensional tolerances drive admixture performance guarantees.
- Concrete Industry:Ready-mix producers incorporate shrinkage-reducing admixtures to meet GB 8076 durability codes for bridge decks and marine substructures. China's port expansion along the Pearl River Delta sustains bulk consumption at scale unmatched by other applications.
- Precast Fabrication:Factory-cured elements demand crack-width thresholds below 0.3mm, mandating glycol-based formulations with certified autogenous shrinkage control. EU F-Gas Regulation compliance pressures are accelerating bio-glycol adoption in carbon-accounted precast projects.
- Asphalt Production:Modified bitumen applications use shrinkage modifiers to reduce thermal cracking in polymer-modified pavements.
- Mortar Manufacturing:Dry-mix mortar plants specify powdered agents for thin-bed adhesive and rendering applications requiring minimal drying shrinkage.
Concrete industry applications retain volume leadership, though precast fabrication exhibits the steepest expansion trajectory as automation tightens dimensional specifications.
End Use Industry:
Procurement authority is migrating from general contractors toward infrastructure developers who specify admixture performance directly, compressing margin pools for undifferentiated suppliers serving traditional contractor channels.
- Infrastructure Developers:Mega-project owners now embed admixture performance guarantees in owner-engineer agreements, bypassing ready-mix plant discretion. China's high-speed rail procurement corridors exemplify this direct specification pattern.
- Construction Firms:General contractors face margin compression as developers capture procurement authority, though regional builders retain influence in residential and commercial mid-rise segments.
- Civil Engineering Firms:Design-build entities specify shrinkage-reducing agents for seismic-resistant structural applications requiring ultra-high-performance concrete convergence.
- Specialty Contractors:Tunneling and marine specialists demand certified formulations meeting project-specific durability codes with full toxicological dossier compliance.
Infrastructure developers hold the dominant procurement share, while specialty contractors are gaining specification influence fastest in technically demanding applications.
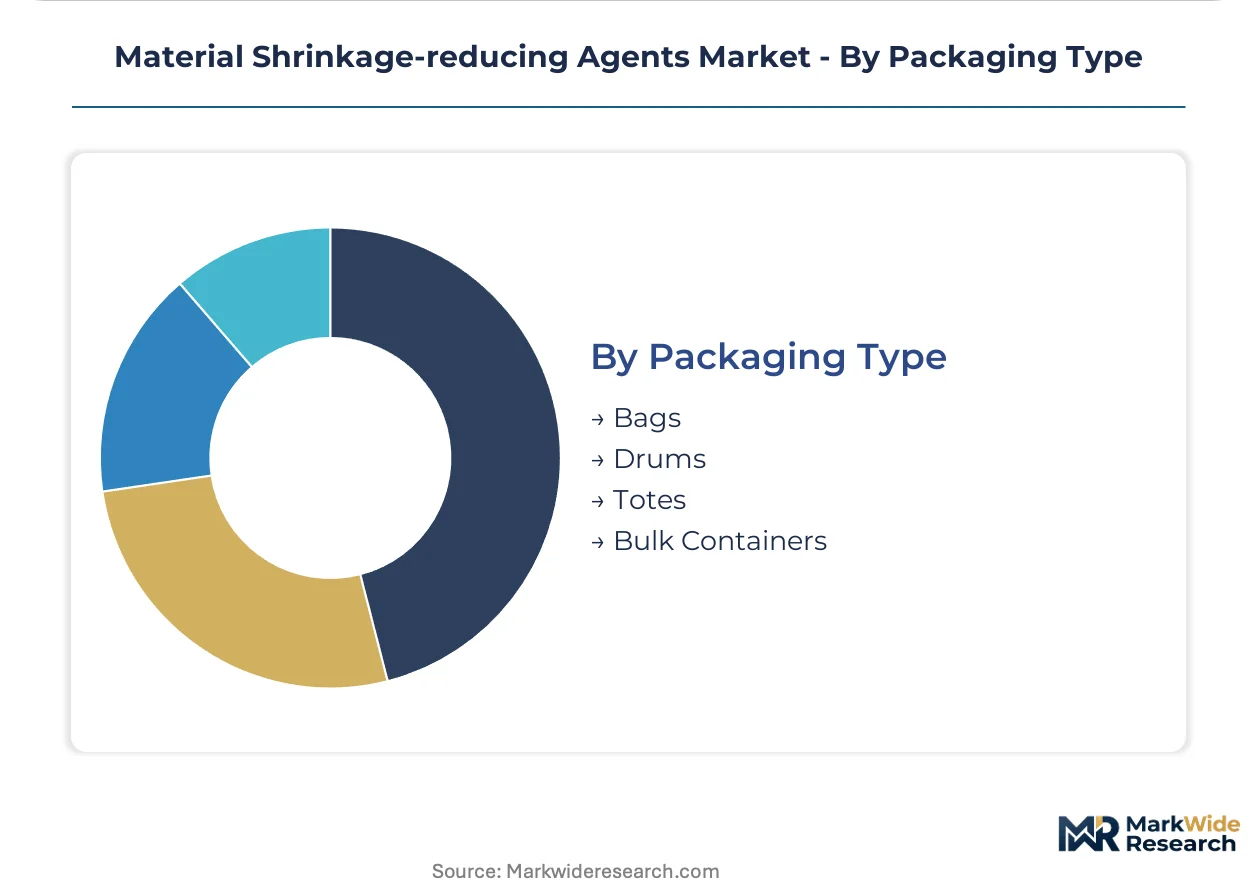
Packaging Type:
Packaging economics track batching scale and logistics infrastructure density, with bulk containers capturing margin in megaproject corridors while drums and totes serve fragmented regional markets.
- Bulk Containers:ISO tank and flexitank deliveries enable continuous supply to high-volume ready-mix plants with dedicated admixture storage. China's Yangtze River Delta cluster drives specification of bulk liquid handling systems.
- Drums:200-liter steel and polyethylene drums balance portability with volume efficiency for mid-scale precast fabricators lacking permanent storage infrastructure.
- Totes:Intermediate bulk containers serve remote jobsites requiring liquid agents where bulk tank installation is uneconomical.
- Bags:Multi-wall paper and woven polypropylene packaging dominates powder agent distribution to mortar manufacturers and small-batch concrete producers.
Bulk containers command the dominant volume share, though totes are expanding most quickly as distributed precast fabrication networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta high-speed rail network underwrites China's dominant position in shrinkage-reducing agent procurement, while EU F-Gas Regulation compliance pressures reshape European formulation chemistry. India's emerging low-carbon building codes and US infrastructure renewal programs complete the geographic demand matrix.
China
Port expansion along the Pearl River Delta and high-speed rail corridors drives bulk additive consumption at unmatched scale. SAMR enforces GB 8076 standards governing concrete admixture performance consistency across provincial construction markets. Shanghai and the broader Yangtze River Delta megacity cluster concentrate specification intensity for glycol-based formulations in mega-bridge and tunnel projects.
United States
Bridge deck rehabilitation and marine substructure renewal programs sustain ready-mix admixture demand along coastal corridors. EPA Clean Air Act Title V permitting governs VOC emissions from concrete admixture production facilities nationwide. Texas and California infrastructure authorities specify shrinkage-reducing agents directly in owner-engineer agreements, bypassing traditional contractor intermediaries.
Germany
Precast fabrication automation in factory-cured concrete elements mandates crack-width thresholds below 0.3mm for structural durability. REACH registration requirements compel toxicological dossier submission for polyether active ingredients, elevating compliance costs for import-dependent formulators. The Ruhr industrial corridor and Bavarian construction chemical clusters anchor glycol-based formulation R&D for carbon-accounted concrete projects.
India
Emerging low-carbon building codes credit crack-resistant concrete formulations toward embodied carbon reduction targets, creating new specification pathways. BIS standards govern construction chemical quality benchmarks across state-level procurement systems. Maharashtra and Gujarat industrial zones concentrate precast fabrication capacity where factory-cured elements demand tighter dimensional tolerances.
United Arab Emirates
Desert climate construction and coastal marine infrastructure drive specification of emulsion-stabilized polyether formulations for tropical shelf-life requirements. MOHAP and local environmental regulators enforce construction chemical import standards aligned with Gulf Cooperation Council technical regulations. Dubai and Abu Dhabi mega-project developers embed admixture performance guarantees directly in procurement contracts, compressing margin pools for undifferentiated suppliers.
Material Shrinkage-reducing Agents Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized construction material formulators. The vendor base spans three tiers: multinational chemical majors with captive R&D infrastructure, regional construction chemical specialists with backward integration into polyether supply chains, and commodity admixture blenders serving fragmented contractor channels. Competitive dynamics center on formulation certification speed and direct specification relationships with infrastructure developers. M&A activity targets regional formulators with established GB 8076 or REACH dossier libraries. Geographic expansion into India's emerging low-carbon code environment represents the dominant growth vector.
Among European-based chemical majors, BASF SE and Sika AG exemplify the R&D-intensive archetype with glycol-based formulation portfolios. MUHU (China) Construction Materials Co., Ltd. represents the regional specialist model with upstream integration into polyether raw materials. These three anchors illustrate the competitive spectrum: multinational scale, regional supply chain control, and emerging market proximity each occupy distinct positioning tiers in developer-direct procurement channels.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Mapei S.p.A. |
| Fosroc International Ltd. |
| Saint-Gobain |
| RPM International Inc. |
| Euclid Chemical Company |
| Cementaid International Group |
| MUHU (China) Construction Materials Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
REACH registration requirements for polyether active ingredients gate both supplier qualification and price differentiation simultaneously. European formulators face elevated fixed costs for toxicological dossiers, compressing mid-tier margins while enabling certified suppliers to command premium positioning for carbon-accounted concrete projects.
Pricing Analysis
Volume-discount tiering structures separate bulk procurement contracts for China's Yangtze River Delta infrastructure corridors from spot purchases by remote precast fabricators. Price differentiation hinges on REACH certification status and backward integration into polyether raw materials. Cost compression in standard-grade liquid agents is intensifying because Asian import-dependent formulators face extended dossier preparation cycles. Regional contractors in India's emerging low-carbon building code environment exhibit highest price sensitivity, while Nordic tunneling specialists demonstrate lowest sensitivity due to performance-guaranteed procurement protocols.
Supply Chain Analysis
China and South Korea anchor polyether raw material production for shrinkage-reducing agent formulation. Active ingredient supply draws from petroleum-based glycol derivatives and emerging bio-glycol fermentation capacity. Single-source vulnerability concentrates in Yangtze River Delta chemical clusters where MEE environmental inspections intermittently disrupt output. Distribution runs through ISO tank deliveries to high-volume ready-mix plants and drum shipments to remote precast fabrication networks lacking permanent storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and regulatory dossier libraries constitute scarce capabilities that determine competitive survival. Suppliers lacking REACH registration or GB 8076 certification face systematic exclusion from developer-direct procurement channels.
For Market Incumbents: Shield margin pools by accelerating bio-glycol formulation R&D ahead of EU F-Gas Regulation tightening. Deepen backward integration into polyether supply chains to offset raw material concentration risk from Asian chemical producers. Secure direct specification relationships with infrastructure developers in China's high-speed rail procurement corridors before contractor intermediaries lose remaining influence. For New Entrants and Emerging Players: Differentiate on powder agent distribution networks serving remote construction corridors lacking liquid handling infrastructure. India's emerging low-carbon building codes offer the most penetrable geography for durability-focused admixtures. Pursue joint development agreements with precast fabricators seeking certified autogenous shrinkage control for factory-cured elements. For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by elevating the value of established REACH dossier libraries. Long-term viability favors formulators with demonstrated compliance infrastructure over commodity blenders dependent on spot ingredient sourcing. Monitor SAMR enforcement variations across Chinese provinces as the critical signal for multi-province supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Supply | MUHU's captive raw material production insulates margin from Asian chemical producer bottlenecks. |
| REACH Dossier Library Acquisition | Mid-tier European formulators consolidate active ingredient sourcing through established registrants to compress compliance timelines. |
| Bio-Glycol Formulation Transition | European precast fabricators accelerate adoption of biopolymer-derived compounds for carbon-accounted concrete projects. |
| Powder Agent Distribution Expansion | Dry-blend compatibility opens remote construction corridors lacking liquid handling infrastructure to premium pricing. |
| Direct Specification Relationship Development | Infrastructure developers in China's high-speed rail corridors now embed admixture performance guarantees bypassing contractor discretion. |
Research Methodology
A standing panel of ready-mix plant operators, precast fabrication technical directors, infrastructure procurement officers, and construction chemical R&D leads provided ongoing calibration across the study period. Primary interview findings triangulated against secondary sources including SAMR GB standards documentation, ECHA REACH registration databases, EPA Clean Air Act permitting records, and customs trade data for polyether raw material flows. Bottom-up volume estimates from application-level consumption patterns reconciled with top-down market sizing from supplier revenue disclosures.
Consistency checks validated volume and value outputs against ACC construction chemical reports and provincial Chinese infrastructure investment disclosures across the projection horizon. Segmentation modeling incorporated product type chemistry tiers, application environment control levels, end-use industry procurement authority, and regional regulatory framework clusters. CAGRs derived from trend-line analysis of historical consumption patterns and elasticity-adjusted demand projections. Industry-specific forecast inputs included high-speed rail mileage expansion timelines and precast fabrication automation adoption curves.
Material uncertainties — polyether supply disruptions from MEE environmental enforcement, REACH registration timeline extensions for bio-glycol alternatives, and provincial GB 8076 compliance variations — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained infrastructure investment intensity and gradual F-Gas Regulation implementation pacing. Recalibration cycles align with material shifts in low-carbon building code adoption and developer-direct procurement penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.