
 Cellulose Ether Market | 2026-2036
Cellulose Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Ether Market Analysis
Chinese specialty chemical producers is realigning cellulose ether capacity toward pharmaceutical-grade output. Nouryon leverages its integrated wood-pulp supply chain to sustain cost advantages across European and Asian markets. Dow Chemical Company anchors North American demand through construction-focused methylcellulose distribution networks. Ashland Global Holdings Inc. differentiates via pharmaceutical excipient certification and controlled-release formulation expertise.
Cellulose ethers are water-soluble polymers derived from cellulose through etherification with alkyl or hydroxyalkyl substituents, typically exhibiting viscosity ranges from 5 to 100,000 mPa·s depending on degree of substitution and molecular weight; these polymers function primarily as thickeners, binders, film-formers, and rheology modifiers across industrial and consumer formulations. Hydroxypropyl methylcellulose dominates construction applications where water retention and open-time extension command premium positioning, while carboxymethylcellulose leads food and beverage stabilization with mature margin pools in commodity-grade supply. Ethylcellulose occupies the fastest-growing niche in pharmaceutical controlled-release coatings as oral solid dosage form complexity intensifies.
EPA industrial chemical reporting requirements and REACH substance registration obligations shape product composition transparency and market access conditions for cellulose ether imports into the United States and European Union. China's MEE environmental compliance audits and GB standards on industrial wastewater discharge are forcing etherification plant upgrades that filter marginal producers from export supply chains. India's CDSCO excipient quality guidelines and BIS certification mandates for construction additives are tightening specification thresholds for market entry. Stakeholders must monitor regulatory divergence between pharmaceutical-grade and industrial-grade compliance pathways to anticipate where certification investments will concentrate.
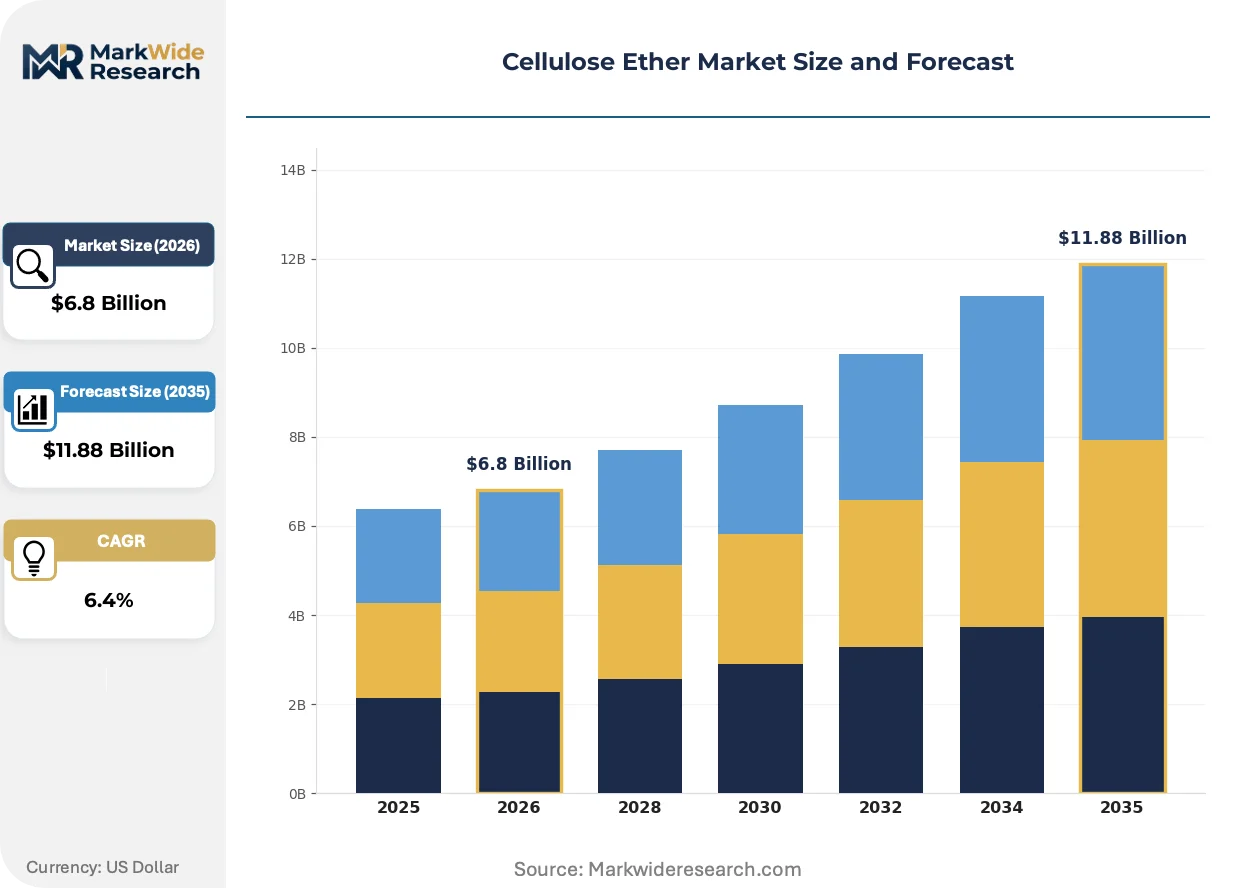
Market Dynamics
China's MEE environmental audits are forcing etherification plant upgrades that filter marginal producers from export supply chains, concentrating cellulose ether manufacturing among integrated pulp-to-ether operators with captive wastewater treatment capabilities.
Growth Catalysts
- Construction-grade water retention demand:Infrastructure contractors in India's western industrial corridor specify hydroxypropyl methylcellulose for workability improvements in high-temperature pouring conditions.
- REACH substance registration obligations:ECHA transparency requirements for industrial chemical imports are accelerating pharmaceutical-grade certification investments among European cellulose ether distributors.
- Controlled-release coating complexity:Oral solid dosage form manufacturers are absorbing ethylcellulose into multi-layer tablet architectures for sustained-release hypertension therapies.
Market Restraints
- Wood pulp input cost volatility:Dissolving-grade pulp prices fluctuate with Nordic forestry harvest cycles and energy-intensive bleaching costs.
- Chinese supply concentration risk:Shandong and Jiangsu provinces host over half of Asia's etherification capacity, exposing buyers to regional environmental shutdown orders.
- Petrochemical substitute encroachment:Synthetic rheology modifiers from acrylamide chemistry compete in construction applications where water retention specifications allow formulation flexibility.
Strategic Opportunities
- Pharmaceutical excipient underpenetration in Brazil:ANVISA's alignment with IPEC-PQG excipient qualification guidelines opens certification pathways for imported cellulose ethers.
- Clean-label food stabilization:FSSAI's tightening restrictions on synthetic thickeners position carboxymethylcellulose for yogurt and beverage applications.
- MEE wastewater discharge incentives:China's dual carbon goals reward etherification plants adopting enzymatic pretreatment and closed-loop solvent recovery systems.
Industry Challenges
- Pharmaceutical excipient master file compilation:CDSCO and FDA DMF requirements demand 12-18 month documentation timelines for new cellulose ether suppliers.
- Legacy batch reactor retrofit costs:Continuous etherification technology requires $15-25 million per production line, straining mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Ether Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxypropyl Methylcellulose, Methylcellulose, Carboxymethylcellulose, Ethylcellulose Application: Pharmaceuticals, Food & Beverages, Construction, Personal Care End User: Healthcare, Food Industry, Construction Companies, Cosmetic Manufacturers Form: Powder, Granules, Solution, Gel |
| Companies Covered | Nouryon, Lotte Fine Chemical, Dow Chemical Company, Shandong Head Co., Ltd., SE Tylose, Ashland Global Holdings Inc., BASF SE, Daicel Corporation, Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Ether Market Emerging Trajectories
Etherification chemistry is pivoting toward enzymatic catalysis and solvent recovery systems that reduce environmental compliance costs while enabling pharmaceutical-grade purity thresholds.
Enzymatic etherification using laccase-mediator systems is absorbing capital allocation from traditional alkali-catalyzed processes. Specialty chemical producers in Germany and Japan pilot these biotransformations to eliminate chlorinated byproduct formation. The technology is absorbing market share in pharmaceutical-grade methylcellulose where residual solvent limits approach single-digit ppm specifications.
REACH Annex XVII restrictions on volatile organic compound emissions in industrial coatings are tightening solvent-based ethylcellulose formulation allowances. Coating manufacturers reformulate with aqueous ethylcellulose dispersions or alternative polymer systems. Oral solid dosage form producers in the Netherlands and Switzerland accelerate qualification of aqueous coating grades to preempt supply discontinuation.
Specification-driven procurement now dominates pharmaceutical excipient sourcing, with buyers demanding IPEC-PQG certification, elemental impurity testing per ICH Q3D, and supply chain transparency documentation. Distributors with integrated quality laboratories and regional warehousing are displacing traditional trading houses in Western European and North American supply chains. This pattern concentrates most visibly among generic drug manufacturers in Ireland and contract development organizations in Massachusetts.
Cellulose Ether Market Segmentation
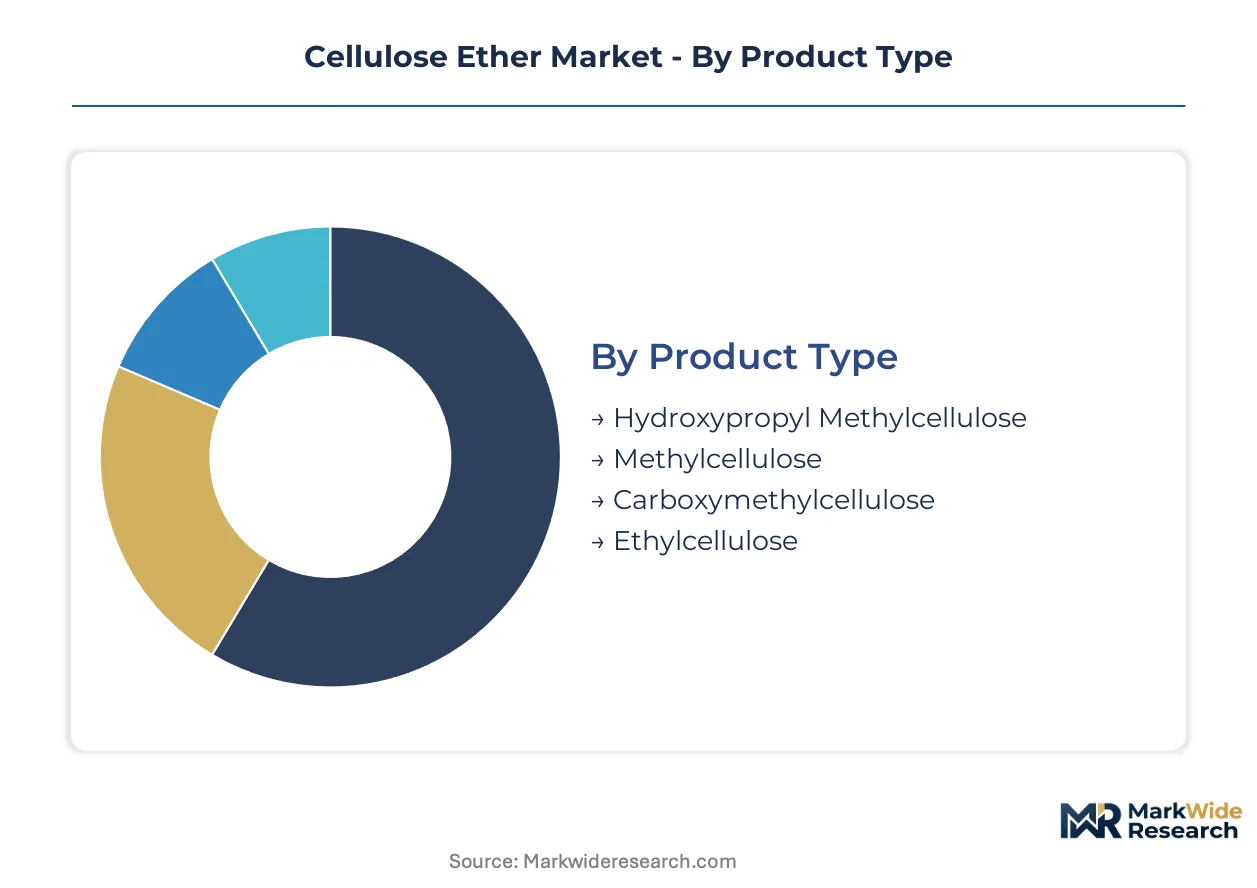
Cellulose ether specifications diverge sharply across end-use certifications, with pharmaceutical-grade purity thresholds commanding fundamentally different production economics than construction-grade formulations. Manufacturers configure etherification plants around either high-margin excipient batches or commodity-scale industrial output.
Product Type:
Replacement cycles in construction-grade formulations accelerate as contractors adopt higher-viscosity grades for extreme-climate pouring, while pharmaceutical applications demand generational upgrades in residual solvent control.
- Hydroxypropyl Methylcellulose:This ether combines methoxy and hydroxypropoxy substituents to deliver thermal gelation and superior water retention. Infrastructure contractors in India's western industrial corridor specify HPMC for workability improvements in high-temperature pouring conditions.
- Ethylcellulose:A thermoplastic cellulose ether with ethoxy substitution enabling moisture-barrier film formation. Oral solid dosage form manufacturers absorb ethylcellulose into multi-layer tablet architectures for sustained-release hypertension therapies.
- Carboxymethylcellulose:Anionic water-soluble polymer dominating food stabilization with mature margin pools in commodity-grade supply.
- Methylcellulose:Non-ionic etherification product serving construction and food applications where thermal gelation properties control formulation behavior.
Volume placements concentrate in Hydroxypropyl Methylcellulose; the faster expansion belongs to Ethylcellulose.
Application:
Cost tiers separate pharmaceutical excipient certification investments from commodity construction additives, with margin structures diverging by an order of magnitude across these pathways.
- Construction:Hydroxypropyl methylcellulose dominates water-retention and open-time extension specifications. Infrastructure contractors in high-temperature zones absorb premium-grade HPMC despite synthetic rheology modifier competition.
- Pharmaceuticals:Controlled-release coating complexity intensifies demand for ethylcellulose and hypromellose in oral solid dosage forms. CDSCO and FDA DMF documentation timelines stretch 12-18 months for new suppliers.
- Food & Beverages:Carboxymethylcellulose leads yogurt and beverage stabilization as FSSAI tightens synthetic thickener restrictions.
- Personal Care:Film-forming methylcellulose grades serve cosmetic formulations where rheology modification drives sensory performance.
Revenue concentration sits with Construction; Pharmaceuticals climbs the fastest.
End User:
Customer procurement sophistication varies dramatically, with healthcare formulators demanding IPEC-PQG certification and elemental impurity testing while construction buyers prioritize volume pricing and logistics reliability.
- Healthcare:Generic drug manufacturers and contract development organizations drive excipient specification intensity. Distributors with integrated quality laboratories displace traditional trading houses in Western European and North American supply chains.
- Construction Companies:Infrastructure contractors specify cellulose ethers for water retention in cementitious systems. India's western industrial corridor concentrates demand as pharmaceutical excipient consumption rises.
- Food Industry:Clean-label positioning accelerates carboxymethylcellulose adoption in yogurt and beverage applications.
- Cosmetic Manufacturers:Personal care formulators absorb methylcellulose for film-forming and thickening functions.
Procurement volume clusters with Construction Companies; Healthcare expands most quickly.
Form:
Supply chain configuration favors powder handling infrastructure, though solution and gel formats capture value-added formulation services for time-sensitive pharmaceutical customers.
- Powder:Standard bulk format enabling flexible reconstitution across construction and industrial applications. Dissolving-grade pulp feedstock quality directly determines powder solubility performance.
- Solution:Pre-hydrated format serving pharmaceutical coating operations where batch consistency commands premium positioning.
- Granules:Intermediate flowability format reducing dust exposure in high-volume construction additive handling.
- Gel:Concentrated aqueous dispersions for personal care and specialized pharmaceutical applications.
Shipment volumes aggregate in Powder; Solution gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dissolving-grade wood pulp availability from Nordic forestry operations anchors European cellulose ether production economics. Asian manufacturing clusters in Shandong and Jiangsu provinces command etherification capacity concentration. North American demand absorbs construction-grade and pharmaceutical-grade imports through integrated distributor networks.
China
Shandong and Jiangsu provinces host over half of Asia's etherification capacity, exposing buyers to regional environmental shutdown orders. MEE environmental compliance audits and GB standards on industrial wastewater discharge are forcing etherification plant upgrades that filter marginal producers from export supply chains. Integrated pulp-to-ether operators with captive wastewater treatment capabilities are concentrating manufacturing around these coastal industrial zones.
United States
Infrastructure contractors absorb hydroxypropyl methylcellulose for water retention and open-time extension in cementitious systems. EPA industrial chemical reporting requirements shape product composition transparency and market access conditions for cellulose ether imports. Construction-grade distribution networks concentrate demand absorption through Gulf Coast and Midwest logistics corridors serving high-temperature pouring zones.
Germany
Specialty chemical producers pilot enzymatic etherification using laccase-mediator systems to eliminate chlorinated byproduct formation. REACH substance registration obligations and ECHA transparency requirements for industrial chemical imports accelerate pharmaceutical-grade certification investments among European cellulose ether distributors. The Rhine-Ruhr industrial cluster anchors enzymatic catalysis pilot programs targeting single-digit ppm residual solvent specifications.
India
Pharmaceutical excipient consumption rises in the western industrial corridor around Maharashtra and Gujarat states. CDSCO excipient quality guidelines and BIS certification mandates for construction additives tighten specification thresholds for market entry. Mumbai-Pune pharmaceutical manufacturing clusters drive specification-driven procurement for oral solid dosage form applications.
Brazil
ANVISA's alignment with IPEC-PQG excipient qualification guidelines opens certification pathways for imported cellulose ethers in oral solid dosage form manufacturing. Generic drug manufacturers in São Paulo state absorb ethylcellulose for controlled-release hypertension therapies. The southeastern industrial corridor concentrates pharmaceutical formulation demand as regulatory harmonization accelerates.
Cellulose Ether Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and enzymatic process technology. The vendor base stratifies between integrated pulp-to-ether operators with captive raw material supply and specialty chemical distributors with regional warehousing and quality laboratory infrastructure. Three archetypes dominate: Nordic-Asian integrated producers, European-Japanese specialty chemical houses, and regional trading distributors. Competitive moves concentrate on backward integration into dissolving-grade pulp supply and strategic partnerships with pharmaceutical contract development organizations.
Within the integrated producer tier, Nouryon leverages its wood-pulp supply chain positioning across European and Asian markets. Dow Chemical Company anchors North American construction-grade distribution networks. Ashland Global Holdings Inc. occupies the pharmaceutical excipient certification vector with controlled-release formulation expertise. These three entities exemplify how geographic raw material access and end-use certification depth determine competitive positioning in etherification markets.
| Leading Market Players |
|---|
| Nouryon |
| Lotte Fine Chemical |
| Dow Chemical Company |
| Shandong Head Co., Ltd. |
| SE Tylose |
| Ashland Global Holdings Inc. |
| BASF SE |
| Daicel Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Infrastructure contractors in India's western industrial corridor now mandate IPEC-PQG-certified cellulose ethers for pharmaceutical-adjacent construction projects, forcing suppliers to absorb certification costs or forfeit premium-tier positioning. This specification creep compresses margins on commodity-grade output while concentrating pricing power among integrated pulp-to-ether operators with captive quality laboratories.
Pricing Analysis
Service bundling separates pharmaceutical-grade suppliers offering DMF compilation support from unbundled commodity traders. Three-tier pricing structure across pharmaceutical, construction-premium, and construction-standard levels reflects certification depth and residual solvent control. Cost compression in construction-standard tiers intensifies as Shandong producers absorb MEE compliance investments. Generic drug manufacturers in Ireland and Massachusetts exhibit lowest price sensitivity; cement additive distributors in Gulf Coast logistics corridors drive hardest volume negotiations.
Supply Chain Analysis
Dissolving-grade pulp supply rests on Nordic forestry operations, Chinese cotton linter processors, and Southeast Asian hardwood plantations. Etherification capacity concentrates in Shandong and Jiangsu provinces, with secondary nodes in the Rhine-Ruhr cluster and Gujarat state. Single-source vulnerability runs through Chinese environmental shutdown exposure. Distribution runs through integrated distributors with regional warehousing and quality laboratory infrastructure displacing traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic etherification chemistry is displacing legacy alkali-catalyzed processes, rewarding producers who retrofit batch reactors with laccase-mediator systems and closed-loop solvent recovery. This transition window favors capital-rich incumbents and specialized technology licensors over marginal commodity operators.
For Market Incumbents: Extend pharmaceutical-grade certification coverage into Brazilian and Indian oral solid dosage form markets before ANVISA and CDSCO guidelines harden. Deepen backward integration into dissolving-grade pulp supply to insulate margin structures from Nordic harvest cycle volatility. Synthetic rheology modifier encroachment in construction applications demands premium-tier positioning through technical service bundling.
For New Entrants and Emerging Players: Launch via contract development organization partnerships in Massachusetts and Ireland, leveraging specification-driven procurement concentration among generic drug manufacturers. Target aqueous ethylcellulose dispersion qualification for Netherlands and Switzerland coating manufacturers facing REACH Annex XVII solvent restrictions. White-space opportunity sits with enzymatic process technology licensing to mid-cap producers avoiding legacy retrofit costs.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated pulp-to-ether operators given MEE environmental audit consolidation and pharmaceutical-grade margin expansion. Long-term viability over the next decade hinges on enzymatic catalysis adoption and dual carbon goal alignment in Chinese manufacturing footprints. The signal to watch is CDSCO and FDA DMF approval velocity for new cellulose ether suppliers as a proxy for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Retrofit | Laccase-mediator systems eliminate chlorinated byproducts for single-digit ppm pharmaceutical specifications. |
| Backward Integration into Pulp Supply | Captive dissolving-grade pulp sourcing insulates margin structures from Nordic forestry harvest volatility. |
| Pharmaceutical DMF Compilation | CDSCO and FDA documentation investments unlock specification-driven procurement among generic drug manufacturers. |
| Aqueous Coating Grade Qualification | REACH Annex XVII compliance enables continued supply to Netherlands and Switzerland oral solid dosage form producers. |
| Regional Quality Laboratory Expansion | Integrated warehousing and testing infrastructure displaces traditional trading houses in Western European distribution. |
Methodological Framework
Trade databases, SEC filings from specialty chemical producers, and ECHA REACH registration records formed the secondary backbone for this analysis. Primary interviews with etherification plant managers, pharmaceutical procurement leads at contract development organizations, construction additive distributors, and technical R&D directors at cellulose ether manufacturers validated demand-side assumptions. Bottom-up segment sizing across product type, application, and grade tier triangulated against top-down pulp consumption and etherification capacity estimates.
Historical trendline analysis of dissolving-grade pulp pricing, etherification plant operating rates, and pharmaceutical excipient import volumes anchored the projection framework. Segmentation modeling incorporated grade tier, end-use industry, certification level, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements across the analysis window. Forecast inputs included MEE environmental compliance audit schedules and IPEC-PQG certification adoption curves.
The model assumes a particular technology adoption path; alternative pathways for enzymatic etherification would alter the outlook if laccase-mediator systems achieve cost parity with alkali-catalyzed processes faster than baseline assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and pulp supply elasticity. A small set of triggers warrants ongoing watch: Chinese environmental shutdown orders, CDSCO excipient guideline revisions, and REACH Annex XVII solvent restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Sophorolipids Market
Specialty Chemicals
Global Non-Halogenated Flame Retardants Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Copovidone Market