
 Global Scale Inhibitors Market | 2026-2036
Global Scale Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scale Inhibitors Market Foresight
The EU Green Deal's water reuse and efficiency mandates is broadening addressable demand for low-phosphorus scale inhibitor formulations across European industrial water treatment. Solvay leverages its phosphonate specialty portfolio to serve power generation and oilfield accounts with tailored threshold inhibition chemistries. Kemira sustains competitive position through backward integration into phosphorus raw materials and captive supply of polymeric dispersants. Dow anchors its presence with aminophosphonate manufacturing scale and deep channel control across North American cooling water treatment providers.
Scale inhibitors are chemical formulations—typically phosphonates, polymers, or aminophosphonates—designed to disrupt crystal nucleation and growth on heat transfer surfaces, operating at threshold concentrations below stoichiometric levels to prevent calcium carbonate, calcium sulfate, and barium sulfate deposition in aqueous systems. Phosphonates retain the largest volume share in mature boiler and cooling tower applications where cost-performance ratios favor established chemistries, while polymer-based formulations represent the fastest-expanding category as biodegradable alternatives displace phosphorus-heavy legacy products under tightening discharge regulations. The oilfield application segment commands premium pricing due to extreme downhole conditions requiring thermally stable phosphonate esters, whereas water treatment for power generation constitutes the deepest volume pool with recurring consumption tied to plant operating hours.
EPA effluent limitation guidelines in the United States restrict phosphorus discharge from industrial cooling systems, directly shaping product substitution patterns toward polymer and aminophosphonate alternatives. REACH registration requirements in Europe impose toxicity testing burdens that favor incumbent suppliers with established dossiers, raising barriers for new market entrants. China's MEE enforces increasingly strict wastewater discharge standards for thermal power plants, driving adoption of advanced scale control programs. Stakeholders must monitor regulatory divergence between phosphorus-constrained jurisdictions and markets where cost-driven phosphonate use persists, as this split will determine regional formulation strategies and manufacturing footprint decisions.
Market Dynamics
Regulatory phosphorus discharge limits are fragmenting formulation strategies between jurisdictions, forcing manufacturers to maintain parallel product portfolios while biodegradable polymer alternatives capture share in constrained markets.
Growth Catalysts
- EU Green Deal water mandates:The EU Green Deal's water efficiency directives are compelling industrial facilities across Germany, France, and the Netherlands to substitute phosphorus-heavy scale inhibitors with biodegradable polymer alternatives.
- China desalination buildout:State-backed desalination and industrial water reuse projects in Shandong and Jiangsu provinces are generating concentrated demand for advanced phosphonate and polymer scale control chemistries.
- Power generation capacity expansion:Thermal power plant construction across India and Southeast Asia is expanding recurring chemical treatment programs to protect boiler and cooling infrastructure.
Market Restraints
- Phosphorus raw material concentration:Phosphate rock mining concentrates in Morocco, China, and Western Sahara, exposing phosphonate manufacturers to geopolitical supply disruptions and export quota volatility.
- REACH registration burdens:ECHA toxicity testing and dossier maintenance requirements impose fixed costs that disproportionately burden smaller formulators seeking European market access.
- Biopolymer performance gaps:Polyaspartate and polymaleic acid alternatives exhibit thermal stability limitations above 80°C that restrict substitution in high-pressure boiler applications.
Strategic Opportunities
- US EPA phosphorus discharge rules:Pending effluent limitation guideline updates for industrial cooling systems will accelerate aminophosphonate and polymer adoption across Texas, California, and Ohio manufacturing corridors.
- Closed-loop cooling systems:Zero liquid discharge mandates in water-stressed regions are creating demand for synergistic scale-corrosion-dispersant packages in semiconductor and data center cooling.
- Digital chemical monitoring integration:IoT-enabled dosing controllers are enabling predictive scale inhibitor feed optimization, opening subscription revenue streams for chemical suppliers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in threshold inhibition kinetics and polymer-phosphonate synergies is concentrating at incumbent suppliers, constraining R&D expansion.
- Multi-jurisdiction registration timelines:Parallel EPA, REACH, and China's MEE approval processes extend product launch cycles to 24-36 months for novel biodegradable actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scale Inhibitors Market |
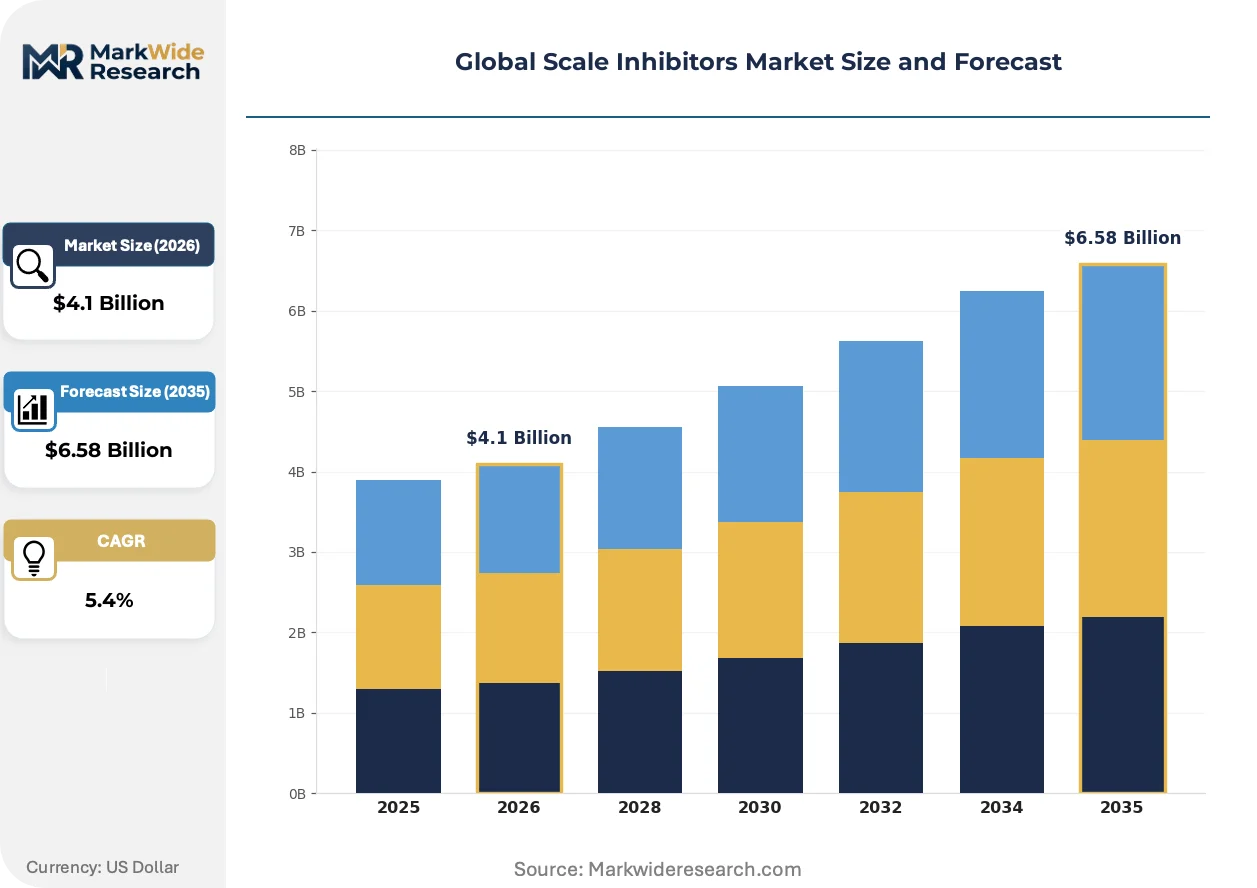
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphonates, Polyphosphates, Polymers, Aminophosphonates, Phosphonates Esters Application: Water Treatment, Oilfield, Cooling Systems, Boilers, Detergents End User Industry: Power Generation, Oil & Energy, Chemical Processing, Paper & Pulp, Textiles Packaging Type: Liquid, Powder, Granules, Tablets |
| Companies Covered | Solvay, Kemira, BASF SE, Solenis, Akzo Nobel N.V., Ecolab, Clariant, Ashland, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scale Inhibitors Market Shifts & Advancements
Formulation chemistry is bifurcating between legacy phosphonate optimization and next-generation biodegradable polymer development, with digital dosing integration emerging as the operational bridge between these parallel tracks.
Polyaspartate and polymaleic acid derivatives are overtaking traditional phosphonates in European cooling water treatment. These biodegradable polymers disrupt calcium carbonate nucleation through threshold inhibition mechanisms comparable to phosphonates. German and Dutch power utilities are adopting them at scale under EU Green Deal discharge mandates. This chemistry transition is compressing margins on commodity phosphonate volumes while opening premium positioning for suppliers with validated biodegradability dossiers.
REACH registration requirements are tightening toxicity data standards for existing scale inhibitor substances. ECHA's updated guidance demands enhanced aquatic toxicity endpoints and endocrine disruption screening for phosphonates and polymers alike. Formulators with pre-2010 dossiers face significant retrospective testing costs. Incumbent suppliers with established registration portfolios are leveraging this friction to defend market position against new entrants.
Power plant operators are consolidating chemical procurement through integrated water treatment service contracts. Long-term supply agreements bundling scale inhibitors with corrosion inhibitors and microbiocides are displacing spot chemical purchasing. This bundling concentrates purchasing authority at corporate engineering departments and reduces supplier count per facility. The shift is most pronounced in US independent power producers and Chinese state-owned generation groups seeking operational simplification.
Global Scale Inhibitors Market Segmentation
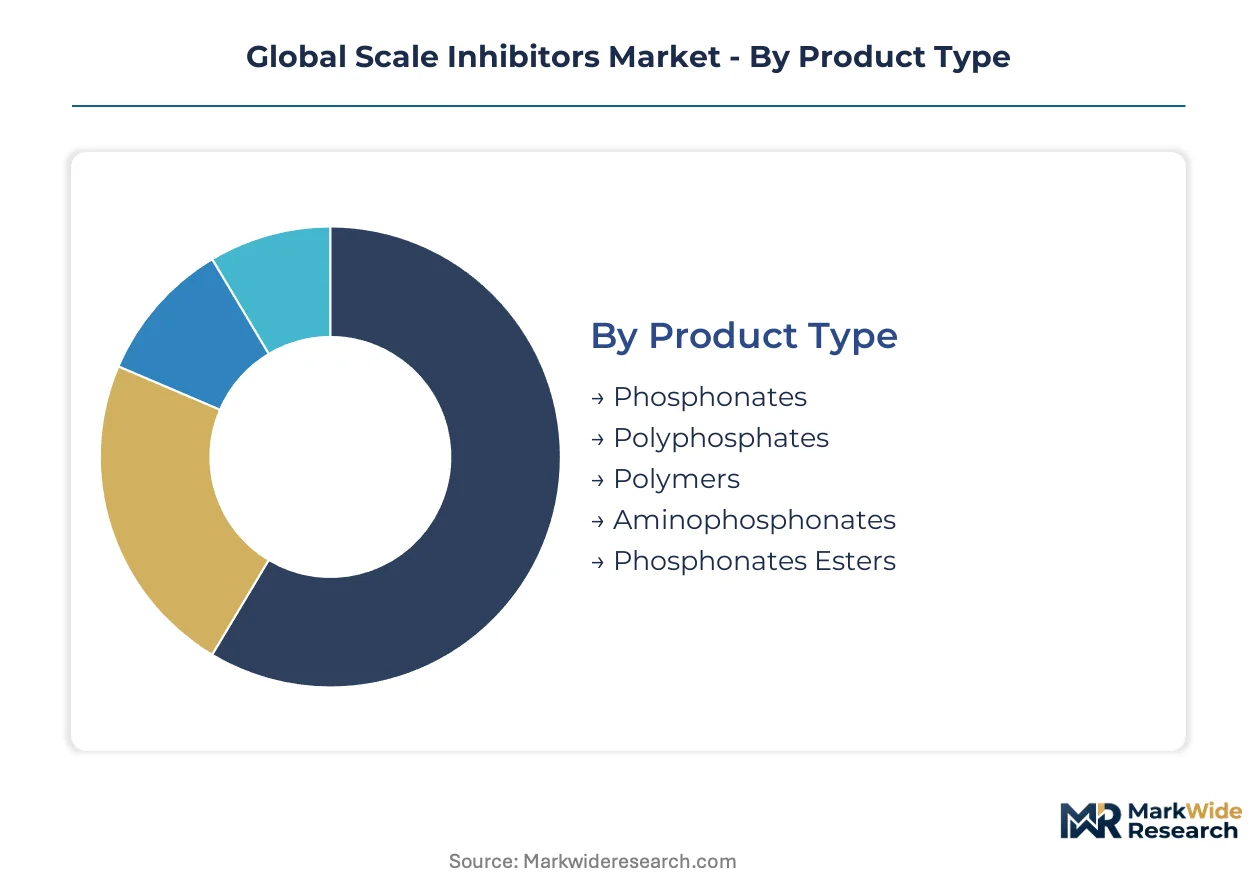
Scale inhibitor purchasing patterns diverge sharply across product chemistries, application severity, and end-user operational requirements. Buyers prioritize thermal stability thresholds in oilfield and boiler applications while favoring biodegradability credentials in cooling and municipal water treatment. Understanding these segmentation fault lines reveals where formulation premiums command pricing power versus where commodity substitution prevails.
Product Type:
Cost-performance tradeoffs separate buyers selecting legacy phosphonates from those paying premiums for biodegradable polymer alternatives.
- Phosphonates:Organophosphorus compounds including HEDP, ATMP, and PBTC deliver threshold inhibition at 2-10 ppm dosages against calcium carbonate and sulfate scales. Power plants in India and Indonesia rely on phosphonates for boiler feedwater treatment where cost efficiency outweighs discharge constraints. EPA phosphorus discharge rules in Texas and Ohio are compressing addressable demand for straight phosphonate formulations.
- Polymers:Polyacrylic acid, polymaleic acid, and polyaspartate derivatives disrupt crystal nucleation through dispersant mechanisms with enhanced biodegradability profiles. German and Dutch industrial cooling systems are adopting polymer alternatives fastest under EU Green Deal discharge mandates. REACH registration dossiers for novel polymer actives impose 24-36 month approval timelines that favor incumbent suppliers.
- Polyphosphates:Linear condensed phosphates including SHMP and TPP sequester hardness ions through complexation in municipal and light industrial applications.
- Aminophosphonates:Nitrogen-functionalized phosphonates combine chelation and threshold inhibition for high-pH cooling water systems.
- Phosphonate Esters:Thermally stable esterified variants withstand downhole temperatures exceeding 150°C in oilfield squeeze treatments.
Phosphonates lead volumes today; polymers are gaining share fastest.
Application:
Severity of operating conditions determines whether buyers accept premium pricing for thermally stable or pressure-resistant formulations.
- Water Treatment:Municipal and industrial water reuse facilities deploy scale inhibitors to protect membrane systems and distribution infrastructure from calcium carbonate fouling. China's MEE wastewater discharge standards for thermal power plants are expanding phosphonate and polymer consumption across Shandong and Jiangsu provinces. Zero liquid discharge mandates in semiconductor fabrication are creating demand for synergistic scale-corrosion packages.
- Oilfield:Downhole squeeze treatments and topside processing require scale inhibitors that maintain activity at 150°C+ temperatures and 10,000+ psi pressures. Barium sulfate and calcium carbonate inhibition in North Sea and Permian Basin formations commands formulation premiums of 3-5x over water treatment grades. Thermally stable phosphonate esters dominate this segment despite higher phosphorus content.
- Cooling Systems:Open recirculating and once-through cooling towers represent the deepest volume pool with recurring consumption tied to plant operating hours.
- Boilers:High-pressure steam generation requires scale inhibitors with thermal stability above 200°C to prevent calcium and silica deposition on heat transfer surfaces.
- Detergents:Builder applications leverage polyphosphates and phosphonates to sequester water hardness and prevent fabric encrustation.
Water treatment commands the broadest geographic footprint; oilfield generates the highest margins per kilogram.
End User Industry:
Operational criticality of heat transfer infrastructure determines procurement centralization and specification stringency across industrial buyers.
- Power Generation:Thermal power plants consume scale inhibitors across boiler water treatment, cooling tower chemistry, and flue gas desulfurization systems. State-owned generation groups in China and independent power producers in the United States are consolidating chemical procurement through integrated service contracts bundling scale inhibitors with corrosion inhibitors and microbiocides. Recurring consumption ties directly to plant capacity factors and operating hours.
- Oil & Energy:Upstream production, midstream pipelines, and downstream refining each present distinct scale control challenges from reservoir to product export. Squeeze treatment programs in Saudi Arabian and Brazilian offshore fields require thermally stable phosphonate esters with validated formation compatibility dossiers.
- Chemical Processing:Petrochemical and specialty chemical plants deploy scale inhibitors to protect heat exchangers and reactor cooling systems from process-side fouling.
- Paper & Pulp:Kraft mill recovery boilers and bleach plant cooling systems require scale control to maintain evaporator efficiency and paper machine runnability.
- Textiles:Dyeing and finishing operations use scale inhibitors to prevent calcium and magnesium precipitation on fabric surfaces and processing equipment.
Power generation anchors volume demand; oil and energy extracts the steepest formulation premiums.
Packaging Type:
Logistics infrastructure and dosing system configuration drive format selection between liquid bulk delivery and solid convenience.
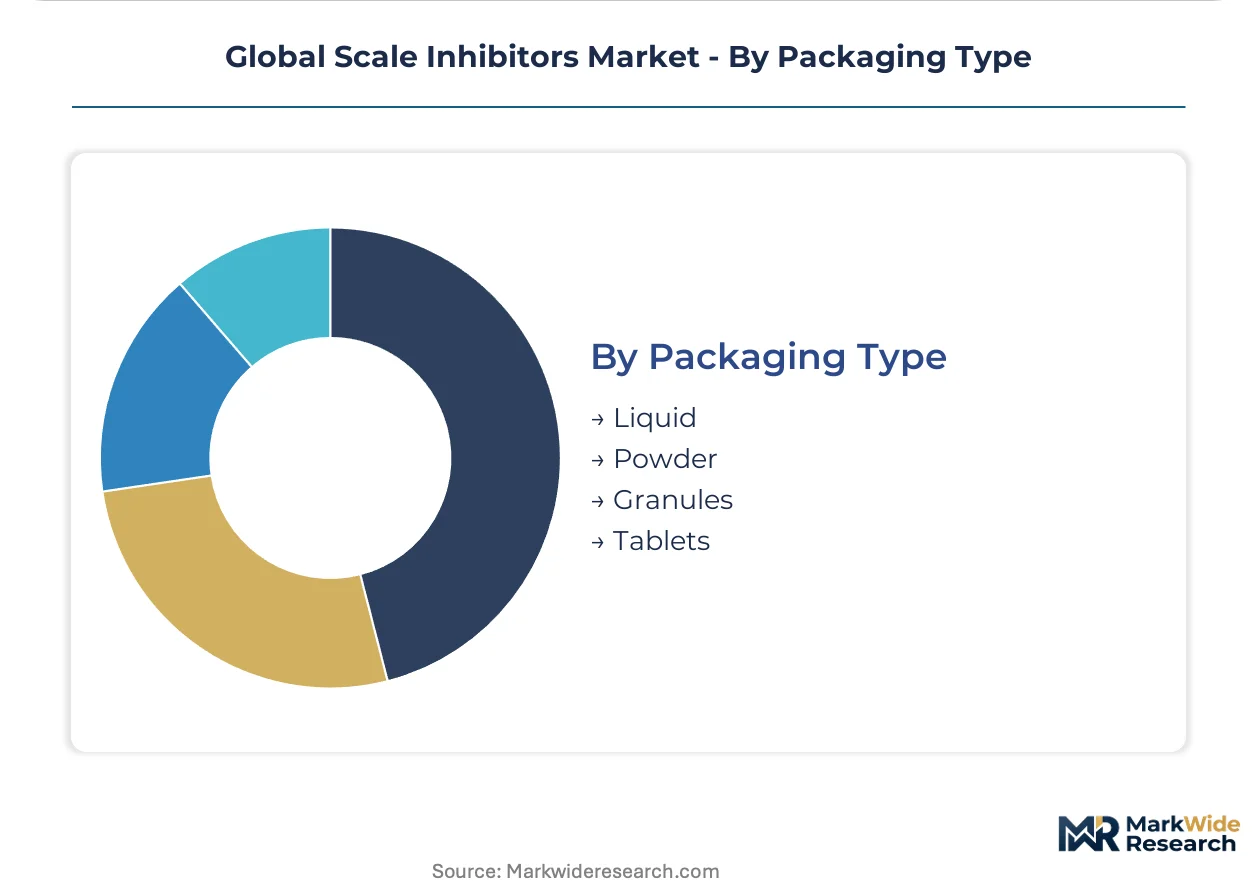
- Liquid:Bulk tanker and drum deliveries dominate industrial applications with automated dosing systems and centralized chemical storage. Liquid phosphonates and polymer solutions integrate directly into power plant and refinery chemical feed skids.
- Powder:Spray-dried formulations reduce shipping weights for remote oilfield locations and detergent manufacturing.
- Granules:Low-dust handling characteristics suit small-scale municipal water treatment and swimming pool applications.
- Tablets:Controlled-release formats serve residential water softeners and point-of-use scale prevention devices.
Liquid formats dominate industrial procurement; solid formats address logistics-constrained and consumer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial water treatment chemistry originated in German and US power generation facilities during the mid-20th century, establishing formulation expertise that spread through multinational chemical companies to regional production hubs worldwide.
United States
Texas and Ohio manufacturing corridors drive phosphonate and aminophosphonate consumption for cooling water treatment in petrochemical complexes and independent power producers. EPA effluent limitation guidelines restrict phosphorus discharge from industrial cooling systems, accelerating substitution toward polymer alternatives. Houston's refining cluster and the Ohio River Valley chemical corridor anchor North American formulation demand.
Germany
Ruhr industrial belt utilities and Rhine-Main chemical parks deploy biodegradable polymer scale inhibitors under EU Green Deal water efficiency mandates. ECHA REACH registration requirements impose toxicity testing burdens that favor incumbent suppliers with established dossiers. BASF's Ludwigshafen headquarters and Bayer's Leverkusen complex exemplify integrated chemical procurement bundling scale inhibitors with corrosion control packages.
China
Shandong and Jiangsu provinces concentrate state-backed desalination and industrial water reuse projects requiring advanced phosphonate and polymer chemistries. MEE wastewater discharge standards for thermal power plants tighten compliance thresholds annually. Qingdao's desalination facilities and Nanjing's petrochemical complex represent the deepest regional demand pools.
Saudi Arabia
Eastern Province oilfield operations and Red Sea desalination plants command premium formulations for extreme temperature and salinity conditions. Thermally stable phosphonate esters dominate offshore squeeze treatments despite higher phosphorus content. Jubail Industrial City and Ras Al-Khair desalination complex anchor Middle Eastern specialty chemical consumption.
India
Thermal power plant construction across Gujarat and Maharashtra expands recurring chemical treatment programs for boiler and cooling infrastructure. Central Electricity Authority water quality guidelines shape procurement specifications for state-owned generation utilities. Mundra and Dahej industrial corridors concentrate demand from captive power plants and refineries.
Global Scale Inhibitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory dossier depth. The vendor base stratifies between integrated chemical conglomerates with captive phosphorus supply and specialized water treatment formulators with regional service networks. Three archetypes dominate: backward-integrated phosphorus producers, polymer-focused biodegradable specialists, and integrated service contractors bundling chemicals with monitoring equipment. Competitive dynamics center on REACH dossier maintenance and long-term power utility service contracts.
Within the integrated chemical tier, Solvay and BASF SE exemplify European-headquartered suppliers leveraging phosphonate specialty portfolios and manufacturing scale. Dow anchors North American presence through aminophosphonate production capacity and channel relationships with cooling water treatment providers. Kemira Oyj represents the Nordic model combining phosphorus raw material integration with polymeric dispersant capabilities.
| Leading Market Players |
|---|
| Solvay |
| Kemira |
| BASF SE |
| Solenis |
| Akzo Nobel N.V. |
| Ecolab |
| Clariant |
| Ashland |
| Dow |
| Others |
Supply & Pricing Matrix
Phosphate rock price indices in Morocco and China cascade through phosphonate manufacturing costs into three-tier pricing structures across premium, standard, and economy levels. Buyers in phosphorus-constrained jurisdictions absorb formulation premiums for biodegradable polymer alternatives while cost-driven markets in India and Southeast Asia sustain commodity phosphonate consumption.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between power utilities and integrated chemical suppliers, with price differentiation resting on REACH dossier completeness and thermal stability certification tiers. Cost compression in standard-grade phosphonates is intensifying because EPA phosphorus discharge rules in Texas and Ohio compress addressable demand for legacy formulations. State-owned generation groups in China exhibit lowest price sensitivity due to bundled service contracts, while independent power producers in India prioritize unit economics.
Supply Chain Analysis
Freight cost differentials between bulk liquid tankers and spray-dried powder formats shape regional distribution economics for remote oilfield locations. Phosphate rock mining concentrates in Morocco, China, and Western Sahara, exposing phosphonate manufacturers to export quota volatility and geopolitical disruption. Raw material dependencies span phosphorus pentoxide, ethylene diamine, and maleic anhydride feedstocks. Single-source vulnerability runs through Moroccan state-controlled phosphate exports. Distribution runs through integrated water treatment service contractors bundling chemicals with dosing equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Scale Inhibitors Market functions as a geographic-arbitrage play where formulation premiums in REACH-regulated Europe offset margin compression in cost-competitive Asia-Pacific procurement.
For Market Incumbents: Hedge phosphonate margin erosion by accelerating biodegradable polymer R&D partnerships with German and Dutch power utilities ahead of EU Green Deal enforcement waves. Backward integration into phosphorus raw materials in Morocco or captive polyaspartate production capacity insulates against supply disruption and substitution technology threats.
For New Entrants and Emerging Players: Begin with specialty aminophosphonate formulations for high-pressure boiler applications in India's Mundra and Dahej industrial corridors, where thermal stability requirements exceed biopolymer performance ceilings. A technical service-led go-to-market approach bypasses entrenched supplier relationships at incumbent-integrated utilities.
For Investors and Strategic Acquirers: Asymmetric upside sits with polymer-focused biodegradable specialists holding validated ECHA dossiers and established supply relationships with Rhine-Main chemical parks. Long-term viability hinges on regulatory divergence persistence between phosphorus-constrained and cost-driven markets. Watch for EPA effluent limitation guideline finalization as inflection signal for North American formulation substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus | Captive phosphate rock access in Morocco insulates Solvay and Kemira from export quota volatility. |
| Biodegradable Polymer Scale-Up | Polyaspartate manufacturing expansion in Germany serves EU Green Deal compliance deadlines. |
| Long-term Utility Service Contracts | Bundled chemical procurement at Chinese state-owned generation groups reduces supplier count per facility. |
| Digital Dosing Integration | IoT-enabled feed controllers at Texas petrochemical complexes open subscription revenue streams. |
| REACH Dossier Maintenance Investment | Retrospective toxicity testing for pre-2010 phosphonate registrations raises barriers against new entrants. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Middle East, with primary inputs from each region combining interviews with power plant chemical procurement managers, water treatment service contractors, phosphonate plant managers, and ECHA regulatory affairs specialists. Secondary validation draws from EPA effluent limitation guidelines, MEE wastewater discharge standards, EU Green Deal implementation documents, and customs trade data. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Granularity extends to product chemistry, application severity, end-user industry, and regional regulatory cluster across the projection horizon. CAGRs derive from trend-line extrapolation of historical consumption patterns adjusted for capacity buildout in Shandong desalination facilities and Permian Basin oilfield activity. Forecast inputs include thermal power plant operating hour projections and REACH registration timeline assumptions for novel biodegradable actives.
Caveats apply where EPA rulemaking delays or Moroccan phosphate export policy shifts could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement velocity and substitution technology performance thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tris Nonylphenyl Phosphite Market
Additives
Silicone Additives Market
Additives
Antiblock Agents Market
Additives
Feed Additives Market
Additives
Magnesium Stearate Market
Additives
Bromine Derivatives Market
Additives
Global Glass Additives Market
Additives
Lecithin and Phospholipids Market
Additives
Inorganic Filler Market
Additives
Ammonium Acetate Market
Additives
Global Peptone Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Global Feed Acidulants Market
Additives
Rosin Ester Market
Additives
Cetane Improver Additives Market
Additives
Plastic Fillers Market