
 North America Citric Acid Market | 2026-2036
North America Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Citric Acid Market Intelligence
Modular bulk-to-bag packaging is shifting procurement patterns across North American citric acid buyers, letting mid-size food processors right-size inventory without committing to full drum volumes. Archer Daniels Midland Company leverages its integrated corn wet milling network to secure low-cost glucose feedstock for fermentation-based production. Jungbunzlauer Suisse AG anchors its regional position through specialized anhydrous grades targeting pharmaceutical contract manufacturers. Cargill Incorporated competes by controlling distribution nodes across the Great Plains, shortening lead times to Midwestern beverage plants.
Citric acid is a tricarboxylic acid produced primarily via submerged fermentation of Aspergillus niger on carbohydrate substrates, yielding a colorless crystalline compound with a molecular weight of 192.12 g/mol and pKa values of 3.13, 4.76, and 6.40 that determine its buffering range. Its primary industrial purpose spans food preservation, pH adjustment, and metal chelation in cleaning formulations. Liquid citric acid dominates volume flows into beverage acidification where tanker delivery minimizes handling costs, while anhydrous citric acid commands premium positioning in pharmaceutical tablet formulations where moisture sensitivity dictates specification. The preservative application segment leads value capture given its irreplaceability in shelf-stable sauces and dressings, whereas chelating agent demand accelerates fastest as phosphate-free dishwasher detergent formulations gain shelf space.
The FDA's 21 CFR 184.1033 food-grade specifications and EPA Safer Choice program criteria jointly determine which citric acid grades qualify for consumer-facing cleaning labels, filtering out lower-purity imports. Health Canada and PMRA coordinate with the FDA on maximum residue limits for fermentation-derived processing aids, creating a harmonized North American compliance corridor. Stakeholders must monitor state-level green chemistry procurement mandates in California and New York, as these jurisdictions increasingly restrict chelating alternatives and elevate bio-based acidulant preference in institutional purchasing.
Market Dynamics
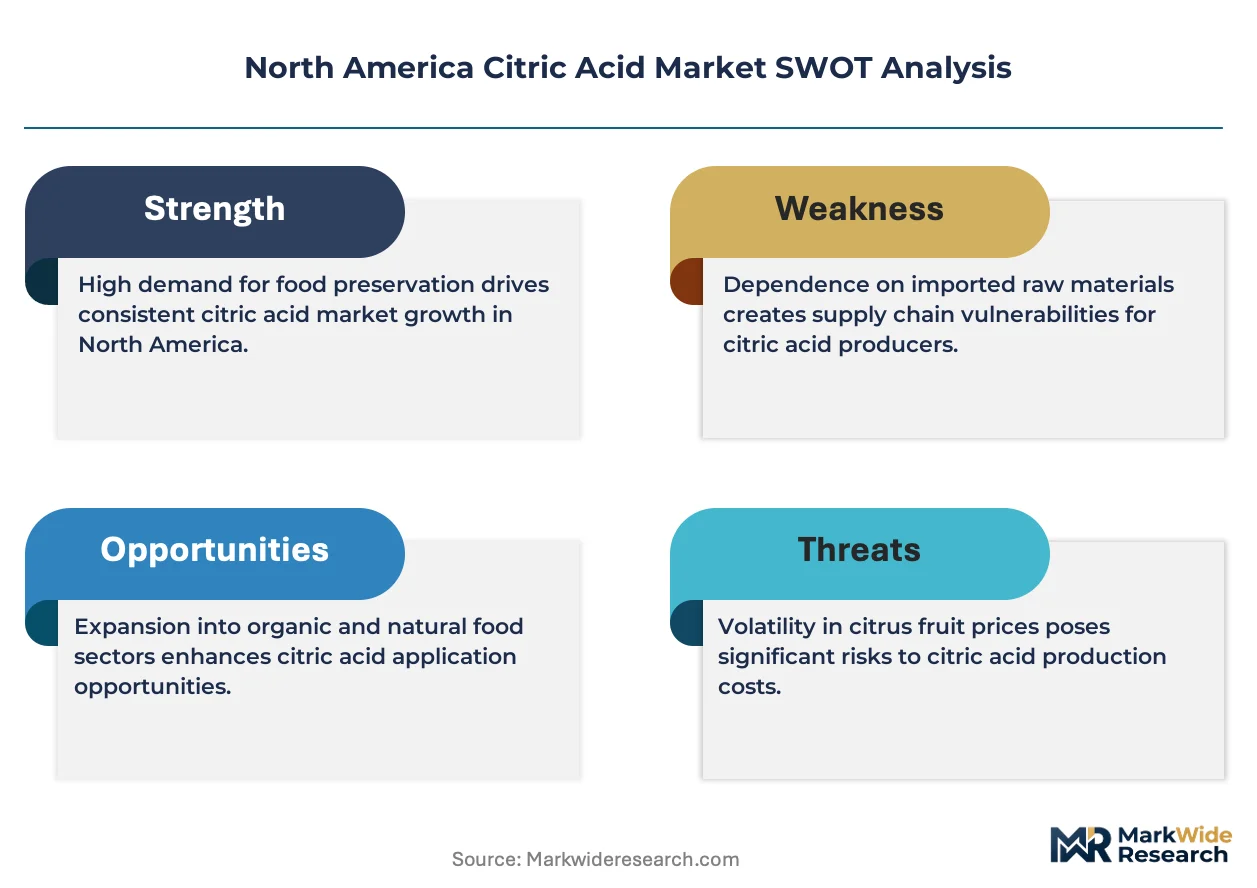
Fermentation feedstock volatility and phosphate-free cleaning mandates are compressing margin structures while forcing capital redeployment toward anhydrous pharmaceutical grades and liquid beverage formulations.
Growth Catalysts
- EPA Safer Choice program criteria:Bio-based chelating agents in phosphate-free dishwasher detergents are capturing shelf space previously held by petrochemical alternatives, expanding citric acid's addressable cleaning market.
- Functional beverage acidification:Electrolyte and probiotic drink manufacturers are specifying liquid citric acid for tanker-fed production lines, locking in volume commitments with Midwest fermentation plants.
- Corn wet milling concentration:Abundant glucose feedstock in Iowa and Illinois sustains cost-competitive fermentation economics against imported citric acid from cane-sugar regions.
Market Restraints
- Glucose price volatility:Corn futures fluctuations transmit directly to fermentation cost structures, compressing margins for non-integrated producers lacking captive wet milling capacity.
- Single-source fermentation strain dependence:Industrial citric acid production relies almost exclusively on Aspergillus niger genetics, creating biological concentration risk without viable alternative microbial platforms.
- 21 CFR 184.1033 purity thresholds:FDA food-grade specifications filter out lower-cost imports that fail residual solvent or heavy metal limits, constraining price competition from offshore suppliers.
Strategic Opportunities
- California green chemistry procurement mandates:State-level institutional purchasing rules are elevating bio-based acidulant preference in school and hospital cleaning contracts, creating premium positioning for certified domestic producers.
- Pharmaceutical anhydrous grades:Moisture-sensitive tablet and capsule formulations are commanding specification premiums as contract manufacturers seek to reduce excipient-related stability failures.
- Modular bulk-to-bag packaging:Mid-size food processors are right-sizing inventory through intermediate container options, opening volume tiers previously inaccessible below full drum commitments.
Industry Challenges
- Fermentation process engineering talent:Specialized bioprocess operators with Aspergillus niger strain optimization experience are concentrated at legacy production sites, constraining greenfield facility staffing.
- cGMP certification timelines:Pharmaceutical-grade anhydrous production requires 18-24 month FDA facility qualification cycles, delaying revenue recognition for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Citric Acid Market |
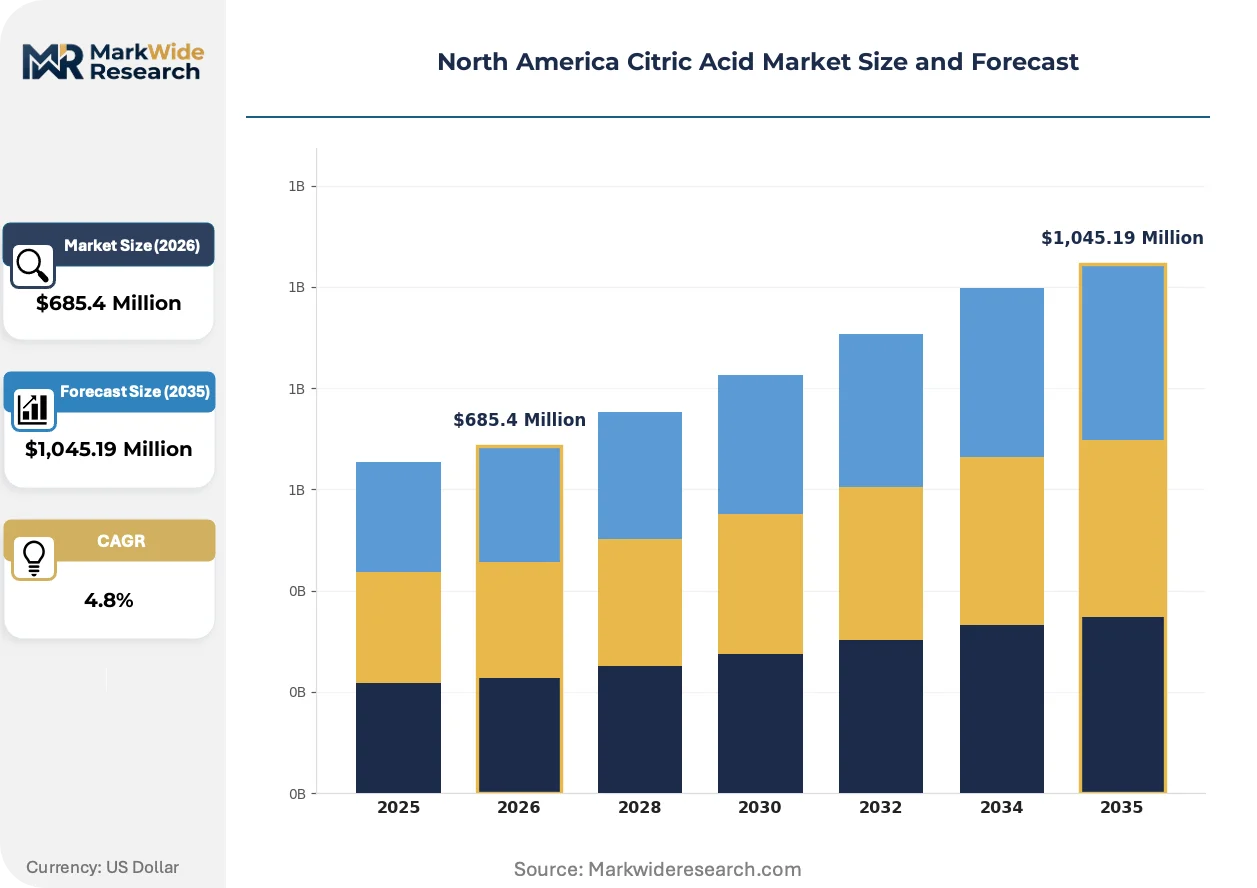
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Citric Acid, Anhydrous Citric Acid, Citric Acid Monohydrate, Citric Acid Granules End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Cleaners Application: Preservative, Flavoring Agent, pH Regulator, Chelating Agent Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Jungbunzlauer Suisse AG, Tate & Lyle PLC, Gadot Biochemical Industries Ltd, Ingredion, FBC Industries, Citrique Belge, Weifang Ensign Industry Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Citric Acid Market Strategic Shifts & Innovations
Continuous fermentation monitoring and real-time metabolite sensing are compressing batch cycle times while enabling predictive process control that reduces contamination losses.
Membrane filtration technology is integrating into downstream citric acid recovery, replacing traditional calcium salt precipitation with nanofiltration and electrodialysis systems that cut wastewater volumes. Beverage concentrate manufacturers in Texas and California are adopting these systems fastest, drawn by water discharge cost reductions. The technology is integrating fermentation and purification into tighter process loops, enabling location of production closer to end-use demand rather than traditional corn-belt concentration.
Health Canada and PMRA coordination on maximum residue limits for fermentation-derived processing aids is harmonizing North American compliance corridors, reducing dual-certification burdens for cross-border suppliers. The FDA's 21 CFR 184.1033 specifications now function as a de facto continental standard, with Mexican COFEPRIS increasingly referencing US purity benchmarks. Pharmaceutical contract manufacturers are responding by consolidating supplier qualification audits around FDA-grade specifications, privileging domestic producers with established Drug Master Files.
Buyers are unbundling acidulant procurement from bundled chemical distributor relationships, establishing direct contracts with fermentation plants for annual volume commitments. Food processors in the Great Lakes region are leading this disintermediation, leveraging electronic data interchange for order management previously handled by regional distributors. The shift is most visible among mid-size sauce and dressing manufacturers seeking to capture margin previously allocated to distributor markups on drum and tote quantities.
North America Citric Acid Market Segmentation
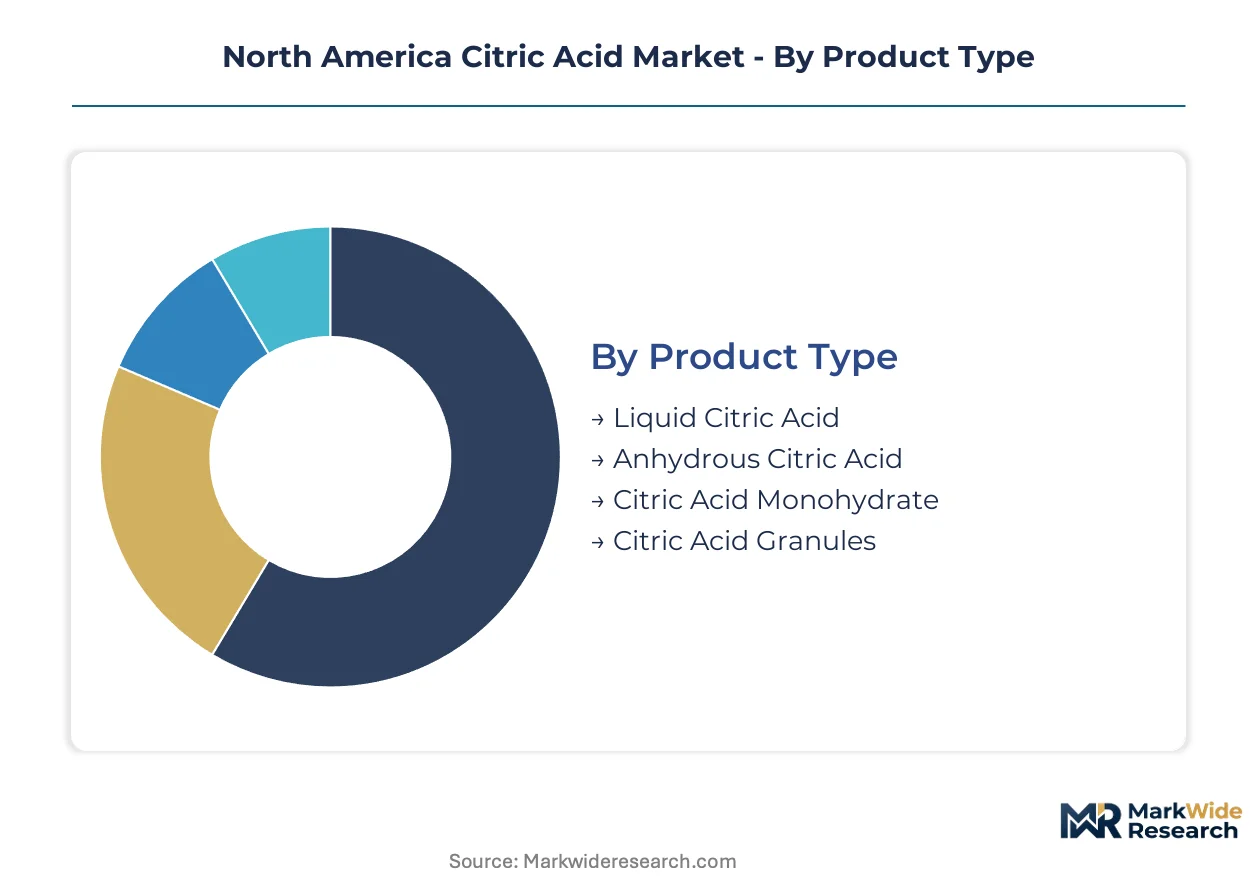
Citric acid procurement patterns diverge sharply across physical forms, end-use specifications, and packaging configurations. Each segmentation axis reflects distinct supply chain economics and regulatory compliance thresholds that reshape buyer-seller relationships.
Product Type:
Standardization dominates liquid grades while pharmaceutical and food applications demand customized purity certifications and moisture specifications.
- Liquid Citric Acid:Aqueous solution typically at 50% concentration delivered via tanker to beverage plants. Midwest fermentation facilities supply Great Lakes and Texas beverage corridors through dedicated logistics contracts. The liquid form eliminates dissolution steps in high-volume acidification processes.
- Anhydrous Citric Acid:Crystalline powder with moisture content below 0.5% specified for moisture-sensitive pharmaceutical tablets. FDA Drug Master File holders command specification premiums from contract manufacturers seeking excipient stability assurance.
- Citric Acid Monohydrate:Single water molecule inclusion provides controlled release characteristics in food applications. Standard grade for sauce and dressing manufacturers balancing cost against shelf stability.
- Citric Acid Granules:Free-flowing particulate form engineered for dust-free handling in automated dispensing systems. Industrial cleaning compound blenders specify this grade for precise metering.
Leading the category by volume: Liquid Citric Acid. Expanding most quickly: Anhydrous Citric Acid.
End User:
Volume concentration clusters in beverage manufacturing while margin capture favors pharmaceutical qualification requirements.
- Food & Beverage:Acidification, preservation, and flavor modulation across carbonated drinks, juices, sauces, and dressings. Tanker-fed production lines at Midwest beverage plants lock in annual volume commitments with fermentation facilities.
- Pharmaceuticals:Excipient-grade citric acid in tablet disintegration, pH buffering, and active salt formation. cGMP certification and FDA Drug Master Files create supplier stickiness and price premiums.
- Cosmetics:pH adjustment in personal care formulations with lower purity thresholds than pharmaceutical grades. California formulators drive preference for bio-based acidulant certification.
- Household Cleaners:Chelating agent in phosphate-free dishwasher detergents expanding under EPA Safer Choice program eligibility. Institutional procurement mandates in New York and California accelerate specification.
Food & Beverage captures the greatest volume share. Pharmaceuticals deliver the steepest margin expansion trajectory.
Application:
Functional differentiation separates irreplaceable preservation roles from substitutable pH adjustment uses.
- Preservative:Irreplaceable antimicrobial function in shelf-stable sauces, dressings, and beverages where pH reduction below 4.6 inhibits pathogen growth. No viable acidulant substitutes exist at equivalent cost.
- Flavoring Agent:Tartness contribution in soft drinks and candy formulations. Malic and fumaric acids compete on cost in less regulated flavor applications.
- pH Regulator:Buffering capacity across food, pharmaceutical, and cosmetic formulations. Commoditized function with price pressure from alternative organic acids.
- Chelating Agent:Metal ion sequestration in cleaning formulations displacing phosphate and EDTA alternatives. EPA Safer Choice certification drives fastest specification growth.
Preservative applications anchor value capture. Chelating agent demand is climbing the fastest.
Packaging Type:
Volume scale determines container economics from bulk tanker to manual-handling pails.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for high-volume beverage and cleaning compound manufacturers. Direct fermentation plant contracts eliminate distributor markups.
- Drums:Standard 55-gallon steel or fiber containers for mid-size food processors and pharmaceutical compounders. Traditional procurement unit facing displacement by modular alternatives.
- Bags:25-50 pound multiwall paper or polyethylene sacks for small-batch food manufacturers and cosmetic formulators. Right-sizing trend favors intermediate bag volumes over drum commitments.
- Pails:5-gallon plastic containers for laboratory, pilot-scale, and specialty cosmetic production. Highest per-unit packaging cost tier with limited volume relevance.
Bulk Containers dominate volume flows. Bags are gaining share fastest among mid-size processors seeking inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States Midwest where corn wet milling infrastructure delivers low-cost glucose feedstock, while consumption spreads across beverage corridors in Texas, California, and Ontario. Canada and Mexico import substantial volumes to compensate for limited domestic fermentation capacity. Regulatory harmonization under FDA-Health Canada-PMRA coordination reduces cross-border compliance friction.
United States
Beverage manufacturers in Texas and California specify liquid citric acid for tanker-fed production lines, locking in annual volume commitments with Iowa and Illinois fermentation facilities. The EPA Safer Choice program criteria expand specification in institutional cleaning procurement across California and New York state mandates. Chicago-area distribution nodes shorten lead times to Great Lakes sauce and dressing plants.
Canada
Health Canada and PMRA coordination on maximum residue limits for fermentation-derived processing aids creates compliance alignment with FDA standards, reducing dual-certification burdens for cross-border suppliers. Ontario food processors drive demand for citric acid monohydrate in sauce formulations. Toronto-area pharmaceutical contract manufacturers source anhydrous grades through FDA Drug Master File holders.
Mexico
COFEPRIS increasingly references FDA 21 CFR 184.1033 purity benchmarks, elevating preference for US-imported citric acid over lower-cost Asian alternatives. Mexico City Metro beverage bottlers expand acidulant procurement for carbonated and functional drink production. Nuevo León cleaning compound manufacturers specify citric acid for phosphate-free dishwasher detergent formulations.
North America Citric Acid Market Key Industry Players
The competitive structure tilts toward integrated agribusiness conglomerates with captive corn wet milling capacity. Three to four fermentation specialists dominate volume production, while regional distributors and specialized pharmaceutical-grade suppliers occupy niche tiers. Strategic moves concentrate on backward integration into glucose feedstock and forward integration into liquid formulation services for beverage clients.
Among integrated agribusiness operators, Archer Daniels Midland Company and Cargill Incorporated represent the scale-driven archetype with Midwest corn-belt concentration. Jungbunzlauer Suisse AG occupies the specialized pharmaceutical-grade tier, anchoring premium positioning through anhydrous citric acid supply to contract manufacturers. These three entities exemplify the dominant competitive configurations shaping procurement relationships across North American end-use segments.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Jungbunzlauer Suisse AG |
| Tate & Lyle PLC |
| Gadot Biochemical Industries Ltd |
| Ingredion |
| FBC Industries |
| Citrique Belge |
| Weifang Ensign Industry Co Ltd |
| Others |
Cost & Logistics Intelligence
Integrated agribusiness conglomerates with captive corn wet milling capacity anchor supply-side discipline, translating upstream glucose cost control into downstream pricing power across fermentation-based citric acid tiers. Their ownership structure—combining Archer Daniels Midland and Cargill's scale with Jungbunzlauer's specialized pharmaceutical focus—creates divergent pricing strategies that segment buyers by certification requirement and volume commitment.
Pricing Analysis
Cost compression in standard-grade liquid citric acid intensifies as corn futures volatility transmits directly to non-integrated producers lacking captive wet milling infrastructure. Three-tier pricing structure across pharmaceutical anhydrous, food-grade monohydrate, and industrial liquid levels separates FDA Drug Master File premiums from commodity beverage acidification contracts. Price differentiation hinges on cGMP certification status and annual volume scale, with mid-size sauce manufacturers exhibiting highest sensitivity to per-unit packaging economics while pharmaceutical contract manufacturers absorb specification premiums for excipient stability assurance.
Supply Chain Analysis
Specialized bioprocess operators with Aspergillus niger strain optimization experience concentrate in Iowa and Illinois fermentation corridors, constraining greenfield facility staffing and tightening batch cycle reliability. Supply draws from United States corn-belt glucose feedstock, Canadian Health Canada-coordinated import channels, and Mexican COFEPRIS-aligned FDA-grade sourcing. Single-source microbial platform dependence creates biological concentration risk without viable alternative fermentation genetics. Distribution runs through Chicago-area nodes to Great Lakes processors and dedicated tanker logistics to Texas and California beverage corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity expansion timelines—requiring 18-24 month FDA facility qualification cycles—prop pricing discipline by constraining rapid supply response to demand spikes in pharmaceutical anhydrous and liquid beverage grades.
For Market Incumbents: Cement backward integration into corn wet milling to insulate margin structures from glucose price volatility transmitted through futures markets. Lock in multi-year tanker-fed volume commitments with Texas and California beverage manufacturers before membrane filtration technology enables distributed production closer to end-use demand. Prioritize cGMP certification maintenance to defend pharmaceutical anhydrous premiums against emerging specialty chemical entrants. For New Entrants and Emerging Players: Continuous fermentation monitoring systems offer entry leverage into mid-size food processor segments underserved by legacy batch-optimization expertise. Target California institutional cleaning procurement mandates for phosphate-free dishwasher detergent formulations where EPA Safer Choice certification creates specification barriers for imported alternatives. Pursue direct electronic data interchange relationships with Great Lakes sauce manufacturers seeking to disintermediate regional distributor markups on modular bulk-to-bag packaging. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation specialists with established Drug Master Files in Midwest corn-belt geographies where glucose feedstock cost advantages sustain margin resilience. Long-term viability rests on consolidation of fragmented pharmaceutical-grade capacity under platforms capable of spanning anhydrous citric acid and excipient formulation services. Watch California and New York green chemistry procurement mandate expansion as inflection signal for bio-based acidulant premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captive glucose supply insulates Archer Daniels Midland and Cargill from commodity futures volatility. |
| cGMP Certification Investment | FDA facility qualification cycles create 18-24 month barriers protecting pharmaceutical-grade pricing premiums. |
| Membrane Filtration Technology Adoption | Nanofiltration and electrodialysis systems cut wastewater volumes for Texas and California beverage concentrate manufacturers. |
| Direct Fermentation Plant Contracts | Electronic data interchange relationships with Great Lakes processors eliminate distributor markup capture. |
| California Green Chemistry Compliance | Bio-based acidulant certification unlocks institutional purchasing premiums in school and hospital cleaning contracts. |
Research Approach
Independent corroboration across fermentation plant managers, beverage procurement leads at Midwest bottlers, pharmaceutical contract manufacturing executives, and cleaning compound R&D directors underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR 184.1033 filings, EPA Safer Choice program eligibility databases, SEC 10-K disclosures by integrated agribusiness operators, and Health Canada-PMRA coordinated maximum residue limit guidelines. Bottom-up volume modeling across liquid, anhydrous, monohydrate, and granule product tiers triangulates against top-down corn wet milling capacity assessments.
Rate-of-change decomposition across the projection horizon segments expansion by pharmaceutical grade tier, beverage acidification volume, preservative application intensity, and chelating agent specification growth. CAGRs derive from metabolite sensing adoption curves, membrane filtration penetration rates in downstream recovery, and institutional procurement mandate rollout timelines. Forecast inputs incorporate Aspergillus niger strain optimization productivity gains and corn futures correlation coefficients with fermentation cost structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained glucose price volatility or accelerated California green chemistry mandate expansion. Assumptions reflect current FDA-Health Canada-PMRA regulatory harmonization trajectories and existing EPA Safer Choice program criteria stability. Material deviation in corn-belt fermentation capacity utilization or pharmaceutical cGMP certification backlog duration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tire Additives Market
Additives
Allura Red AC Market
Additives
Anti Crystallizing Agents Market
Additives
Global Glass Additives Market
Additives
Calcium Diglutamate Market
Additives
South America Concrete Admixtures Market
Additives
Additives for Metalworking Fluids Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
United States Betaine Market
Additives
Global Ester Gum Market
Additives
Middle East Feed Additives Market
Additives
Viscosity Reducing Agents Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Automotive Coolant Additives Market
Additives
Liquid Thickeners Market
Additives
United Kingdom Sodium Reduction Ingredient Market