
 Plasticizer Concrete Admixtures Market | 2026-2036
Plasticizer Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Plasticizer Concrete Admixtures Market Analytics
EN 934 certification for admixtures for concrete, mortar and grout is reorganizing competitive access across Europe. Sika AG leverages its integrated supply chain for polycarboxylate ether production to sustain premium positioning in self-consolidating concrete applications. BASF SE anchors its presence through backward integration into acrylic acid monomers, while GCP Applied Technologies competes on technology leadership in rheology-modifying admixtures for shotcrete.
Plasticizer concrete admixtures are chemical additives, primarily polycarboxylate ethers, lignosulfonates, and napthalene-based compounds, dosed at 0.5–3.0% by weight of cement to reduce water demand by 15–40% while maintaining or enhancing workability; they function by dispersing cement particles through steric hindrance and electrostatic repulsion, enabling high-performance concrete with lower water-to-cement ratios and improved compressive strength. Polycarboxylate formulations dominate value capture due to superior water reduction and slump retention, while lignosulfonate variants occupy cost-sensitive ready-mix segments where basic plasticization suffices. Self-consolidating concrete applications represent the fastest-growing demand pool within the application dimension, as complex formwork and dense reinforcement configurations require extended flow without segregation.
REACH registration requirements in Europe and EPA toxicity evaluations in the United States constrain napthalene-based product lines while accelerating migration toward polycarboxylate and modified viscosity alternatives. China's MEE enforces GB 8076 standards for concrete admixture performance, creating compliance thresholds that filter regional suppliers. Stakeholders must monitor evolving restrictions on formaldehyde condensate chemistries and align R&D pipelines with biopolymer-derived plasticizer platforms.
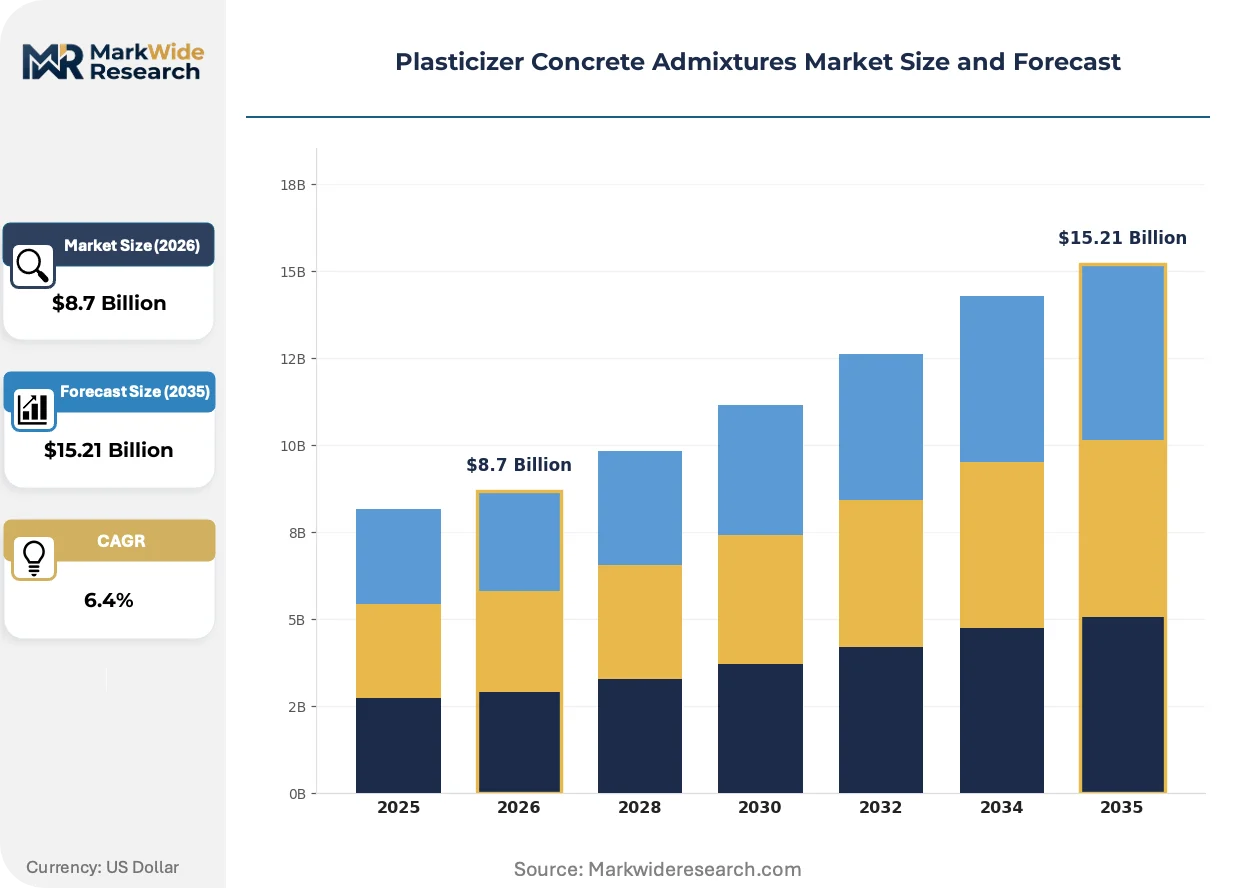
Market Dynamics
Migration from naphthalene sulfonate to polycarboxylate ether formulations is compressing legacy supply chains while elevating performance thresholds across commercial infrastructure, with REACH compliance in Europe and China's GB 8076 standards filtering supplier bases and redirecting procurement toward certified producers.
Growth Catalysts
- GB 8076 Standards:China's MEE enforcement of concrete admixture performance thresholds is filtering regional suppliers and consolidating procurement toward certified polycarboxylate producers serving highway and metro expansion.
- Self-consolidating concrete:Complex formwork geometries and dense reinforcement configurations in commercial towers and bridge segments require extended flow retention without segregation, elevating specification rates for high-range water reducers.
- India's national infrastructure pipeline:Concentrated highway and metro expansion programs are aggregating demand through centralized procurement, creating volume anchors for admixture suppliers with in-country blending capacity.
Market Restraints
- Olefins feedstock volatility:Acrylic acid and polyethylene glycol input costs fluctuate with crude derivatives, compressing margin predictability for polycarboxylate ether producers without captive monomer supply.
- Formaldehyde condensate restrictions:ECHA's REACH evaluations and EPA toxicity assessments are constraining naphthalene-based product lines, forcing reformulation investments and inventory obsolescence risk.
- Technical limitation in cold-climate slump retention:Polycarboxylate ethers exhibit accelerated workability loss below 5°C, requiring supplementary retarders and complicating winter construction specifications in northern geographies.
Strategic Opportunities
- Biopolymer-derived plasticizers:Lignin modification and carbohydrate-based dispersants align with EU Green Deal procurement preferences, opening specification pathways in public infrastructure tenders with embedded carbon criteria.
- 3D concrete printing:Layered construction methods demand ultra-low water-to-cement ratios with precise rheology windows, creating application-specific formulations with premium pricing potential.
- Pre-mixed dry mortar channels:Packaged construction chemicals distribution through retail building supply networks bypasses traditional ready-mix gatekeepers, accessing residential renovation and small-contractor segments.
Industry Challenges
- EN 934 certification timelines:European admixture approval requires 12-18 month testing protocols for new chemistries, delaying product launches and compressing effective patent windows.
- Integration complexity with supplementary cementitious materials:Fly ash and slag variability alters polycarboxylate adsorption kinetics, demanding job-specific dosage optimization that strains technical service capacity.
- Specialized formulation chemist scarcity:Polymer synthesis expertise for comb-architecture PCE design concentrates among senior technical staff, constraining R&D expansion at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasticizer Concrete Admixtures Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate, Lignosulfonate, Napthalene, Modified Viscosity End User: Residential Construction, Commercial Infrastructure, Industrial Projects, Transportation Development Application: Ready-Mix Concrete, Precast Concrete, Shotcrete, Self-Consolidating Concrete Functionality: Water Reduction, Workability Enhancement, Set Retarding, Durability Improvement |
| Companies Covered | Sika AG, BASF SE, GCP Applied Technologies Inc., Mapei SpA, RPM International, Inc., Fosroc, Inc., MBCC Group, Arkema Group, CHYRSO SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasticizer Concrete Admixtures Market Evolving Landscape
Formulation chemistry is pivoting toward bio-attributed feedstocks and precision rheology control, with regulatory pressure on residual toxicity and construction automation redefining performance specifications across commercial and infrastructure segments.
Viscosity-modifying admixtures integrated with polycarboxylate backbones are displacing standalone cellulose ether and welan gum solutions in self-consolidating and underwater concrete applications. Major contractors in Germany and Japan are specifying these hybrid systems for tunnel linings and marine structures, compressing the addressable market for conventional thickeners while elevating technical barriers for formulation suppliers.
REACH registration requirements for formaldehyde condensate chemistries are accelerating product line rationalization across European admixture portfolios. Suppliers are sunsetting naphthalene sulfonate and melamine variants, redirecting technical resources toward polycarboxylate platform extensions and biopolymer research pipelines to maintain specification access in public infrastructure tenders.
Specification decisions are migrating from ready-mix producers to engineering-consultant and contractor-led procurement, particularly in design-build and public-private partnership structures. This disintermediation concentrates influence among technical specification writers in France and Australia, who now mandate EN 934-compliant performance certificates upstream of supplier selection, compressing price-based competition in favor of documented durability outcomes.
Plasticizer Concrete Admixtures Market Segmentation
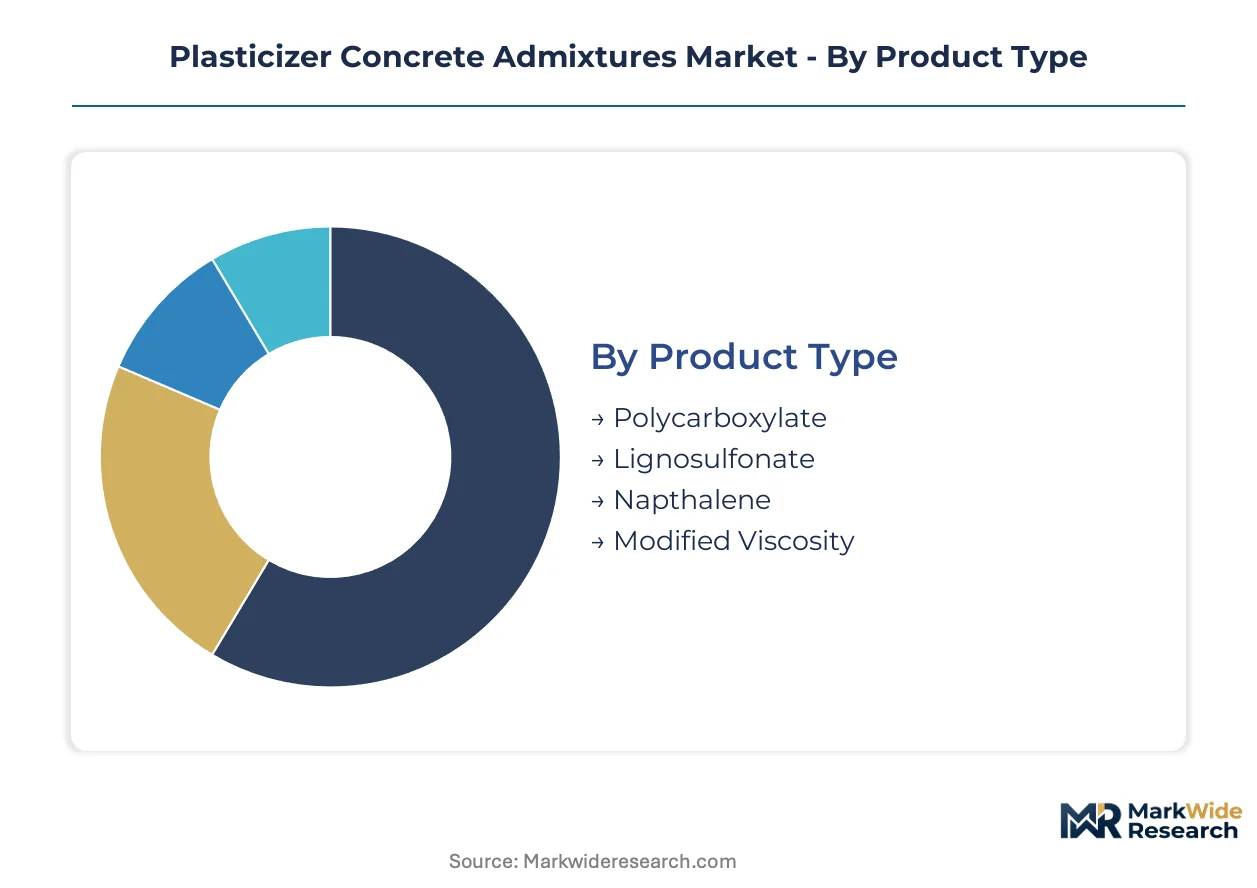
Segmentation in plasticizer concrete admixtures reveals how procurement channels, performance specifications, and regulatory compliance intersect to determine supplier access. Understanding these dimensions exposes where margin pools concentrate and which technical capabilities unlock premium positioning.
Product Type:
Channel mix varies sharply across chemistries: polycarboxylate ethers flow through engineering-consultant specifications in commercial infrastructure, while lignosulfonates dominate cost-driven ready-mix procurement with minimal technical service attachment.
- Polycarboxylate:Comb-architecture polymer backbones with polyethylene glycol side chains deliver 25–40% water reduction through steric hindrance mechanisms. Demand concentrates in China's highway and metro expansion programs where GB 8076 certification filters procurement toward certified producers with in-country blending capacity.
- Lignosulfonate:Wood-pulp byproduct derivatives provide 5–15% water reduction at lowest unit cost. Cost-sensitive residential and small-scale commercial projects in India aggregate volume through centralized national infrastructure pipeline procurement, compressing margin for suppliers without feedstock integration.
- Napthalene:Formaldehyde condensate chemistry faces REACH registration constraints across Europe and EPA toxicity evaluations in the United States.
- Modified Viscosity:Hybrid polycarboxylate-thickener systems displace standalone cellulose ethers in self-consolidating and underwater concrete specifications.
Polycarboxylate dominates installed base. Modified viscosity formulations are where expansion concentrates.
End User:
Cost tier stratification separates specification-led procurement from price-driven volume: premium chemistries attach to engineer-mandated commercial projects, while economy formulations serve contractor-direct residential channels.
- Commercial Infrastructure:High-rise towers, bridge segments, and complex formwork geometries mandate extended slump retention without segregation. Self-consolidating concrete specifications in Germany and Japan drive polycarboxylate demand with embedded durability performance clauses.
- Transportation Development:Highway, metro, and airport expansion programs concentrate volume through centralized procurement with compliance documentation requirements. India's national infrastructure pipeline and China's MEE-enforced standards filter supplier bases toward certified producers.
- Residential Construction:Small-contractor and renovation segments access admixtures through packaged dry mortar retail channels, bypassing traditional ready-mix gatekeepers.
- Industrial Projects:Power plants and manufacturing facilities specify durability-enhancing formulations with supplementary cementitious material compatibility requirements.
Transportation development commands volume scale. Commercial infrastructure offers the steepest expansion trajectory for premium formulations.
Application:
Volume distribution tracks construction method automation: ready-mix channels serve dispersed sites, while precast and 3D printing concentrate demand at manufacturing points with precise rheology windows.
- Self-Consolidating Concrete:Complex reinforcement configurations and architectural formwork demand extended flow without vibration. Tunnel linings and marine structures in Japan and Germany specify viscosity-modified polycarboxylate systems with documented segregation resistance.
- Ready-Mix Concrete:Dispersed construction sites with variable haul times require slump retention across temperature ranges. Cold-climate limitations below 5°C drive supplementary retarder demand, complicating winter specifications in northern geographies.
- Precast Concrete:Controlled manufacturing environments enable low water-to-cement ratios with accelerated strength development cycles.
- Shotcrete:Sprayed applications require rheology-modifying admixtures with immediate adhesion and reduced rebound loss.
Ready-mix concrete anchors volume throughput. Self-consolidating concrete is gaining share fastest among specification-driven segments.
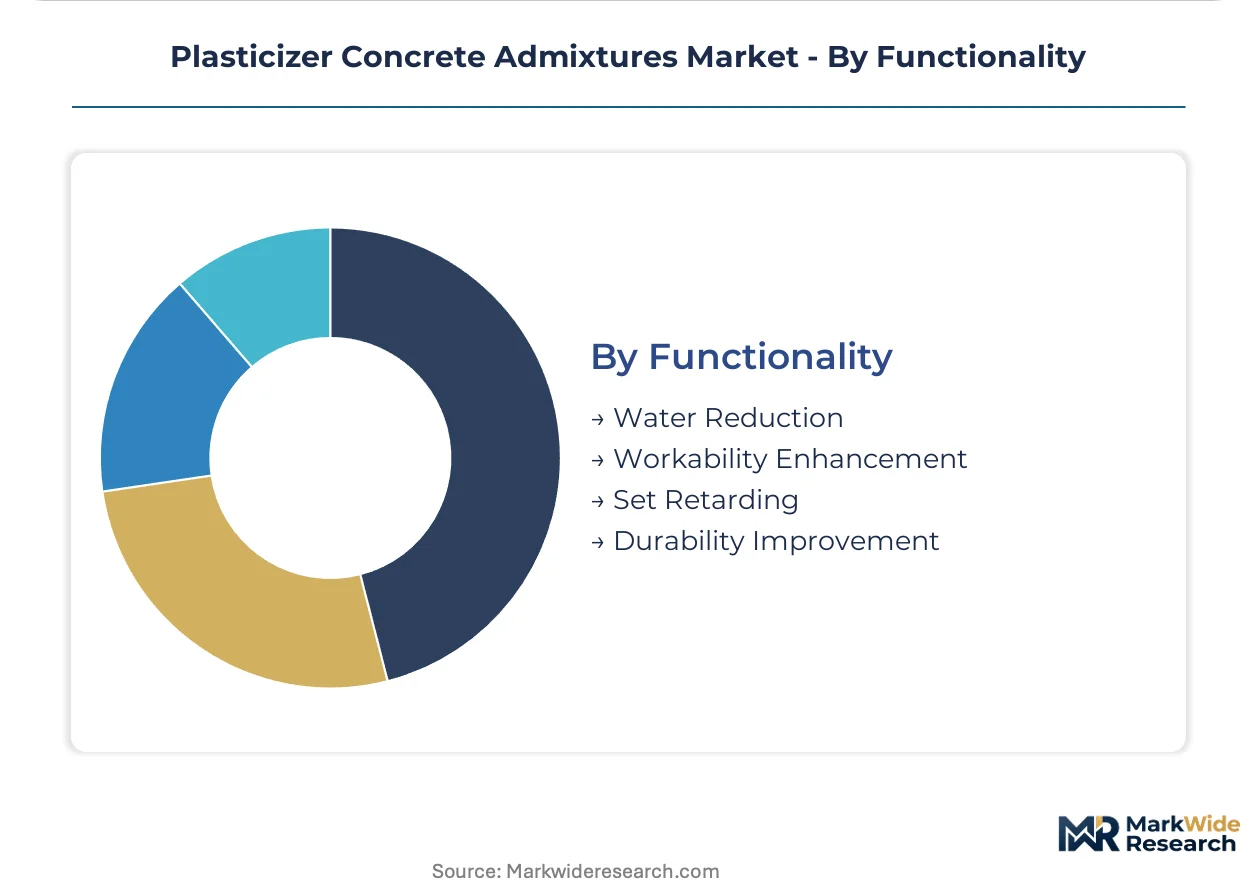
Functionality:
Customer type bifurcation separates performance-paying commercial buyers from cost-optimizing residential procurement, with functionality bundles determining technical service intensity.
- Water Reduction:Core function enabling high-performance concrete with reduced cement content and improved compressive strength. Polycarboxylate ethers dominate this specification tier through superior dispersion kinetics.
- Workability Enhancement:Slump retention and flow maintenance address haul time variability and placement complexity. Self-consolidating concrete applications in dense reinforcement configurations drive specification rates.
- Set Retarding:Delayed hydration controls placement in hot climates and large-volume pours, often combined with water reducers in tropical construction zones.
- Durability Improvement:Permeability reduction and chloride resistance specifications align with EU Green Deal procurement preferences for extended service life.
Water reduction commands the broadest installed base. Durability improvement is where specification premiums are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 2,298-kilometer Beijing-Guangzhou high-speed rail corridor underwrites China's commanding position in plasticizer concrete admixture consumption, with parallel metro and highway networks extending demand across provincial construction bureaus.
China
Highway expansion and metro construction in Chengdu, Xi'an, and Wuhan aggregate polycarboxylate ether procurement through state-owned construction conglomerates. MEE enforcement of GB 8076 performance standards filters regional admixture suppliers, consolidating procurement toward certified producers with in-country blending facilities. The Yangtze River Delta corridor concentrates manufacturing capacity for polyethylene glycol monomer feedstocks.
India
National highway widening and metro rail projects in Mumbai, Delhi, and Bengaluru concentrate demand through centralized infrastructure pipeline procurement. BIS certification requirements for concrete admixtures create compliance thresholds that favor established suppliers with technical service networks. Gujarat's chemical manufacturing clusters supply lignosulfonate derivatives for cost-sensitive ready-mix segments.
Germany
Tunnel linings for Stuttgart-Ulm rail infrastructure and commercial towers in Frankfurt specify self-consolidating concrete with EN 934-certified viscosity-modified polycarboxylate systems. ECHA REACH registrations constrain formaldehyde condensate chemistries, redirecting R&D toward biopolymer platforms. The Rhine-Ruhr industrial corridor anchors formulation laboratories serving Central European infrastructure tenders.
United States
Bridge rehabilitation programs and data center construction in Texas, California, and Virginia drive specification rates for high-range water reducers with extended slump retention. EPA toxicity evaluations of naphthalene-based admixtures accelerate migration toward polycarboxylate alternatives. The Gulf Coast petrochemical corridor supplies acrylic acid monomers for captive polycarboxylate ether production.
Japan
Seismic-resistant commercial towers and marine concrete structures in Tokyo, Osaka, and Yokohama mandate rheology-modified admixtures with documented segregation resistance. METI industrial standards for construction chemicals align procurement with durability performance clauses. The Kanto region concentrates technical specification influence among engineering consultants for design-build contracts.
Plasticizer Concrete Admixtures Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and certification access, creating a tiered structure where scale-driven multinationals anchor premium infrastructure segments while regional compounders capture cost-sensitive ready-mix volume. Three archetypes dominate: integrated petrochemical players with captive monomer supply, specialized admixture formulators with EN 934 and GB 8076 certification depth, and construction chemical divisions of diversified materials conglomerates. Competitive moves concentrate on backward integration into acrylic acid and polyethylene glycol production, plus geographic expansion through in-country blending facilities to meet local certification requirements.
Within the certification-heavy tier, Sika AG and BASF SE exemplify integrated supply chain positioning, while GCP Applied Technologies occupies a technology-focused niche. Swiss-incorporated Sika AG represents the European model of formulation leadership coupled with global distribution networks. German-based BASF SE anchors its presence through upstream control over acrylic acid monomer production. United States-headquartered GCP Applied Technologies sits within the specialized technology vector, with its corporate name signaling applied engineering orientation rather than commodity chemical scale.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| GCP Applied Technologies Inc. |
| Mapei SpA |
| RPM International, Inc. |
| Fosroc, Inc. |
| MBCC Group |
| Arkema Group |
| CHYRSO SAS |
| Others |
Value Network & Pricing Analysis
GB 8076 certification in China and EN 934 compliance in Europe simultaneously gate supplier qualification and stratify price tiers, compressing procurement pools toward certified producers while elevating premium capture for polycarboxylate formulations with documented durability performance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and technical service intensity. Polycarboxylate ethers with EN 934 or GB 8076 documentation command premium positioning in commercial infrastructure tenders, while lignosulfonate variants compete on unit cost in centralized highway procurement. Price erosion runs through naphthalene-based product lines as REACH registration costs and EPA toxicity evaluations force inventory rationalization. Small contractors in residential renovation segments exhibit highest price sensitivity, purchasing through packaged dry mortar retail channels with minimal technical support attachment.
Supply Chain Analysis
Acrylic acid monomer production concentrates in the Gulf Coast petrochemical corridor, the Yangtze River Delta, and the Rhine-Ruhr industrial zone, tethering polycarboxylate ether manufacturing to regional olefins feedstock availability. Polyethylene glycol and lignosulfonate derivatives draw from wood-pulp processing clusters in Gujarat and the southeastern United States. Single-source vulnerability in acrylic acid supply exposes formulators without captive monomer production to margin compression during crude derivative volatility. Distribution runs through in-country blending facilities serving state-owned construction conglomerates and centralized infrastructure procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasticizer concrete admixtures represent early-cycle expansion as 3D concrete printing and self-consolidating concrete specifications penetrate commercial infrastructure, creating formulation premiums for rheology precision that legacy naphthalene chemistries cannot address.
For Market Incumbents: Compound certification depth across multiple regulatory jurisdictions to defend specification access against regional compounders with lower compliance overhead. Deepen backward integration into acrylic acid monomers to offset olefins feedstock volatility eroding margin predictability in polycarboxylate ether production. Expand in-country blending capacity in India and Southeast Asia to capture volume from centralized infrastructure pipeline procurement. For New Entrants and Emerging Players: Anchor in biopolymer-derived plasticizer platforms aligned with EU Green Deal procurement preferences, where lignin modification and carbohydrate-based dispersants open specification pathways absent entrenched polycarboxylate competition. Target packaged dry mortar retail channels in residential renovation segments, bypassing ready-mix gatekeepers through building supply distribution partnerships with technical support-light positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across in-country blending facilities and certification testing infrastructure, favoring scaled producers with amortized compliance costs over mid-tier formulators. Acquisition candidates with GB 8076 and EN 934 certification depth, captive monomer supply, or established technical service networks in high-growth geographies offer durable positioning. Monitor ECHA REACH registration timelines and EPA toxicity evaluation outcomes as signals of naphthalene product line rationalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Monomers | Gulf Coast and Rhine-Ruhr producers secure feedstock cost predictability against olefins volatility. |
| GB 8076 Certification Investment | China's MEE enforcement filters regional suppliers toward certified polycarboxylate producers. |
| Biopolymer Platform R&D Expansion | EU Green Deal procurement preferences create specification pathways for lignin-derived dispersants. |
| In-Country Blending Facility Buildout | India's national infrastructure pipeline concentrates demand through centralized procurement channels. |
| Viscosity-Modified PCE Formulation Launch | German and Japanese tunnel specifications displace standalone cellulose ether thickeners. |
Research Methodology
The analysis maps polycarboxylate ether, lignosulfonate, naphthalene, and modified viscosity formulations, each validated through technical R&D directors at admixture producers, procurement leads at state-owned construction conglomerates, plant managers at ready-mix operations, and engineering consultants specifying self-consolidating concrete. Primary interview insights triangulate against customs and trade data, SEC 10-K filings, GB standard documentation, ECHA REACH registration databases, and infrastructure project procurement records. Bottom-up volume aggregation across product types, end users, and applications reconciles with top-down macro construction spending indicators.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models chemistry type, end-use industry, construction method, and regional regulatory cluster dimensions. CAGRs derive from segmented growth rate synthesis incorporating infrastructure pipeline commitments, certification adoption curves, and substitution dynamics from naphthalene to polycarboxylate platforms. Key inputs include MEE enforcement intensity, EN 934 testing protocol durations, and supplementary cementitious material compatibility requirements.
Material uncertainties — feedstock cost volatility, regulatory restriction expansion, and cold-climate formulation performance limitations — sit outside the modeled envelope. Forecasts reflect assumptions regarding GB 8076 certification adoption rates and REACH registration completion timelines. Practitioners should keep alternative scenarios live as ECHA formaldehyde condensate evaluations and EPA toxicity assessments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Iso-Butyric Acid Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Conditioning Agent Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Plastic Additives Market
Additives
Glycol Acetate Market
Additives
Organic Dispersants Market
Additives
Tocopheryl Acetate Market
Additives
Grease Additives Market
Additives
Green Polymer Additive Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Biofuel Additives Market
Additives
Viscosity Reducing Agents Market
Additives
Agrochemicals Additives Market
Additives
Feed Additives Market
Additives
China Sodium Reduction Ingredient Market