
 Carbide Tools Market | 2026-2036
Carbide Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Carbide Tools Market Intelligence
A capital-intensity divergence between integrated tungsten miners and pure-play tool fabricators is unwinding competitive stability across the sector. Sandvik Coromant leverages captive powder-metallurgy capacity to secure feedstock margins that rivals cannot match. Kennametal Inc. anchors its position through dense North American distribution networks serving automotive OEMs. OSG Corporation differentiates via specialized micro-grain geometries for medical and electronics machining.
Carbide tools are cemented tungsten-carbide cutting implements, typically containing 70-97% WC with cobalt or nickel binders, produced through powder pressing and liquid-phase sintering at 1,400°C to achieve hardness exceeding 1,600 HV for high-speed material removal. Inserts dominate volume throughput in metalworking applications where indexable geometries minimize downtime, while coated variants command premium positioning through TiAlN and DLC layers that extend tool life in aerospace superalloy machining. Solid carbide end mills sustain growth in mold-and-die fabrication where spindle speeds above 20,000 RPM demand homogeneous substrate integrity.
OSHA mandates govern cobalt exposure limits in US grinding operations, compelling manufacturers to adopt enclosed coolant systems and binder alternatives. ECHA's REACH restrictions on hexavalent chromium push coating houses toward PVD-only architectures. Japan's METI circular-economy guidelines require tungsten recovery quotas from spent inserts. Stakeholders must monitor binder-phase innovations and regional scrap-recovery infrastructure as decisive variables for cost structures and supply security.
Market Dynamics
REACH and EU AI Act compliance requirements are tightening material traceability standards across the carbide tools supply chain, forcing fabricators to reconfigure powder sourcing and coating house operations around documented cobalt and tungsten provenance.
Growth Catalysts
- Aerospace superalloy machining:Titanium and Inconel workpiece volumes are rising at Boeing and Airbus tier-1 suppliers, pulling coated carbide inserts with TiAlN layers into high-temperature cutting regimes where tool life directly determines throughput economics.
- Germany's precision engineering clusters:Stuttgart and Aachen host dense concentrations of mold-and-die fabricators and medical device machinists whose demand for micro-grain solid carbide end mills sustains premium pricing power for specialized geometries.
- METI circular-economy guidelines:Japan's mandatory tungsten recovery quotas from spent inserts are accelerating investment in closed-loop powder metallurgy, creating captive feedstock advantages for integrated manufacturers.
Market Restraints
- Tungsten concentrate supply concentration:Chinese state-owned miners control roughly two-thirds of global tungsten ore output, exposing non-integrated tool fabricators to price volatility and export quota disruptions.
- Cobalt binder cost exposure:DRC-sourced cobalt hydroxide prices swing with battery sector demand, compressing margins for standard-grade inserts where cobalt content exceeds 10% by weight.
- Ceramic and CBN substitution:Silicon nitride and cubic boron nitride cutting tools are displacing carbide in hardened steel finishing above 55 HRC, capping addressable market expansion in automotive powertrain machining.
Strategic Opportunities
- India's PLI scheme for machine tools:Production-linked incentives for capital goods manufacturing are drawing Sandvik Coromant and OSG Corporation toward joint ventures with domestic precision engineering firms in Pune and Bangalore.
- Additive-manufactured tool bodies:Convergence of powder-bed fusion with conventional carbide brazing enables conformal cooling channels in milling cutters, opening mold-and-die applications where thermal distortion limits conventional geometries.
- Digital tool monitoring platforms:Sensor-embedded inserts transmitting wear data to cloud analytics are creating recurring revenue streams through predictive replacement subscriptions, displacing spot procurement at Tier-2 metalworking shops.
Industry Challenges
- Powder metallurgy technician scarcity:Liquid-phase sintering expertise and HIP densification know-how are concentrating at retirement-age demographics in Ohio and Pennsylvania, constraining capacity expansion at US-based substrate producers.
- REACH SVHC notification timelines:ECHA's substance-of-very-high-concern candidate list expansions require 6-12 month compliance documentation for new cobalt binder formulations, delaying product launches and freezing R&D pipelines.
- Multi-axis grinding machine capex:5-axis CNC tool grinders with on-machine measurement exceed $2 million per unit, creating entry barriers for mid-cap specialists seeking to compete in complex geometry segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbide Tools Market |
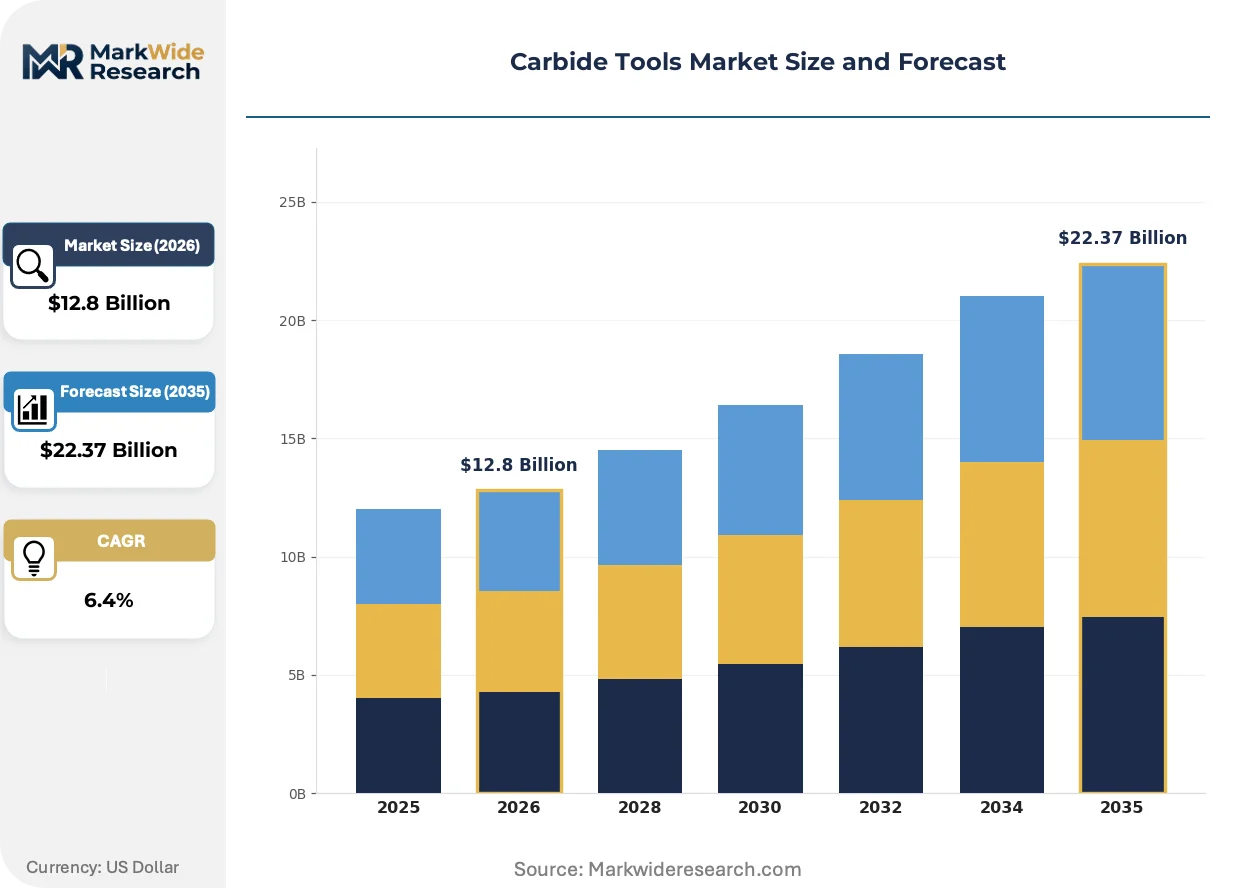
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: End Mills, Drills, Inserts, Tools for Grinding Application: Aerospace, Automotive Manufacturing, Woodworking, Metalworking End User: OEMs, Tier-1 Suppliers, Tooling Companies, Fabricators Technology: Coated, Uncoated, Solid, Tungsten Carbide |
| Companies Covered | Mitsubishi Materials Corporation, OSG Corporation, Sandvik Coromant, Walter AG, Gühring KG, Kennametal Inc., Tungaloy Corporation, Sumitomo Electric Industries Ltd., Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbide Tools Market Strategic Shifts & Innovations
Coating architectures and substrate microstructures are evolving faster than machine tool spindle capabilities, compressing replacement cycles and redefining value capture between insert producers and grinding service providers.
Multi-layer nanocomposite PVD coatings combining TiAlN with AlCrN are miniaturizing grain structures below 50 nanometers, enabling cutting-edge temperatures above 1,100°C without thermal cracking. Medical device machinists in Switzerland and Massachusetts are adopting these substrates for cobalt-chrome knee implant finishing, where surface integrity requirements prohibit coolant flooding. The technology is miniaturizing the performance gap between premium and standard insert tiers, forcing price compression at the mid-market.
ECHA's REACH restrictions on hexavalent chromium in electroplating operations are eliminating CVD coating alternatives for wear-resistant layers, redirecting investment toward PVD-only architectures. Coating houses in Germany and Austria are retooling sputtering lines to meet the 2024 sunset date for chromium trioxide use in tool surface treatments. Aerospace suppliers in Toulouse and Hamburg face the tightest compliance windows, accelerating qualification of chromium-free alternatives for flight-critical titanium machining.
Tool management as a service is displacing spot purchasing at mid-size metalworking job shops, with distributors bundling insert consumption analytics with just-in-time replenishment. Kennametal's North American branch network and Sandvik Coromant's Tooling Solutions contracts exemplify the model's traction among automotive suppliers managing mixed-part machining campaigns. The shift is most visible in Michigan and Ontario, where OEM vendor-managed inventory programs are cascading tier-down to sub-tier metalworkers.
Carbide Tools Market Segmentation
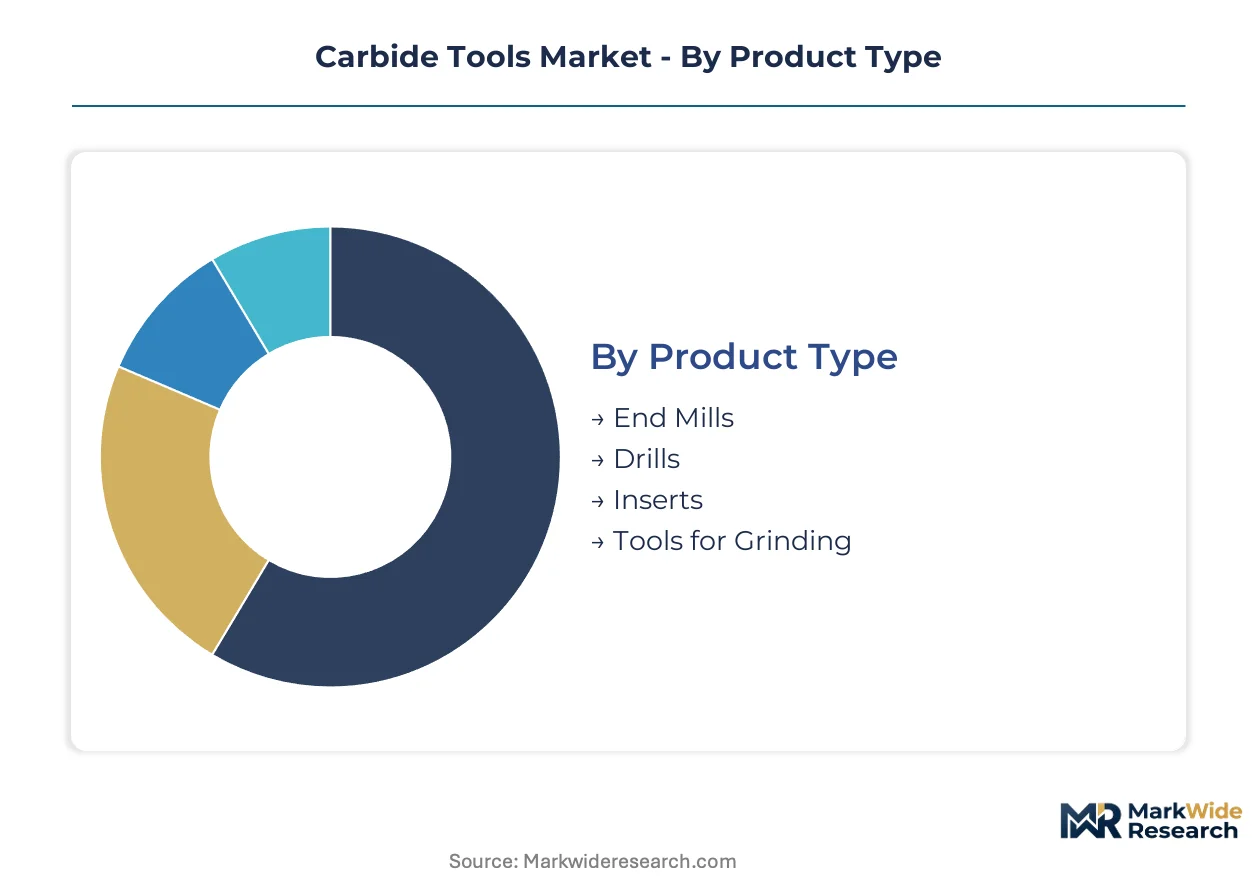
Carbide tools fragment across four dimensions that determine margin capture: product geometry dictates manufacturing complexity, application verticals set performance certification requirements, end-user scale shapes procurement economics, and coating technology governs price-to-wear ratios. Understanding these segment boundaries exposes where integrated manufacturers extract premium returns versus where commoditization pressures concentrate.
Product Type:
Margin pools concentrate in indexable geometries where material efficiency and regrind economics create recurring revenue streams, while solid tools compete on spindle-speed compatibility and substrate homogeneity.
- Inserts:Indexable carbide geometries with multiple cutting edges and standardized seat pockets dominate metalworking throughput. Demand concentrates at Boeing and Airbus tier-1 suppliers in Toulouse and Hamburg, where TiAlN-coated variants for titanium machining command pricing premiums tied directly to tool-life guarantees.
- End Mills:Solid or brazed-carbide rotating cutters with helical flute geometries sustain mold-and-die fabrication in Germany's Stuttgart cluster, where spindle speeds exceeding 20,000 RPM demand micro-grain substrate integrity without thermal distortion.
- Drills:Fluted cutting tools with point geometries optimized for hole-making operations in automotive powertrain blocks. Japanese and German OEMs specify these for crankshaft line boring where positional accuracy requirements exceed 10 microns.
- Tools for Grinding:Bonded abrasive implements with superabrasive layers for finish machining hardened steels. Demand from bearing manufacturers in Schweinfurt and medical device machinists in Massachusetts favors diamond-impregnated variants for cobalt-chrome implant finishing.
The dominant share belongs to Inserts, while End Mills is closing the gap fastest.
Application:
Volume distribution tracks capital equipment intensity across manufacturing verticals, with aerospace and automotive commanding specification authority that cascades through supplier tiers.
- Aerospace:Superalloy machining applications for titanium and Inconel workpieces at Boeing and Airbus assembly ecosystems. REACH and EU AI Act compliance requirements are tightening material traceability standards for flight-critical components, forcing documented tungsten and cobalt provenance.
- Automotive Manufacturing:Powertrain and chassis machining at high-volume OEM assembly plants. Michigan and Ontario-based suppliers manage mixed-part campaigns through vendor-managed inventory programs that bundle insert consumption with predictive analytics.
- Metalworking:General-purpose material removal across job shops and contract manufacturers. This segment spans the widest price spectrum, from standard-grade inserts for roughing operations to precision-ground geometries for finishing hardened steels.
- Woodworking:Profile cutting and joinery machining in furniture and construction materials. Applications favor uncoated carbide or diamond-tipped variants where abrasive wood fibers accelerate wear on standard geometries.
Aerospace commands the highest technology premium, though Automotive Manufacturing delivers the steepest volume expansion trajectory.
End User:
Procurement scale and technical specification authority separate price-takers from price-makers across the demand pyramid.
- OEMs:Original equipment manufacturers with in-house machining capacity and direct supplier qualification programs. These entities set performance benchmarks that propagate through their certified supplier networks.
- Tier-1 Suppliers:Contract manufacturers serving OEM assembly operations with dedicated production lines. Their tooling decisions follow OEM vendor lists, constraining switching flexibility.
- Tooling Companies:Specialized distributors and grinding service providers managing insert inventories and regrind operations. These intermediaries are consolidating through digital tool monitoring platforms that create recurring revenue streams.
- Fabricators:Small-to-mid-size job shops bidding on short-run contracts across mixed materials. Price sensitivity here is highest, with procurement shifting toward spot purchasing and generic substitute brands.
OEMs retain specification control, while Tooling Companies are capturing margin expansion fastest through service bundling.
Technology:
Coating architecture and substrate integrity separate performance tiers, with surface engineering investments determining thermal limits and wear resistance.
- Coated:Multi-layer PVD architectures combining TiAlN, AlCrN, or DLC layers deposited via sputtering or arc-evaporation processes. ECHA's REACH restrictions on hexavalent chromium are eliminating CVD alternatives, redirecting aerospace suppliers toward PVD-only qualification paths.
- Solid:Homogeneous carbide substrates without brazed or mechanically attached cutting edges. These sustain high-speed applications where centrifugal forces and thermal cycling stress joint integrity.
- Uncoated:Bare carbide substrates for applications where coating costs exceed wear-life benefits, or where material compatibility prohibits reactive layer contact.
- Tungsten Carbide:Cemented carbide compositions with 70-97% WC content and cobalt or nickel binders, produced through liquid-phase sintering. Japan's METI circular-economy guidelines are mandating recovery quotas from spent inserts, favoring integrated manufacturers with captive powder metallurgy.
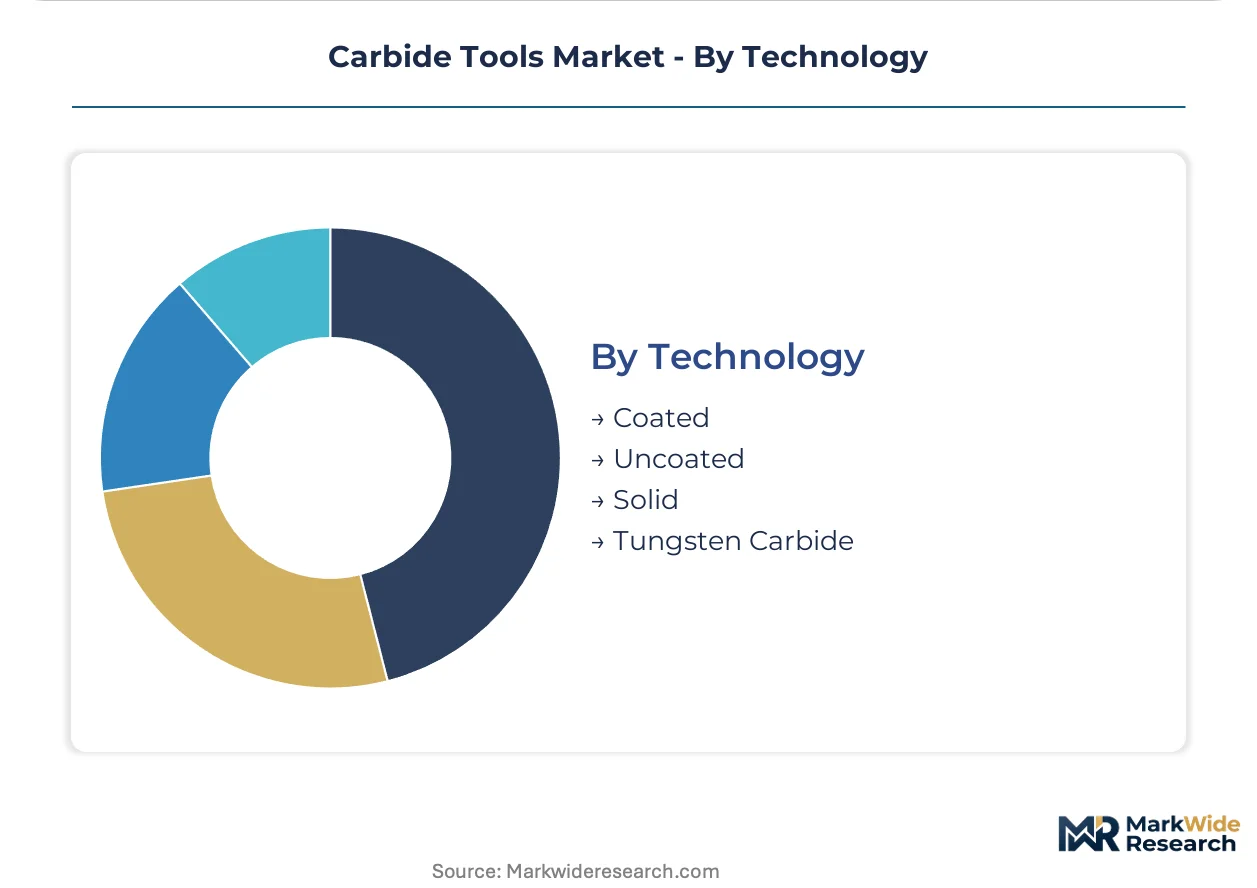
Coated technology holds the revenue majority, while Solid is expanding most quickly in additive-manufactured tool body applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbide tool consumption patterns diverge sharply by geography: aerospace-driven superalloy machining dominates Western demand, while automotive powertrain volume and electronics precision work anchor Asian markets. European fabricators prioritize REACH-compliant traceability and PVD coating investments, whereas Japanese and Chinese producers emphasize closed-loop tungsten recovery and captive powder metallurgy integration.
United States
Aerospace tier-1 suppliers at Boeing and Lockheed Martin ecosystems in Washington and Texas pull TiAlN-coated inserts for titanium machining. OSHA mandates on cobalt exposure limits compel grinding operations toward enclosed coolant systems and binder alternatives. Michigan and Ohio host dense automotive supplier networks where Kennametal's vendor-managed inventory programs bundle predictive analytics with just-in-time insert replenishment.
Germany
Stuttgart and Aachen precision engineering clusters sustain premium demand for micro-grain solid carbide end mills in mold-and-die fabrication. ECHA's REACH SVHC notification timelines freeze 6-12 month compliance documentation for new cobalt binder formulations, delaying product launches. Hamburg and Toulouse-facing aerospace suppliers accelerate qualification of chromium-free PVD coatings ahead of the 2024 sunset date for hexavalent chromium electroplating.
Japan
Medical device machinists in Nagoya and Osaka adopt nanocomposite PVD coatings for cobalt-chrome knee implant finishing where surface integrity prohibits coolant flooding. METI circular-economy guidelines mandate tungsten recovery quotas from spent inserts, favoring integrated manufacturers with captive powder metallurgy. OSG Corporation anchors specialized micro-grain geometries for electronics and medical applications from its Aichi Prefecture base.
China
State-owned miners control roughly two-thirds of global tungsten ore output, exposing non-integrated fabricators to price volatility and export quota disruptions. Yangtze River Delta machine tool builders consume standard-grade inserts for roughing operations at scale-driven automotive plants. Domestic coating houses retool sputtering lines to meet emerging traceability standards for EU-bound aerospace component machining.
India
PLI scheme production-linked incentives for capital goods manufacturing draw Sandvik Coromant and OSG Corporation toward joint ventures with domestic precision engineering firms in Pune and Bangalore. BIS standards govern tool steel imports while DGFT regulations shape tungsten concentrate sourcing. Tamil Nadu and Maharashtra automotive hubs generate rising insert consumption as OEM vendor-managed inventory programs cascade to sub-tier metalworkers.
Carbide Tools Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive powder-metallurgy capacity separating margin capture from commodity exposure. The upper tier commands feedstock security through backward integration into tungsten carbide production, while mid-cap specialists compete on geometry complexity and application-specific certifications. Two strategic archetypes dominate: integrated miners-with-fabricators leveraging raw material control, and pure-play tool engineers betting on digital service bundling. Competitive moves concentrate on M&A for regional distribution density and strategic partnerships for additive-manufactured tool body development.
Among Japanese fabricators, Mitsubishi Materials Corporation, OSG Corporation, and Tungaloy Corporation occupy positions spanning integrated materials-to-tools portfolios and specialized micro-grain geometries. These Tokyo and Nagoya-based entities exemplify the premium-tier vector where medical and electronics machining certifications sustain pricing power. Their geographic concentration in the Chubu and Kanto regions aligns with METI recovery mandates and dense automotive OEM supplier networks.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| OSG Corporation |
| Sandvik Coromant |
| Walter AG |
| Gühring KG |
| Kennametal Inc. |
| Tungaloy Corporation |
| Sumitomo Electric Industries Ltd. |
| Kyocera Corporation |
| Others |
Cost & Logistics Intelligence
Ninety-day powder inventory cycles at German coating houses now determine contract pricing power across the carbide tools sector, binding tungsten concentrate availability to insert premium tiers and exposing non-integrated fabricators to margin compression when Chinese export quotas tighten.
Pricing Analysis
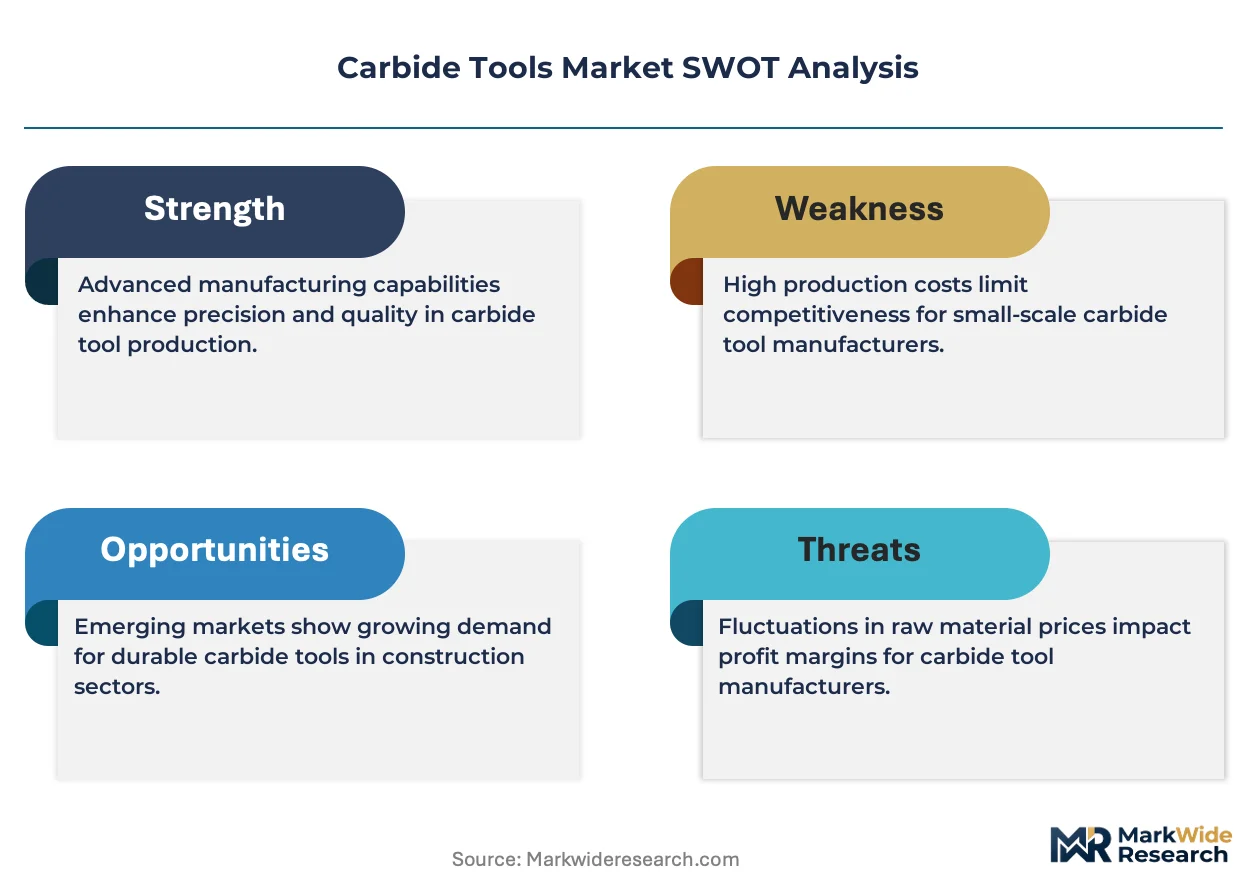
Long-term offtake agreements dominate procurement between aerospace tier-1 suppliers and integrated manufacturers, locking in cobalt carbide feedstock costs across multi-year horizons while spot purchasing persists among Michigan automotive job shops. Three-tier pricing structure across premium, standard, and economy levels separates TiAlN-coated aerospace inserts from uncoated roughing geometries, with brand premium and ISO 9001 certification tiering creating substantial spreads. Cost compression in standard-grade segments is intensifying because DRC cobalt hydroxide price volatility feeds directly into binder formulations. Fabricators bidding on short-run mixed-material contracts exhibit highest price sensitivity, whereas Boeing-qualified suppliers accept premium positioning for documented provenance.
Supply Chain Analysis
Inventory lead-times stretching to sixteen weeks for specialty cobalt powders from DRC smelters expose coating houses to production scheduling risks that cascade through just-in-time aerospace supply chains. Concentration in China, Vietnam, and Russia for tungsten ore extraction draws from geological endowment and state mining concessions, while cobalt hydroxide feeds from the Democratic Republic of Congo and Indonesian laterite projects. Single-source vulnerability concentrates at Chinese state-owned miners controlling two-thirds of global tungsten concentrate. Distribution runs through dense North American branch networks and German precision engineering clusters serving mold-and-die fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic and CBN substitution threats in hardened steel finishing above 55 HRC demand active defense from carbide incumbents, as silicon nitride cutting tools capture automotive powertrain applications once dominated by cobalt-bonded inserts.
For Market Incumbents: Shield aerospace qualification positions by accelerating chromium-free PVD coating certification ahead of REACH sunset deadlines, while deepening backward integration into tungsten carbide powder production to offset Chinese concentrate price volatility. Captive metallurgy capacity at Sandvik Coromant and Kennametal demonstrates how feedstock control defends margin structures against DRC cobalt swings. For New Entrants and Emerging Players: CE marking fast-track for medical device machining certifications opens white-space in Swiss and Massachusetts cobalt-chrome implant finishing, where nanocomposite PVD coatings command premium positioning and incumbent concentration remains lowest. Target India's PLI scheme joint ventures in Pune precision engineering clusters, leveraging production-linked incentives to establish regional grinding capacity without full metallurgy investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected tool divisions lacking digital service platforms or captive powder supply. Mid-cap specialists with aerospace qualification pipelines but insufficient tungsten recovery infrastructure represent acquisition archetypes with 5-10 year viability windows contingent on circular-economy mandate compliance. Monitor Japan's METI recovery quota enforcement as inflection signal for integrated versus non-integrated competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Powder | Captive feedstock production at Ohio and Pennsylvania facilities insulates margins from Chinese export quota disruptions. |
| Chromium-Free PVD Coating Certification | ECHA REACH compliance for Toulouse and Hamburg aerospace suppliers eliminates CVD alternative qualification paths. |
| Digital Tool Monitoring Platform Launch | Sensor-embedded inserts transmitting wear data to cloud analytics create recurring revenue at Michigan automotive job shops. |
| Joint Venture in India PLI Scheme | Pune and Bangalore partnerships with domestic precision engineering firms capture rising OEM vendor-managed inventory demand. |
| Additive-Manufactured Tool Body Development | Conformal cooling channels in milling cutters open Stuttgart mold-and-die applications where thermal distortion limits conventional geometries. |
Research Approach
The analysis maps coated inserts, solid end mills, drills, and grinding tools, each validated through powder metallurgy technicians, aerospace procurement managers, automotive Tier-1 supplier engineers, and coating house operations directors. Primary fieldwork combined structured interviews with grinding service providers and insert regrind operators alongside secondary validation through SEC 10-K filings, ECHA REACH substance notifications, METI circular-economy compliance reports, and customs trade data for tungsten concentrate flows. Bottom-up segment sizing triangulated against top-down market aggregation from powder production capacity and machine tool consumption indices.
Consistency checks validated volume and value outputs against external benchmarks including machine tool spindle speed adoption curves and aerospace superalloy machining throughput data. The forecast framework modeled product geometry, application vertical, coating technology tier, and end-user procurement scale dimensions across the projection horizon. CAGRs derived from segment-level growth rate convergence anchored in tungsten recovery infrastructure investment trajectories and PVD coating line expansion announcements.
Decision-makers should treat outputs as directional under assumptions of sustained aerospace build rates and stable Chinese tungsten export policy; material deviation in battery sector cobalt demand or REACH enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Sandblaster Market
Abrasives
RDP Powder Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Carborundum Market
Abrasives
New Zealand Abrasives Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Polishing Chemicals Market
Abrasives
Global Abrasives Market
Abrasives
Coated Abrasives Market
Abrasives
Grinding Wheels Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Glass Abrasives Market
Abrasives
Europe Abrasives Market