
 Sandblaster Market | 2026-2036
Sandblaster Market Size, Share, and Industry Trends Forecast 2026-2036
Sandblaster Market Analytics
Robotic nozzle positioning and closed-loop media recovery is tilting capital deployment toward automated platforms over manual cabinet systems. Graco leverages its fluid handling heritage to dominate portable sprayer-blast hybrid units for construction contractors. Clemco Industries anchors its position through captive manufacturing of blast pots and respirator-integrated helmets in North America. Blast-One International competes on aftermarket service density, operating rental fleets and certified technician networks across Australian mining corridors.
A sandblaster is a pneumatic or centrifugal device that propels abrasive media at controlled pressures to strip coatings, deburr metal, or impart surface roughness profiles measured in anchor-pattern mils. Portable units dominate construction job sites where mobility outweighs containment precision, while automated gantry systems command premium pricing in aerospace manufacturing for repeatable Ra values on turbine airfoils. Cabinet systems retain stable replacement demand from automotive restoration shops, though margin pools are migrating toward dust collection and media recycling attachments that extend operating cycles.
OSHA enforces permissible exposure limits on respirable crystalline silica, forcing operators toward wet blasting and non-silica media substitutes in US fabrication facilities. REACH regulates substance authorization for cobalt-dense steel shot across European foundries, redirecting procurement toward glass bead and ceramic alternatives. EPA air quality standards on particulate emissions shape equipment design for outdoor blasting operations. Stakeholders must weigh capital intensity of automated compliance against labor arbitrage from manual methods as regulatory thresholds tighten without grandfathering existing fleets.
Market Dynamics
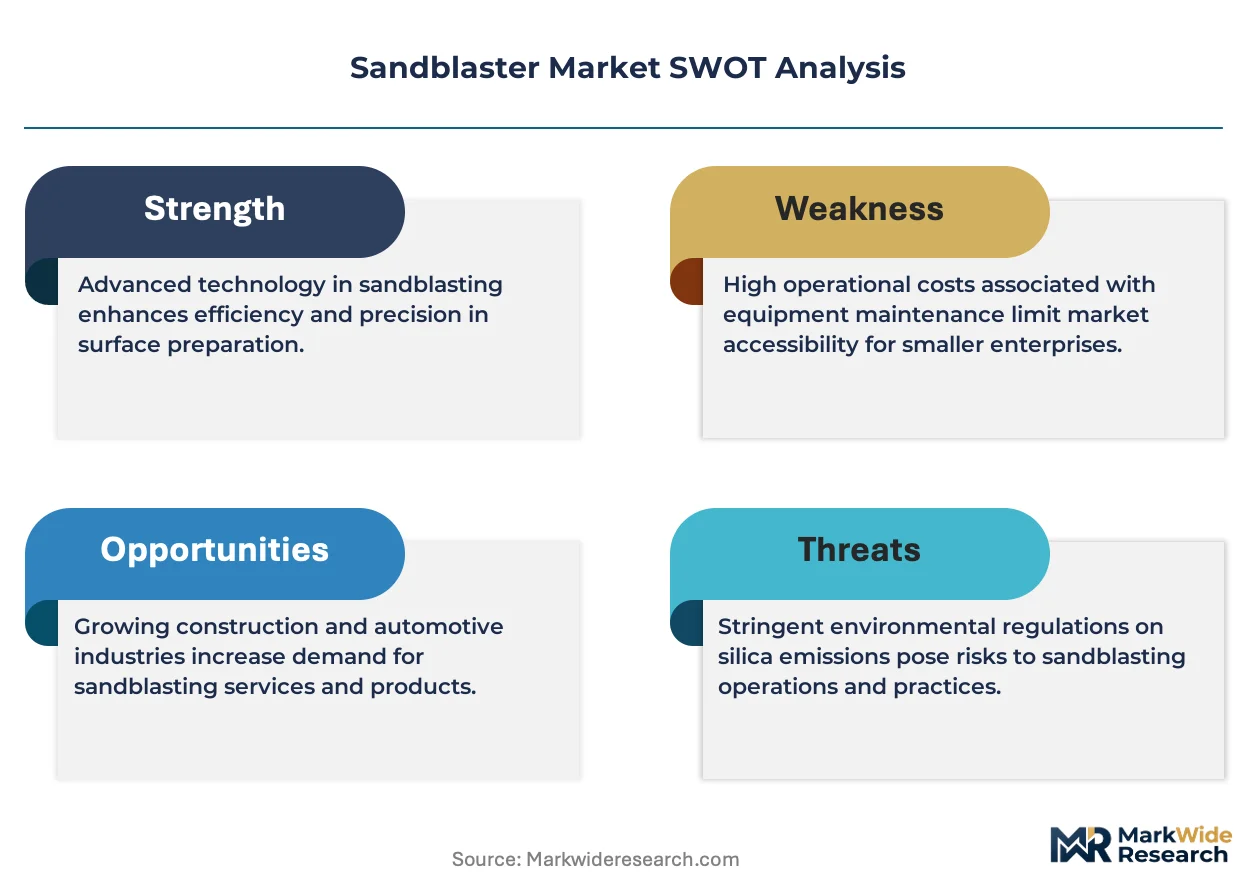
OSHA silica exposure limits and REACH substance restrictions are compressing permissible abrasive media compositions, forcing capital reallocation toward wet blasting infrastructure and closed-loop recovery systems that extend operating cycles.
Growth Catalysts
- Automated nozzle positioning:Robotic gantry systems deliver repeatable Ra values on turbine airfoils for aerospace manufacturers in Germany.
- REACH authorization pathways:Cobalt-dense steel shot restrictions redirect European foundries toward glass bead and ceramic abrasive substitutes.
- Dry-dock refurbishment:Shipyard clusters around Mumbai and Chennai drive surface preparation volumes for maritime asset lifecycle extension.
Market Restraints
- Input cost volatility:Garnet and aluminum oxide supply concentrates in Australian and Chinese mining corridors, exposing margins to freight and export duty fluctuations.
- Technical limitation:Wet blasting systems face throughput constraints in high-volume continuous production lines where drying cycles extend total process time.
- Regulatory friction:EPA air quality standards on particulate emissions impose equipment redesign burdens for outdoor blasting contractors without grandfathering existing fleet investments.
Strategic Opportunities
- Underpenetrated geography:Vietnamese shipbuilding yards lack automated blasting capacity, creating first-mover advantage for equipment-leasing models.
- Regulatory tailwind:EU Green Deal industrial decarbonization incentives favor energy-efficient media recovery systems over single-pass abrasive consumption.
- Technology convergence:Integration of real-time surface profilometry with robotic nozzle positioning enables closed-loop quality control in aerospace MRO facilities.
Industry Challenges
- Certified technician scarcity:OSHA-compliant respiratory protection training programs face enrollment bottlenecks, constraining fleet expansion for rental operators.
- Capex intensity:Automated gantry systems with integrated dust collection require upfront investment multiples exceeding manual cabinet configurations.
- Legacy integration friction:Retrofitting closed-loop media recovery onto existing blast pots demands custom engineering for non-standard vessel geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandblaster Market |
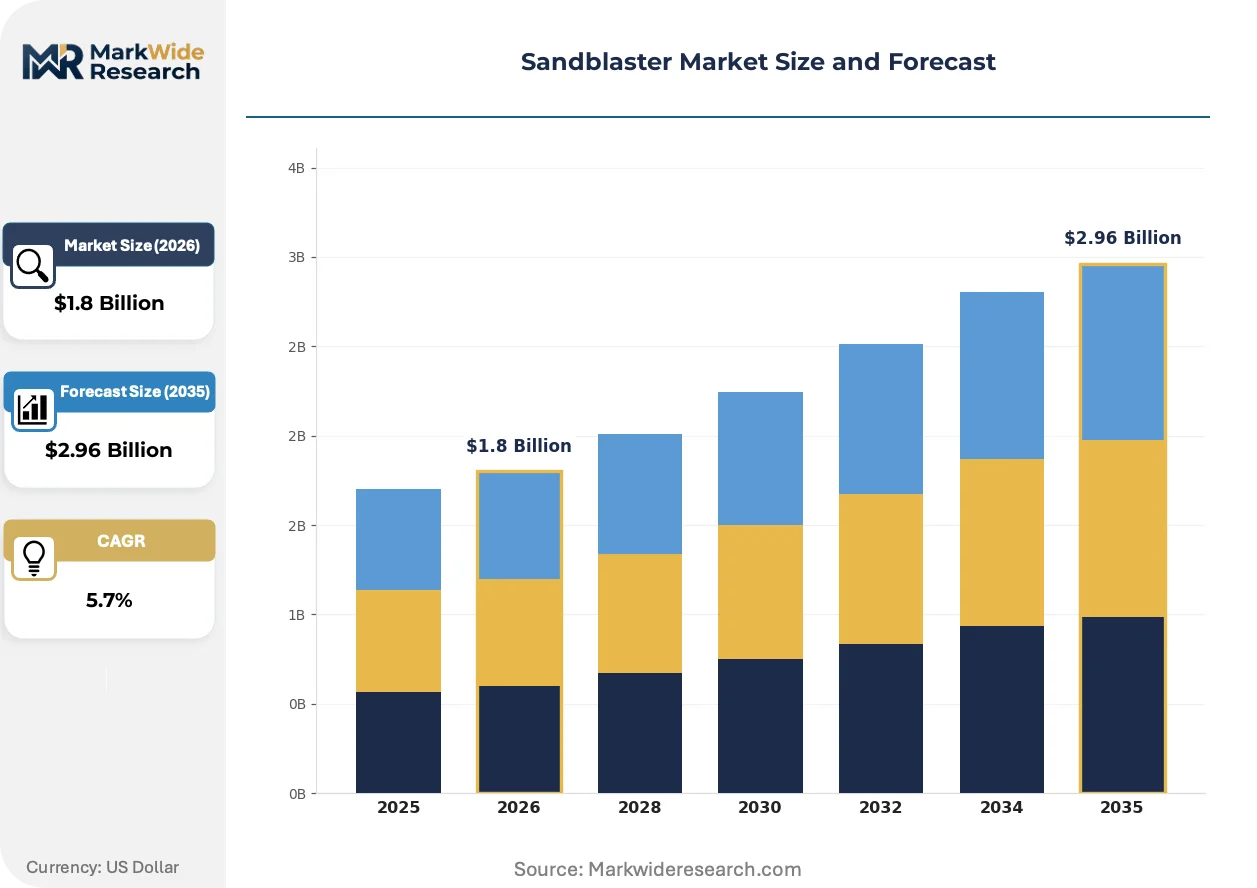
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Cabinet, Automated Application: Surface Preparation, Abrasive Blasting, Etching, Cleaning End User: Construction, Automotive, Aerospace, Manufacturing Media Type: Sand, Glass Beads, Steel Shots, Plastic Beads |
| Companies Covered | Graco, Blast-One International, Clemco Industries, Vaniman, BrandSafway, Wheelabrator, Sinto Group, Titan Abrasive, Empire Abrasive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandblaster Market Evolving Landscape
Wet blasting and vapor-abrasive hybrids are compressing the addressable market for dry silica-based systems as regulatory thresholds tighten without transition relief.
Ultrasonic-assisted wet blasting combines cavitation energy with conventional abrasive propulsion to strip coatings without substrate damage. Aerospace MRO facilities in Germany and France are adopting these systems for turbine component refurbishment where dimensional tolerances are tight. The technology is rendering obsolete dry suction-blast cabinets in precision restoration applications.
REACH substance authorization timelines for cobalt-containing abrasives are extending procurement lead times for European foundries. Manufacturers now pre-qualify glass bead and ceramic shot suppliers to avoid production interruptions. Steel shot formulations with reduced cobalt content are commanding price premiums in German and Italian metalcasting operations.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale fabrication shops. Rental fleets with bundled maintenance and media supply are capturing share from distributor sales channels in Australian mining corridors and US Gulf Coast petrochemical maintenance. This shift concentrates fleet ownership among specialized lessors with certified technician networks.
Sandblaster Market Segmentation
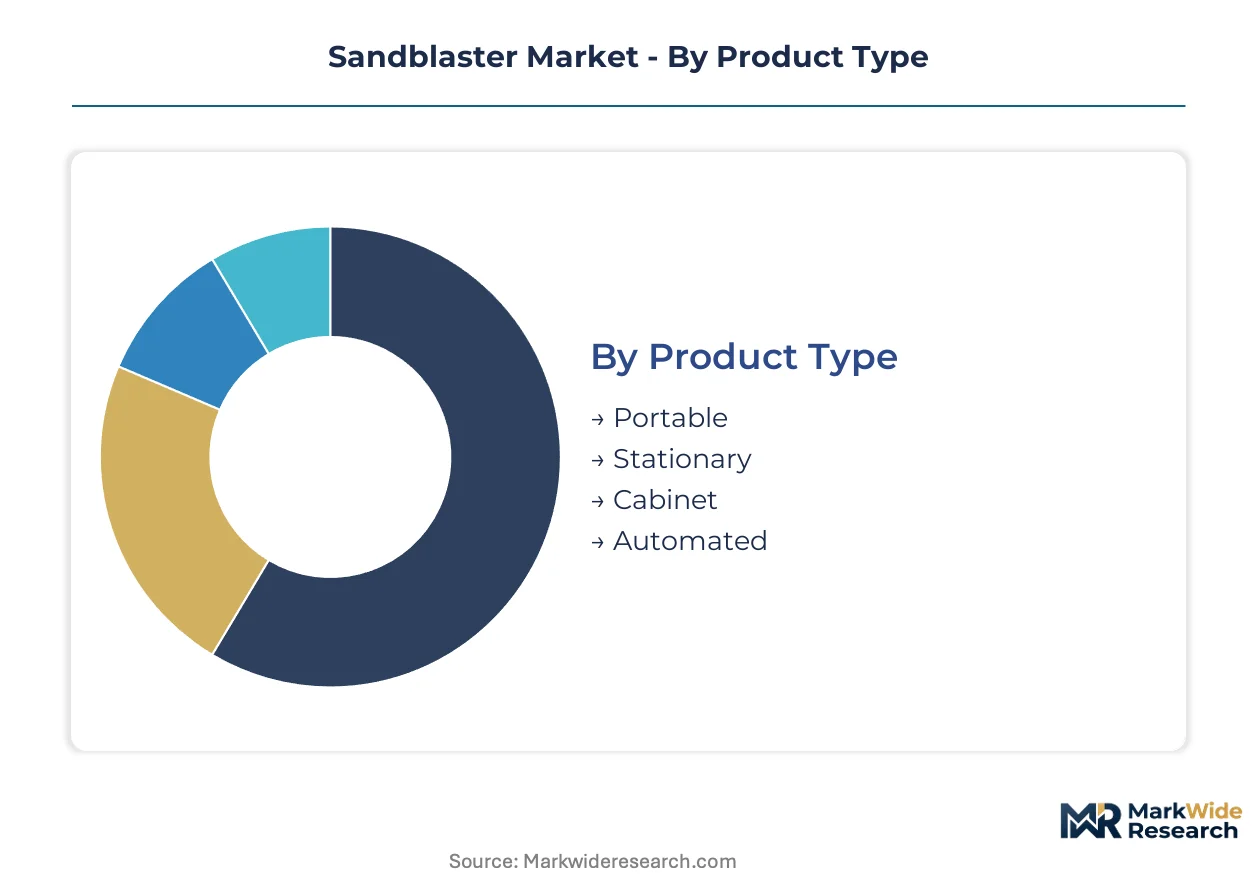
Sandblaster segmentation maps capital intensity against regulatory compliance requirements. Product architecture determines whether operators absorb OSHA silica limits through wet blasting retrofits or full system replacement cycles.
Product Type:
Mature cabinet configurations coexist with emerging automated platforms as aerospace manufacturers demand repeatable surface roughness values.
- Portable:Pneumatic or electric units mounted on wheeled chassis for construction job sites where mobility outweighs containment precision. Demand concentrates in US Gulf Coast petrochemical maintenance corridors where contractors prioritize equipment transportability between turnaround projects.
- Stationary:Fixed-installation blast rooms with integrated ventilation and media recovery for high-volume production environments. German automotive OEMs deploy these systems for powertrain component deburring where throughput justifies permanent floor space allocation.
- Cabinet:Enclosed manual systems with glove ports and viewing windows for small-part processing. Automotive restoration shops in France and Italy sustain replacement demand despite margin compression from dust collection attachment sales.
- Automated:Robotic gantry systems with closed-loop nozzle positioning and real-time surface profilometry. Aerospace MRO facilities in Germany are scaling these platforms for turbine airfoil refurbishment where dimensional tolerances are tight.
Portable units handle the majority of throughput; automated systems are gaining share fastest as regulatory thresholds tighten without grandfathering existing fleets.
Application:
Cost tier stratification separates commodity surface stripping from precision etching where substrate damage tolerance approaches zero.
- Surface Preparation:Coating removal and substrate profiling for protective paint adhesion. Shipyard clusters around Mumbai and Chennai drive volume for maritime asset lifecycle extension where dry-dock schedules compress project timelines.
- Abrasive Blasting:General-purpose media propulsion for rust removal and mill scale stripping. Construction contractors in Australian mining corridors favor portable wet-blasting variants to meet EPA particulate emission standards on remote job sites.
- Etching:Controlled material removal for decorative or functional surface texturing. Italian luxury automotive trim suppliers deploy precision cabinet systems for alloy wheel patterning where aesthetic consistency commands premium pricing.
- Cleaning:Non-destructive contaminant removal from delicate substrates. Aerospace manufacturers in France adopt ultrasonic-assisted wet blasting for turbine component refurbishment where cavitation energy substitutes for abrasive impact.
Surface preparation commands the installed base; etching applications are expanding most quickly as automotive styling differentiation intensifies.
End User:
Customer type determines procurement modality, with rental fleets capturing mid-scale fabrication shops while aerospace primes favor capital purchase with integrated service contracts.
- Construction:Infrastructure and building contractors deploying portable units for structural steel preparation. US-based contractors face OSHA respiratory protection training bottlenecks that constrain fleet expansion velocity.
- Automotive:OEM manufacturing and aftermarket restoration operations. German and Italian metalcasters pre-qualify glass bead suppliers to circumvent REACH authorization delays for cobalt-dense steel shot formulations.
- Aerospace:Commercial and defense aircraft manufacturers plus MRO providers. Turbine component refurbishment in Germany and France demands automated systems with closed-loop quality control for airfoil surface roughness repeatability.
- Manufacturing:General industrial fabrication and equipment production. European foundries redirect procurement toward ceramic abrasive alternatives as REACH substance restrictions extend cobalt-containing media lead times.
Construction absorbs the largest equipment rental volume; aerospace represents the steepest expansion trajectory as automated platform adoption accelerates.
Media Type:
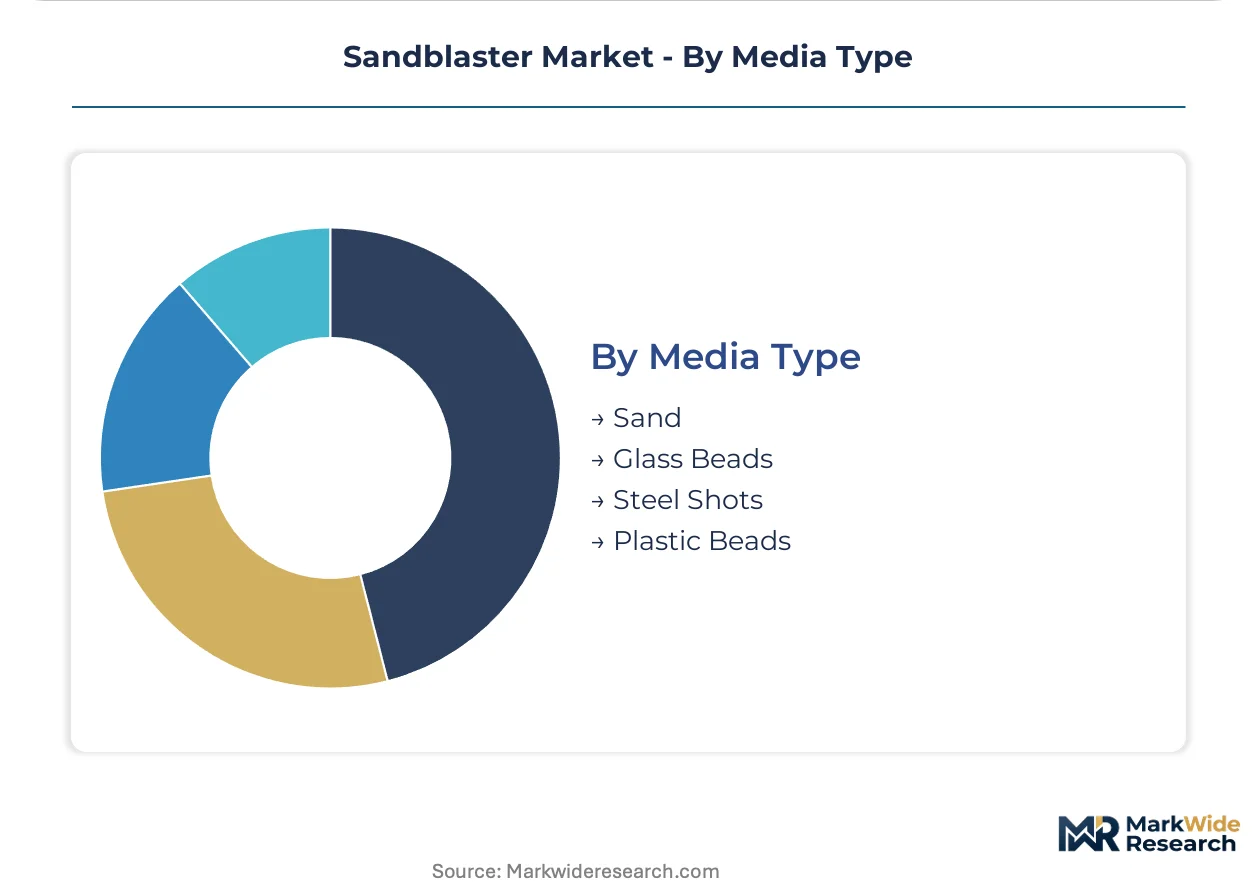
Supply concentration in Australian and Chinese mining corridors exposes procurement costs to freight and export duty volatility.
- Sand:Silica-based natural abrasive facing regulatory compression under OSHA respirable crystalline silica exposure limits. US fabrication facilities are displacing dry silica systems with wet blasting infrastructure to maintain compliance.
- Glass Beads:Spherical soda-lime glass media for non-ferrous surface finishing without substrate embedding. European foundries pre-qualify suppliers to avoid production interruptions from REACH authorization pathway delays.
- Steel Shots:Metallic abrasive in cast or conditioned formulations for aggressive material removal. Reduced-cobalt formulations command price premiums in German metalcasting operations as substance restrictions tighten.
- Plastic Beads:Thermoset polymer media for delicate substrate cleaning without dimensional change. Aerospace MRO facilities favor these for composite airframe component preparation where metallic contamination risks are prohibitive.
Steel shots retain the largest consumption volume; glass beads are climbing the fastest as REACH-driven substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment buyers cluster around shipyard refurbishment corridors, aerospace manufacturing hubs, and mining maintenance districts where surface preparation volumes justify capital deployment. Regulatory divergence across OSHA, REACH, and national mining safety codes shapes procurement specifications for abrasive media and dust containment systems.
United States
Gulf Coast petrochemical turnaround contractors drive portable equipment rental volumes between scheduled maintenance windows. OSHA respirable crystalline silica exposure limits force fabrication shops toward wet blasting retrofits or full system replacement cycles. Houston and Corpus Christi anchor the densest contractor fleet concentrations for offshore platform surface preparation.
Germany
Aerospace MRO facilities in Bavaria and Baden-Württemberg scale automated gantry systems for turbine airfoil refurbishment requiring tight dimensional tolerances. REACH substance authorization pathways for cobalt-dense abrasives extend procurement lead times, redirecting foundries toward pre-qualified glass bead suppliers. Munich-Stuttgart industrial corridor hosts the steepest automated platform adoption rates in European aerospace manufacturing.
India
Dry-dock surface preparation volumes climb at shipyard clusters around Mumbai and Chennai where maritime asset lifecycle extension compresses project timelines. Central Electricity Authority norms on industrial emissions shape equipment specifications for coastal fabrication facilities. Mazagon Dock and Cochin Shipyard drive concentrated demand for high-capacity stationary blast rooms.
Australia
Mining corridor maintenance contractors favor portable wet-blasting variants to meet EPA particulate emission standards on remote Pilbara and Bowen Basin job sites. Equipment-as-a-service contracting displaces outright purchase as rental fleets bundle maintenance and media supply. Perth and Brisbane anchor the densest certified technician networks for fleet support.
France
Aerospace manufacturers in Toulouse and Nantes adopt ultrasonic-assisted wet blasting for turbine component refurbishment where cavitation energy substitutes for abrasive impact. ANSM workplace exposure guidelines complement REACH substance restrictions on cobalt-containing media. Île-de-France precision metalcasters pre-qualify ceramic abrasive suppliers to circumvent authorization delays.
Sandblaster Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consolidation concentrates among North American and European equipment fabricators with captive manufacturing of blast pots and respiratory protection systems. Three archetypes dominate: integrated safety-equipment conglomerates, abrasive-media specialists with downstream equipment extension, and regional fabrication shops serving mining maintenance corridors. Competitive moves center on rental fleet expansion with bundled technician certification and automated platform technology licensing to aerospace MRO facilities.
Among North American equipment fabricators, Graco and Clemco Industries exemplify divergent strategic positions. Graco leverages fluid handling heritage across portable sprayer-blast hybrid configurations, while Clemco anchors market presence through captive manufacturing of blast pots and respirator-integrated helmets. Blast-One International occupies a distinct service-density position, operating rental fleets and certified technician networks across Australian mining corridors where equipment-as-a-service contracting displaces distributor sales channels.
| Leading Market Players |
|---|
| Graco |
| Blast-One International |
| Clemco Industries |
| Vaniman |
| BrandSafway |
| Wheelabrator |
| Sinto Group |
| Titan Abrasive |
| Empire Abrasive |
| Others |
Value Network & Pricing Analysis
Australian garnet mining corridors around Port Gregory anchor global abrasive feedstock capacity, with extraction volumes and export duty regimes transmitting directly into downstream media pricing power for European and North American equipment operators.
Pricing Analysis
Cost-plus contracts with aluminum oxide indexation dominate procurement between Indian shipyards and media suppliers, with freight differentials from Chinese bauxite refineries creating price separation between coastal and inland buyers. Three-tier pricing structure across automated gantry, stationary blast room, and portable cabinet configurations reflects certification grade and integrated dust collection specifications. Cost compression in manual cabinet tiers is intensifying because OSHA-compliant respiratory attachments are becoming mandatory without grandfathering. Construction contractors in Australian mining corridors exhibit the highest price sensitivity, while aerospace MRO facilities in Germany demonstrate minimal elasticity for automated platforms with closed-loop quality control.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for aluminum oxide and garnet feedstocks. Raw material extraction concentrates in Australia, China, and India, with equipment fabrication anchored in Germany, Italy, and the United States. Blast pot manufacturing draws from steel plate and pneumatic valve components, while respiratory protection systems rest on silicone and filtration media supply. Distribution runs through specialized industrial equipment distributors and rental fleet operators with certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sandblaster incumbents face substitution pressure from laser ablation and chemical stripping technologies in precision aerospace applications, requiring defensive positioning around regulatory-compliant wet blasting infrastructure.
For Market Incumbents: Pre-empt laser ablation substitution in turbine component refurbishment by accelerating ultrasonic-assisted wet blasting R&D partnerships with German aerospace MRO facilities. Deepen backward integration into cobalt-reduced steel shot formulations to circumvent REACH authorization bottlenecks. Captive manufacturing of respirator-integrated helmets creates switching costs against rental fleet competitors. For New Entrants and Emerging Players: Vietnamese shipbuilding yards lacking automated blasting capacity represent the most penetrable entry point for equipment-leasing models with bundled media supply and technician certification. Target coastal fabrication facilities in India facing Central Electricity Authority emission norms with wet blasting retrofit packages. Equipment-as-a-service contracting with maintenance bundling offers lower capital barrier than outright purchase competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because OSHA silica limits and REACH substance restrictions are tightening without transition relief, forcing replacement cycles. Acquisition targets should emphasize rental fleet operators with dense certified technician networks and automated platform technology licensing to aerospace MRO facilities. Watch for EPA particulate emission standard revisions as inflection indicators for wet blasting adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Technology Licensing | Enables aerospace MRO facilities in Germany to achieve repeatable Ra values on turbine airfoils. |
| Backward Integration into Media Manufacturing | Captures margin pools from cobalt-reduced steel shot formulations demanded by REACH compliance. |
| Equipment-as-a-Service Fleet Expansion | Displaces distributor sales channels in Australian mining corridors through bundled maintenance contracts. |
| Wet Blasting Retrofit Development | Addresses OSHA silica exposure limits for US fabrication facilities without full system replacement. |
| Certified Technician Network Scaling | Resolves enrollment bottlenecks constraining rental fleet expansion velocity in construction segments. |
Research Methodology
A standing panel of blast equipment maintenance directors, plant engineers at automotive OEMs, aftermarket service heads, and procurement leads at shipyard operators provided ongoing calibration across primary interviews and secondary validation. Secondary sources included customs and trade data from Australian and Indian export authorities, SEC 10-K filings from listed industrial equipment manufacturers, and OSHA enforcement action databases. Bottom-up equipment shipment tallies triangulated against top-down abrasive media consumption estimates.
Scenario-bracketing around regulatory enforcement intensity and mining capital expenditure cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application precision tier, end-user industry, and media composition. CAGRs were derived from equipment replacement cycle analysis and regulatory-driven retrofit demand. Industry-specific inputs incorporated REACH authorization timeline probabilities and dry-dock refurbishment schedules at Indian shipyard clusters.
Macroeconomic conditions sit as an overlay; deviation in mining commodity prices and ocean freight rates would shift the trajectory of media cost pass-through and equipment procurement timing. Forecasts reflect assumptions about regulatory grandfathering policies and technician training program expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Polishing Chemicals Market
Abrasives
Global Abrasives Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Abrasive Rolls Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Vitrified Bonded Grinding Wheels Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Fine Sandpaper Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Carbide Tools Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Synthetic Abrasives Market