
 Carbide Inserts Market | 2026-2036
Carbide Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Carbide Inserts Market Analysis
Aerospace's share of insert consumption is realigning upward as titanium-alloy airframe programs multiply. Sandvik Coromant dominates coated-grade development for heat-resistant superalloys. Kennametal anchors North American supply through captive powder production and direct mill relationships. Kyocera Corporation specializes in cermet formulations for high-speed finishing of hardened steels.
Carbide inserts are sintered composite cutting tools comprising tungsten carbide particles bound in cobalt or nickel matrices, typically pressed and sintered at temperatures exceeding 1,400°C to achieve hardness values near 1,600 HV. They serve as indexable cutting edges in lathes, mills, and drill bodies, enabling repeatable tool positioning without full tool replacement. Turning inserts command the largest volume share across global metalworking, while TiAlN-coated variants capture expanding margin pools in aerospace and medical-grade titanium machining. Drilling inserts remain the fastest-growing product type as deep-hole applications in energy equipment multiply.
ISO 513 classification standards govern insert grade designation for steel, stainless, cast iron, and non-ferrous applications, while OSHA silica exposure limits shape carbide powder handling protocols in US manufacturing plants. The EU's REACH framework restricts cobalt sourcing disclosures, compelling European toolmakers to certify supply-chain provenance. Stakeholders must monitor binder substitution timelines and coating deposition technology shifts to preserve grade qualification status across regulated end-use sectors.
Market Dynamics
Cobalt supply-chain scrutiny from REACH and MEE discharge mandates is forcing rapid binder chemistry transitions across European and Chinese manufacturing plants. Powder metallurgy houses must requalify entire grade portfolios under compressed timelines.
Growth Catalysts
- Titanium-alloy airframe expansion:Aerospace OEMs are qualifying new coated grades for heat-resistant superalloy machining on next-generation engine programs.
- REACH compliance deadlines:European toolmakers are accelerating low-cobalt formulation R&D to meet ECHA disclosure requirements without supply disruption.
- Deep-hole energy applications:Drilling insert demand from oilfield equipment and power generation turbine manufacturers is multiplying order volumes for indexable drill bodies.
Market Restraints
- Tungsten concentrate volatility:Chinese state reserve releases and export quota adjustments create raw material cost instability for sintering operations.
- Binder substitution physics:Nickel and iron-based matrices fail to match cobalt's wetting properties at grain boundaries, limiting immediate grade-for-grade replacement.
- MEE discharge enforcement:Chinese environmental inspectors are suspending production permits at carbide powder facilities exceeding wastewater metal limits.
Strategic Opportunities
- Medical-grade titanium finishing:Orthopedic implant manufacturers require certified insert grades for bone-screw thread milling with sub-micron surface finish specifications.
- Tool-as-a-service models:Machine shops are migrating from capital purchase to per-part pricing agreements with integrated regrind and coating refresh cycles.
- India precision machining cluster:Automotive component suppliers around Pune and Chennai are expanding multi-axis turning capacity requiring ISO-certified insert supply.
Industry Challenges
- Grade requalification timelines:Aerospace OEMs demand twelve-to-eighteen-month validation cycles for new binder formulations, freezing supplier switches.
- PVD coating technician scarcity:Arc-evaporation and sputtering expertise concentrates at a handful of European and Japanese equipment houses, constraining capacity expansion.
- Legacy ERP integration:Tier-two distributors struggle to connect electronic data interchange protocols with manufacturer inventory systems for real-time availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbide Inserts Market |
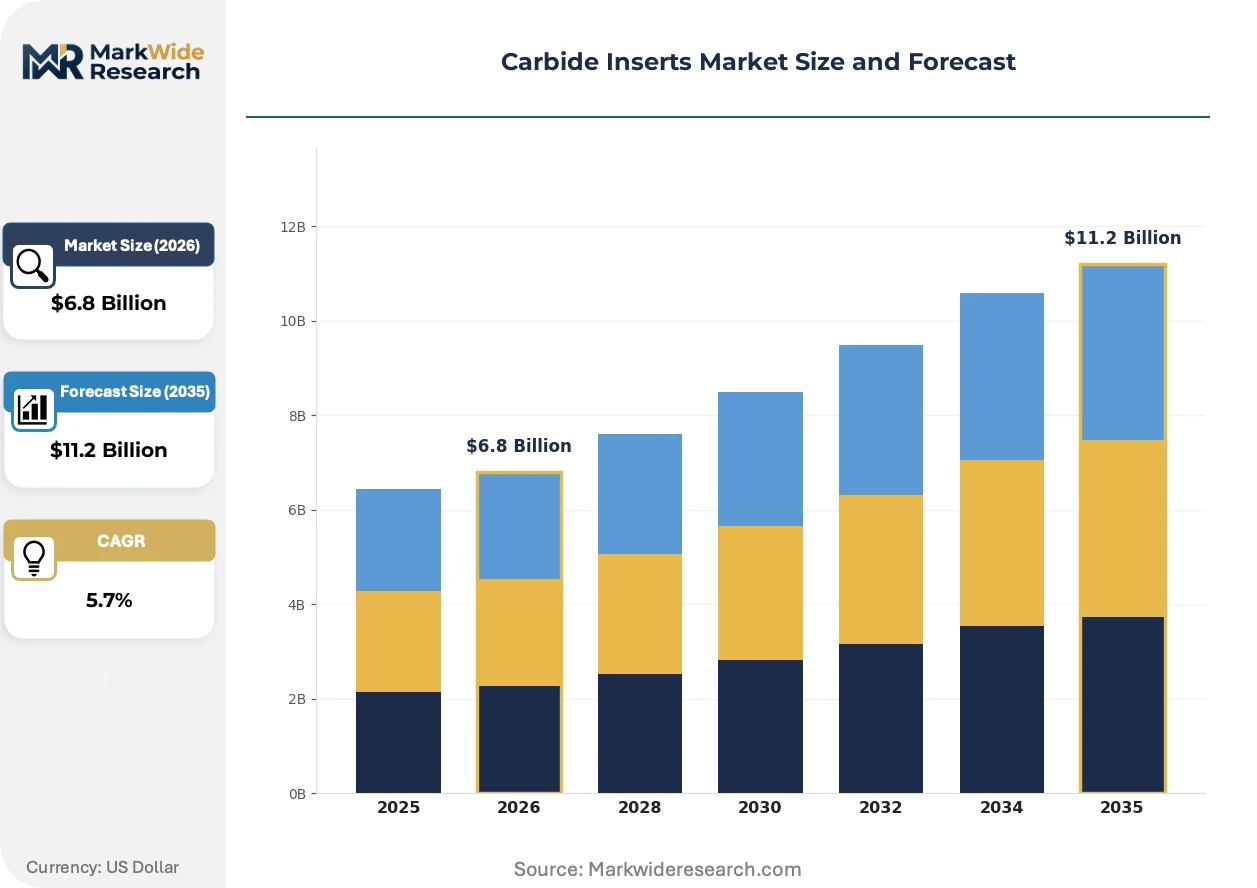
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turning Inserts, Milling Inserts, Drilling Inserts, Chip Breakers Application: Metalworking, Aerospace, Automotive, Construction End User: Manufacturers, Job Shops, OEMs, Tool Distributors Coating Type: Cermet Coated, TiN Coated, TiAlN Coated, Uncoated |
| Companies Covered | Tungaloy Corporation, Sumitomo Electric Industries, Ltd., Sandvik Coromant, Seco Tools AB, Ceratizit SA, Kennametal Inc., Kyocera Corporation, Walter AG, Mitsubishi Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbide Inserts Market Emerging Trajectories
Physical vapor deposition technology is consolidating around high-power pulsed magnetron sputtering configurations. Tool manufacturers are racing to secure coating capacity before aerospace qualification windows close.
Multi-layer TiAlN-TiSiN architectures are consolidating as the dominant platform for high-temperature alloy machining. Engine component suppliers in Germany and the United States are specifying these coatings for titanium beta-phase turning operations. The technology is consolidating supplier tiers by requiring captive arc-evaporation lines that smaller competitors cannot finance.
China's MEE discharge rules are tightening effluent standards for cobalt and tungsten compounds at carbide powder synthesis facilities. Plants in Hunan and Jiangxi provinces face retrofit investments or consolidation into state-controlled industrial parks. European importers are demanding third-party wastewater audit certificates to maintain qualified supplier status under REACH due diligence obligations.
Machine shops are unbundling tool management from equipment purchase agreements, contracting directly with insert manufacturers for consignment inventory and technical field support. Large automotive stampers in Stuttgart and Detroit are piloting vendor-managed stock programs with automated consumption tracking. This pattern is compressing distributor margins while rewarding manufacturers with direct mill relationships and application engineering depth.
Carbide Inserts Market Segmentation
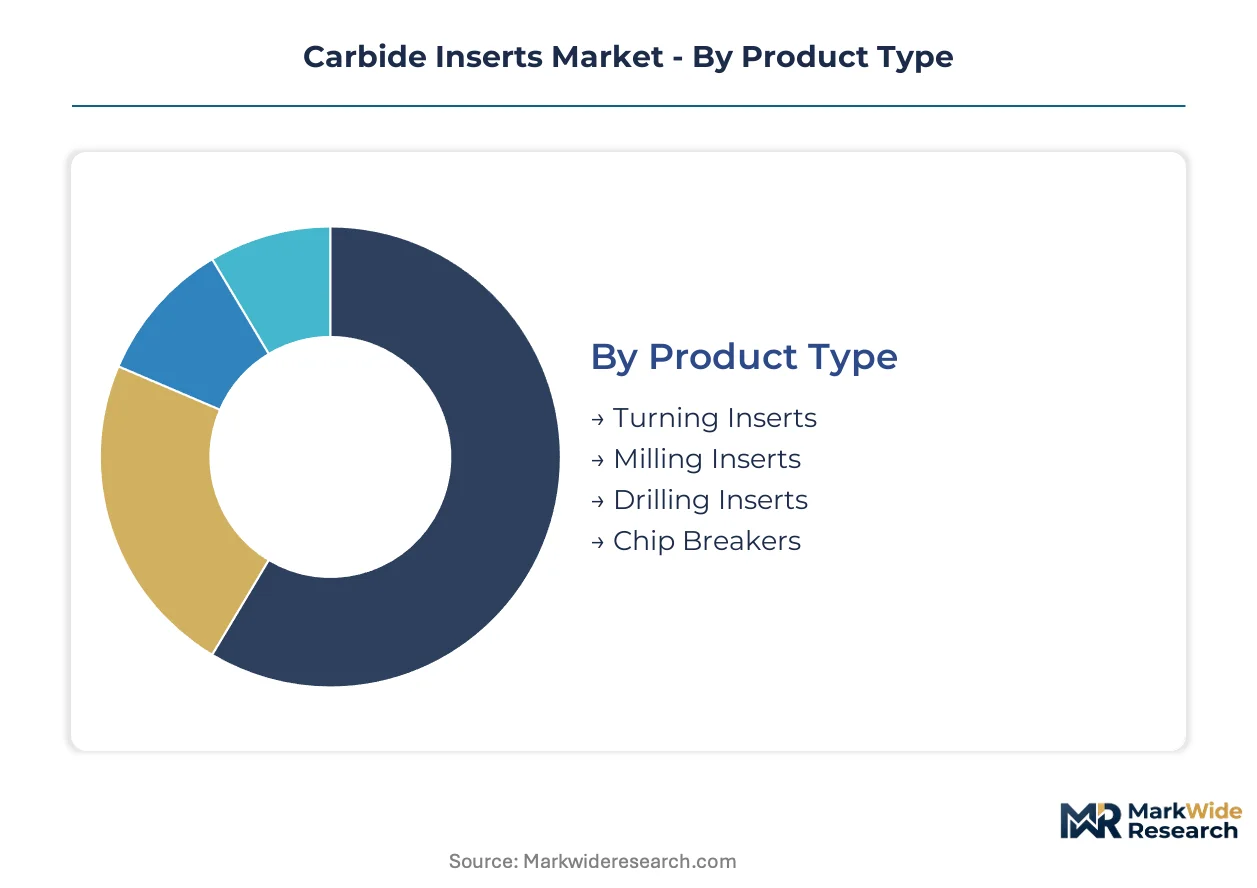
Carbide insert specification varies sharply across machining disciplines, with geometry, substrate, and coating chemistry calibrated to workpiece material and cutting parameters. Segmentation reveals how suppliers allocate R&D resources between high-volume standard grades and application-specific formulations.
Product Type:
Customization intensity spans from commodity geometries for general turning to engineered chip control for exotic alloys.
- Turning Inserts:Rhombic, triangular, and round geometries dominate lathe operations across steel and cast iron applications. German precision machining clusters around Stuttgart consume the highest volumes for automotive powertrain finishing.
- Milling Inserts:Octagonal and square cutting edges with helical rake angles handle interrupted cuts in die and mold machining. Aerospace frame component manufacturers in the United States specify these for titanium pocketing operations on structural brackets.
- Drilling Inserts:Indexable drill bodies with central and peripheral inserts enable deep-hole penetration in energy equipment.
- Chip Breakers:Precision-ground topographies control swarf formation in high-feed turning of ductile materials.
Leading the category by volume: Turning Inserts. Expanding most quickly: Drilling Inserts.
Application:
Performance requirements escalate from general metalworking tolerances to aerospace surface integrity specifications.
- Metalworking:General-purpose machining of carbon steels, stainless grades, and non-ferrous alloys across job shop environments. Indian automotive component suppliers around Pune drive standard-grade consumption for transmission shaft production.
- Aerospace:Heat-resistant superalloy and titanium beta-phase machining with sub-micron surface finish requirements. Engine program contractors in Germany and the United States qualify coated grades under twelve-to-eighteen-month validation protocols.
- Automotive:High-volume turning and milling of crankshafts, camshafts, and brake rotors with Cpk-driven tool life targets.
- Construction:Heavy-duty milling of structural steel and wear-resistant plate for earthmoving equipment frames.
Steepest expansion trajectory: Aerospace. Highest absolute consumption: Metalworking.
End User:
Procurement sophistication ranges from spot-buy distributors to integrated tool management contracts.
- Manufacturers:Captive machine shops within automotive and aerospace OEMs with direct mill relationships and consignment inventory programs.
- Job Shops:Independent contract machinists purchasing through distributors with price-sensitive spot-buy patterns.
- OEMs:Original equipment builders specifying approved supplier lists for production tooling with technical field support requirements.
- Tool Distributors:Tier-two and tier-three channel partners struggling with legacy ERP integration for real-time availability.
Capturing margin expansion: Manufacturers. Facing margin compression: Tool Distributors.
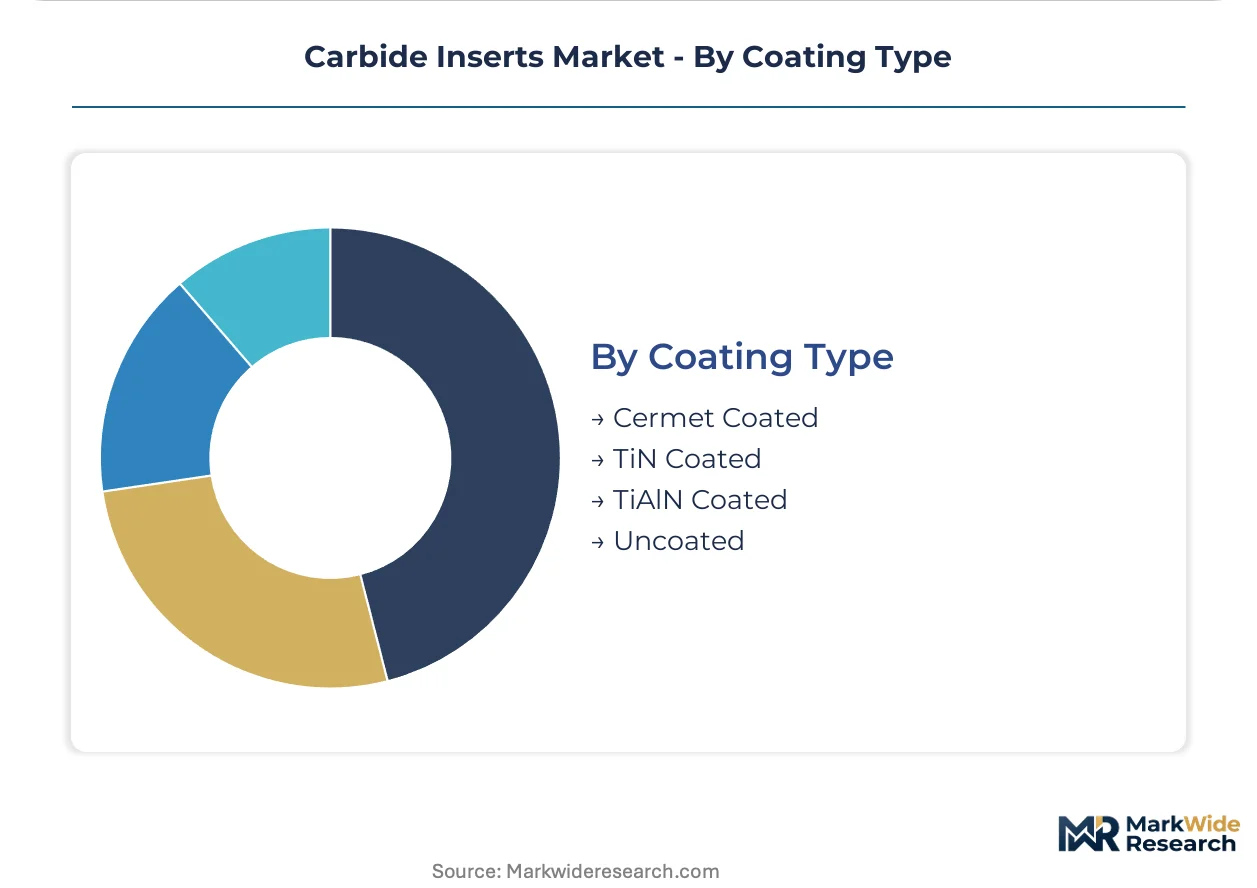
Coating Type:
Coated variants command premium positioning against uncoated substrates in high-temperature and high-speed regimes.
- Cermet Coated:Titanium carbonitride-based ceramics for high-speed finishing of hardened steels above 45 HRC. Japanese equipment manufacturers specialize in these formulations for precision bearing race machining.
- TiN Coated:Gold-colored titanium nitride for general-purpose steel machining with moderate speed and feed parameters.
- TiAlN Coated:Aluminum-rich architectures for heat-resistant superalloy machining at elevated temperatures. Multi-layer TiAlN-TiSiN configurations consolidate as the dominant platform for aerospace titanium beta-phase turning.
- Uncoated:Substrate-only inserts for non-ferrous materials where coating adhesion fails or chip welding risks dominate.
Highest value capture: TiAlN Coated. Lowest unit economics: Uncoated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hunan Xiangtan Economic and Technological Development Zone concentrates carbide powder synthesis capacity under MEE discharge compliance mandates. Germany's precision machining corridor around Stuttgart anchors European coated-grade demand for aerospace powertrain components. India's automotive component belt drives standard-grade consumption for transmission and engine part production.
Germany
Engine program contractors in Stuttgart and Aachen qualify multi-layer TiAlN-TiSiN coated grades for titanium beta-phase turning operations. REACH compliance through ECHA mandates cobalt supply-chain disclosure and low-binder formulation transitions. The Baden-Württemberg precision machining cluster consumes the highest European volumes for automotive powertrain finishing.
China
State reserve releases of tungsten concentrate and export quota adjustments create raw material cost volatility for sintering operations. MEE discharge enforcement suspends production permits at carbide powder facilities in Hunan and Jiangxi provinces exceeding wastewater metal limits. The Xiangtan industrial park consolidates powder synthesis into state-controlled complexes with third-party audit requirements.
United States
Aerospace frame manufacturers specify octagonal milling inserts for titanium pocketing on structural brackets. OSHA silica exposure limits shape carbide powder handling protocols at domestic manufacturing plants. The Detroit automotive stamping corridor pilots vendor-managed inventory programs with automated consumption tracking for high-volume turning operations.
India
Automotive component suppliers around Pune and Chennai expand multi-axis turning capacity requiring ISO-certified insert supply. BIS standards govern tool steel specifications for domestic certification. The Maharashtra-Gujarat automotive belt drives standard-grade consumption for transmission shaft and crankshaft production at contract machining facilities.
Japan
Equipment manufacturers specialize in cermet formulations for precision bearing race machining above 45 HRC. METI industrial standards coordinate domestic tool steel and coating chemistry specifications. The Nagoya precision machinery cluster concentrates high-speed finishing expertise for hardened steel applications.
Carbide Inserts Market Vendor Landscape
Top-tier vendors anchor aerospace and automotive OEM supply through captive powder production and direct mill relationships, while mid-tier specialists compete on application engineering for job shop environments. The vendor base stratifies across three tiers: integrated powder-to-insert manufacturers with captive coating lines, regional substrate specialists purchasing PVD services, and commodity geometry distributors. Two dominant competitive moves are consolidating: backward integration into tungsten carbide powder synthesis to secure concentrate supply, and strategic partnerships with machine tool builders for tool-as-a-service program deployment.
Within the integrated manufacturing tier, Sandvik Coromant, Kennametal Inc., and Kyocera Corporation occupy positions defined by captive production capabilities. Sandvik Coromant represents the European archetype with headquarters-derived geographic positioning in coated-grade development. Kennametal Inc. exemplifies North American supply anchoring through in-house powder operations. Kyocera Corporation sits within the Japanese specialist tradition for cermet and ceramic matrix formulations. These three entities collectively illustrate how geographic concentration of powder metallurgy expertise shapes competitive positioning across regulated end-use sectors.
| Leading Market Players |
|---|
| Tungaloy Corporation |
| Sumitomo Electric Industries, Ltd. |
| Sandvik Coromant |
| Seco Tools AB |
| Ceratizit SA |
| Kennametal Inc. |
| Kyocera Corporation |
| Walter AG |
| Mitsubishi Materials Corporation |
| Others |
Supply Flow & Price Mechanics
High-power pulsed magnetron sputtering adoption simultaneously elevates coating capital costs and consolidates supplier tiers by requiring captive arc-evaporation lines that smaller competitors cannot finance. This production-method transition concentrates pricing power among integrated manufacturers while compressing margins for regional substrate specialists purchasing PVD services.
Pricing Analysis
Short lead-time premiums dominate aerospace procurement, where engine program contractors pay substantial markups for qualified coated grades against twelve-to-eighteen-month validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified TiAlN-TiSiN formulations from general-purpose TiN coatings and commodity uncoated substrates. Price differentiation hinges on certification grade and volume scale, with automotive OEMs extracting discounts through consignment inventory programs. Price erosion runs through distributor tiers as manufacturers deploy direct mill relationships and tool-as-a-service contracts. Job shops exhibit highest price sensitivity, while aerospace OEMs prioritize technical field support and grade qualification status over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Nagoya maintain hub-and-spoke patterns for just-in-time delivery to precision machining clusters. Geographic supply concentration centers on China for tungsten carbide powder synthesis, Germany for coated-grade finishing, and Japan for cermet formulation expertise. Raw material dependencies draw from tungsten concentrate, cobalt binder, and titanium carbonitride ceramic precursors. Single-source vulnerability pervades PVD coating equipment, where arc-evaporation and sputtering expertise concentrates at European and Japanese equipment houses. Distribution runs through direct manufacturer relationships with automotive and aerospace OEMs, bypassing tier-two distributors struggling with legacy ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive tungsten carbide powder production and in-house coating lines determine competitive survival. Players pursue upstream control over concentrate supply and downstream tool-as-a-service deployment as the decisive levers.
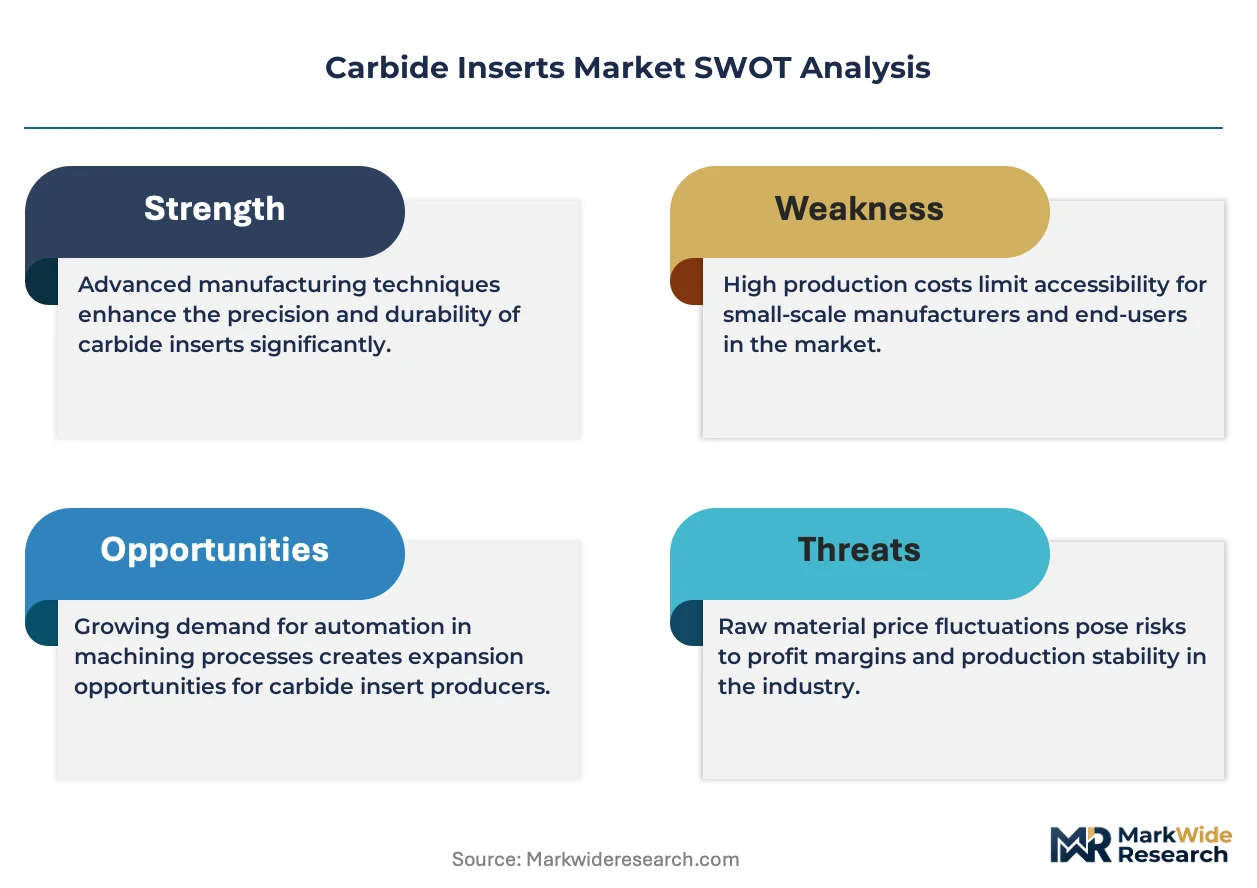
For Market Incumbents: Anticipate cobalt substitution physics limiting immediate grade-for-grade replacement by accelerating low-binder formulation R&D ahead of REACH compliance deadlines. Secure captive powder production capacity in Hunan and Jiangxi provinces before MEE discharge enforcement consolidates supply into state-controlled industrial parks. Defend aerospace qualification status by maintaining twelve-to-eighteen-month validation protocols that freeze supplier switches. For New Entrants and Emerging Players: REACH in Europe opens a window for low-cobalt formulation specialists to penetrate qualified supplier lists before ECHA disclosure requirements fully mature. Target India's precision machining cluster around Pune and Chennai, where automotive component suppliers expand multi-axis turning capacity requiring ISO-certified insert supply. Pursue coating service partnerships with established PVD equipment houses rather than capital-intensive captive line investment. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated powder-to-insert manufacturers seeking regional substrate specialists with application engineering depth. Long-term viability favors entities with backward integration into tungsten carbide powder synthesis and direct mill relationships across regulated end-use sectors. Watch PVD coating technician scarcity as the inflection indicator for capacity expansion constraints and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive tungsten carbide production secures concentrate supply against Chinese state reserve volatility. |
| Low-Cobalt Formulation R&D | REACH compliance through ECHA mandates binder substitution ahead of competitor requalification timelines. |
| Tool-as-a-Service Deployment | Per-part pricing agreements with Stuttgart automotive stampers compress distributor margins while locking OEM relationships. |
| PVD Coating Capacity Expansion | High-power pulsed magnetron sputtering lines capture aerospace qualification windows before they close. |
| India Distribution Partnership | Pune and Chennai precision machining clusters drive standard-grade consumption for transmission shaft production. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with powder metallurgy plant managers, aerospace procurement leads, PVD coating technicians, automotive Tier 1 supplier engineers, and carbide insert distributors combined with secondary validation from SEC filings, ECHA substance registrations, MEE discharge records, and ISO certification databases. Bottom-up grade-level volume estimates triangulated against top-down end-use consumption models.
Granularity-level modeling disaggregated projections across product type, coating chemistry, application discipline, and end-user procurement sophistication. CAGRs derived from segment-level growth drivers including titanium-alloy airframe expansion, REACH compliance transitions, and deep-hole energy equipment demand. Forecast inputs incorporated tungsten concentrate price volatility assumptions, aerospace OEM qualification timelines, and MEE enforcement intensity scenarios across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for high-power pulsed magnetron sputtering would alter the outlook if arc-evaporation retains dominance. Forecasts reflect assumptions around cobalt substitution physics, REACH disclosure timelines, and Chinese environmental enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Seals Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Paint Knife Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Metal Molds Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Briquetting Press Market