
 Tile Abrasion Testing Market | 2026-2036
Tile Abrasion Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Abrasion Testing Market Outlook
PEI Class 4 and Class 5 abrasion resistance specifications is redrawing competitive requirements across the tile abrasion testing landscape. Taber Industries leverages its rotary platform heritage to dominate standardized wear-index protocols in North American laboratories. Zwick Roell Group anchors European demand through precision servo-hydraulic systems aligned with EN ISO 10545-7. Haida International Equipment Co Ltd competes aggressively on cost-calibrated units serving mid-tier ceramic producers in East Asia.
Tile abrasion testing quantifies surface wear resistance under controlled abrasive load conditions, typically measuring mass loss or visual degradation after a defined cycle count using standardized abrasive media. The method serves ceramic, porcelain, and natural stone manufacturers seeking durability certification for commercial and high-traffic residential installations. Porcelain tile applications generate the strongest structural pull within the testing market, as PEI Class 5 ratings command premium positioning in airport, hospital, and retail flooring specifications. Composite tile segments represent an emerging growth vector where hybrid material formulations require adapted abrasive media and modified cycle protocols. Flooring end-use channels sustain the dominant share of installed testing capacity, though wall cladding applications are expanding as large-format porcelain slabs penetrate vertical surfaces in commercial architecture.
ISO 10545-7, ASTM C1027, and EN 154 define the tripartite regulatory foundation governing test methodology, abrasive calibration, and result reporting across major ceramic export jurisdictions. FDA oversight of silica exposure in abrasive compound manufacturing indirectly shapes consumables sourcing for laboratories running high-frequency tile abrasion programs. Stakeholders must monitor evolving PEI classification harmonization between European and Chinese national standards, as divergence in test-cycle equivalence would fragment equipment compatibility and recalibration service demand.
Market Dynamics
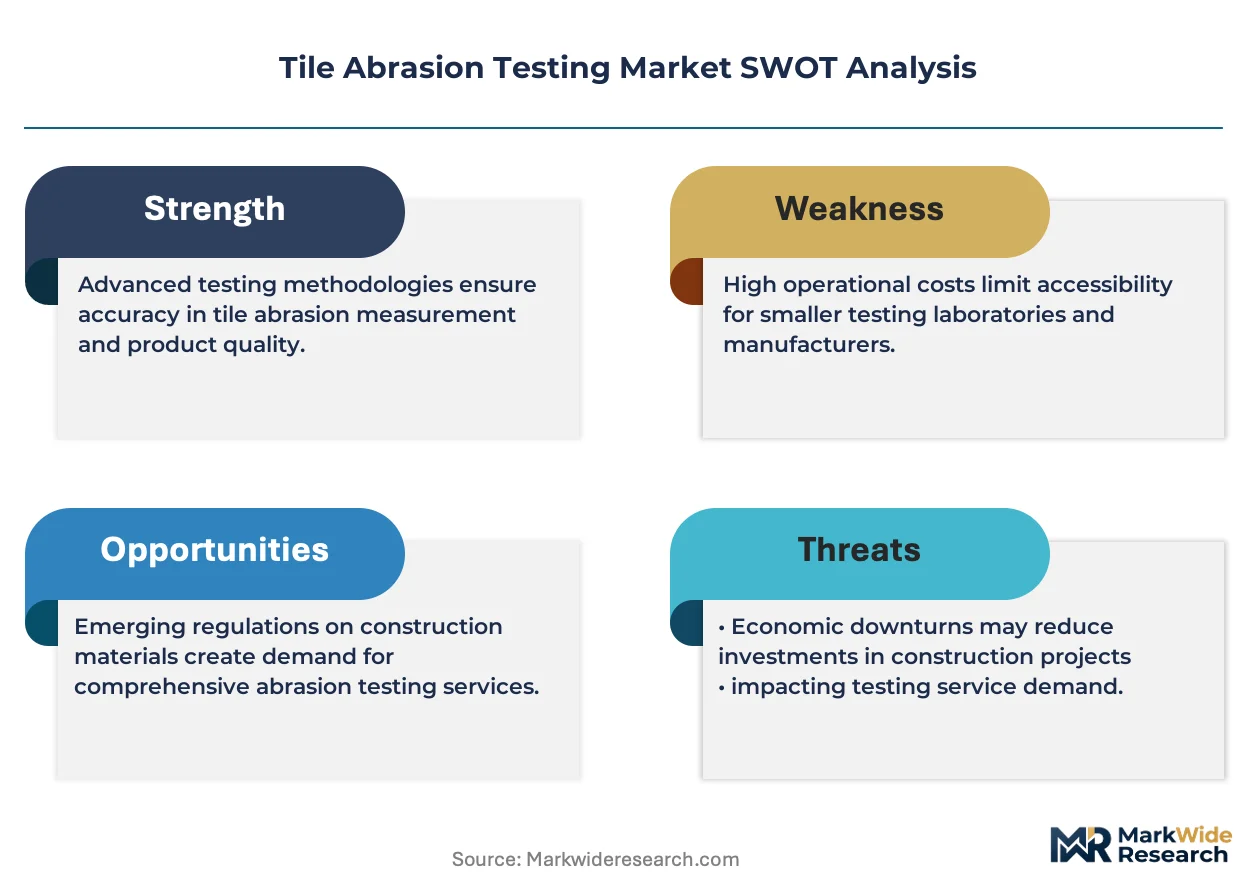
PEI rating harmonization between European and Chinese ceramic standards is compressing equipment calibration cycles and forcing laboratories into dual-protocol compliance investments.
Growth Catalysts
- ISO 10545-7 alignment:Export certification requirements from China's tile manufacturing clusters are driving continuous testing volume for abrasion resistance validation.
- Commercial flooring infrastructure:Large-scale construction contractors across Asia-Pacific are expanding certified testing capacity to meet hospital and airport PEI Class 5 specifications.
- Silica exposure protocols:FDA oversight of abrasive compound manufacturing is indirectly shaping consumables sourcing for high-frequency testing programs.
Market Restraints
- Abrasive media cost volatility:Specialized corundum and silicon carbide grit prices fluctuate with mining supply disruptions from South African and Chinese suppliers.
- Equipment supply concentration:Precision servo-hydraulic system production clusters in Germany and Japan create extended lead times for recalibration services.
- Test-cycle equivalence gaps:Divergence between EN 154 and Chinese national standards fragments equipment compatibility across export jurisdictions.
Strategic Opportunities
- Composite tile formulations:Hybrid material testing requires adapted abrasive media and modified cycle protocols, opening service expansion for specialized laboratories.
- Vertical surface applications:Large-format porcelain slabs penetrating commercial wall cladding create new testing demand outside traditional flooring channels.
- EU Green Deal procurement:Public infrastructure tenders with embedded durability certification mandates are pulling PEI Class 4 and 5 testing into municipal specification workflows.
Industry Challenges
- Metrology technician scarcity:Laboratories struggle to recruit operators proficient in both EN ISO 10545-7 and ASTM C1027 protocol execution.
- Dual-standard recalibration:Equipment serving both European and Chinese export markets requires parallel certification maintenance, doubling compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Abrasion Testing Market |
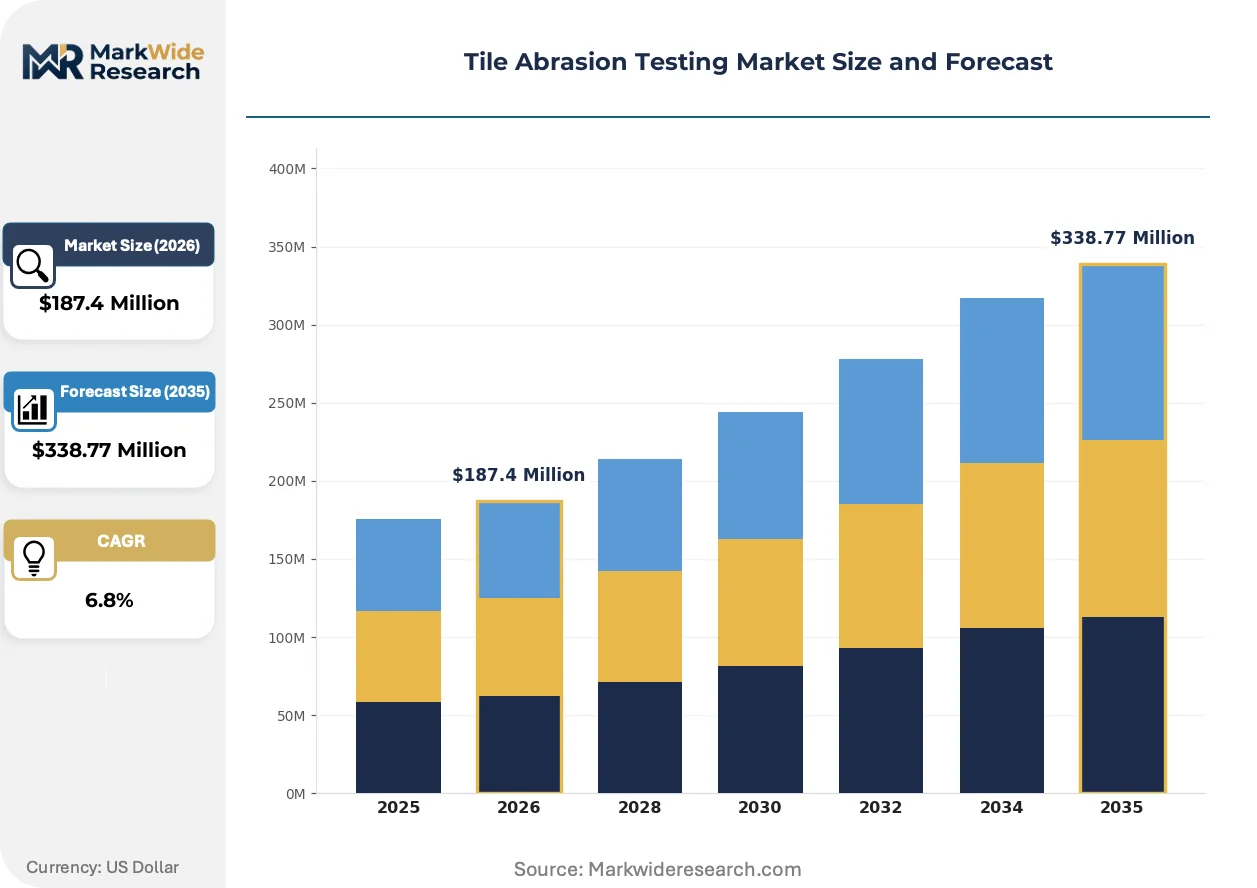
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tiles, Porcelain Tiles, Natural Stone Tiles, Composite Tiles Application: Flooring, Wall Cladding, Countertops, Decorative Surfaces End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Taber Industries, Haida International Equipment Co Ltd, Testing Machines Inc, Presto Group, Zwick Roell Group, Matest SpA, Cooper Research Technology Ltd, Hegewald & Peschke Meß- und Prüftechnik GmbH, Aimil Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Abrasion Testing Market Strategic Shifts
Digital image correlation systems are replacing manual visual assessment in abrasion testing workflows, compressing result subjectivity and enabling automated PEI classification.
Automated rotary platform systems with integrated mass-loss sensors are displacing manual Taber-type configurations in high-throughput ceramic laboratories. North American flooring certification bodies are adopting these platforms to reduce operator-dependent variation in wear-index reporting. The shift is compressing turnaround times for PEI Class 4 and 5 validation from days to hours.
REACH restrictions on crystalline silica in abrasive media are forcing consumables reformulation across European testing facilities. Manufacturers are shifting toward engineered ceramic grit alternatives that maintain EN 154 calibration standards while eliminating respiratory exposure liabilities. German and Italian laboratories are absorbing the highest compliance costs during this transition.
Certification-driven procurement is consolidating buyer power among tier-one construction contractors who mandate pre-qualification testing from accredited laboratories. Mid-tier ceramic producers are losing direct access to project specifications as general contractors bundle testing into master service agreements. This channel compression is most visible in China's export-oriented manufacturing clusters serving Middle East and African infrastructure projects.
Tile Abrasion Testing Market Segmentation
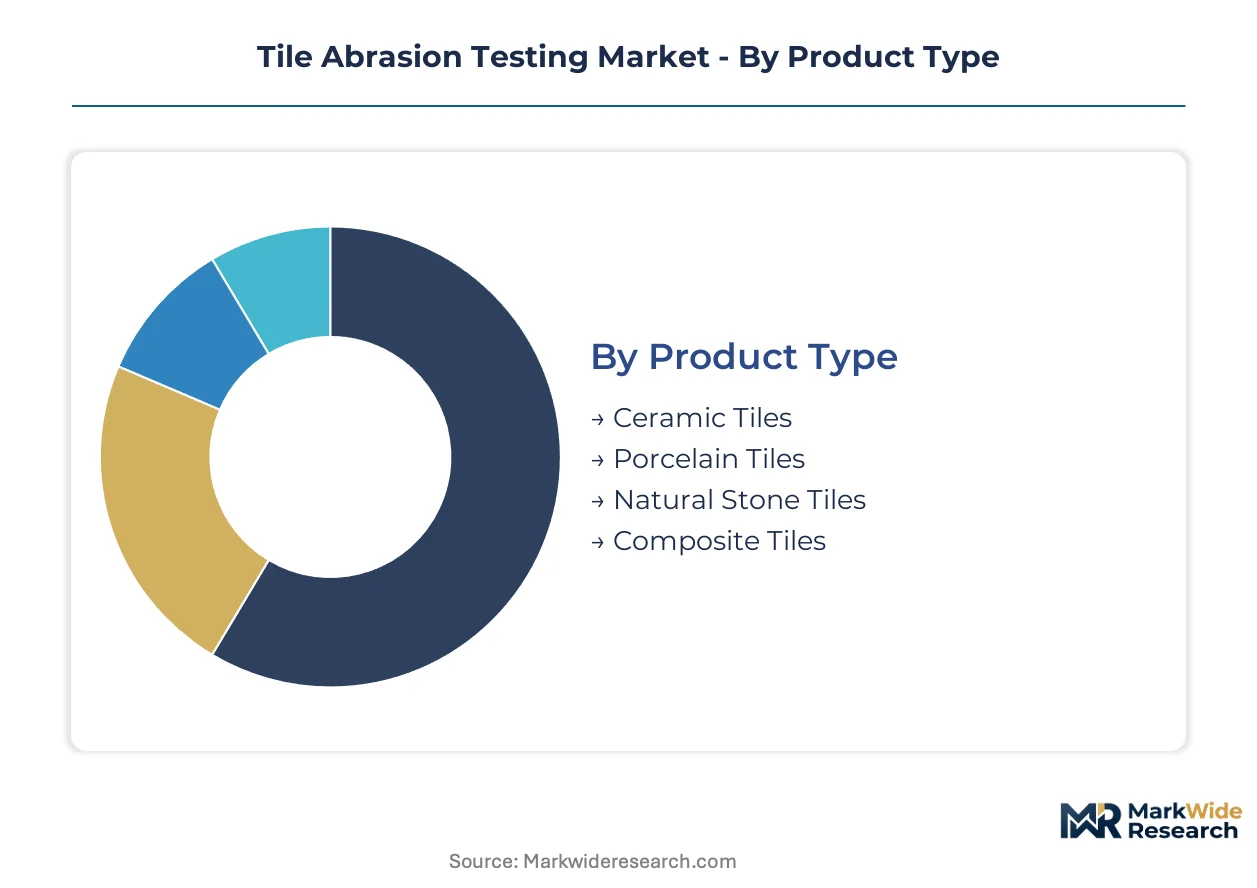
Tile abrasion testing demand fragments across material specifications, installation geometries, and procurement channels. Each segment carries distinct PEI rating requirements, equipment calibration protocols, and buyer power concentrations that reshape competitive positioning.
Product Type:
Porcelain tiles face the most intense substitute pressure from engineered ceramic composites, forcing manufacturers to defend PEI Class 5 certification premiums through accelerated testing programs.
- Porcelain Tiles:Dense vitrified bodies with water absorption below 0.5% require the most rigorous abrasion validation. Airport and hospital flooring specifications in Germany and the UAE concentrate demand for certified PEI Class 5 systems, with contractors bundling testing into master service agreements.
- Ceramic Tiles:Porous earthenware and stoneware compositions dominate residential applications. China's export manufacturing clusters around Foshan and Zibo sustain continuous testing volume for ISO 10545-7 compliance, though mid-tier producers are losing direct specification access to general contractor consolidation.
- Natural Stone Tiles:Granite, marble, and travertine surfaces use modified ASTM C503 protocols adapted from ceramic standards.
- Composite Tiles:Hybrid polymer-ceramic formulations require proprietary abrasive media and cycle adaptations not yet harmonized across EN 154 and Chinese national standards.
Porcelain tiles retain volume leadership; composite tiles hold the steepest expansion curve.
Application:
Cost tier differentiation separates specification-grade commercial installations from commodity residential projects, with testing fees scaling directly against PEI rating stringency.
- Flooring:Horizontal surfaces bear direct abrasive loads from foot traffic, furniture movement, and particulate grinding. Retail, healthcare, and transportation infrastructure in Saudi Arabia and Singapore drive premium testing demand for PEI Class 4 and 5 validation.
- Wall Cladding:Large-format porcelain slabs on vertical surfaces use modified protocols measuring edge chipping and surface dulling rather than mass loss. Commercial architecture in Milan and Dubai is expanding testing capacity outside traditional flooring channels.
- Countertops:Kitchen and laboratory surfaces require combined abrasion and chemical resistance testing under EN ISO 10545-13.
- Decorative Surfaces:Low-traffic ornamental installations often bypass formal PEI certification, relying on supplier declarations.
Flooring applications command the dominant share of installed testing capacity; wall cladding is gaining share fastest.
End User:
Customer type concentration among tier-one construction contractors is compressing mid-tier ceramic producers into indirect procurement channels.
- Commercial:Office complexes, retail centers, and hospitality projects mandate pre-qualification testing from accredited laboratories. General contractors in the UK and Australia are consolidating testing into bundled master agreements, excluding smaller manufacturers from direct bidding.
- Institutional:Government and healthcare procurement with embedded durability mandates under the EU Green Deal is pulling PEI Class 4 and 5 testing into municipal specification workflows across France and Spain.
- Residential:Single-family and multi-family housing relies on builder-grade certifications with lower testing frequency.
- Industrial:Manufacturing floors and warehouses require specialized heavy-load abrasion protocols beyond standard PEI classifications.
Commercial end users retain volume leadership; institutional buyers are climbing the fastest.
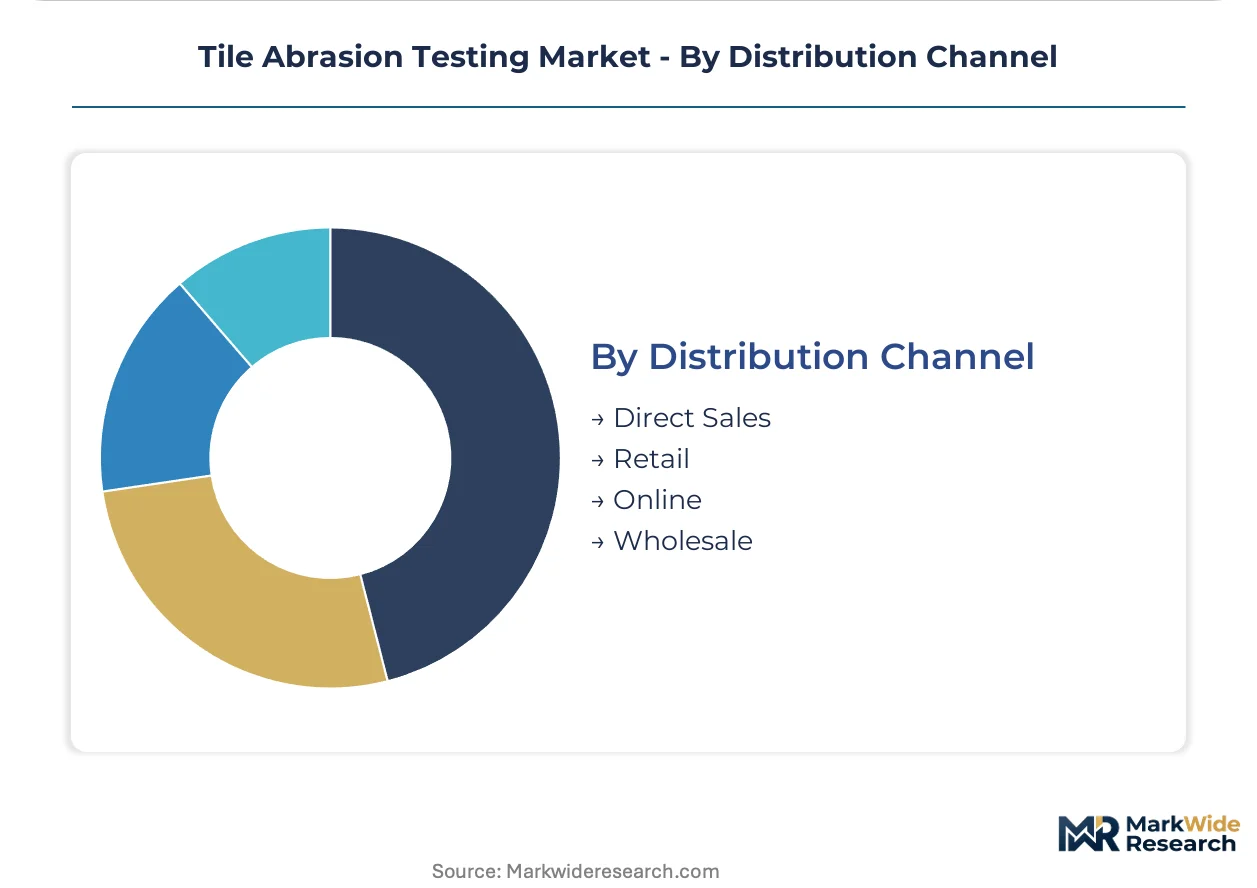
Distribution Channel:
Supply concentration in precision servo-hydraulic system production clusters is extending lead times for recalibration services, favoring direct manufacturer relationships over intermediaries.
- Direct Sales:Equipment manufacturers like Taber Industries and Zwick Roell Group sell calibrated systems directly to large ceramic producers and third-party laboratories. German and Japanese production clusters serve this channel with extended order backlogs.
- Wholesale:Distributors aggregate consumables and spare parts for high-throughput testing facilities. REACH compliance costs for silica-free abrasive media are compressing margins across European wholesale networks.
- Retail:Limited to small-scale portable abrasion testers for on-site quality verification.
- Online:Emerging channel for replacement abrasive wheels and calibration standards, though precision equipment remains relationship-driven.
Direct sales retain volume leadership; wholesale channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision equipment manufacturing clusters in Germany and Japan dominate supply-side output, while demand concentrates in ceramic production centers across China, Italy, and the UAE. Testing protocol divergence between EN 154 and Chinese national standards fragments equipment compatibility across export jurisdictions.
Germany
Precision servo-hydraulic system production around Stuttgart and Munich anchors European supply capacity. ECHA REACH restrictions on crystalline silica in abrasive media are forcing consumables reformulation across testing facilities. The Zwick Roell Group's Baden-Württemberg operations serve laboratories requiring EN ISO 10545-7 calibration.
China
Foshan and Zibo manufacturing clusters sustain continuous testing volume for ISO 10545-7 export compliance. SAMR oversight of GB standard harmonization with PEI classifications is compressing equipment recalibration cycles. Mid-tier ceramic producers in Guangdong province are losing direct specification access to general contractor consolidation.
United States
North American flooring certification bodies in Ohio and Illinois are adopting automated rotary platforms to reduce operator-dependent variation. FDA oversight of silica exposure in abrasive compound manufacturing shapes consumables sourcing for high-frequency programs. Taber Industries' New York operations dominate standardized wear-index protocols in regional laboratories.
Italy
Sassuolo ceramic district laboratories absorb the highest REACH compliance costs during silica-free abrasive media transitions. EU Green Deal procurement mandates are pulling PEI Class 4 and 5 testing into municipal specification workflows across Emilia-Romagna. Matest SpA's Bologna operations exemplify precision equipment serving Mediterranean export markets.
United Arab Emirates
Dubai and Abu Dhabi infrastructure specifications for airport and hospital flooring drive premium demand for PEI Class 5 validation. MOHAP building material safety frameworks reference EN 154 protocols for imported ceramic certification. General contractors in the Gulf Cooperation Council are consolidating testing into bundled master service agreements.
Tile Abrasion Testing Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the tile abrasion testing landscape. German and Japanese precision equipment manufacturers anchor premium-tier positioning through servo-hydraulic calibration systems, while Chinese fabricators compete on cost-calibrated units for mid-tier ceramic producers. The market structure fragments across three strategic archetypes: precision instrument specialists, volume-oriented equipment fabricators, and integrated testing service providers. Dominant competitive moves include backward integration into abrasive media production and geographic expansion through certification body partnerships.
Among precision instrument specialists, Taber Industries represents the rotary platform heritage archetype in North American laboratories, while Zwick Roell Group occupies a position exemplifying European precision engineering alignment with EN standards. Haida International Equipment Co Ltd sits within the cost-calibrated fabricator tier serving East Asian mid-market demand. These three anchors illustrate how technology specialization, regional regulatory alignment, and manufacturing cost structure differentiate competitive positioning across the testing equipment value chain.
| Leading Market Players |
|---|
| Taber Industries |
| Haida International Equipment Co Ltd |
| Testing Machines Inc |
| Presto Group |
| Zwick Roell Group |
| Matest SpA |
| Cooper Research Technology Ltd |
| Hegewald & Peschke Meß- und Prüftechnik GmbH |
| Aimil Ltd |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese servo-hydraulic system plants shapes both supply concentration and price floors for precision testing equipment, with backlogs extending calibration service premiums while Chinese fabricators exploit idle capacity to undercut mid-tier pricing.
Pricing Analysis
PEI rating harmonization between EN 154 and Chinese GB standards dictates the pricing tier structure across the tile abrasion testing landscape. Equipment serving dual-protocol compliance commands premium positioning against single-standard units, with certification-grade precision systems separating from cost-calibrated alternatives. Cost compression in consumables is intensifying because REACH-mandated silica-free abrasive reformulation is absorbing margin across European laboratories. Mid-tier ceramic producers in China's export clusters exhibit the highest price sensitivity, while Gulf Cooperation Council general contractors bundling testing into master service agreements show the lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for precision equipment components sourced from Stuttgart and Munich production clusters. Manufacturing concentration in Germany, Japan, and China creates geographic supply fragmentation, with servo-hydraulic systems drawing from Baden-Württemberg engineering networks and cost-calibrated units feeding from Guangdong fabrication centers. Single-source vulnerability sits with corundum and silicon carbide grit suppliers in South Africa and China, where mining disruptions propagate raw material volatility. Distribution runs through direct manufacturer relationships for precision systems and wholesale networks for consumables and spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital image correlation displacement of manual visual assessment represents a technological inflection compressing result turnaround from days to hours, positioning laboratories investing in automation to capture certification volume from contractors facing compressed project timelines.
For Market Incumbents: Compound technology leadership in automated rotary platforms with integrated mass-loss sensors to defend against emerging Chinese competitors offering cost-calibrated alternatives. Backward integration into engineered ceramic grit production reduces REACH compliance cost exposure while securing consumables margin. Priority capacity addition in the UAE addresses Gulf Cooperation Council infrastructure demand for PEI Class 5 validation.
For New Entrants and Emerging Players: Differentiate on composite tile testing protocols requiring proprietary abrasive media adaptations not yet harmonized across EN 154 and Chinese national standards. White-space concentration in wall cladding applications for large-format porcelain slabs offers the most penetrable expansion vector outside saturated flooring channels. Go-to-market through certification body partnerships in Milan and Dubai accelerates specification access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated testing service providers bundling equipment, consumables, and calibration maintenance into multi-year laboratory contracts. Long-term viability over a five-to-ten-year window favors precision instrument specialists with captive abrasive media supply and dual-standard certification capabilities. The signal to watch is SAMR acceleration of GB standard harmonization with PEI classifications, which would compress equipment recalibration cycles and expand service attach rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Media | REACH silica restrictions force reformulation; captive supply eliminates third-party margin and exposure. |
| Dual-Standard Certification Investment | EN 154 and GB harmonization compresses recalibration cycles, favoring laboratories with parallel protocol capability. |
| Digital Image Correlation Deployment | Automated PEI classification reduces operator-dependent variation and compresses turnaround times for contractors. |
| Geographic Expansion through Certification Partnerships | EU Green Deal procurement mandates in France and Spain pull testing into municipal workflows. |
| Composite Tile Protocol Development | Hybrid polymer-ceramic formulations require adapted media and cycles not yet standardized across jurisdictions. |
Study Parameters
A spread of perspectives from ceramic manufacturing plant managers, third-party laboratory technical directors, general contractor procurement leads, and precision equipment R&D heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against ISO 10545-7 calibration records, ECHA REACH compliance filings, SAMR GB standard harmonization notices, and customs data tracking abrasive media trade flows. Bottom-up equipment shipment analysis and top-down construction spending attribution were triangulated to anchor volume estimates.
Segmentation dimensions modeled include material specification (porcelain, ceramic, natural stone, composite), installation geometry (flooring, wall cladding, countertops), end-user procurement channel (direct sales, wholesale, bundled master agreements), and regional regulatory cluster (EN 154, ASTM C1027, GB standards). CAGRs were derived from equipment replacement cycles, construction infrastructure pipelines, and export certification velocity across the projection horizon. Industry-specific forecast inputs incorporated PEI rating adoption curves and silica-free abrasive media transition timelines.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment in Asia-Pacific, REACH enforcement continuity, or PEI-GB harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding equipment replacement elasticity and contractor bundling behavior. Abrasive supply disruptions, regulatory divergence, or metrology technician scarcity represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Abrasive Tools Market
Abrasives
Carborundum Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
RDP Powder Market
Abrasives
Chemical Deflasher Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Calcined Shale Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
North America Abrasives Market
Abrasives
Synthetic Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Abrasive Rolls Market
Abrasives
Global Ceramic Flap Disc Market
Abrasives
Abrasive Grains Market