
 Tungsten Carbide Band Saw Blade Market | 2026-2036
Tungsten Carbide Band Saw Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Carbide Band Saw Blade Market Analytics
The EU Green Deal is restructuring purchasing criteria across European metalworking sectors, with tier-one suppliers now mandating documented tool life and recyclability metrics in procurement contracts. LENOX leverages its captive powder-metallurgy capabilities to guarantee batch consistency for aerospace-certified blades. WIKUS sustains dominance in continental distribution through direct technical service teams embedded in Germany's Ruhr industrial basin. Starrett anchors its European position with calibration-grade dimensional tolerances that meet DIN 50150 testing protocols for structural steel cutting.
Tungsten carbide band saw blades consist of a flexible alloy steel backing strip electron-beam welded to a tooth edge of sintered tungsten carbide-cobalt composite, typically graded at 6-10% cobalt binder content for fracture resistance during high-feed cutting of hardened steels and exotic alloys. Their primary purpose is to deliver extended cutting life and dimensional stability in continuous production environments where bi-metal blades fail prematurely. Customized blades command premium positioning because they match specific tooth geometries to customer material portfolios, while standard blades compete on availability and distributor stocking density. Metalworking applications absorb the majority of volume, with CNC-integrated sawing systems driving demand for blades with ground-set tooth patterns that minimize kerf loss in titanium aerospace bar stock.
Germany's KBA enforces machinery safety standards that mandate blade guarding and breakage detection on industrial sawing equipment, indirectly favoring suppliers with certified fatigue-test documentation. REACH compliance through ECHA restricts cobalt sourcing transparency requirements, compelling blade manufacturers to map smelter origins in their supply chains. OSHA and EPA regulations in the United States impose coolant mist exposure limits that push fabricators toward dry-cutting carbide geometries that eliminate chemical disposal burdens. Stakeholders must monitor evolving cobalt conflict-mineral tracing rules and assess whether powder-recycling investments can offset raw material price volatility without compromising tooth-edge hardness specifications.
Market Dynamics
The EU F-Gas Regulation and industrial decarbonization mandates are compressing replacement cycles for consumable tooling, forcing fabricators to prioritize wear-resistant carbide geometries that eliminate energy-intensive resharpening and reduce chemical coolant dependency in high-volume metalworking operations.
Growth Catalysts
- Aerospace bar stock demand:German and Italian machine shops serving Airbus and Leonardo supply chains are standardizing carbide-tipped blades for titanium and nickel-alloy cutting, driven by tight tolerances on structural airframe components.
- REACH cobalt traceability:ECHA-mandated smelter disclosure requirements are favoring manufacturers with vertically integrated powder-metallurgy capabilities, rewarding suppliers who control raw material provenance from mine to tooth edge.
- Medical device precision:Stuttgart-area fabricators cutting cobalt-chrome and stainless steel for orthopedic implants require ground-set tooth patterns that bi-metal blades cannot sustain, creating pull-through demand for custom carbide geometries.
Market Restraints
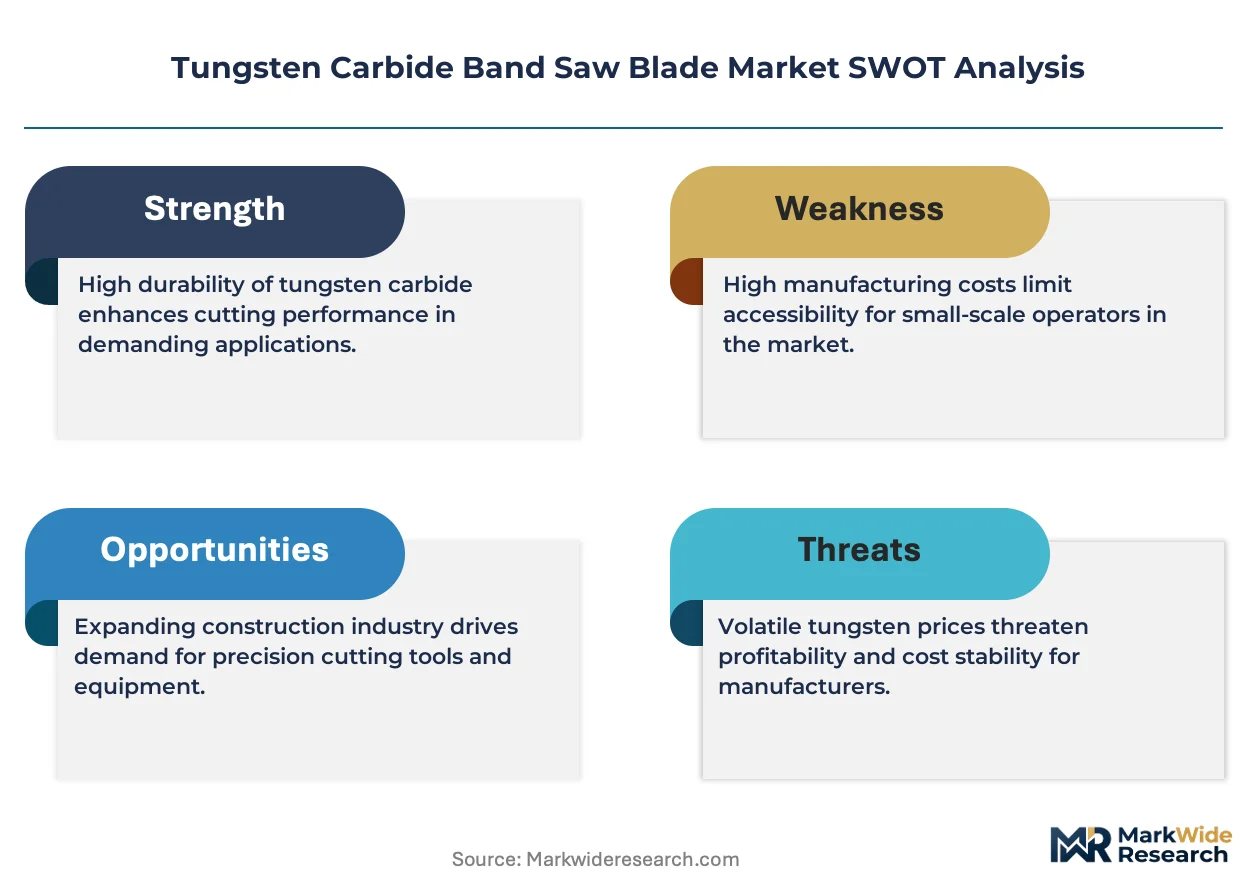
- Tungsten price volatility:Concentrated supply from Chinese state-owned mining operations exposes European blade manufacturers to input cost swings that compress margin buffers on standard-grade products.
- Electron-beam welding capacity:The specialized joining equipment required to fuse carbide edges to flexible steel backings is concentrated among a handful of German and Austrian equipment suppliers, creating bottleneck risk for capacity expansion.
- Bi-metal substitution in mild steel:Low-alloy structural applications in construction and general fabrication continue to default to cheaper bi-metal alternatives, capping carbide penetration in price-sensitive volume segments.
Strategic Opportunities
- Dry-cutting geometries:OSHA coolant mist exposure limits in US fabrication shops are creating openings for carbide tooth designs engineered to cut hardened steels without chemical flood coolants, eliminating disposal liability.
- Powder recycling integration:Captive reclamation of cobalt-tungsten grinding swarf offers margin recovery potential for manufacturers willing to invest in in-house thermal processing to offset raw material price spikes.
- CNC-integrated blade monitoring:Sensor-embedded carbide bands that feed real-time wear data to machine control systems are enabling predictive replacement scheduling in Japanese and South Korean smart-factory deployments.
Industry Challenges
- Electron-beam welder technician scarcity:The precision welding discipline required for carbide-to-steel fusion lacks formal training pipelines, forcing manufacturers to internalize multi-year apprenticeship investments.
- Aerospace certification timelines:DIN 50150 and NADCAP fatigue-test documentation requirements extend new product qualification cycles, delaying revenue recognition on customized blade geometries.
- Legacy saw system integration:Retrofitting carbide-optimized tooth geometries onto existing band saw frames designed for bi-metal blades requires spindle speed and feed rate recalibration that many job shops defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Carbide Band Saw Blade Market |
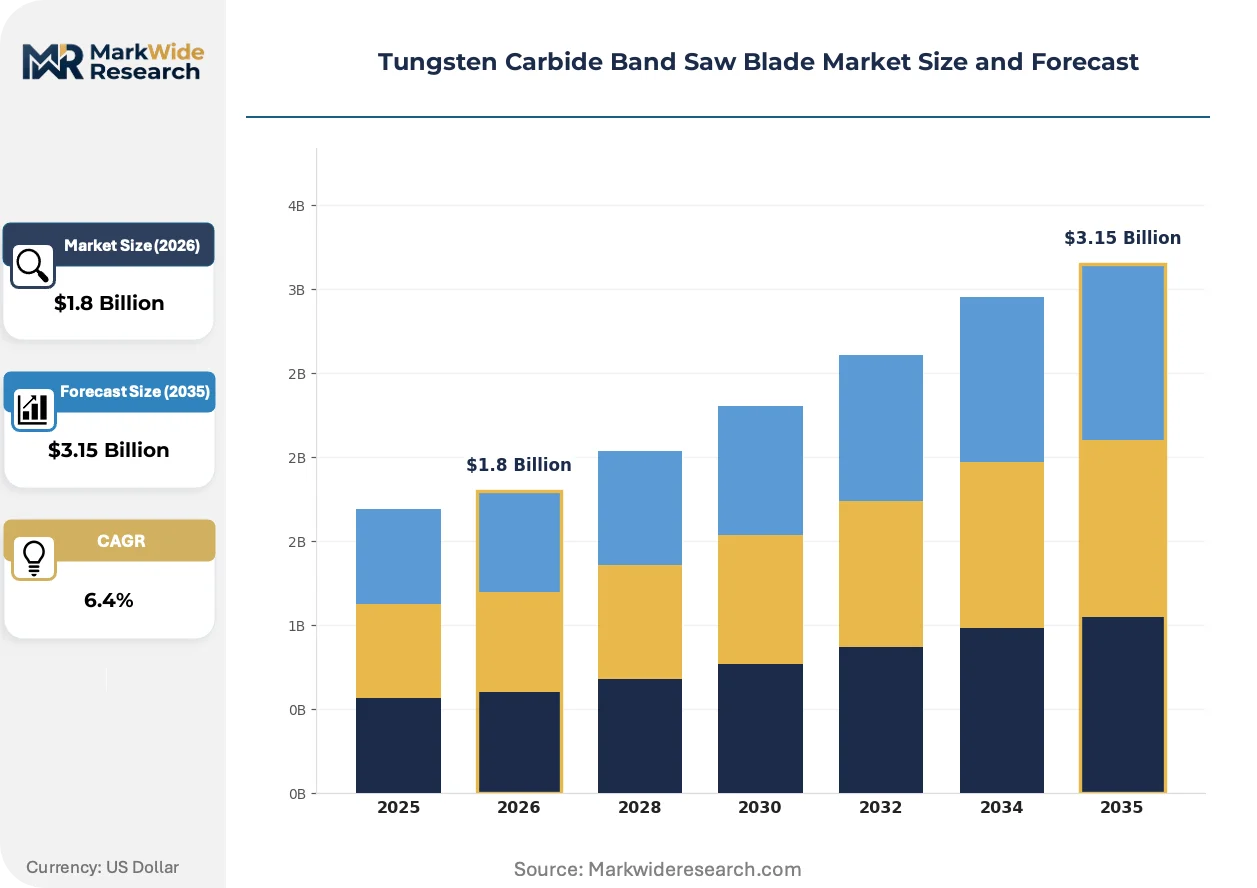
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blades, Customized Blades, Specialty Blades, Bi-Metal Blades Application: Woodworking, Metalworking, Construction, Manufacturing End User: Construction Firms, Manufacturing Plants, Woodworking Shops, Metal Fabricators Technology: Sawing Technology, CNC Technology, Laser Cutting, Conventional Cutting |
| Companies Covered | LENOX, Starrett, AMADA, WIKUS, BAHCO, DOALL, M. K. Morse, Bichamp Cutting Technology, Benxi Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Carbide Band Saw Blade Market Evolving Landscape
Machine-vision tooth inspection and automated grinding compensation are compressing quality variance in carbide edge preparation, while regulatory pressure on consumable waste streams accelerates adoption of predictive wear monitoring across European and North American metalworking clusters.
Ground-set tooth grinding with in-process laser measurement is automating the final geometry calibration that previously required manual bench inspection. Aerospace-tier suppliers in Germany and Japan are adopting these cells to hit ±0.02mm kerf consistency on titanium bar stock. The technology is automating the elimination of human variance from high-value blade finishing, compressing defect rates and qualification documentation burdens.
The EU Green Deal's embedded carbon accounting requirements are mandating documented tool life metrics in tier-one supplier contracts. Fabricators must now certify cutting hours per blade and end-of-life recyclability to maintain automotive and medical device supply chain eligibility. German precision engineering corridors are responding fastest, with Stuttgart and Solingen machine shops demanding batch-traceable fatigue-test data from carbide suppliers.
Buyer consolidation among contract metal service centers is compressing vendor counts and unbundling after-sales technical service from blade pricing. Large German distributors now specify direct field engineering support as a contract condition, displacing traditional stocking-distributor relationships. The Ruhr industrial basin exhibits this pattern most acutely, with integrated steel processors consolidating procurement around suppliers maintaining embedded technical teams.
Tungsten Carbide Band Saw Blade Market Segmentation
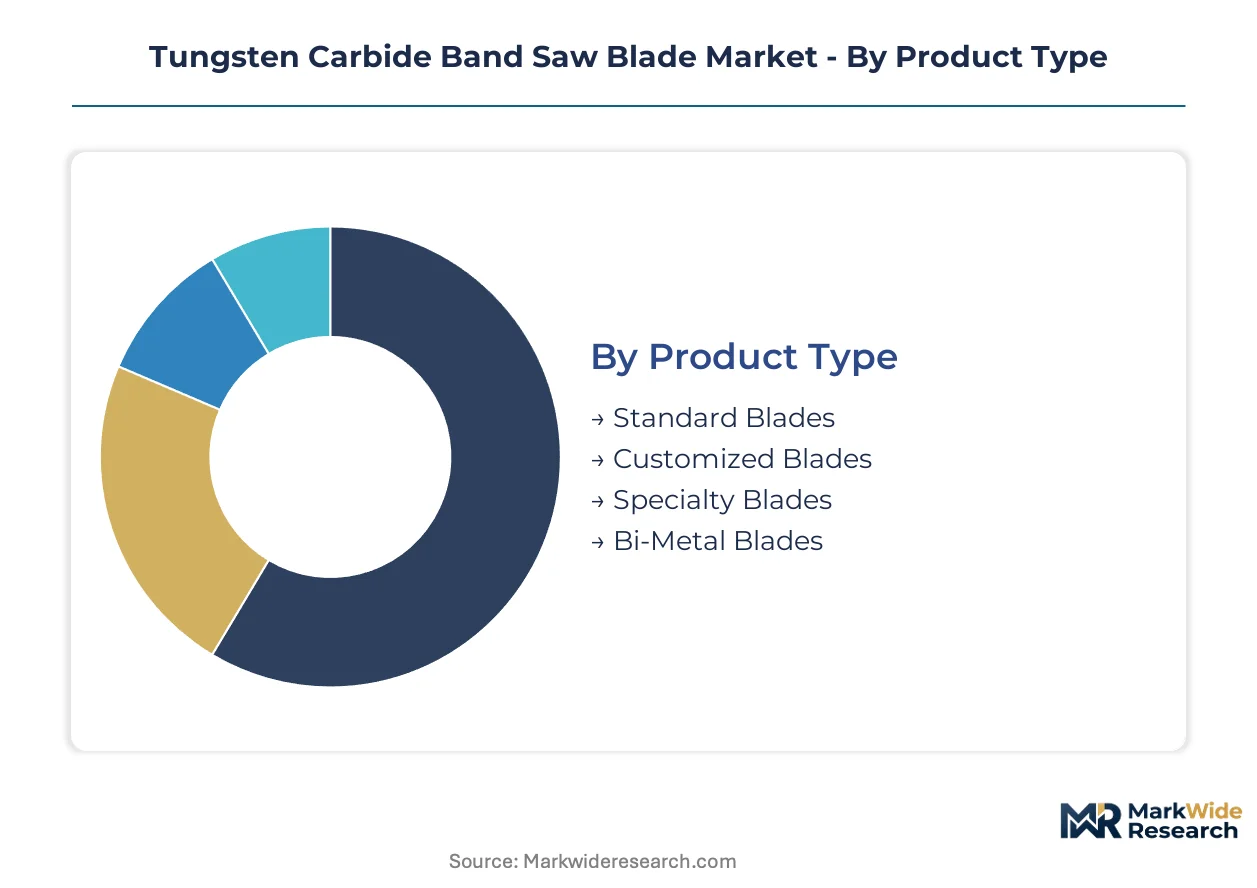
Segmentation in the tungsten carbide band saw blade market reveals how cutting geometries, integration depth, and end-use precision requirements fragment commercial opportunity. Understanding these divisions exposes where captive powder-metallurgy capabilities command premium positioning versus commoditized volume plays.
Product Type:
Standalone blades for general fabrication contrast with embedded system geometries engineered for CNC-integrated production lines.
- Standard Blades:Off-the-shelf tooth configurations with fixed pitch and set patterns serve job shops running mixed material portfolios. German distributors in the Ruhr industrial basin stock these for construction and general metal fabrication where setup flexibility outweighs cutting optimization.
- Customized Blades:Application-specific tooth geometries ground to match customer material specifications dominate aerospace bar stock cutting in Stuttgart and Solingen. DIN 50150 fatigue-test documentation and batch-traceable cobalt provenance separate qualified suppliers from catalog competitors.
- Specialty Blades:Extreme-duty geometries for nickel-alloy and hardened steel applications.
- Bi-Metal Blades:Lower-cost alternatives capping carbide penetration in mild steel construction cutting.
Volume placements concentrate in Standard Blades; the faster expansion belongs to Customized Blades.
Application:
Cost tiers separate high-wear exotic alloy cutting from price-sensitive bulk material processing.
- Metalworking:CNC-integrated sawing systems in German precision engineering corridors absorb the majority of carbide blade value. Ground-set tooth patterns minimize kerf loss in titanium aerospace bar stock while REACH-mandated cobalt traceability favors vertically integrated suppliers.
- Manufacturing:Continuous production environments for automotive and medical device components require documented tool life metrics under EU Green Deal procurement rules. Stuttgart-area fabricators cutting cobalt-chrome for orthopedic implants pull through demand for fatigue-tested geometries.
- Woodworking:Carbide-tipped blades for hardwood and composite processing.
- Construction:Structural steel cutting defaulting to cheaper bi-metal alternatives.
Margin capture peaks in Metalworking; Manufacturing climbs fastest on regulatory compliance requirements.
End User:
Customer type determines whether procurement prioritizes distributor availability or embedded technical service.
- Metal Fabricators:Contract metal service centers consolidating vendor counts demand direct field engineering support as contract conditions. Large German processors specify real-time wear monitoring integration for predictive replacement scheduling.
- Manufacturing Plants:Tier-one automotive and medical device suppliers mandate documented recyclability metrics and end-of-life blade recovery programs. EU F-Gas Regulation compliance favors longer-lasting carbide geometries that reduce energy-intensive resharpening cycles.
- Construction Firms:Price-sensitive volume buyers defaulting to bi-metal substitution in low-alloy structural applications.
- Woodworking Shops:Smaller-scale operations with limited CNC integration.
Procurement consolidation concentrates in Metal Fabricators; Manufacturing Plants drive specification escalation fastest.
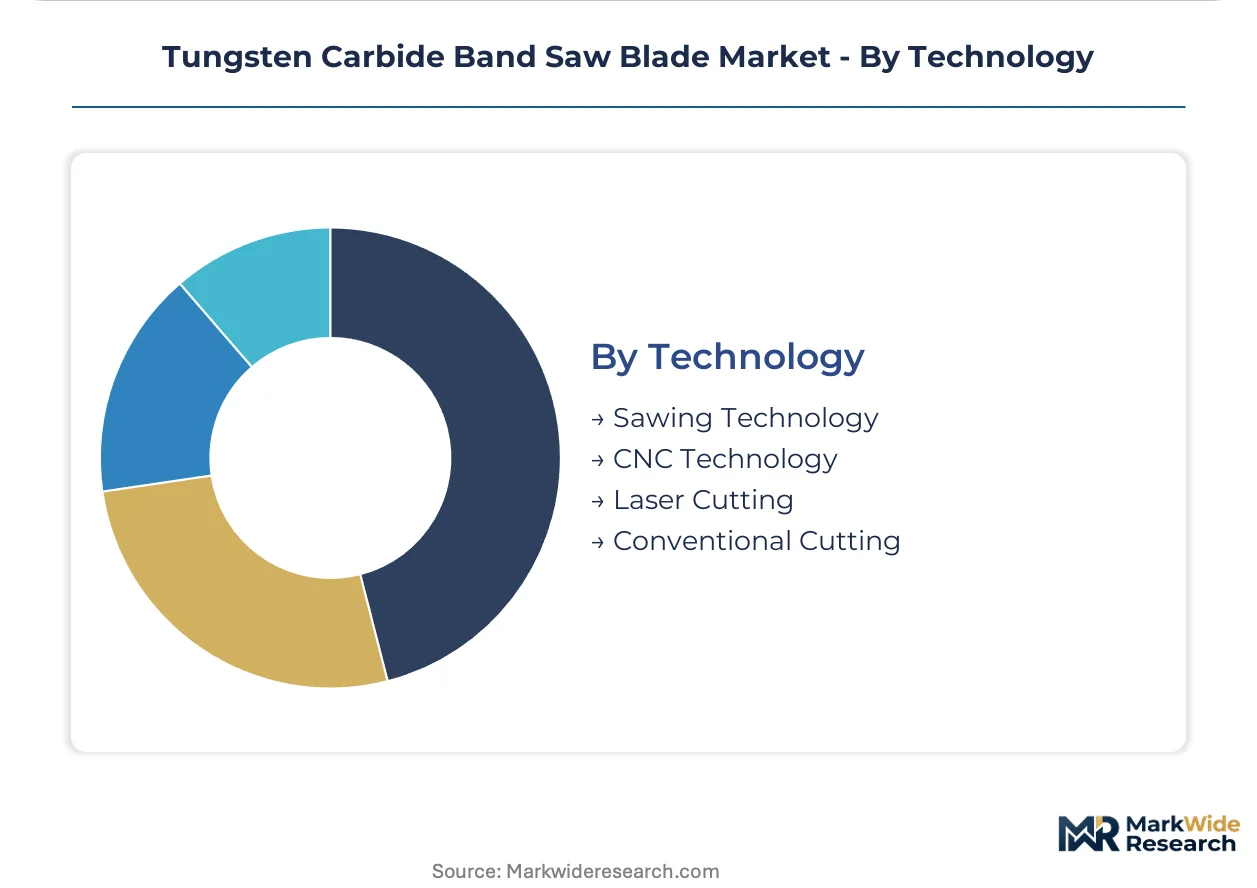
Technology:
Maturity curves separate established mechanical systems from sensor-embedded smart cutting platforms.
- CNC Technology:Computer-numerical control integration enables real-time feed rate optimization and automated blade tension adjustment. Japanese and South Korean smart-factory deployments are pioneering sensor-embedded carbide bands that transmit wear data directly to machine control systems.
- Sawing Technology:Conventional band saw mechanics with manual setup and operator-dependent optimization.
- Laser Cutting:Competing thermal process technology for thin-gauge material applications.
- Conventional Cutting:Legacy equipment requiring spindle speed and feed rate recalibration for carbide-optimized geometries.
Installed base concentrates in Sawing Technology; CNC Technology gains share fastest on predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the precision engineering corridor driving carbide blade specification escalation, with machine shops clustered across Baden-Württemberg setting EU procurement benchmarks for aerospace and medical device cutting operations.
Germany
Airbus supply chain demand for titanium bar stock cutting and KBA machinery safety standards mandating blade guarding documentation concentrate procurement authority in Stuttgart, Munich, and Solingen. The EU F-Gas Regulation pushes fabricators toward longer-lasting carbide geometries that eliminate energy-intensive resharpening cycles in continuous production environments.
United States
OSHA coolant mist exposure limits and EPA chemical disposal regulations drive dry-cutting carbide adoption in fabrication shops serving defense and energy infrastructure. The Pacific Northwest and Gulf Coast metal service centers consolidate vendor counts around suppliers offering predictive wear monitoring integration for CNC sawing systems.
Japan
METI smart-factory initiatives and automotive tier-one supplier consolidation accelerate sensor-embedded carbide blade deployment in Nagoya and Osaka industrial basins. Ground-set tooth grinding with in-process laser measurement automates quality calibration for titanium aerospace component cutting.
China
State-owned tungsten mining concentration and MIIT industrial upgrading policies shape raw material cost structures for domestic blade manufacturers. Yangtze River Delta fabricators serving export-oriented precision engineering demand REACH-compliant cobalt traceability documentation for European automotive supply chain access.
South Korea
MFDS medical device manufacturing standards and Hyundai-Kia automotive supply chain requirements pull through demand for fatigue-tested carbide geometries in Seoul Capital Area machine shops. CNC-integrated blade monitoring systems feed real-time wear data to predictive maintenance platforms in Busan-Ulsan heavy industrial zones.
Tungsten Carbide Band Saw Blade Market Competitive Landscape
The competitive structure tilts toward vertically integrated powder-metallurgy specialists with captive cobalt-tungsten supply chains. Tier-one aerospace and medical device procurement consolidation favors suppliers guaranteeing batch-traceable fatigue-test documentation under DIN 50150 protocols. Three archetypes dominate: German precision engineering houses with embedded Ruhr basin technical service teams, Japanese smart-factory technology integrators, and Chinese state-linked raw material processors. Dominant competitive moves include electron-beam welding capacity expansion and powder recycling integration to offset tungsten price volatility.
Among German-based manufacturers, LENOX and WIKUS exemplify the technical service-embedded archetype, with the former representing captive powder-metallurgy capabilities and the latter anchoring continental distribution through direct field engineering support. Starrett occupies a position as a calibration-grade dimensional tolerance specialist meeting structural steel testing protocols. These three illustrate how procurement consolidation among contract metal service centers compresses vendor counts around suppliers maintaining embedded technical teams rather than traditional stocking-distributor relationships.
| Leading Market Players |
|---|
| LENOX |
| Starrett |
| AMADA |
| WIKUS |
| BAHCO |
| DOALL |
| M. K. Morse |
| Bichamp Cutting Technology |
| Benxi Tool |
| Others |
Value Network & Pricing Analysis
Aerospace tier-one procurement consolidation across Airbus and Boeing supply chains anchors value-based pricing models that tie blade costs to certified cutting hours and fatigue-test documentation rather than unit transaction prices. This buyer concentration rewards suppliers with captive powder-metallurgy capabilities and batch-traceable cobalt provenance, compressing margin buffers on standard-grade catalog products while sustaining premiums for DIN 50150-qualified custom geometries.
Pricing Analysis
Cutting-hour guarantees and throughput-based contracts dominate aerospace and medical device procurement, with pricing stratifying across premium certified-grade, standard industrial-grade, and economy mild-steel tiers. Certification level under EU REACH cobalt traceability mandates and customization depth for ground-set tooth patterns drive price differentiation between qualified suppliers and catalog competitors. Cost compression in standard-grade segments intensifies because Chinese state-owned tungsten mining concentration exposes European manufacturers to input price volatility. Job shops running mixed material portfolios exhibit highest price sensitivity, while Stuttgart-area orthopedic implant fabricators prioritize fatigue-test documentation over unit cost.
Supply Chain Analysis
Freight cost escalation for electron-beam welding equipment shipments from German and Austrian suppliers compresses margin recovery timelines for blade manufacturers expanding capacity. Raw material sourcing draws from Chinese state-owned tungsten mining operations, Russian cobalt refining, and domestic European powder-metallurgy reclaim facilities. Single-source vulnerability concentrates in electron-beam welder technician scarcity, where multi-year apprenticeship investments bottleneck production scaling. Distribution runs through embedded technical service teams in Germany's Ruhr industrial basin rather than traditional stocking-distributor relationships, with large metal service centers consolidating procurement around field-engineering-capable suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tungsten carbide band saw blade market sits in a technology-transition phase as sensor-embedded smart-factory geometries displace conventional sawing technology in Japanese and South Korean CNC-integrated deployments.
For Market Incumbents: Lock in aerospace certification timelines by accelerating DIN 50150 fatigue-test documentation investments before tier-one procurement consolidation hardens vendor panels. Defend against bi-metal substitution in mild steel construction segments by embedding predictive wear monitoring as a bundled service offering. Prioritize electron-beam welding capacity expansion in Germany's precision engineering corridor to capture Airbus supply chain demand for titanium bar stock cutting. For New Entrants and Emerging Players: Enter via dry-cutting geometry specialization targeting US fabrication shops facing OSHA coolant mist exposure limits, where regulatory pressure eliminates chemical disposal burdens for incumbent suppliers. Target South Korean medical device manufacturing clusters where MFDS standards pull through demand for fatigue-tested carbide geometries with shorter qualification cycles than aerospace tiers. Deploy powder-recycling integration as a cost-structure differentiator against established players exposed to tungsten price volatility. For Investors and Strategic Acquirers: The window for entry favors vertically integrated powder-metallurgy specialists with captive cobalt-tungsten supply chains and established REACH compliance documentation. Long-term viability hinges on smart-factory technology integration capabilities as CNC-embedded sensor platforms become standard procurement requirements. Watch Japanese METI smart-factory initiative deployment rates as the inflection indicator for predictive maintenance platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Welding Capacity Expansion | Captures bottlenecked production capacity serving Airbus titanium cutting demand in Stuttgart. |
| Powder Recycling Integration | Offsets Chinese state-owned tungsten mining price volatility through captive reclaim processing. |
| Sensor-Embedded Blade Development | Aligns with METI smart-factory initiatives driving predictive maintenance in Nagoya industrial basins. |
| REACH Compliance Documentation Investment | Secures tier-one automotive and medical device procurement eligibility under EU Green Deal mandates. |
| Embedded Technical Service Team Deployment | Meets Ruhr basin metal service center consolidation demands for direct field engineering support. |
Research Methodology
Independent corroboration across plant engineers at German precision engineering corridors, procurement leads at Airbus tier-one suppliers, and aftermarket service heads at Ruhr basin metal service centers underwrites the qualitative findings in this study. Secondary validation drew from ECHA REACH filings, KBA machinery safety documentation, SEC 10-K disclosures by listed industrial tool manufacturers, and German customs trade data for tungsten carbide imports. Bottom-up demand modeling from CNC-integrated sawing system deployments triangulates against top-down market sizing from powder-metallurgy production capacity estimates.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type (standard, customized, specialty), application (metalworking, manufacturing, woodworking, construction), end user (metal fabricators, manufacturing plants, construction firms), and technology integration depth (CNC, conventional, laser competing processes). CAGRs derive from geometric progression modeling of installed base replacement cycles and new system penetration rates, with aerospace bar stock demand intensity and EU F-Gas Regulation compliance timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Chinese state-owned tungsten export restriction scenarios or accelerated electron-beam welding technician shortages. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Boron Carbide Market
Abrasives
Abrasive Base Paper Market
Abrasives
Abrasive Rolls Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Artificial Abrasives Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
New Zealand Abrasives Market
Abrasives
Global Abrasives Market
Abrasives
Sandblaster Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Tungsten Carbide Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Carborundum Market
Abrasives
Synthetic Abrasives Market
Abrasives
RDP Powder Market
Abrasives
Polishing Chemicals Market