

Abrasive Base Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasive Base Paper Market Insights
Maintenance and resurfacing subscription contracts for fleet operators and industrial contractors is hardening into a recurring revenue layer that paper suppliers must now support with predictable grit-grade availability and just-in-time replenishment logistics. Saint-Gobain leverages its European distribution network to anchor long-term service agreements with automotive refinishing chains. Klingspor competes through specialized product lines calibrated to regional abrasive standards across its core markets.
Abrasive base paper is a cellulose or synthetic substrate engineered with controlled porosity, tensile strength, and uniform thickness to carry abrasive mineral coatings for precision surface finishing; grammage typically ranges from 80 to 400 g/m² depending on the target application. Kraft paper dominates volume production for heavy-duty metal grinding and construction sanding due to its cost-efficient fiber structure and tear resistance. Glassine paper occupies premium positioning in automotive clear-coat finishing where ultra-smooth substrate surfaces prevent coating defects and extend abrasive belt life.
EPA emissions guidelines in the United States restrict volatile organic compound release from solvent-based coating lines, redirecting capital toward water-based and UV-cured technology platforms. ECHA REACH substance authorization in Europe limits specific resin binders and crosslinkers, compelling reformulation of coating recipes for paper-backed abrasives sold into German and French manufacturing bases. Stakeholders must monitor evolving chemical compliance thresholds while calibrating coating technology investments against end-user switching costs in fabrication and assembly operations.
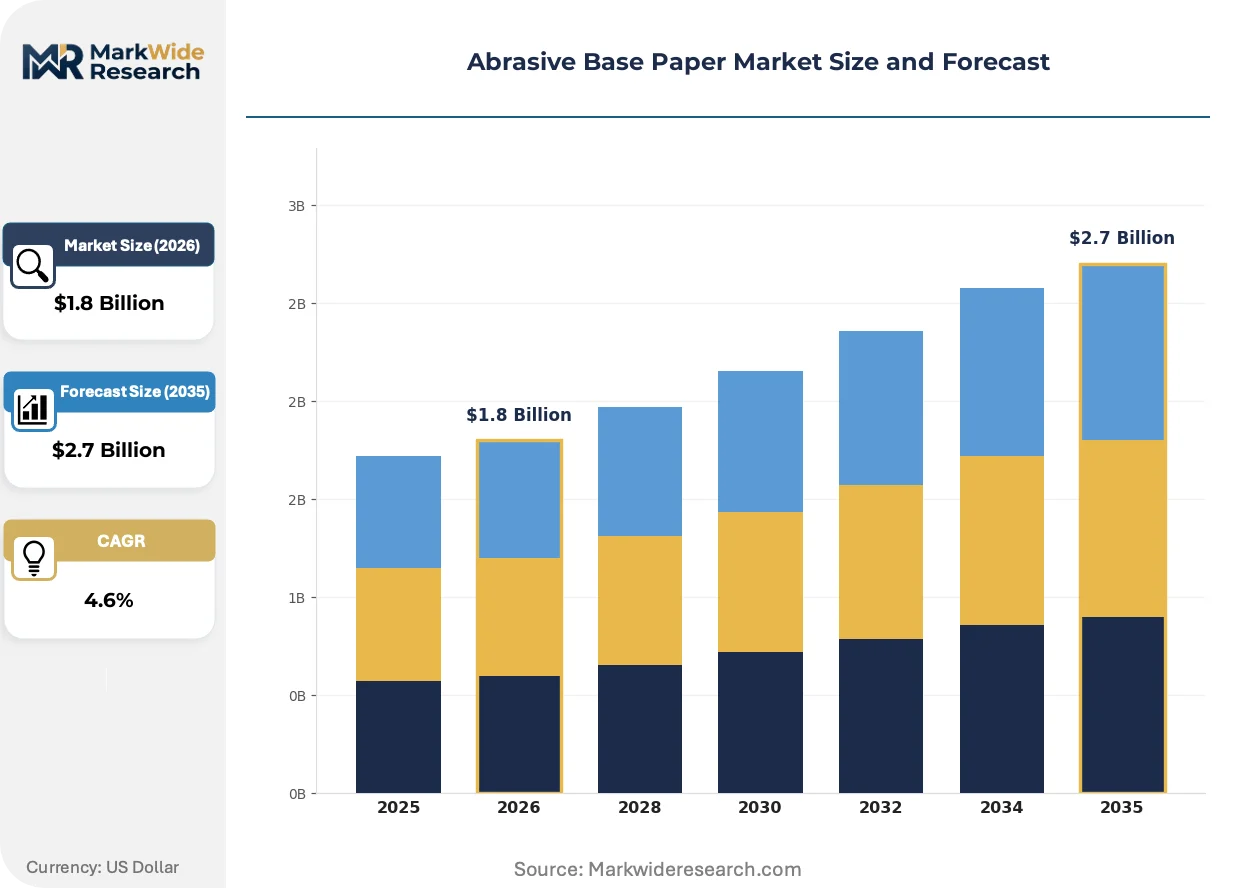
Market Dynamics
Water-based coating chemistry mandates from ECHA REACH and the EU Green Deal are forcing capital reallocation across European production lines, while automotive OEM surface-quality protocols pull premium substrate specifications upward.
Growth Catalysts
- Automotive refinishing protocols:OEMs in Germany enforce tighter surface-finish tolerances for bodywork repairs, mandating ultra-smooth glassine substrates that extend abrasive belt operational life.
- REACH substance authorization:ECHA restrictions on solvent-based resin binders accelerate water-based coating line investments, creating compliant capacity expansion.
- Fleet maintenance subscriptions:Industrial contractors and logistics operators sign recurring abrasive replenishment contracts, hardening predictable demand for calibrated grit-grade availability.
Market Restraints
- Pulp fiber cost volatility:Kraft paper feedstock prices swing with softwood supply disruptions, compressing margin buffers for heavy-duty metal grinding grades.
- Coating line capital intensity:UV-cured and water-based technology platforms demand eight-figure retrofit investments that freeze smaller European producers in legacy solvent configurations.
- Synthetic substrate substitution:Polyester and polyimide films penetrate high-temperature metal grinding applications where cellulose thermal limits constrain performance.
Strategic Opportunities
- Industrial woodworking clusters:Premium-grade consumption concentrates in German furniture manufacturing hubs where precision finishing commands substrate quality premiums.
- UV-cured coating convergence:Instant polymerization technology merges with water-based resin systems, enabling emission-compliant high-speed production lines.
- Just-in-time logistics integration:Abrasive suppliers embed inventory management software with automotive refinishing chains, capturing service-layer revenue.
Industry Challenges
- Coating formulation expertise gap:Water-based binder chemistry requires polymer science specialists scarce in traditional paper-abrasive engineering departments.
- Multi-jurisdiction compliance timelines:Simultaneous EPA VOC guidelines and ECHA substance reviews force parallel certification tracks that delay product launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasive Base Paper Market Trends and Innovations
Coating technology platforms and procurement architectures are restructuring how abrasive substrates reach end-users. Three developments merit particular attention.
UV-cured resin systems is electrifying European production economics. These instant-polymerization platforms eliminate thermal drying stages, cutting energy consumption per coated ton. Automotive refinishing chains in Stuttgart and Wolfsburg adopt UV-compatible abrasive belts at accelerating pace. The technology is electrifying capital efficiency benchmarks for mid-volume European producers.
EPA emissions guidelines restrict volatile organic compound release from solvent-based coating lines in the United States. Capital redirects toward water-based and UV-cured platforms, freezing expansion of legacy thermal-dry infrastructure. Paper-backed abrasive manufacturers serving automotive and metal fabrication verticals face compressed compliance windows.
Maintenance subscription contracts harden recurring revenue expectations among fleet operators and industrial contractors. Abrasive suppliers must guarantee grit-grade availability and just-in-time replenishment logistics. German automotive refinishing chains demand vendor-managed inventory with penalty clauses for stockouts.
Abrasive Base Paper Market Segmentation
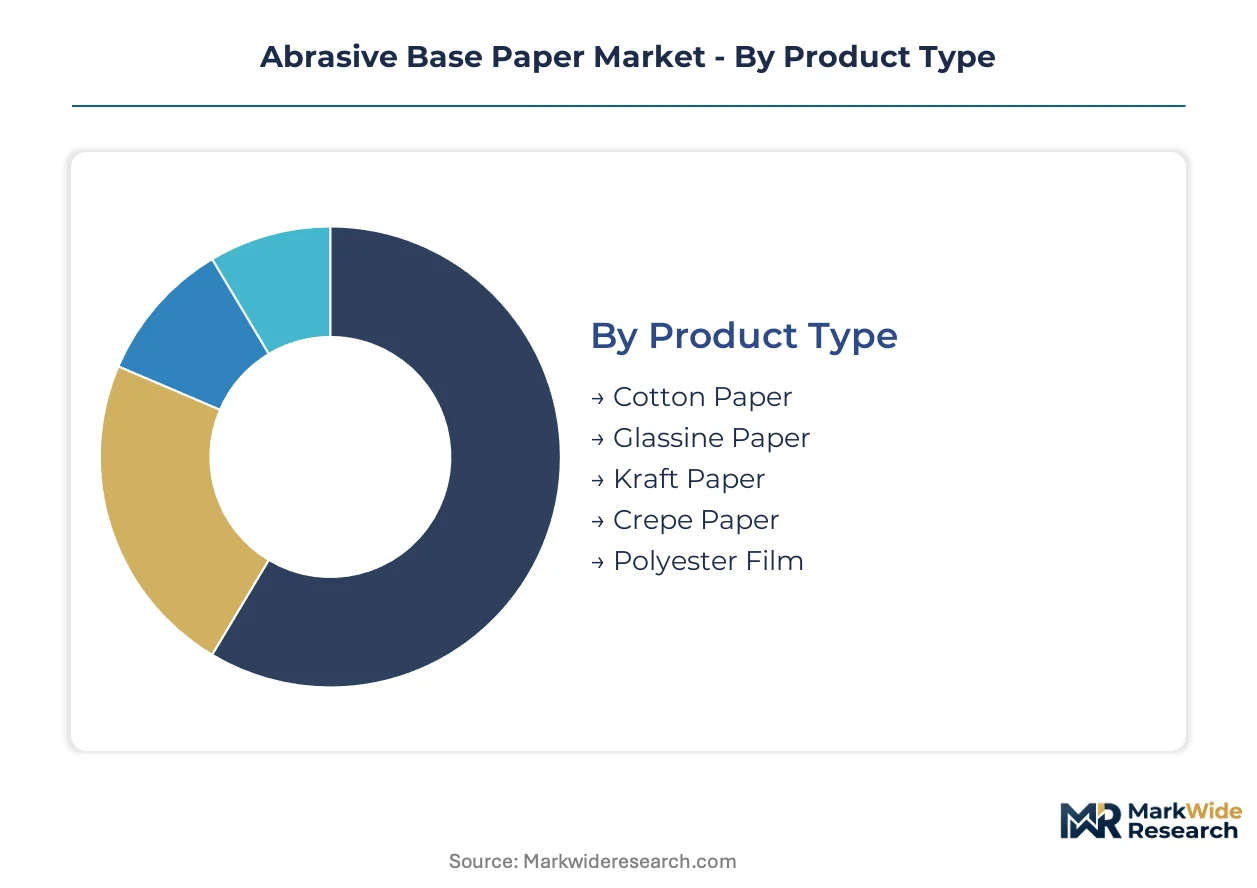
Substrate specifications and coating chemistries fragment the abrasive base paper landscape into distinct performance tiers. Each segment carries unique compliance burdens and margin structures that reshape supplier positioning across automotive, aerospace, and industrial woodworking verticals.
Product Type:
Material composition dictates thermal tolerance, tear resistance, and surface finish fidelity across precision grinding operations.
- Kraft Paper:Unbleached softwood pulp construction delivers cost-efficient tear resistance for heavy-duty metal grinding belts. Construction contractors in Germany anchor volume demand as infrastructure maintenance cycles tighten abrasive consumption patterns.
- Glassine Paper:Supercalendered cellulose substrate achieves sub-micron surface smoothness that prevents coating defects in automotive clear-coat finishing. Stuttgart and Wolfsburg refinishing chains specify glassine-backed abrasives to extend belt operational life under OEM surface-quality protocols.
- Cotton Paper:Rag fiber content provides conformability for contoured woodworking applications where substrate flexibility prevents edge burning.
- Crepe Paper:Crimped fiber structure absorbs vibration in hand-sanding operations across furniture manufacturing clusters.
- Polyester Film:Synthetic substrate penetrates high-temperature metal grinding where cellulose thermal degradation limits performance.
Kraft paper leads on scale; glassine paper leads on momentum.
Application:
End-use precision requirements stratify substrate specifications from rough-stock removal to mirror-finish polishing.
- Automotive Bodywork:OEM refinishing protocols mandate ultra-smooth substrates for clear-coat defect prevention. German automotive clusters drive specification tightening as surface-finish tolerances compress.
- Metal Finishing:Heavy-duty grinding of fabricated components consumes kraft-backed abrasives in volume. Fabrication shops prioritize tear resistance and cost efficiency over surface perfection.
- Woodworking:Precision furniture finishing commands premium substrate quality in German manufacturing hubs.
- Marine Maintenance:Salt-air corrosion resistance requirements shape coating binder specifications for shipyard abrasive inventories.
- Aerospace Components:Tight dimensional tolerances and thermal cycling resistance define substrate selection for turbine blade finishing.
Metal finishing dominates volume throughput; automotive bodywork climbs fastest on specification premiumization.
End User Industry:
Procurement scale and technical sophistication diverge sharply between maintenance contractors and precision manufacturers.
- Vehicle Assemblers:Captive refinishing operations specify glassine substrates under long-term vendor-managed inventory contracts. Fleet maintenance subscriptions harden recurring revenue expectations with penalty clauses for stockouts.
- Construction Contractors:Price-sensitive bulk procurement of kraft-backed abrasives for structural metal preparation. Softwood pulp cost volatility compresses margin buffers for suppliers serving this tier.
- Fabrication Shops:Mid-volume grinding operations balance substrate durability against per-belt cost.
- Shipyards:Maintenance scheduling drives seasonal demand spikes for corrosion-resistant abrasive inventories.
- Aircraft Manufacturers:Certification-grade finishing requirements lock in premium substrate specifications with limited supplier switching.
Construction contractors anchor volume scale; vehicle assemblers drive contract structuring innovation.
Coating Technology:
Regulatory compliance timelines and capital intensity fragment supplier capabilities across chemistry platforms.
- Water-Based:ECHA REACH substance authorization and EU Green Deal mandates redirect European production investment. Reformulation expertise gaps in polymer science constrain smaller producers.
- UV-Cured:Instant polymerization eliminates thermal drying, cutting energy consumption per coated ton. Stuttgart refinishing chains adopt UV-compatible belts at accelerating pace.
- Solvent-Based:EPA VOC guidelines restrict expansion of legacy thermal-dry infrastructure in the United States.
- Hot Melt:Thermoplastic adhesive systems serve cost-sensitive applications with lower performance thresholds.
- Electrostatic:Precision coating deposition for premium abrasive grades where mineral distribution uniformity determines cut consistency.
Solvent-based retains installed base dominance; UV-cured gains share fastest on capital efficiency benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-grade consumption through automotive refinishing clusters, while the United States anchors volume scale through construction and metal fabrication demand. China builds synthetic substrate capacity for high-temperature industrial applications. Geographic differentiation sharpens as regulatory timelines and end-use specifications diverge.
United States
Metal fabrication shops and construction contractors drive kraft paper consumption for structural grinding and surface preparation. EPA VOC guidelines restrict solvent-based coating line expansion, redirecting capital toward water-based and UV-cured platforms. Industrial corridors in Ohio and Michigan concentrate abrasive belt demand from automotive component suppliers.
Germany
Automotive OEM refinishing protocols mandate ultra-smooth glassine substrates for clear-coat defect prevention. ECHA REACH substance authorization limits specific resin binders, compelling coating recipe reformulation. Stuttgart and Wolfsburg refinishing chains specify premium substrates under vendor-managed inventory contracts with penalty clauses.
China
High-temperature metal grinding applications accelerate polyester and polyimide film substitution where cellulose thermal limits constrain performance. GB standards and dual carbon goals pressure coating line efficiency improvements. Yangtze River Delta manufacturing hubs integrate abrasive substrate production with downstream mineral coating operations.
Japan
Precision electronics finishing and aerospace component manufacturing command substrate uniformity premiums. METI industrial standards shape coating chemistry specifications for domestic abrasive producers. Nagoya and Osaka industrial zones concentrate demand from turbine blade and semiconductor equipment fabricators.
India
Furniture manufacturing and shipyard maintenance drive cotton and kraft paper consumption across price-sensitive procurement tiers. BIS quality standards and PLI scheme incentives support domestic abrasive substrate capacity expansion. Gujarat and Maharashtra industrial corridors anchor regional distribution networks for construction and woodworking applications.
Abrasive Base Paper Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium automotive refinishing favoring integrated coating-substrate specialists while construction-grade volume flows to cost-optimized kraft suppliers. The vendor base organizes into three archetypes: European coating-technology leaders, Asian scale-driven substrate fabricators, and regional logistics-integrated service providers. Consolidation pressure concentrates among mid-volume European producers facing eight-figure compliance retrofit costs. Dominant competitive moves include backward integration into pulp supply and just-in-time logistics partnerships with fleet maintenance operators.
Among European coating-technology leaders, Saint-Gobain and Klingspor occupy positions exemplifying divergent strategic vectors. Saint-Gobain leverages its distribution network to anchor long-term service agreements with automotive refinishing chains. Klingspor competes through specialized product lines calibrated to regional abrasive standards. These two represent the branded specialist tier confronting compliance-driven capital reallocation.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Klingspor |
| Mirka |
| Deerfos |
| Carborundum Universal |
| Sia Abrasives Industries |
| Hermes Schleifmittel |
| AWUKO Abrasives |
| Others |
Pricing and Supply Chain Analysis
UV-cured coating line adoption in Germany and the United States simultaneously compresses per-unit production costs and concentrates supply among capital-rich producers capable of eight-figure retrofits, reshaping competitive economics across substrate tiers.
Pricing Analysis
Capacity additions in China for polyester film substrates are reshaping price floors for high-temperature metal grinding grades. Three-tier pricing structure across premium, standard, and economy levels separates glassine-backed automotive abrasives from kraft construction grades and synthetic film industrial belts. Price differentiation hinges on coating chemistry compliance costs and substrate uniformity certification. Construction contractors in Germany exhibit highest price sensitivity, while vehicle assemblers accept premium positioning for vendor-managed inventory guarantees.
Supply Chain Analysis
Polymer science specialist shortages in European coating engineering hubs and skilled technician gaps across Yangtze River Delta manufacturing clusters constrain production scaling. Supply concentrates in Germany for premium glassine substrates, China for synthetic film capacity, and the United States for kraft paper volume production. Raw material flows draw from Nordic softwood pulp, petroleum-based resin feedstocks, and mineral abrasive imports. Single-source vulnerability runs through German automotive refinishing chains dependent on Saint-Gobain and Klingspor distribution networks. Distribution runs through direct OEM contracts for premium tiers and industrial distributors for construction grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: ECHA REACH compliance costs in Europe run 40-60% above EPA guideline adherence in the United States, creating margin expansion opportunities for transatlantic production footprints.
For Market Incumbents: Deepen backward integration into Nordic softwood pulp supply to buffer kraft paper margin compression from fiber cost volatility. Secure captive coating chemistry R&D capacity in polymer science to close formulation expertise gaps before water-based mandate deadlines. Defensive consolidation targets mid-volume European producers frozen in legacy solvent configurations by compliance retrofit burdens. For New Entrants and Emerging Players: Regional fabrication shops in India present the most penetrable buyer archetype, with BIS standards compliance creating lower barriers than ECHA or EPA regimes. White-space targets include cotton paper conformability grades for Gujarat furniture manufacturing clusters and corrosion-resistant coating binders for Maharashtra shipyard maintenance. Go-to-market leverage should anchor on price-competitive kraft supply with flexible minimum order quantities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-volume European producers facing stranded asset risk from water-based transition capital demands. Long-term viability across the analysis window favors coating-technology specialists with installed UV-cured capacity and automotive OEM contract tenure. Acquisition target archetype: German glassine substrate fabricators with vendor-managed inventory relationships in Stuttgart refinishing chains. Signal to watch: fleet maintenance subscription contract penetration rates as recurring revenue quality indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic softwood fiber sourcing insulates kraft paper margins from spot market volatility. |
| UV-Cured Coating Line Retrofit | Instant polymerization technology cuts energy consumption per coated ton for Stuttgart automotive suppliers. |
| Vendor-Managed Inventory Partnership | Just-in-time logistics integration captures service-layer revenue from German refinishing chains. |
| Water-Based Chemistry R&D Investment | Polymer science capacity closes formulation expertise gaps before ECHA REACH deadlines. |
| Synthetic Film Capacity Expansion | Polyester and polyimide substrates penetrate high-temperature grinding applications beyond cellulose limits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged coating technology directors at European abrasive manufacturers, procurement leads at German automotive refinishing chains, pulp supply managers at Nordic fiber producers, and logistics coordinators at industrial distribution networks. Secondary validation drew from ECHA substance authorization databases, EPA emissions guideline filings, customs trade data for abrasive substrate imports, and SEC disclosures from publicly traded coating technology suppliers. Bottom-up demand modeling triangulated against top-down industry value chain estimates.
Segment-weighting approaches distributed value and volume across substrate material tiers, coating chemistry platforms, end-use applications, and geographic production clusters. Analytical frameworks modeled adoption curves for water-based and UV-cured technologies over the projection horizon. CAGRs derived from regression analysis of historical capacity expansion patterns and regulatory compliance investment cycles. Industry-specific forecast inputs included automotive OEM surface-quality protocol tightening timelines and pulp fiber spot price volatility indices.
Underlying measurement precision varies by segment; glassine paper automotive grades carry tighter precision than cotton paper woodworking tiers due to concentrated buyer concentration and contract visibility. Forecasts reflect documented assumptions on ECHA REACH enforcement intensity and EPA guideline expansion scope. Material deviation in softwood pulp supply disruptions or synthetic substrate substitution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.