
 New Zealand Abrasives Market | 2026-2036
New Zealand Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Abrasives Market Foresight
Skilled abrasive application technicians is rotating toward higher-value precision work as automated grinding systems displace manual finishing in Canterbury and Waikato manufacturing plants. Norton Abrasives leverages its bonded abrasive foundry network to dominate heavy metalworking supply chains. GMA Garnet anchors the industrial blasting segment through its controlled alluvial garnet deposits in Western Australia feeding New Zealand distributors. Saint-Gobain differentiates via ceramic grain technology leadership in high-speed precision grinding for aerospace subcontractors.
Abrasives are hard minerals or synthetic grains bonded to backing materials that cut, grind, polish, or finish surfaces through frictional wear, with specifications measured by grit size, grain type, and bonding matrix. Superabrasives such as diamond and cubic boron nitride command premium positioning in toolroom and precision engineering applications where conventional aluminum oxide fails. Coated abrasives lead volume through construction and woodworking channels, while bonded abrasives sustain margin pools in foundry and metal fabrication end uses. Non-woven abrasives represent the fastest-growing product category as surface conditioning demand expands in automotive refinishing and medical device manufacturing.
WorkSafe New Zealand enforces the Health and Safety at Work Act exposure standards that mandate local exhaust ventilation for silica-generating abrasive processes, directly elevating demand for engineered vacuum-compatible products. BIS certification requirements for imported bonded abrasive wheels create compliance barriers that favor established suppliers with in-country testing relationships. Stakeholders must monitor how the proposed Product Stewardship Scheme for abrasive waste reshapes distributor accountability and end-of-life collection infrastructure.
Market Dynamics
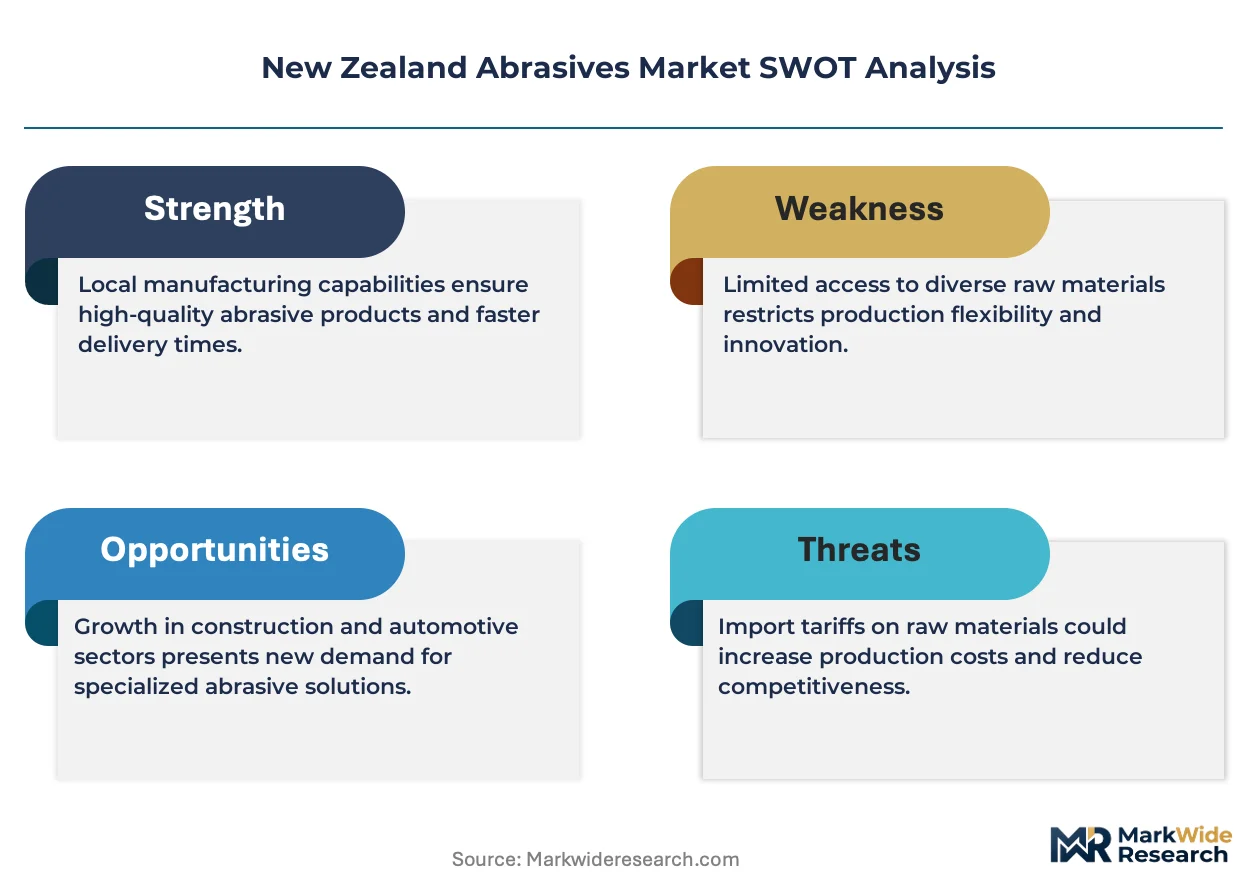
WorkSafe New Zealand's silica exposure standard revisions are compressing demand toward vacuum-integrated abrasive systems, forcing distributors to reconfigure their product portfolios around dust-controlled specifications rather than conventional price-competitive offerings.
Growth Catalysts
- Auckland infrastructure pipeline:The city's transport and water asset renewals are concentrating coated abrasive procurement in the upper North Island, with civil contractors specifying high-performance flap discs and fiber discs for structural steel preparation.
- WorkSafe exposure mandates:Updated Health and Safety at Work Act enforcement is elevating specification priority for on-tool extraction compatibility across construction and manufacturing procurement.
- Ceramic grain migration:Precision engineering subcontractors in Canterbury are adopting seeded-gel aluminum oxide for high-speed grinding applications where conventional fused alumina generates excessive heat.
Market Restraints
- Import dependency for superabrasives:Diamond and cubic boron nitride wheel supply concentrates through Australian distributors, exposing end-users to currency volatility and extended lead times.
- BIS certification friction:Bonded abrasive wheel import requirements create compliance delays that favor established suppliers with in-country testing relationships, raising barriers for new market entrants.
- Silica substitute limitations:Garnet and olivine blasting media face performance gaps in heavy marine coating removal, constraining full displacement of silica sand in shipyard applications.
Strategic Opportunities
- Wellington precision manufacturing cluster:Medical device and aerospace subcontractors present unmet demand for superabrasive toolroom products with documented traceability and batch certification.
- Product Stewardship Scheme development:Pending abrasive waste regulations would mandate producer-funded collection infrastructure, creating first-mover advantage for distributors establishing reverse logistics networks.
- Non-woven surface conditioning:Automotive refinishing shops in Waikato are transitioning from conventional coated abrasives to unified surface conditioning discs for scratch refinement and blend preparation.
Industry Challenges
- Skilled application technician scarcity:Automated grinding system deployment in Waikato and Canterbury manufacturing plants is reducing manual finishing headcount while creating demand for operators capable of programming and maintaining robotic cells.
- Legacy equipment integration:Foundries and metal fabricators operating conventional bench grinders face retrofit costs for exhaust ventilation compliance, compressing capital available for abrasive technology upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Abrasives Market |
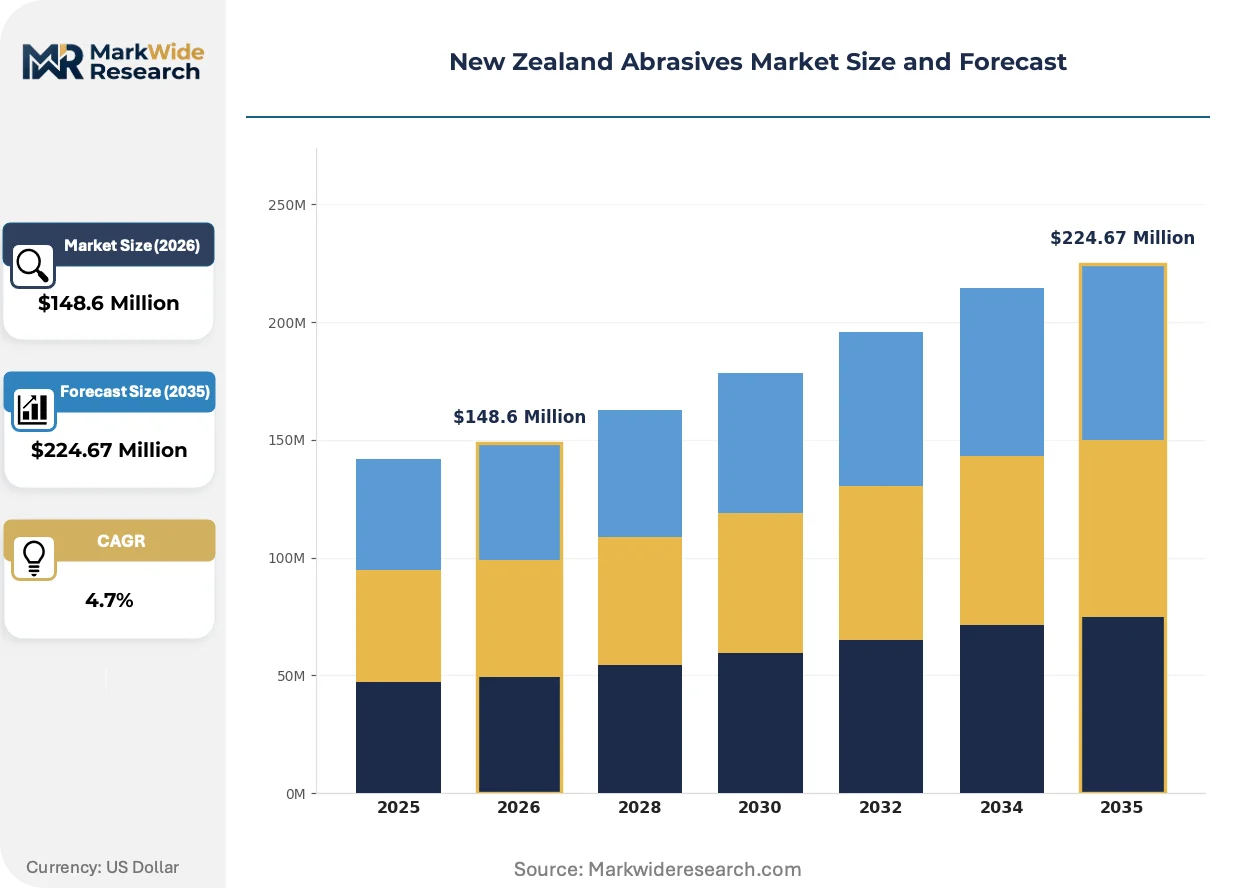
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $224.67 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Superabrasives, Non-Woven Abrasives End User: Manufacturing, Construction, Automotive, Metalworking Application: Surface Finishing, Grinding, Cutting, Polishing Distribution Channel: Direct Sales, Retail Sales, Online Sales, Wholesale |
| Companies Covered | Norton Abrasives, GMA Garnet Pty Ltd, Saint-Gobain, sia Abrasives Industries AG, Winoa, 3M, WASHINGTON MILLS, Mirka Ltd, Tyrolit Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Abrasives Market Shifts & Advancements
Automation and regulatory stringency are converging to reshape specification priorities across New Zealand's abrasive supply chains. Distributors must now bundle technical compliance support with traditional product supply to maintain relevance with institutional buyers.
Robotic grinding cells equipped with force-controlled abrasive belts are displacing manual weld preparation in Canterbury structural steel fabrication. Tier-two engineering subcontractors are adopting these systems to meet WorkSafe vibration exposure limits while maintaining throughput. The technology is compressing demand for conventional resin fiber discs in high-volume repetitive applications.
WorkSafe New Zealand's crystalline silica exposure standard reduction is mandating local exhaust ventilation for all abrasive blasting operations. Surface treatment contractors must now specify vacuum-blast systems or water-abrasive injection equipment for shipyard and infrastructure maintenance work. The regulation is elevating capital requirements for blasting service providers while favoring distributors offering equipment-and-media bundled solutions.
Specification authority is migrating from procurement departments to health and safety officers with technical competency requirements. Large construction firms and manufacturing groups now require abrasive product datasheets documenting silica content, exhaust compatibility, and vibration emission data prior to vendor approval. This shift is most visible in Auckland's infrastructure consortiums, where safety-led sourcing is overriding traditional price-based supplier selection.
New Zealand Abrasives Market Segmentation
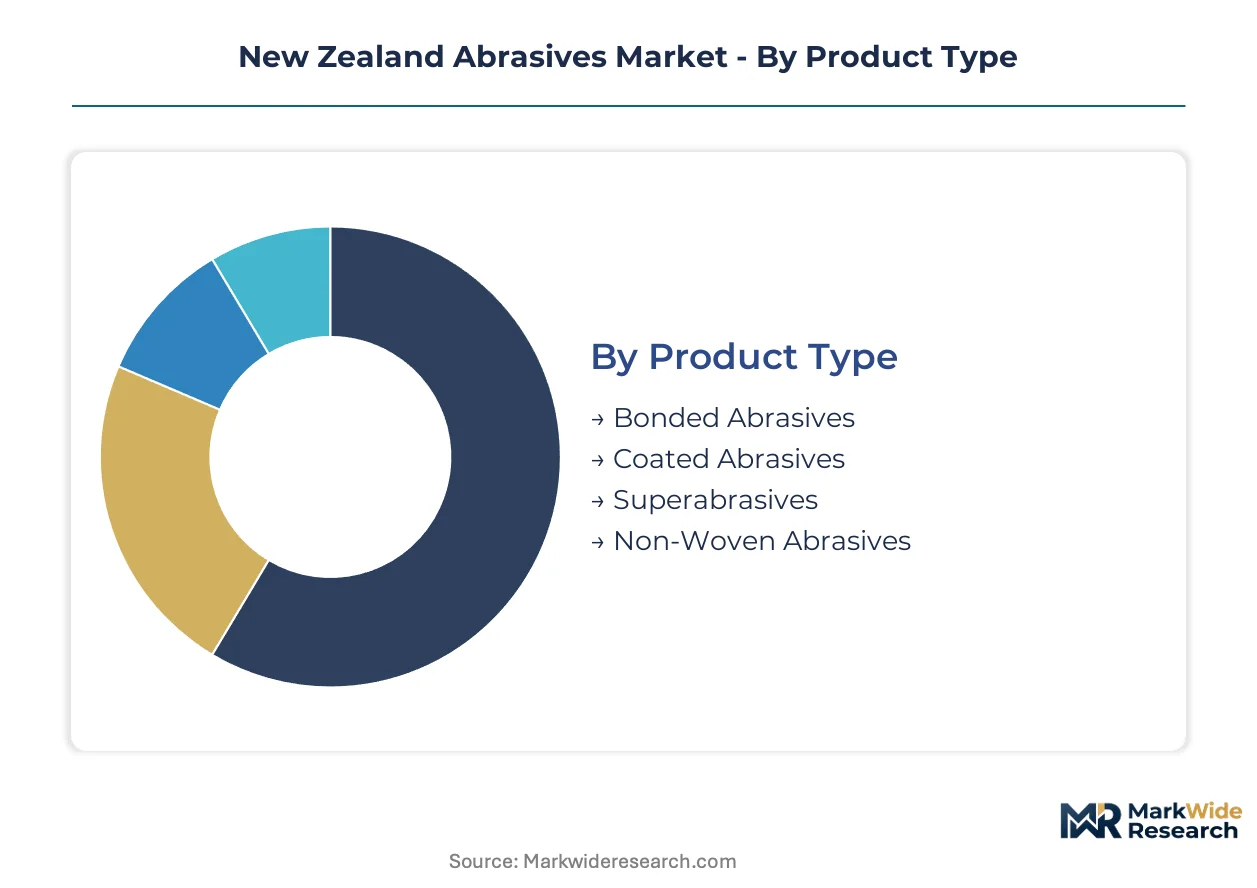
New Zealand's abrasive procurement patterns diverge sharply between domestic infrastructure demand and export-serving precision manufacturing. Segmentation reveals how WorkSafe compliance mandates and automation investments are reshaping specification priorities across product categories and end-use channels.
Product Type:
Domestic demand concentrates in bonded and coated abrasives serving construction and foundry work, while superabrasives remain almost entirely import-dependent through Australian distribution channels.
- Bonded Abrasives:Resinoid and vitrified grinding wheels dominate foundry and heavy metalworking applications across Waikato and Canterbury manufacturing belts. Foundries in Hamilton specify these for casting cleanup and weld grinding where thermal stability matters. WorkSafe's silica exposure mandates are forcing specification upgrades toward low-dust formulations with documented exhaust compatibility.
- Coated Abrasives:Flap discs, fiber discs, and sanding belts lead absolute volume through Auckland's infrastructure pipeline and residential construction channels. Civil contractors preparing structural steel for the City Rail Link and Central Interceptor projects drive procurement of high-performance ceramic-alumina variants. This segment holds the largest share; momentum sits with ceramic grain migration as contractors trade up from conventional aluminum oxide for faster cut rates.
- Superabrasives:Diamond and cubic boron nitride wheels serve toolroom and precision engineering applications with near-total import dependency through Australian distributors.
- Non-Woven Abrasives:Surface conditioning discs and hand pads are climbing the fastest as automotive refinishing shops in Waikato transition from conventional coated products for scratch refinement and blend preparation.
Coated abrasives dominate volume; non-woven products are gaining share fastest through automotive and medical device channels.
End User:
Cost-tier stratification separates premium specification manufacturing from price-sensitive construction procurement, with divergent compliance burdens reshaping supplier relationships.
- Manufacturing:Precision engineering subcontractors in Wellington and Canterbury drive demand for documented batch certification and traceability in superabrasive and ceramic grain applications. Medical device manufacturers require ISO-compliant surface finishing protocols that elevate specification authority toward quality engineers.
- Construction:Auckland's transport and water asset renewals concentrate coated abrasive procurement among tier-one civil contractors with safety-led sourcing mandates. WorkSafe enforcement has shifted specification authority from procurement departments to health and safety officers requiring silica content documentation and vibration emission data.
- Automotive:Refinishing shops and collision repair networks in upper North Island population centers sustain steady demand for surface conditioning and polishing systems.
- Metalworking:Foundries and structural steel fabricators across Waikato and Canterbury represent the core bonded abrasive installed base facing retrofit costs for exhaust ventilation compliance.
Construction commands volume leadership; manufacturing captures margin premium through compliance-intensive specification.
Application:
Application maturity varies by automation exposure, with robotic grinding displacing manual processes in high-volume repetitive work while hand-finishing persists in complex geometries.
- Surface Finishing:Non-woven abrasives and fine-grit coated products serve automotive refinishing and medical device manufacturing where cosmetic and functional surface specifications converge. Wellington's precision manufacturing cluster presents unmet demand for documented process control.
- Grinding:Robotic grinding cells equipped with force-controlled abrasive belts are displacing manual weld preparation in Canterbury structural steel fabrication. Tier-two engineering subcontractors adopt these systems to meet WorkSafe vibration exposure limits.
- Cutting:Thin-wheel bonded abrasives and diamond blades serve construction demolition and metal fabrication with specification driven by speed and safety certification requirements.
- Polishing:Final-stage surface refinement in aerospace subcontracting and automotive refinishing demands superabrasive compounds and unified surface conditioning systems with documented traceability.
Grinding applications are automating fastest; surface finishing holds the broadest cross-industry penetration.
Distribution Channel:
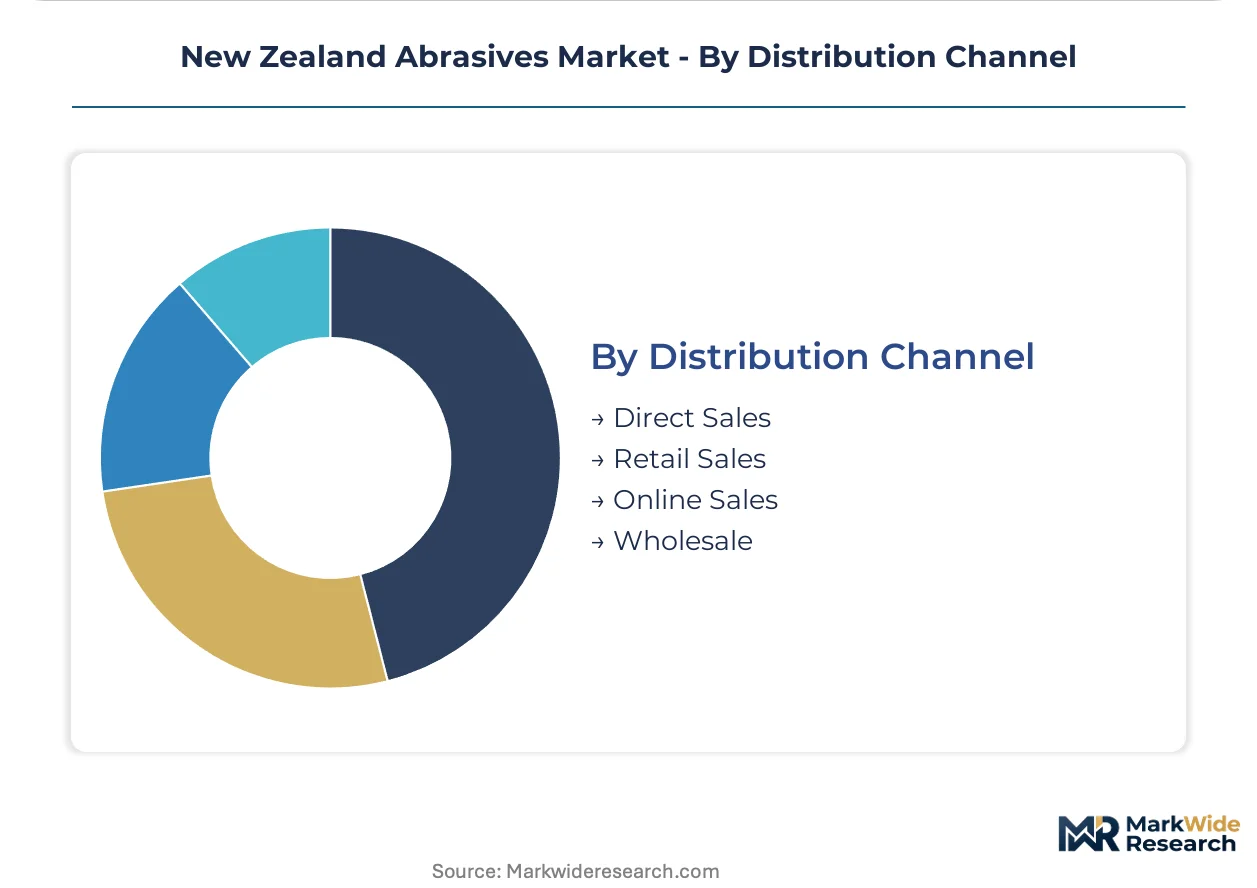
Channel configuration reflects customer scale and technical support requirements, with bundled equipment-and-media solutions gaining traction among compliance-pressured contractors.
- Direct Sales:Large manufacturing groups and infrastructure consortiums in Auckland procure through direct supplier relationships with technical compliance support bundled into supply agreements. Saint-Gobain and Norton Abrasives maintain field engineering presence for specification development.
- Retail Sales:Independent hardware and trade supply outlets serve residential construction and small metalworking shops with standard coated abrasive SKUs and limited technical guidance.
- Online Sales:E-commerce penetration remains constrained by BIS certification documentation requirements and the need for application-specific technical consultation in bonded abrasive wheel selection.
- Wholesale:Industrial distributors with in-country testing relationships capture bonded abrasive wheel volume by navigating compliance barriers that exclude direct import channels.
Wholesale channels dominate bonded abrasive volume; direct sales capture premium manufacturing accounts with embedded technical service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional consumption patterns diverge sharply between Auckland's infrastructure-heavy demand and Canterbury's precision manufacturing requirements, with WorkSafe enforcement creating compliance-driven specification gradients across the North and South Islands.
Auckland
Auckland's transport and water asset renewals concentrate coated abrasive procurement among tier-one civil contractors preparing structural steel for the City Rail Link and Central Interceptor projects. WorkSafe New Zealand's silica exposure mandates have shifted specification authority from procurement departments to health and safety officers requiring documented exhaust compatibility. The metropolitan region anchors volume demand for high-performance flap discs and fiber discs with vacuum-integration capabilities.
Waikato
Foundries and metal fabricators across Hamilton and the broader Waikato manufacturing belt sustain core bonded abrasive demand for casting cleanup and weld grinding applications. WorkSafe enforcement is forcing specification upgrades toward low-dust formulations with thermal stability credentials. The region's structural steel fabricators are deploying robotic grinding cells to meet vibration exposure limits while maintaining throughput.
Canterbury
Precision engineering subcontractors in Christchurch drive demand for ceramic grain abrasives and documented batch certification in aerospace and medical device manufacturing. Tier-two engineering firms are adopting force-controlled abrasive belt systems to displace manual weld preparation. The region's manufacturing plants are reducing manual finishing headcount while creating demand for robotic cell operators.
Wellington
Wellington's precision manufacturing cluster presents unmet demand for superabrasive toolroom products with ISO-compliant surface finishing protocols. Medical device manufacturers in the region require documented traceability and process control that elevates specification authority toward quality engineers. The capital's aerospace subcontractors are migrating toward seeded-gel aluminum oxide for high-speed grinding applications.
Upper North Island
Automotive refinishing shops across Waikato and Bay of Plenty population centers are transitioning from conventional coated abrasives to non-woven surface conditioning discs for scratch refinement. Collision repair networks sustain steady demand for polishing systems and unified surface preparation products. The region's distribution channels are bundling equipment-and-media solutions to capture compliance-pressured contractor volume.
New Zealand Abrasives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in New Zealand's abrasive supply chains. The upper tier combines global manufacturing scale with in-country technical service presence, while mid-tier players navigate BIS certification barriers through established testing relationships. Strategic archetypes include bonded abrasive foundry specialists, ceramic grain technology leaders, and industrial blasting media suppliers. Competitive moves concentrate on portfolio diversification around dust-controlled specifications and geographic expansion through distributor network consolidation.
Among the integrated leaders, Norton Abrasives and Saint-Gobain exemplify the premium-tier vector combining field engineering presence with specification development capabilities. GMA Garnet Pty Ltd anchors the industrial blasting segment through controlled alluvial garnet deposits feeding New Zealand distributors. These three companies represent distinct strategic positions: bonded abrasive foundry dominance, ceramic grain precision leadership, and blasting media supply security respectively.
| Leading Market Players |
|---|
| Norton Abrasives |
| GMA Garnet Pty Ltd |
| Saint-Gobain |
| sia Abrasives Industries AG |
| Winoa |
| 3M |
| WASHINGTON MILLS |
| Mirka Ltd |
| Tyrolit Group |
| Others |
Supply & Pricing Matrix
WorkSafe New Zealand's BIS certification requirements for bonded abrasive wheels gate both supplier qualification and price differentiation simultaneously, forcing distributors with in-country testing relationships to command premium positioning while excluding direct import channels from price-competitive participation.
Pricing Analysis
Long-term offtake agreements dominate procurement for tier-one Auckland infrastructure consortiums, while spot purchasing persists among residential contractors and small metalworking shops. Three-tier pricing structure across premium, standard, and economy levels separates ceramic grain systems with exhaust compatibility documentation from conventional aluminum oxide products and unbranded import alternatives. Cost compression in the economy tier is intensifying because BIS certification delays favor established suppliers with testing infrastructure. Tier-one civil contractors demonstrate lowest price sensitivity due to safety-led sourcing mandates, while independent hardware outlets serving residential construction remain most responsive to unit cost.
Supply Chain Analysis
Container availability fluctuations across the Trans-Tasman trade lane elevate inbound logistics costs for Australian-distributed superabrasives and bonded abrasive wheels. Manufacturing concentration in Australia, China, and the United States feeds New Zealand's import-dependent superabrasive segment, while bonded abrasive foundry supply draws from Australian and Southeast Asian production hubs. Raw material dependencies span fused alumina, silicon carbide, and synthetic diamond feedstocks. Single-source vulnerability concentrates in Australian distributor channels for cubic boron nitride wheels. Distribution runs through wholesale industrial distributors with BIS navigation capabilities, supplemented by direct sales relationships for premium manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between vacuum-integrated abrasive systems and robotic grinding platforms is creating platform-economics inflection, rewarding suppliers who bundle equipment, media, and compliance documentation into unified procurement packages.
For Market Incumbents: Compound technical service capabilities around dust-controlled specification development to defend against emerging equipment-and-media bundlers. Deepen backward integration into ceramic grain supply through Australian foundry partnerships. Prioritize certification investment for WorkSafe exhaust compatibility documentation to maintain specification authority with Auckland infrastructure consortiums.
For New Entrants and Emerging Players: BIS certification fast-track through established testing laboratory relationships unlocks bonded abrasive wheel market access otherwise blocked to direct import channels. Target Wellington precision manufacturing cluster for superabrasive toolroom products with ISO-compliant batch traceability. Pursue automotive refinishing shops in Waikato transitioning to non-woven surface conditioning discs as the most penetrable conversion segment.
For Investors and Strategic Acquirers: WorkSafe New Zealand's pending Product Stewardship Scheme reshapes the acquisition landscape toward distributors with reverse logistics infrastructure capabilities. Five-to-ten year viability favors wholesale channels with in-country testing relationships and technical compliance bundling. Target acquisition archetype: mid-tier industrial distributors with established BIS navigation and field engineering presence. Signal to monitor: regulatory finalization of abrasive waste collection mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Supply | Australian foundry partnerships secure seeded-gel aluminum oxide feedstock for high-speed grinding specifications. |
| Equipment-and-Media Bundled Solutions | Vacuum-blast system packages with garnet media capture compliance-pressured shipyard contractor procurement. |
| Reverse Logistics Network Development | Producer-funded collection infrastructure creates first-mover positioning under pending Product Stewardship regulations. |
| Robotic Grinding Cell Integration | Force-controlled abrasive belt systems displace manual weld preparation in Canterbury structural steel fabrication. |
| Superabrasive Toolroom Certification | Documented batch traceability unlocks Wellington medical device and aerospace subcontractor specification authority. |
Research Methodology
The analysis maps bonded abrasive foundry supply, coated abrasive distribution channels, superabrasive import dependency, and non-woven surface conditioning adoption, each validated through procurement managers at tier-one civil contractors, health and safety officers with specification authority, wholesale distributor technical directors, and precision engineering quality engineers. Primary interview insights combined with WorkSafe New Zealand regulatory filings, BIS certification documentation, customs import records, and industry association trade data. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, application method, and regional demand cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection and automation penetration rates. Industry-specific forecast inputs incorporate WorkSafe enforcement intensity and Auckland infrastructure pipeline project commitments.
Underlying assumptions cover sustained BIS certification requirements, silica exposure standard maintenance, and infrastructure project continuity, with deviation risk concentrated in regulatory timeline acceleration or project deferral. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Abrasive Rolls Market
Abrasives
Grinding Wheels Market
Abrasives
Boron Carbide Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Metal Abrasives Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Liquid Sandpaper Market
Abrasives
Super Abrasives Market
Abrasives
Carbide Tools Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Calcined Shale Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
RDP Powder Market
Abrasives
Vitrified Bonded Grinding Wheels Market