
 Chemical Mechanical Polishing Market | 2026-2036
Chemical Mechanical Polishing Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Mechanical Polishing Market Analysis
Advanced logic foundries is recalibrating the demand profile for CMP consumables as 3nm and 2nm process ramps absorb higher pad and slurry volumes per wafer pass. Applied Materials Inc leverages its integrated process equipment portfolio to bundle CMP tools with adjacent metrology systems. DuPont de Nemours Inc. anchors the North American slurry supply base through its specialty chemicals division, while Entegris Inc. controls contamination-critical fluid handling architectures that protect pad and slurry integrity.
Chemical mechanical polishing combines abrasive slurry chemistry with precise mechanical abrasion to achieve nanometer-scale planarization on silicon, dielectric, and metal surfaces, typically operating at pressures below 6 psi with particle sizes ranging from 10 to 300 nanometers depending on the target material removal rate. The process enables multilevel interconnect fabrication in semiconductor manufacturing where topography control directly impacts yield at smaller nodes. Slurries and pads capture the majority of recurring consumable spend as foundries prioritize consistency in removal rate and defectivity. Equipment and tools represent higher upfront capital outlays but generate extended revenue through service contracts and upgrade cycles.
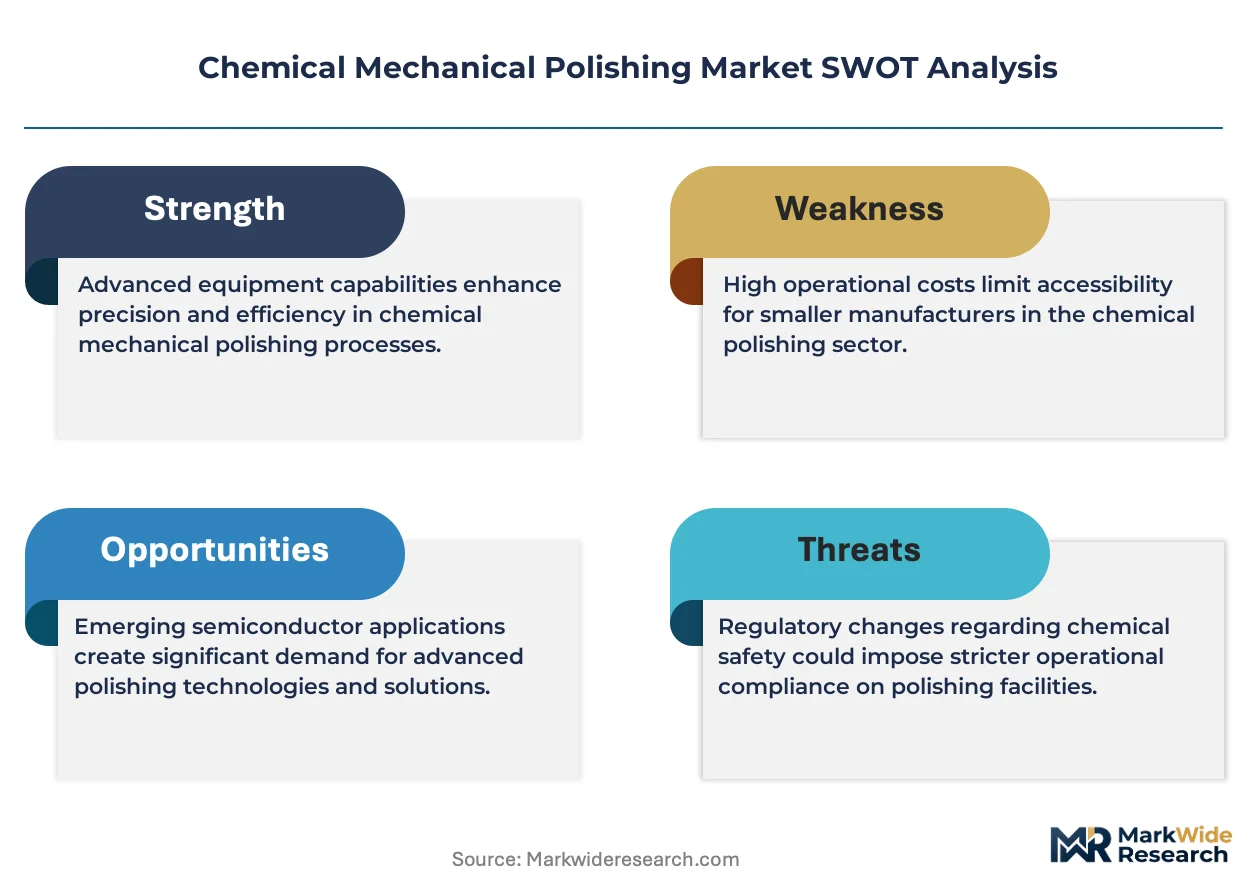
EPA regulations in the United States govern hazardous chemical reporting for slurry constituents, while REACH in Europe mandates full substance registration and safety documentation for imported polishing compounds. Japan's METI enforces chemical management protocols that affect slurry formulation transparency across the supply chain. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that disrupt qualification timelines.
Market Dynamics
Sub-3nm node ramps are recalibrating consumable intensity per wafer pass, with foundries absorbing 40-60% higher slurry volumes for advanced logic planarization compared to legacy nodes. This geometry compression is forcing simultaneous pad refresh rate acceleration and contamination control tightening across Taiwan, South Korea, and Japan's concentrated fabrication clusters.
Growth Catalysts
- Advanced node geometry compression:Logic manufacturers at 2nm and 3nm nodes require multiple CMP steps per metal layer, multiplying recurring consumable pull-through per wafer start.
- EPA hazardous chemical reporting:Slurry formulation disclosure mandates under the Toxic Substances Control Act are accelerating qualification of lower-toxicity abrasive chemistries among US-based semiconductor operations.
- Chinese fab localization:Domestic tool procurement subsidies under China's integrated circuit investment guidelines are expanding installed CMP capacity for 28nm and 14nm mature node production.
Market Restraints
- Colloidal silica supply concentration:High-purity fumed silica feedstock for abrasive particles concentrates among Japanese and German chemical suppliers, exposing formulators to input cost volatility and allocation risk.
- Pad duopoly structure:Polyurethane polishing pad manufacturing remains captive to two US-based material science firms, limiting second-source options for foundries seeking supply assurance.
- Slurry shelf-life constraints:Particle aggregation kinetics in ceria and alumina formulations impose 6-12 month use windows, complicating inventory positioning for distant fabrication sites.
Strategic Opportunities
- India semiconductor manufacturing incentives:Production-linked incentive schemes for domestic fabs in Gujarat and Assam create greenfield CMP consumable demand as tool installation accelerates through 2027.
- Dielectric-to-metal slurry convergence:Formulators developing dual-purpose chemistries compatible with both oxide and copper surfaces can compress SKU complexity for foundry procurement teams.
- Closed-loop slurry filtration:On-site particle separation and chemistry regeneration systems offer foundries 15-25% consumable cost reduction while aligning with EPA waste minimization preferences.
Industry Challenges
- Process engineer scarcity:The intersection of materials chemistry, tribology, and semiconductor physics required for CMP optimization outpaces university pipeline output in Taiwan and South Korea.
- Multi-site qualification burden:Foundries operating identical process nodes across geographically dispersed fabs must replicate slurry-pad-tool matching studies for each location, extending new product introduction timelines.
- Legacy 200mm tool compatibility:Power discrete and analog chip manufacturers on older polishing platforms face constrained pad and slurry availability as suppliers prioritize 300mm advanced node formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Mechanical Polishing Market |
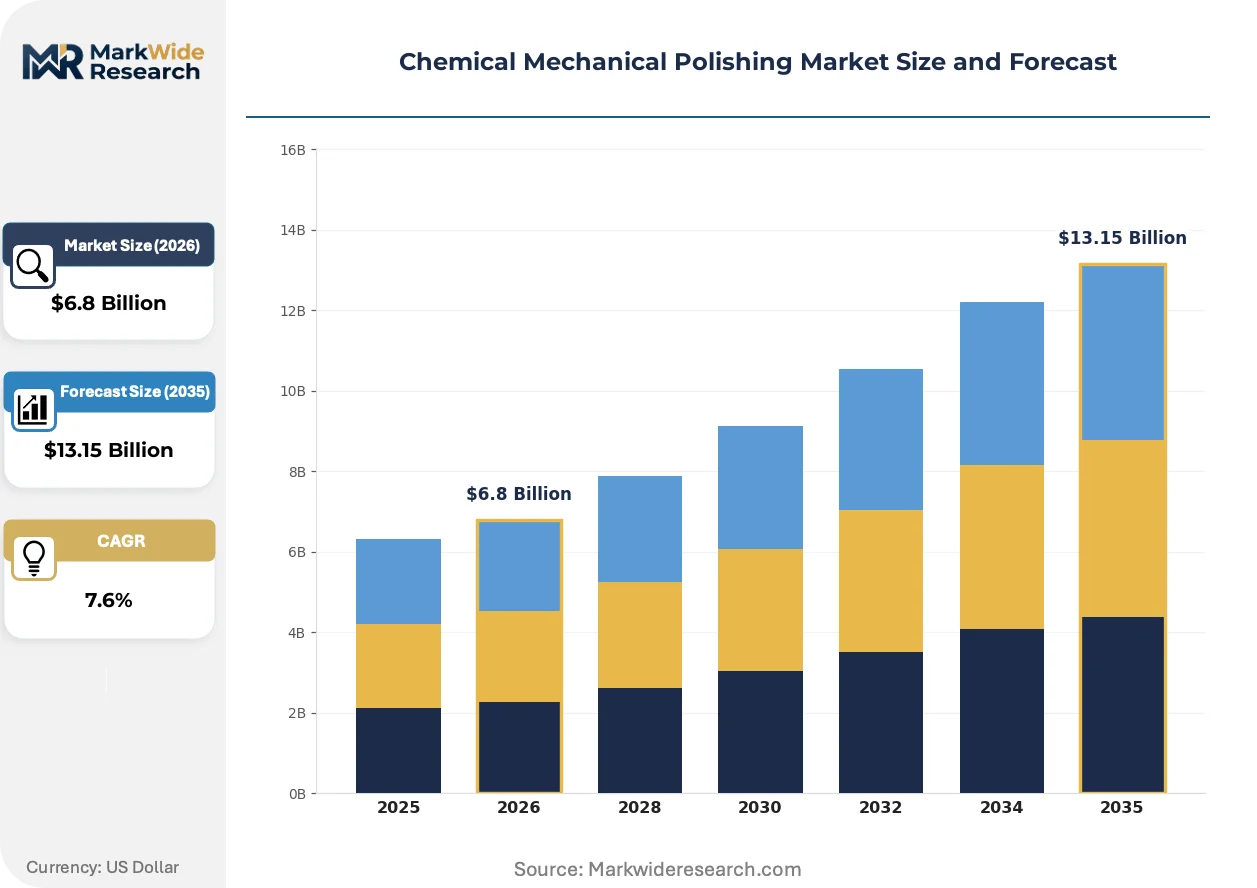
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slurries, Pads, Tools, Equipment Application: Semiconductors, Data Storage, Optics, Solar Cells End User: Manufacturers, Original Equipment Manufacturers, Foundries, Research Institutions Deployment: In-House, Contract Manufacturing, Outsourced Services, On-Site Support |
| Companies Covered | Applied Materials Inc, Ebara Corporation, DuPont de Nemours Inc., Entegris Inc., Cabot Microelectronics Corporation, Fujibo Holdings Inc., Tokyo Electron Limited, Resonac Holdings, Fujimi Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Mechanical Polishing Market Emerging Trajectories
Process control digitization is embedding real-time endpoint detection and predictive maintenance into CMP tool architectures, compressing the feedback loop between metrology and consumable adjustment. This instrumentation densification is reshaping supplier relationships and service contract structures.
Ceria-based slurries with engineered particle size distributions are expanding into tungsten plug and barrier metal applications previously dominated by alumina formulations. Memory manufacturers in South Korea are qualifying these chemistries for 3D NAND string stacking processes where tungsten fill uniformity determines cell reliability. The shift is expanding into logic foundries seeking single-slurry solutions across multiple metal layers.
REACH substance registration requirements in Europe are mandating full supply chain disclosure for slurry constituents above 0.1% concentration thresholds. Formulators must now document abrasive particle surface chemistry modifications and additive packages previously treated as proprietary. German chemical distributors are responding by consolidating supplier qualification documentation to accelerate customs clearance for imported polishing compounds.
Foundry procurement teams are consolidating slurry suppliers from 4-6 qualified sources per process node to 2-3 strategic partners with integrated pad-tool service capabilities. This concentration reflects total cost of ownership calculations that weight chemistry performance against logistics coordination and technical support density. The pattern is most visible among Taiwan-based pure-play foundries managing multi-fab consumable standardization programs.
Chemical Mechanical Polishing Market Segmentation
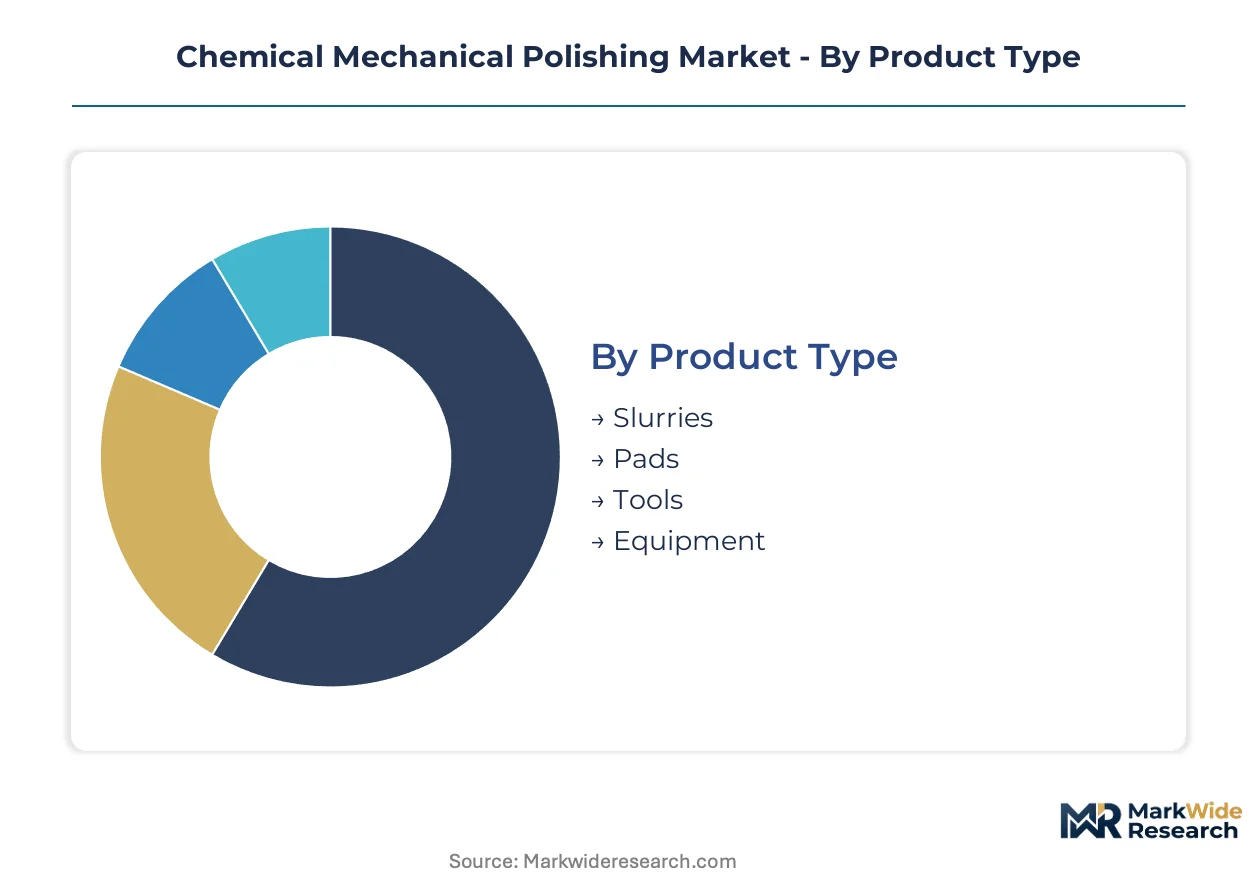
CMP market segmentation reveals distinct procurement patterns between consumables and capital equipment, with foundries managing radically different cost structures and supplier relationships across each category. Understanding these divisions illuminates where margin capture concentrates and where localization pressures reshape competitive dynamics.
Product Type:
Standalone consumables dominate recurring revenue streams while integrated tool systems anchor long-term vendor lock-in through service contracts and upgrade cycles.
- Slurries:Colloidal silica, ceria, and alumina suspensions engineered for specific removal rates on oxide, metal, and barrier layers. Taiwan and South Korea foundries absorb the highest volumes as 3nm logic ramps multiply CMP steps per wafer.
- Pads:Polyurethane-based polishing surfaces with engineered pore structures and groove patterns that determine planarization uniformity. DuPont anchors North American supply while Japanese material firms serve the concentrated Asian fabrication clusters.
- Tools:Polish heads, platens, and conditioning modules requiring precision mechanical alignment with consumable interfaces. Chinese fabs accelerate procurement of 28nm and 14nm compatible platforms under domestic investment guidelines.
- Equipment:Fully integrated CMP systems with embedded metrology and endpoint detection. Applied Materials bundles these with adjacent process equipment to compress qualification timelines for advanced node manufacturers.
Volume placements concentrate in slurries; the faster expansion belongs to equipment as digitization embeds process control capabilities.
Application:
Technology node requirements fragment demand profiles, with sub-3nm geometries imposing radically different consumable specifications than mature process manufacturing.
- Semiconductors:Logic and memory fabrication requiring nanometer-scale planarization across multiple metal and dielectric layers. South Korean 3D NAND manufacturers qualify ceria-based chemistries for tungsten plug uniformity.
- Data Storage:Hard disk drive substrate polishing where aluminum-magnesium alloy and glass surfaces demand distinct abrasive chemistries. Japanese precision component suppliers dominate this specialized consumable niche.
- Optics:Precision lens and mirror finishing for lithography systems and laser applications. German optical manufacturers source ultra-high-purity colloidal silica with tight particle size distributions.
- Solar Cells:Silicon wafer texturing and edge isolation processes where cost sensitivity favors lower-purity abrasive formulations. Chinese photovoltaic manufacturers drive procurement scale in this price-compressed segment.
Revenue density peaks in semiconductors; optics delivers the steepest expansion trajectory as extreme ultraviolet lithography deployment accelerates.
End User:
Procurement sophistication varies sharply, with foundries demanding integrated consumable-tool-service packages while research institutions prioritize experimental flexibility over scale economics.
- Manufacturers:Integrated device makers managing captive fabrication for proprietary chip designs. Texas Instruments and Analog Devices maintain in-house CMP operations for analog and power discrete production.
- Original Equipment Manufacturers:Tool builders sourcing consumable-compatible components and validation services. Applied Materials and Tokyo Electron coordinate pad and slurry qualifications with their platform architectures.
- Foundries:Pure-play contract manufacturers standardizing consumables across multi-fab networks. Taiwan Semiconductor Manufacturing Company consolidates suppliers from 4-6 sources to 2-3 strategic partners per node.
- Research Institutions:Universities and national laboratories testing novel abrasive chemistries and process parameters. MIT and IMEC maintain flexible qualification protocols for experimental slurry formulations.
Procurement volume clusters at foundries; research institutions generate the fastest qualification pipeline for next-generation formulations.
Deployment:
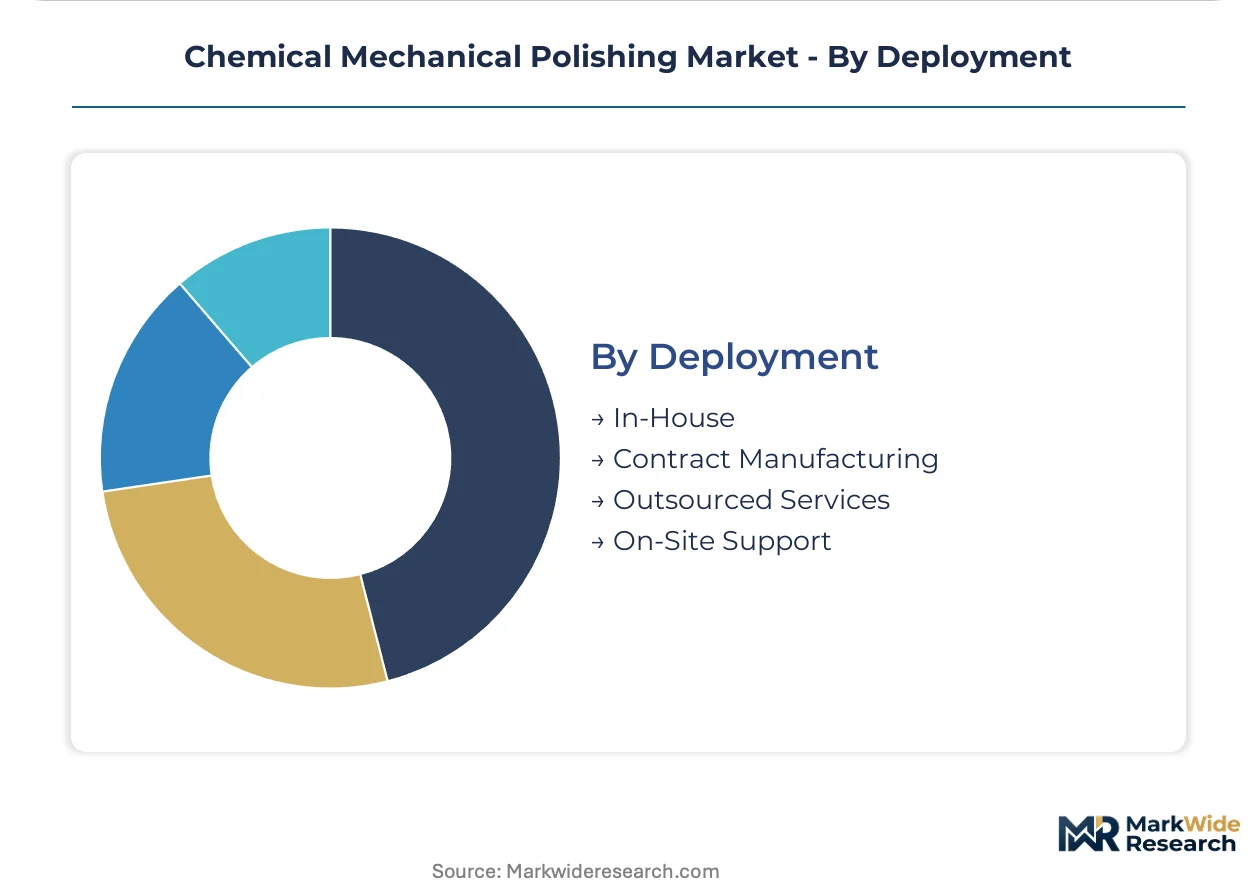
Operational model selection reflects capital intensity trade-offs, with advanced node manufacturers favoring captive capabilities while mature node producers exploit outsourcing flexibility.
- In-House:Captive CMP operations with dedicated engineering teams and direct supplier relationships. Samsung and SK Hynix maintain fully integrated polishing departments across their South Korean fabrication complexes.
- Contract Manufacturing:Third-party wafer processing services where CMP is bundled with lithography and deposition steps. GlobalFoundries offers this model for specialty semiconductor customers.
- Outsourced Services:Consumable supply and process management delegated to specialized vendors. Entegris provides fluid handling and contamination control as a managed service to US-based fabs.
- On-Site Support:Embedded technical teams from consumable suppliers coordinating real-time process optimization. Cabot Microelectronics stations engineers at major Taiwan foundry sites.
Capital deployment concentrates in in-house operations; outsourced services are climbing fastest as foundries seek to convert fixed costs to variable spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park in Taiwan concentrates the highest density of advanced CMP capacity globally, with tax incentives and infrastructure subsidies drawing consumable suppliers into co-located service operations.
Taiwan
Foundries at the 3nm node drive slurry consumption intensity 40-60% above legacy geometries. The National Development Council coordinates industrial park expansion to secure chemical supply chain resilience. Hsinchu and Tainan Science Parks host the majority of installed polish tools, with consumable suppliers embedding technical teams for real-time process support.
South Korea
Memory manufacturers qualify ceria-based formulations for 3D NAND tungsten plug applications previously served by alumina. METI-aligned chemical management protocols govern slurry import documentation and surface chemistry disclosure. Pyeongtaek and Yongin semiconductor clusters absorb the highest pad refresh rates as string stacking processes multiply CMP steps per wafer.
Japan
High-purity colloidal silica feedstock production concentrates among domestic chemical suppliers serving global formulators. METI enforces substance registration requirements that extend to abrasive particle surface modifications. The Kyushu region maintains specialty polishing capacity for silicon carbide power device substrates.
United States
EPA hazardous chemical reporting under the Toxic Substances Control Act accelerates qualification of lower-toxicity abrasive chemistries. Domestic foundries and IDMs manage captive CMP operations for analog and power discrete production. Texas and Arizona fabrication sites prioritize slurry formulations with extended shelf-life stability to offset distribution distances.
China
Domestic tool procurement subsidies under integrated circuit investment guidelines expand installed capacity for 28nm and 14nm mature node production. The Ministry of Ecology and Environment tightens wastewater discharge standards for polishing effluent. Yangtze River Delta fabs accelerate localization of pad and slurry supply chains to reduce import dependency.
Chemical Mechanical Polishing Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consumable formulators defending recurring revenue streams while equipment builders capture extended value through service contracts. The vendor base organizes into three tiers: integrated process equipment conglomerates, specialty chemical formulators with captive material science capabilities, and regional polish tool assemblers serving mature node demand. Consolidation pressures concentrate among consumable suppliers as foundries reduce qualified sources per node. Dominant competitive moves include backward integration into high-purity abrasive feedstock and geographic co-location with concentrated fabrication clusters.
Within the integrated equipment tier, Applied Materials Inc and Tokyo Electron Limited exemplify platform bundling strategies that compress qualification timelines for advanced node manufacturers. Among specialty chemical formulators, DuPont de Nemours Inc. anchors North American supply through material science capabilities, while Entegris Inc. occupies a position controlling contamination-critical fluid handling architectures. These three companies represent distinct archetypes: equipment-centric systems integration, chemical-centric consumable formulation, and infrastructure-centric process protection.
| Leading Market Players |
|---|
| Applied Materials Inc |
| Ebara Corporation |
| DuPont de Nemours Inc. |
| Entegris Inc. |
| Cabot Microelectronics Corporation |
| Fujibo Holdings Inc. |
| Tokyo Electron Limited |
| Resonac Holdings |
| Fujimi Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive integration into high-purity colloidal silica feedstock anchors both supply security and pricing power for slurry formulators serving Taiwan and South Korea foundries. This upstream control insulates qualified suppliers from Japanese and German chemical producer allocation volatility while compressing second-source options for buyers.
Pricing Analysis
Expedited lead-time premiums dominate contract negotiations as foundries running 3nm ramps absorb 40-60% higher consumable intensity per wafer. Pricing stratifies across premium, standard, and economy tiers where ceria-based formulations command brand premiums over alumina alternatives. Cost compression in mature-node slurries intensifies because Chinese domestic producers expand 28nm and 14nm supply capacity. Research institutions and specialty analog chipmakers exhibit highest price sensitivity due to constrained procurement volumes and legacy tool compatibility requirements.
Supply Chain Analysis
China's integrated circuit investment guidelines and domestic-content procurement subsidies are reshaping sourcing patterns for Yangtze River Delta fabs building 28nm capacity. High-purity fumed silica concentrates in Japan and Germany; polyurethane polishing pad manufacturing rests on two US-based material science firms. Single-source vulnerability pervades abrasive particle supply as METI-aligned chemical management protocols and EPA hazardous substance reporting tighten qualification barriers for new entrants. Distribution runs through direct technical service relationships with embedded engineering teams at major fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where foundry procurement teams reducing qualified suppliers from 4-6 sources to 2-3 strategic partners force weaker formulators and regional tool assemblers toward exit or acquisition.
For Market Incumbents: Cement supply assurance through backward integration into colloidal silica feedstock or binding long-term offtake with Japanese chemical producers. Expand embedded technical service density across Taiwan's Hsinchu-Tainan corridor to defend against equipment-centric bundling from Applied Materials and Tokyo Electron. Priority lever rests on contamination-control certification investment as Entegris-style fluid handling architectures become procurement gatekeepers.
For New Entrants and Emerging Players: Direct-to-foundry digital qualification platforms offer lower-friction entry paths than traditional multi-site matching studies. Target India's Gujarat and Assam greenfield fabs where production-linked incentive schemes create virgin procurement relationships absent incumbent lock-in. Dielectric-to-metal slurry convergence presents the most penetrable formulation white space as procurement teams seek SKU compression.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated equipment conglomerates seeking consumable-tool bundling capability. Five-to-ten-year viability favors formulators with captive abrasive feedstock and geographic co-location with Taiwan-South Korea fabrication density. Watch for EPA waste minimization preference enforcement as inflection signal accelerating closed-loop slurry filtration system deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colloidal Silica Feedstock | DuPont and Cabot Microelectronics anchor North American supply security against Japanese chemical allocation volatility. |
| Geographic Co-location with Taiwan Foundry Clusters | Embedded technical teams at Hsinchu Science Park compress real-time process optimization feedback loops. |
| Dual-Purpose Slurry Formulation Development | Ceria-based chemistries qualified for both oxide and copper surfaces reduce foundry procurement SKU complexity. |
| Closed-Loop Slurry Filtration System Deployment | On-site particle separation aligns with EPA waste minimization preferences while reducing consumable cost burden. |
| Long-Term Supply Agreement with Memory Manufacturers | SK Hynix and Samsung tungsten plug uniformity requirements lock in ceria formulation demand across 3D NAND ramps. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with slurry formulation chemists, CMP process engineers, foundry procurement directors, and fluid handling system architects validated demand assumptions. EPA Toxic Substances Control Act submissions, METI chemical management protocols, REACH substance registration databases, and semiconductor equipment import manifests supplied quantitative foundations. Bottom-up wafer start projections across Taiwan, South Korea, and China fabrication sites triangulated against top-down consumable spend estimates from IDM and foundry capital expenditure disclosures.
Granularity-level modeling distinguished between consumables and capital equipment segments, with slurry chemistry type, pad material composition, and tool platform generation constituting the primary product dimensions. Application-level splits captured logic versus memory fabrication intensity differentials, while deployment mode distinguished captive in-house operations from outsourced service arrangements. CAGRs derived from regression analysis of historical consumable intensity trends against node migration timelines, with foundry-reported CMP steps per wafer serving as critical input variables.
The model holds under continued sub-3nm node ramp schedules and stable abrasive feedstock supply; deviation in Chinese domestic tool procurement subsidy levels or colloidal silica export restriction enforcement would shift capacity expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carborundum Market
Abrasives
Metal Abrasives Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Fine Sandpaper Market
Abrasives
Synthetic Abrasives Market
Abrasives
Grinding Wheels Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Carbide Tools Market
Abrasives
Polishing Powder Market
Abrasives
Bonded Abrasive Market
Abrasives
Calcined Shale Market
Abrasives
Europe Abrasives Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Coated Abrasives Market
Abrasives
Glass Abrasives Market