
 Middle East and Africa Abrasives Market | 2026-2036
Middle East and Africa Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Abrasives Market Foresight
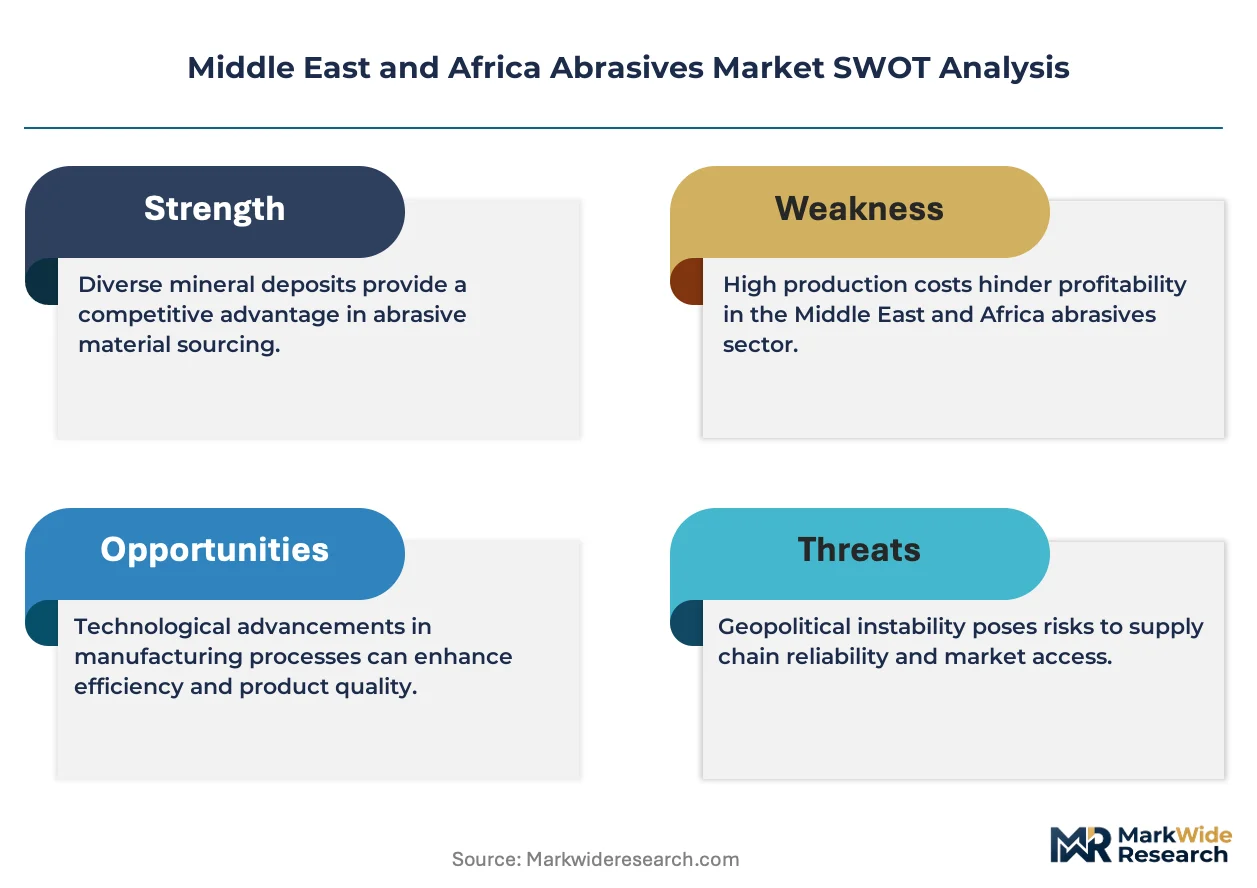
Asset-light leasing models for precision grinding equipment is reconfiguring competitive dynamics across the Middle East and Africa abrasives landscape. Saint-Gobain Abrasives leverages its bonded abrasives expertise to anchor long-term supply contracts with Gulf-based metal fabrication clusters. Robert Bosch GmbH competes through integrated power tool and consumable ecosystems that lock in recurring abrasive purchases. Carborundum Universal Ltd. sustains its position via backward integration into raw material sourcing across Southern Africa.
Abrasives are hard minerals or synthetic grains bonded into wheels, discs, belts, or loose media, engineered to specific grit sizes and hardness ratings for controlled material removal through friction. Bonded abrasives dominate volume flows into regional steel and foundry operations where grinding wheel integrity determines throughput. Super abrasives, particularly diamond and cubic boron nitride variants, command premium positioning in aerospace component finishing and precision tool sharpening applications. Coated abrasives lead growth velocity as automotive repair and woodworking SMEs across Nigeria and Kenya adopt flap disc and sandpaper formats for lower capital entry.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and South Africa's National Regulator for Compulsory Specifications (NRCS) enforce product safety and performance benchmarks that filter substandard imports from Asian suppliers. The UAE's Emirates Authority for Standardization and Metrology (ESMA) conformity assessment requirements shape market access protocols for bonded and coated abrasive imports through Dubai's re-export corridors. Stakeholders must monitor evolving localization incentives and certification reciprocity agreements between Gulf Cooperation Council members to anticipate shifts in procurement routing and supplier qualification thresholds.
Market Dynamics
Saudi Vision 2030 industrial localization mandates are redirecting procurement flows toward domestic and regional suppliers, compressing import dependency and rewiring competitive positioning across bonded and coated abrasive categories.
Growth Catalysts
- SASO Technical Regulations:Saudi Standards, Metrology and Quality Organization product safety benchmarks filter substandard imports, creating qualified supplier slots for compliant regional manufacturers.
- Construction intensity:Gulf state infrastructure programs expand concrete finishing and surface preparation demand, pulling bonded abrasives into high-volume deployment.
- Super abrasive adoption:Diamond and cubic boron nitride variants penetrate aerospace component finishing, anchoring premium positioning in precision applications.
Market Restraints
- Alumina and silicon carbide input volatility:Raw material price swings compress margin predictability for bonded abrasive producers serving steel and foundry operations.
- Asian supplier concentration:Substandard import filtering by ESMA and NRCS reveals persistent dependency on distant manufacturing clusters with elongated lead times.
- Technical substitution pressure:Laser cutting and waterjet systems displace mechanical grinding in thin-walled metal fabrication, constraining coated abrasive growth in precision segments.
Strategic Opportunities
- Kenya and Nigeria SME penetration:Automotive repair and woodworking micro-enterprises adopt flap disc and sandpaper formats, opening low-capital entry channels for coated abrasive distributors.
- ESMA conformity reciprocity:Emerging GCC certification mutual recognition agreements streamline multi-country market access for bonded abrasive suppliers qualifying through Dubai corridors.
- Asset-light leasing convergence:Precision grinding equipment rental models merge with consumable supply contracts, embedding abrasive vendors into captive usage cycles.
Industry Challenges
- Grinding wheel integrity certification:Bonded abrasive safety testing timelines stretch qualification periods for new product introductions, delaying revenue recognition.
- Legacy equipment integration:Retrofitting automated abrasive delivery systems into established metal fabrication lines demands capital coordination between tool OEMs and consumable suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Abrasives Market |
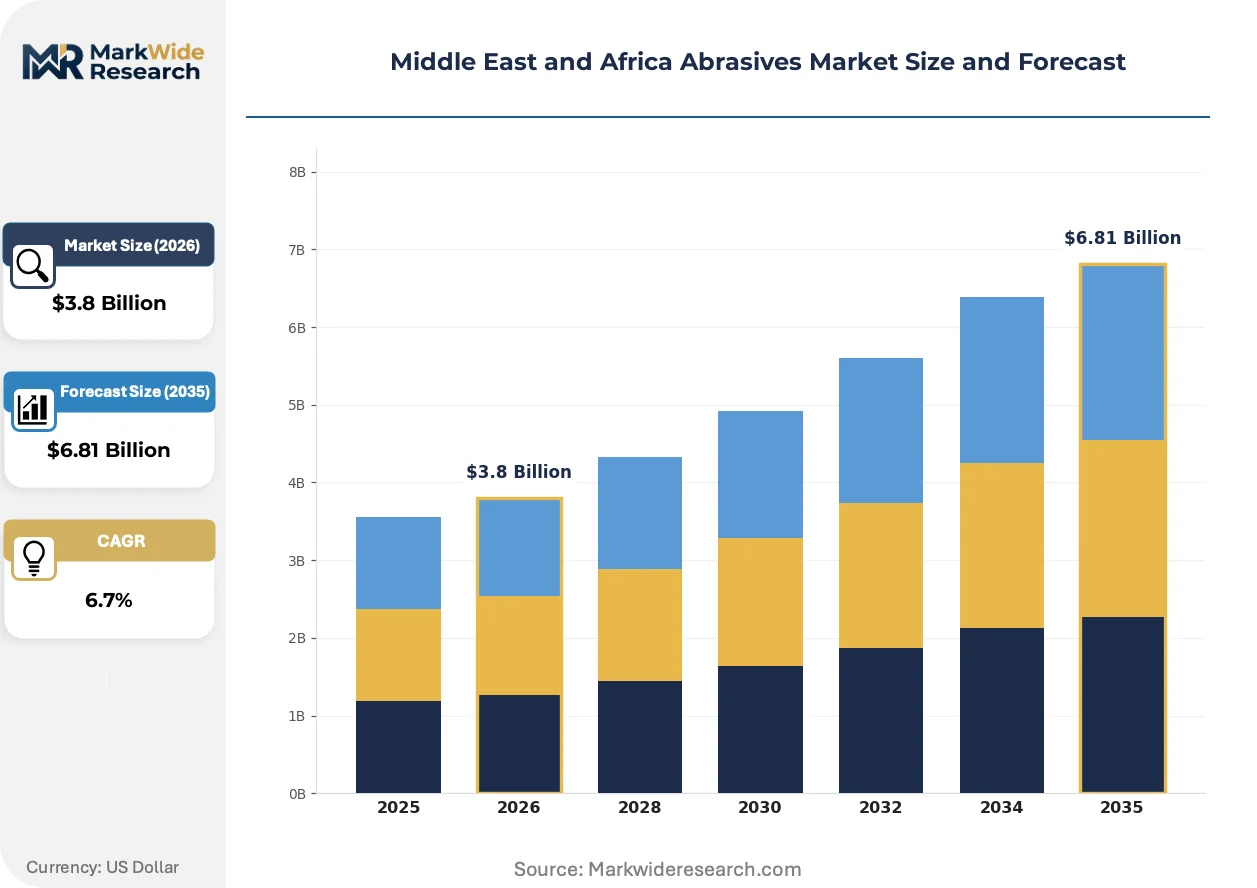
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Super Abrasives, Non-Woven Abrasives Material: Ceramic, Diamond, Silicon Carbide, Aluminum Oxide Application: Metalworking, Automotive, Woodworking, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Carborundum Universal Ltd., sia Abrasives, 3M, RHODIUS Abrasives GmbH, Robert Bosch GmbH, Saint-Gobain Abrasives, Weiler Abrasives, CUMI AWUKO Abrasives GmbH, Tyrolit Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Abrasives Market Shifts & Advancements
Digital specification tools and sustainability-linked procurement criteria are compressing traditional specification cycles and elevating traceability requirements across abrasive supply chains.
Engineered ceramic grain technology is migrating from aerospace turbine blade finishing into general metal fabrication. Tier-two Saudi and UAE machine shops adopt seeded-gel aluminum oxide formats at accelerating rates. The shift is migrating from premium-niche positioning toward volume-tier displacement of conventional fused alumina.
SASO technical regulations and South Africa's NRCS product safety mandates tighten bonded abrasive integrity standards. Import screening protocols now require batch-level test documentation. Coated abrasive flows through Dubai's Jebel Ali re-export hub face extended customs verification, compressing inventory velocity for non-compliant suppliers.
Specification authority is concentrating among Gulf-based procurement consortiums serving metal fabrication clusters. Individual machine shop purchasing autonomy is contracting as centralized buying desks negotiate multi-year abrasive supply frameworks. Kenya's emerging automotive repair chains replicate this consolidation, aggregating flap disc demand under single distributor relationships.
Middle East and Africa Abrasives Market Segmentation
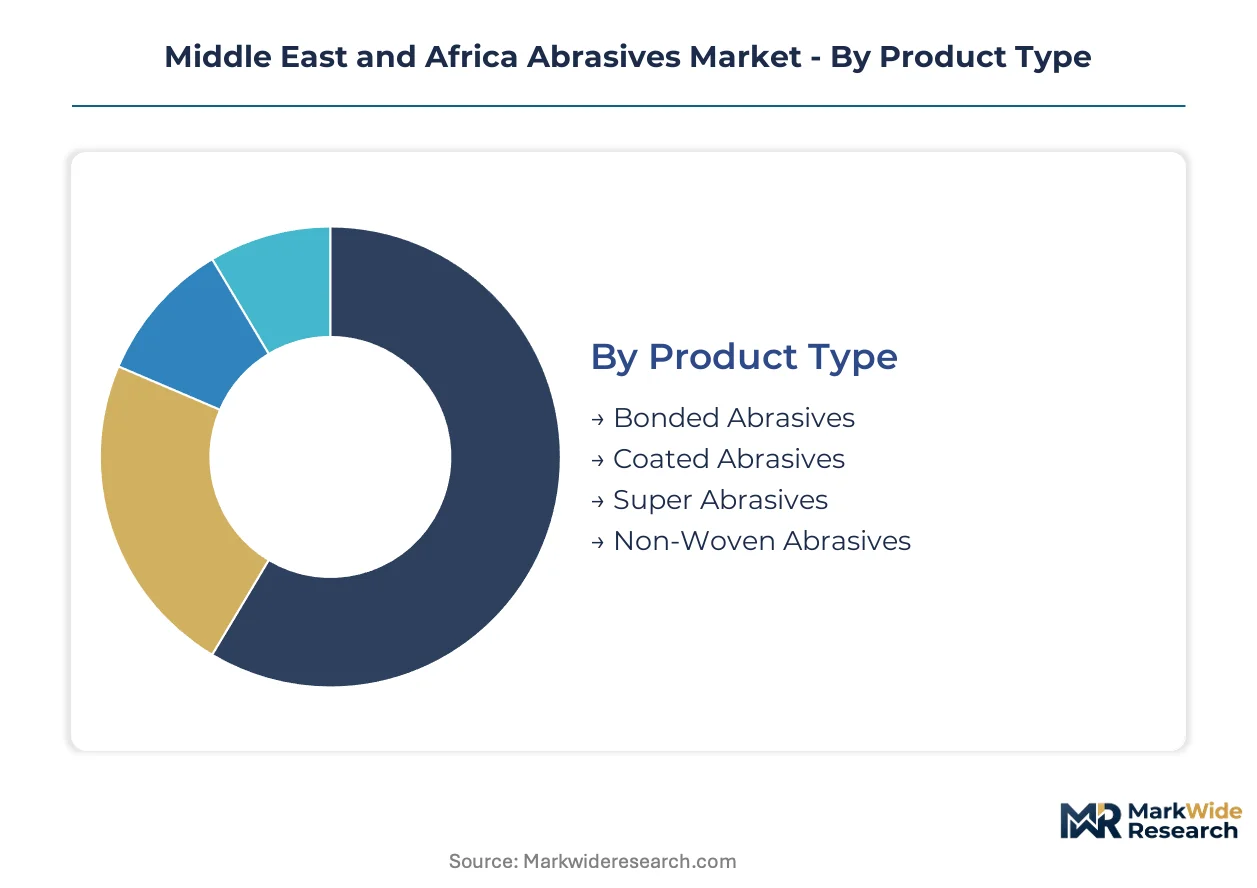
Abrasives procurement across the Middle East and Africa fragments along product chemistry, application intensity, and channel access. Segment boundaries determine margin capture, with bonded and super abrasive categories commanding premium positioning against commoditized coated alternatives.
Product Type:
Inventory velocity diverges sharply across product categories, with consumable flap discs turning in weeks while precision grinding wheels sit for months awaiting specification approval.
- Bonded Abrasives:Grinding wheels, cut-off discs, and sharpening stones fuse abrasive grains with vitrified or resinoid bonds. Saudi steel mills and UAE foundries anchor regional demand, though SASO batch-testing protocols stretch procurement cycles and compress distributor margins.
- Coated Abrasives:Sandpaper, flap discs, and abrasive belts adhere grains to flexible backings. Nigerian and Kenyan automotive repair micro-enterprises drive fastest inventory turnover, with flap disc formats penetrating at lowest capital entry.
- Super Abrasives:Diamond and cubic boron nitride variants serve aerospace finishing and precision tool sharpening.
- Non-Woven Abrasives:Surface conditioning wheels and hand pads blend nylon fibers with abrasive grit for burr removal.
Bonded abrasives anchors the volume base while coated abrasives gains share at the steepest rate.
Material:
Raw material tiering separates specification-grade ceramics from commodity fused oxides, with diamond commanding absolute premium positioning.
- Aluminum Oxide:Brown and white fused alumina variants dominate general-purpose grinding across Gulf metal fabrication. Price volatility in bauxite feedstocks compresses margin predictability for regional bonded abrasive producers.
- Silicon Carbide:Harder, sharper grains excel in glass, stone, and non-ferrous metal applications. Construction sector demand concentrates in UAE concrete surface preparation, where black silicon carbide formats penetrate at volume.
- Ceramic:Seeded-gel aluminum oxide technology migrates from aerospace into general fabrication.
- Diamond:Synthetic and natural diamond variants anchor super abrasive premium tiers.
Aluminum oxide supplies the widest application base while ceramic seeded-gel formats climb the fastest on performance substitution.
Application:
End-use concentration shapes abrasive specification authority, with metal fabrication procurement desks consolidating multi-year supply frameworks.
- Metalworking:Grinding, deburring, and finishing operations across Saudi and UAE steel service centers consume bonded abrasive volumes. Centralized procurement at Jebel Ali fabrication clusters compresses distributor negotiating leverage.
- Construction:Concrete grinding, surface preparation, and masonry cutting pull silicon carbide and diamond abrasives. Gulf state infrastructure programs accelerate coated abrasive deployment for floor finishing systems.
- Automotive:Collision repair and OEM finishing concentrate in South African assembly plants and Nigerian aftermarket chains.
- Woodworking:Furniture manufacturing and joinery operations across Kenya and Egypt drive coated abrasive sheet demand.
Metalworking commands the deepest specification integration while construction expands most quickly on infrastructure program acceleration.
Distribution Channel:
Channel structure determines market access velocity, with direct sales locking in captive usage cycles against distributor fragmentation.
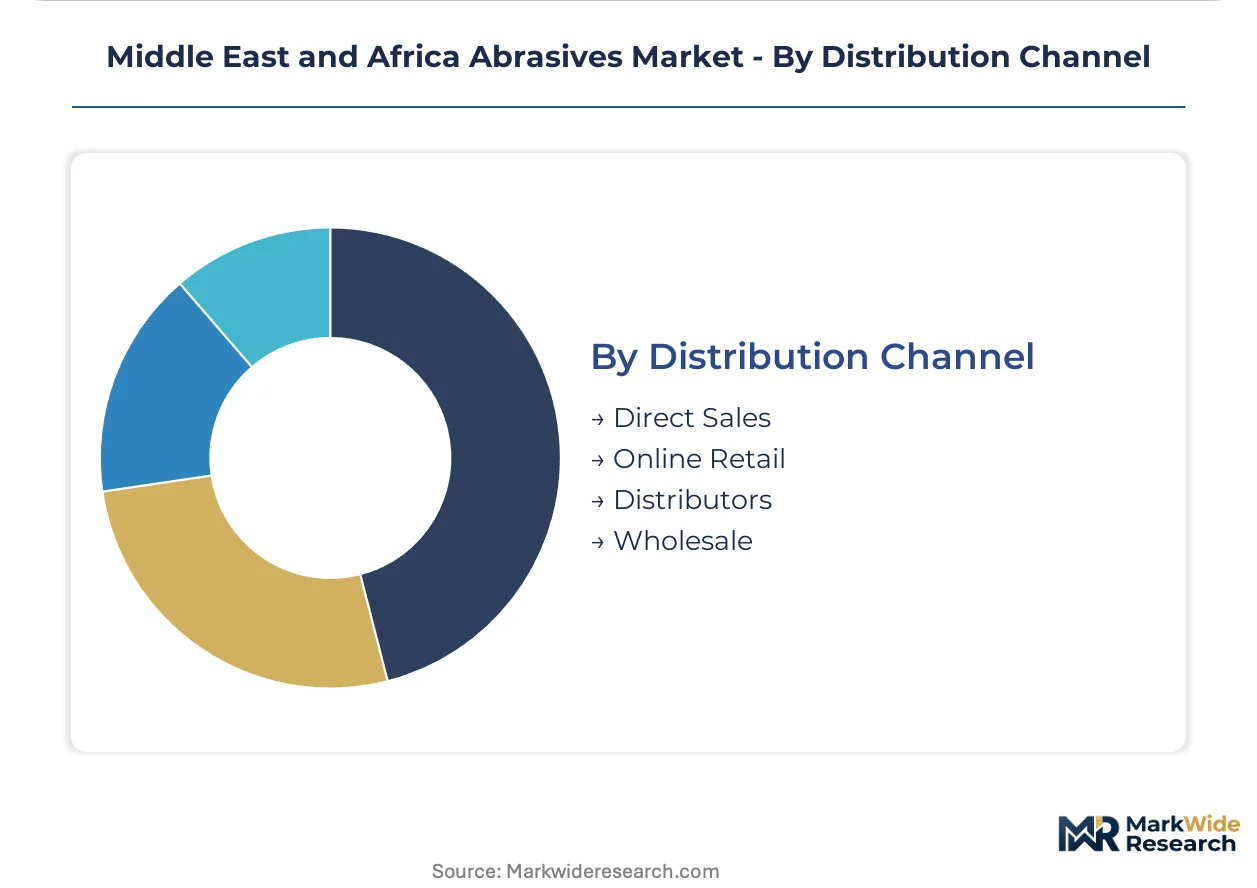
- Distributors:Industrial supply houses across Dubai, Jeddah, and Johannesburg aggregate fragmented demand from machine shops and repair facilities. ESMA conformity documentation requirements filter non-compliant Asian imports, compressing inventory breadth for smaller distributors.
- Direct Sales:Saint-Gobain and Robert Bosch deploy field technical teams to anchor multi-year supply contracts with Gulf fabrication clusters. Asset-light grinding equipment leasing bundles consumable supply into captive procurement relationships.
- Wholesale:Bulk procurement corridors through Jebel Ali re-export hubs serve African markets.
- Online Retail:E-commerce penetration concentrates in South African and UAE consumer-grade coated abrasives.
Distributors retain the widest geographic coverage while direct sales captures the steepest margin expansion on integrated equipment-consumable contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency across the Middle East and Africa abrasives sector is compressing as localization mandates redirect procurement flows toward regional suppliers, rewiring trade corridors that historically funneled Asian manufactured goods through Dubai's re-export hub.
Saudi Arabia
Steel mill expansion and foundry modernization under Vision 2030 industrial programs anchor bonded abrasive consumption. SASO technical regulations filter substandard imports, creating qualified supplier slots for compliant regional manufacturers. Eastern Province fabrication clusters concentrate procurement authority under centralized buying desks.
United Arab Emirates
Jebel Ali's manufacturing and re-export hub channels coated abrasive flows into African markets while local metal fabrication clusters consume precision grinding wheels. ESMA conformity assessment requirements shape market access protocols for bonded abrasive imports. Dubai-based procurement consortiums negotiate multi-year supply frameworks with integrated equipment vendors.
South Africa
Automotive assembly plants and mining equipment maintenance anchor super abrasive demand for precision tool sharpening. The National Regulator for Compulsory Specifications enforces product safety benchmarks that filter substandard imports. Gauteng Province steel service centers consolidate specification authority for bonded abrasive procurement.
Nigeria
Automotive repair micro-enterprises and emerging collision repair chains drive flap disc and sandpaper adoption at lowest capital entry. Import screening protocols compress inventory velocity for non-compliant Asian suppliers. Lagos-based distributor networks aggregate fragmented demand from informal sector workshops.
Kenya
Woodworking SMEs and furniture manufacturing operations adopt coated abrasive sheet formats for finishing applications. Automotive repair chains replicate Gulf procurement consolidation, aggregating demand under single distributor relationships. Nairobi industrial zones concentrate specification authority among centralized buying desks.
Middle East and Africa Abrasives Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: integrated multinational conglomerates with captive raw material sourcing, regional specialists leveraging geographic proximity, and Asian exporters competing on cost through Dubai's re-export corridors. Strategic archetypes include backward-integrated mineral processors, equipment-consumable ecosystem bundlers, and precision application specialists. Dominant competitive moves encompass multi-year supply contract anchoring with Gulf fabrication clusters and asset-light grinding equipment leasing models that embed consumable vendors into captive usage cycles.
Among European-headquartered conglomerates, Saint-Gobain Abrasives and Robert Bosch GmbH exemplify the integrated ecosystem archetype, while Carborundum Universal Ltd. represents regional specialists with upstream control over raw material sourcing. sia Abrasives and RHODIUS Abrasives GmbH occupy positions within the precision application tier, and 3M sits within the diversified materials science segment. Weiler Abrasives, CUMI AWUKO Abrasives GmbH, and Tyrolit Group exemplify mid-scale specialists competing through application-specific expertise rather than full portfolio breadth.
| Leading Market Players |
|---|
| Carborundum Universal Ltd. |
| sia Abrasives |
| 3M |
| RHODIUS Abrasives GmbH |
| Robert Bosch GmbH |
| Saint-Gobain Abrasives |
| Weiler Abrasives |
| CUMI AWUKO Abrasives GmbH |
| Tyrolit Group |
| Others |
Supply & Pricing Matrix
Jebel Ali port logistics corridors transmit freight cost volatility directly into abrasive pricing tiers, compressing margins for Dubai-based distributors while amplifying price differentiation between bonded wheel imports and locally warehoused coated consumables. Procurement consolidation among Gulf fabrication clusters concentrates negotiating leverage, forcing suppliers to absorb logistics swings or surrender volume slots to regional competitors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with super abrasive diamond formats commanding certification-grade premiums while commodity flap discs compete on volume scale. Price differentiation separates SASO-compliant bonded wheels from uncertified Asian imports, with ESMA documentation requirements adding compliance cost layers that filter economy-tier suppliers. Pricing pressure stems from raw material volatility in alumina and silicon carbide feedstocks, compressing margin predictability for regional producers. Automotive repair micro-enterprises in Nigeria and Kenya exhibit highest price sensitivity, prioritizing lowest capital entry over performance tier, while aerospace finishing operations in the UAE demonstrate lowest sensitivity due to specification-locked procurement frameworks.
Supply Chain Analysis
Export control regimes on synthetic diamond and cubic boron nitride super abrasive technologies limit technology transfer flows, constraining regional production capacity for precision grinding applications. Supply concentrates in China for coated abrasive backings and fused alumina grains, India for bonded abrasive resinoid bonds, and Germany for engineered ceramic grain technology. Raw material dependencies rest on bauxite for aluminum oxide, petroleum coke for silicon carbide, and synthetic diamond feedstocks for super abrasive tiers. Single-source vulnerability runs through Chinese coated abrasive manufacturers serving Dubai re-export corridors. Distribution runs through Jebel Ali wholesale hubs aggregating fragmented African demand alongside direct sales channels embedding consumable supply into equipment leasing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa abrasives market reads as a service-attach opportunity where precision grinding equipment leasing and consumable replenishment contracts expand faster than standalone abrasive sales, embedding vendors into captive recurring revenue cycles.
For Market Incumbents: Harden specification authority through multi-year supply frameworks with Jebel Ali fabrication clusters, anchoring bonded abrasive volumes against laser cutting substitution in thin-walled metal applications. Deepen backward integration into raw material sourcing across Southern Africa to buffer alumina price volatility and compress competitor margin room. Invest in SASO batch-testing infrastructure to accelerate qualification timelines and capture qualified supplier slots filtering Asian imports. For New Entrants and Emerging Players: Kenya's woodworking SME segment offers lowest competitive density for coated abrasive sheet penetration, with centralized buying desks at Nairobi industrial zones aggregating demand under single distributor relationships. Target Nigerian automotive repair chains replicating Gulf procurement consolidation patterns, offering flap disc formats at lowest capital entry with technical training attach. Pursue ESMA conformity reciprocity pathways to streamline multi-country market access through Dubai corridors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core abrasives divisions lacking regional localization capabilities. Long-term viability centers on suppliers with captive raw material sourcing and equipment-consumable bundling infrastructure. Monitor SASO technical regulation enforcement intensity as inflection indicator for qualified supplier slot availability and import substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive bauxite and silicon carbide supply buffers margin compression from feedstock volatility. |
| Asset-Light Grinding Equipment Leasing | Precision grinding rentals embed consumable vendors into captive usage cycles at Gulf fabrication clusters. |
| SASO Certification Infrastructure Investment | Accelerated batch-testing timelines capture qualified supplier slots filtering substandard Asian imports. |
| ESMA Conformity Reciprocity Expansion | Multi-country GCC certification mutual recognition streamlines bonded abrasive market access through Dubai. |
| Coated Abrasive Distribution Network Buildout | Lagos and Nairobi hub expansion aggregates fragmented SME demand from informal sector workshops. |
Research Methodology
A spread of perspectives from plant engineers at Saudi steel mills, procurement leads at UAE fabrication clusters, distribution channel partners across Dubai and Johannesburg, and aftermarket service heads at automotive repair chains converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, SASO technical regulation filings, ESMA conformity assessment records, and SEC 10-K disclosures from listed abrasive manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling product type segmentation across bonded, coated, super, and non-woven categories alongside material tier, application intensity, and channel access dimensions. End-use concentration in metal fabrication, construction, automotive, and woodworking shaped volume allocation. CAGRs derived from historical trajectory analysis adjusted for localization policy intensity, infrastructure program acceleration, and substitution technology penetration rates. Alumina and silicon carbide input cost curves, together with certification reciprocity agreement momentum, fed industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported abrasive exporters or accelerated laser cutting adoption in Gulf metal fabrication would shift outcomes. Material shifts in Saudi Vision 2030 localization enforcement intensity or ESMA-NRCS regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Tungsten Carbide Powder Market
Abrasives
Synthetic Abrasives Market
Abrasives
Vitrified Bonded Grinding Wheels Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
North America Abrasives Market
Abrasives
Super Abrasives Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Bonded Abrasive Market
Abrasives
Chemical Deflasher Market
Abrasives
Abrasive Grains Market
Abrasives
Abrasive Tools Market
Abrasives
RDP Powder Market
Abrasives
Polishing Powder Market
Abrasives
Abrasive Base Paper Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market