
 Carborundum Market | 2026-2036
Carborundum Market Size, Share, and Industry Trends Forecast 2026-2036
Carborundum Market Intelligence
A shift from multi-sourcing toward strategic single-supplier partnerships for high-purity grades is repositioning competitive positioning. This trend favors large-scale producers with verified quality control systems. Saint-Gobain Ceramics Materials GmbH leverages its global manufacturing footprint, while KYOCERA Corporation specializes in advanced ceramic applications. Carborundum Universal Ltd anchors its position through a diversified product portfolio serving multiple industrial end-uses.
Carborundum, or silicon carbide (SiC), is a synthetic compound of silicon and carbon known for its extreme hardness, approaching 9.5 on the Mohs scale. It is produced at high temperatures through the Acheson process. Among product types, Black Silicon Carbide constitutes the bulk of material used in abrasives and refractories. The high-purity Green Silicon Carbide segment, while smaller in volume, commands premium pricing due to its essential role in electronics.
Market access and product specifications are governed by a multi-jurisdictional regulatory landscape. The EU’s REACH regulation controls chemical substances, while US OSHA standards mandate workplace safety regarding abrasive dust exposure. China's GB standards define material quality for domestic use. Navigating these varied compliance requirements is a critical operational task for producers and exporters.
Market Dynamics
The market's central dynamic is the divergence between the high-volume, cost-sensitive black silicon carbide segment and the high-purity, technology-driven green silicon carbide segment. This bifurcation influences everything from investment priorities to supply chain structures and regulatory compliance strategies.
Growth Catalysts
- Electric Vehicle Powertrains:The use of silicon carbide in inverters and on-board chargers for electric vehicles improves energy efficiency and reduces charging times, directly driving demand for high-purity SiC wafers and power modules.
- China's Industrial Policy:Government support for semiconductor self-sufficiency and the expansion of renewable energy infrastructure under China's dual carbon goals stimulates massive domestic production and consumption of all grades of carborundum.
- Aerospace Material Science:Demand from the aerospace and defense sectors for materials that offer high strength-to-weight ratios and thermal stability is expanding the use of SiC in ceramic matrix composites and protective coatings.
Market Restraints
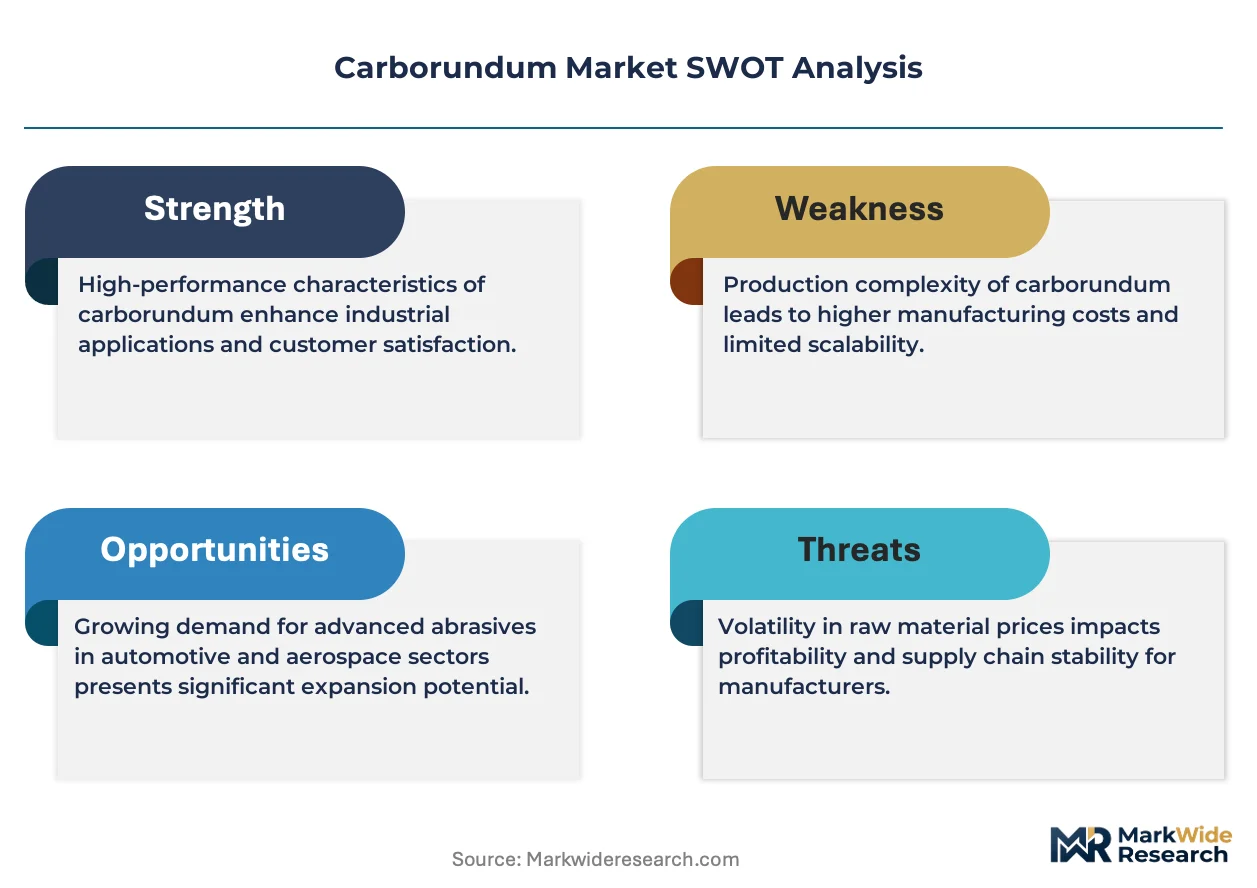
- Energy-Intensive Production:The Acheson process, the primary method for SiC synthesis, is extremely energy-intensive, making production costs highly vulnerable to fluctuations in global electricity prices and carbon taxes.
- Supply Chain Concentration:A heavy concentration of global black silicon carbide production within China exposes the market to geopolitical risks, trade policy shifts, and potential supply disruptions for downstream industries.
- Wafer Manufacturing Complexity:The technical difficulty and high cost of growing large, defect-free single-crystal SiC boules limit the yield and scalability of wafer production, constraining supply for the electronics sector.
Strategic Opportunities
- Hydrogen Economy Components:SiC's excellent thermal and chemical resistance creates opportunities for its use in components for hydrogen production, such as high-temperature electrolysis systems, and in advanced fuel cell technologies.
- Energy Efficiency Mandates:Regulations like the EU Green Deal and US efficiency standards for electronics and industrial motors create a powerful incentive for manufacturers to adopt more efficient SiC-based power components.
- Advanced Composite Materials:The convergence of SiC fibers with polymer or metal matrices opens new applications in lightweight structural components for automotive, industrial, and recreational equipment where durability is paramount.
Industry Challenges
- Capital Investment Hurdles:The substantial capital required to construct new, efficient Acheson furnace plants or advanced SiC crystal growth facilities presents a significant barrier to entry and capacity expansion for many producers.
- Multi-Jurisdictional Compliance:Manufacturers face operational complexity in managing compliance across differing international standards, such as the EU's REACH chemical safety rules and US OSHA workplace dust exposure limits.
- Specialized Talent Scarcity:A shortage of material scientists and process engineers with deep expertise in high-purity SiC synthesis and wafer processing hinders innovation and the optimization of production yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carborundum Market |
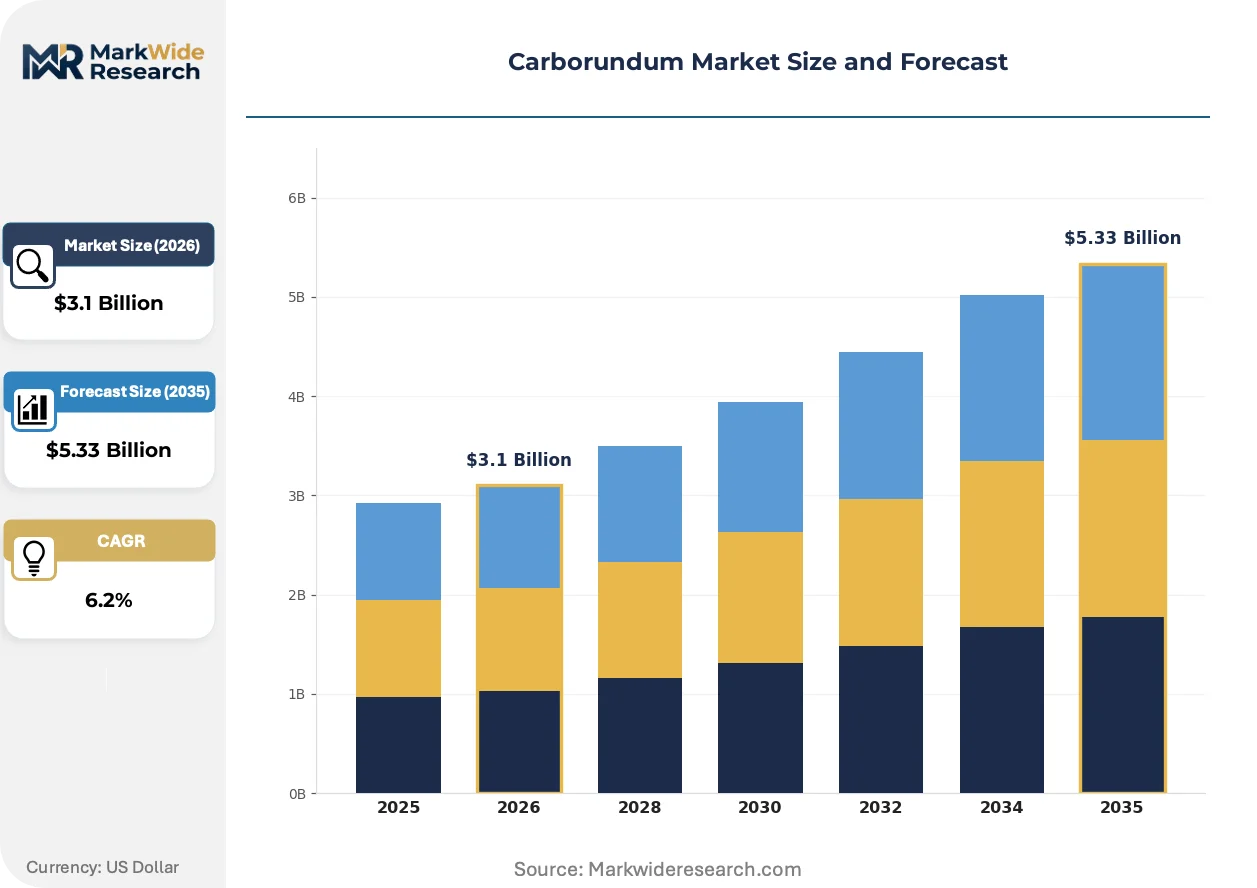
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.33 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Silicon Carbide, Green Silicon Carbide, Brown Silicon Carbide, Synthetic Carborundum Application: Abrasives, Refractories, Ceramics, Metallurgy, Electronics End User: Foundries, Construction Materials, Chemical Processing, Electronics Manufacturing Packaging Type: Bag, Bulk, Box, Drum |
| Companies Covered | KYOCERA Corporation, AGSCO Corporation, ESK-SIC GmbH, The Dow Chemical Company, Xiamen Powerway Advanced Material Company Limited, Saint-Gobain Ceramics Materials GmbH, Grindwell Norton Ltd, Entegris Inc., Carborundum Universal Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carborundum Market Strategic Shifts & Innovations
The carborundum market's evolution is defined by a technological push into advanced electronics, which is creating a distinct, high-value segment separate from its traditional industrial abrasives base. This specialization is forcing a re-evaluation of quality control, supply chain partnerships, and material science innovation.
Silicon carbide wafer technology provides a superior substrate for manufacturing high-power, high-frequency semiconductor devices compared to traditional silicon. The electric vehicle, 5G telecommunications, and renewable energy sectors are rapidly adopting these advanced substrates to improve system performance and energy efficiency. This technology is integrating advanced power management capabilities directly into systems that were previously reliant on larger, less efficient silicon-based components.
The EU’s REACH regulation imposes stringent requirements for the registration and documentation of chemical substances sold within the European market. This mandate directly impacts carborundum producers, forcing them to provide extensive data on material properties and potential hazards. The high-purity green silicon carbide segment is most affected, as suppliers must invest in costly testing and transparent supply chain tracking to gain access to the critical European electronics industry.
A shift from short-term, price-driven purchasing to strategic, long-term supply agreements is altering procurement patterns for high-purity grades. This trend sees semiconductor and EV power module manufacturers locking in supply to ensure quality consistency and availability, displacing the more volatile spot market. This behavior is most visible among major electronics and automotive firms in Germany, Japan, and the United States, who prioritize supply chain stability above all else.
Carborundum Market Segmentation
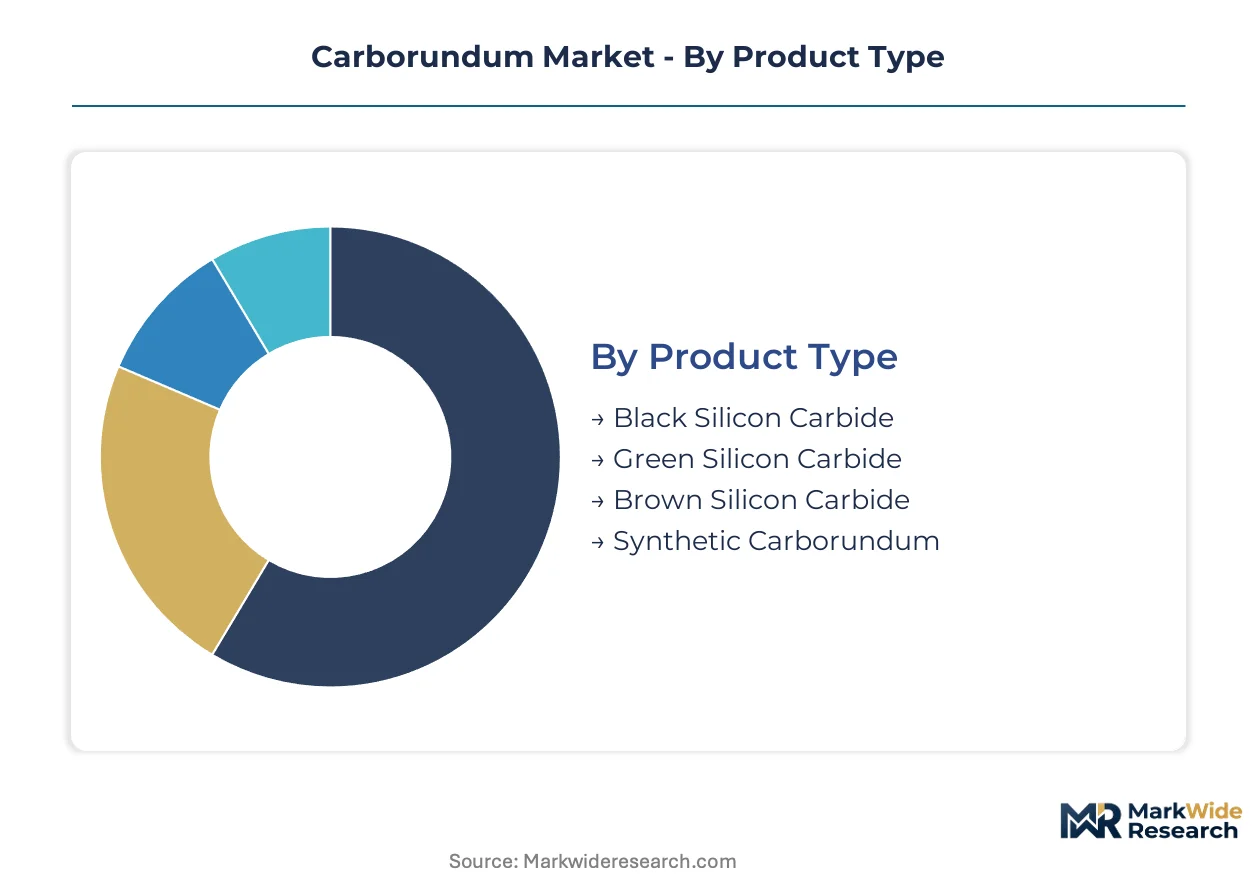
The carborundum market's segmentation reflects distinct material properties and specialized end-use requirements, influencing production processes and supply chain configurations. Understanding these divisions is critical for producers to align product development with specific industry demands and regulatory frameworks. Each segment presents unique challenges and opportunities for market participants.
Product Type:
Navigating the varied regulatory landscape is paramount, with specific product types requiring distinct certifications for market access in jurisdictions like the EU and China.
- Black Silicon Carbide:This material is primarily produced through the Acheson process, characterized by its high hardness and cost-effectiveness. Demand remains robust in traditional abrasive applications and refractory linings across industrial sectors, particularly in China's heavy manufacturing base.
- Green Silicon Carbide:Distinguished by its high purity and crystalline structure, this segment commands premium pricing due to its essential role in advanced electronics. Its superior electrical properties are driving adoption in power modules for electric vehicles in Germany and Japan.
- Brown Silicon Carbide:An intermediate grade, brown silicon carbide offers a balance of abrasive properties and cost, finding application in less demanding abrasive tasks. This product type is widely used in general industrial grinding and polishing.
- Synthetic Carborundum:This term encompasses the broader category of industrially produced silicon carbide, often referring to various grades used across diverse sectors. It serves as a foundational material for many industrial processes.
Leading the category by volume: Black Silicon Carbide. Growing fastest: Green Silicon Carbide.
Application:
The functional requirements of specific applications heavily influence the required purity and grain size of carborundum, impacting production complexity and pricing structures.
- Electronics:This application demands ultra-high purity green silicon carbide for semiconductor substrates and power devices, particularly in the 5G telecommunications and electric vehicle sectors. Silicon carbide wafers enable more efficient power conversion and higher operating temperatures.
- Abrasives:Carborundum's extreme hardness makes it ideal for grinding wheels, sandpaper, and blasting media across metalworking and construction. Black silicon carbide dominates this high-volume, cost-sensitive segment.
- Refractories:In high-temperature industrial furnaces and kilns, silicon carbide bricks and shapes offer exceptional thermal shock resistance and chemical inertness. Steel and ceramics production facilities in Europe rely on these properties.
- Ceramics:Silicon carbide is a key component in advanced technical ceramics, valued for its strength, wear resistance, and thermal stability in extreme environments. Automotive and aerospace components increasingly utilize SiC ceramics.
- Metallurgy:Used as a deoxidizer and an additive in iron and steel production, carborundum enhances material properties and refines grain structure. Foundries in the United States incorporate it for improved casting quality.
Electronics applications are driving value creation, while abrasives maintain significant volume.
End User:
Specific end-user industries dictate the scale of procurement, required product specifications, and the long-term strategic partnerships formed within the carborundum market.
- Electronics Manufacturing:This sector requires stringent quality control and high-purity green silicon carbide for semiconductor fabrication and power electronics. Manufacturers in South Korea and Taiwan are key consumers.
- Foundries:Primarily consuming black silicon carbide for abrasives and refractories, foundries represent a mature, volume-driven segment. Metal casting operations in India depend on consistent supply.
- Construction Materials:Carborundum is utilized in various construction applications, including abrasive tools and wear-resistant concrete additives. Infrastructure projects globally incorporate these materials.
- Chemical Processing:The chemical industry uses silicon carbide for its corrosion resistance and thermal stability in harsh environments, such as heat exchangers and specialized filtration systems.
Electronics Manufacturing exhibits the highest growth potential, whereas Foundries represent consistent demand.
Packaging Type:
Logistical efficiency and end-user handling requirements primarily determine the choice of packaging type, influencing transportation costs and storage solutions.
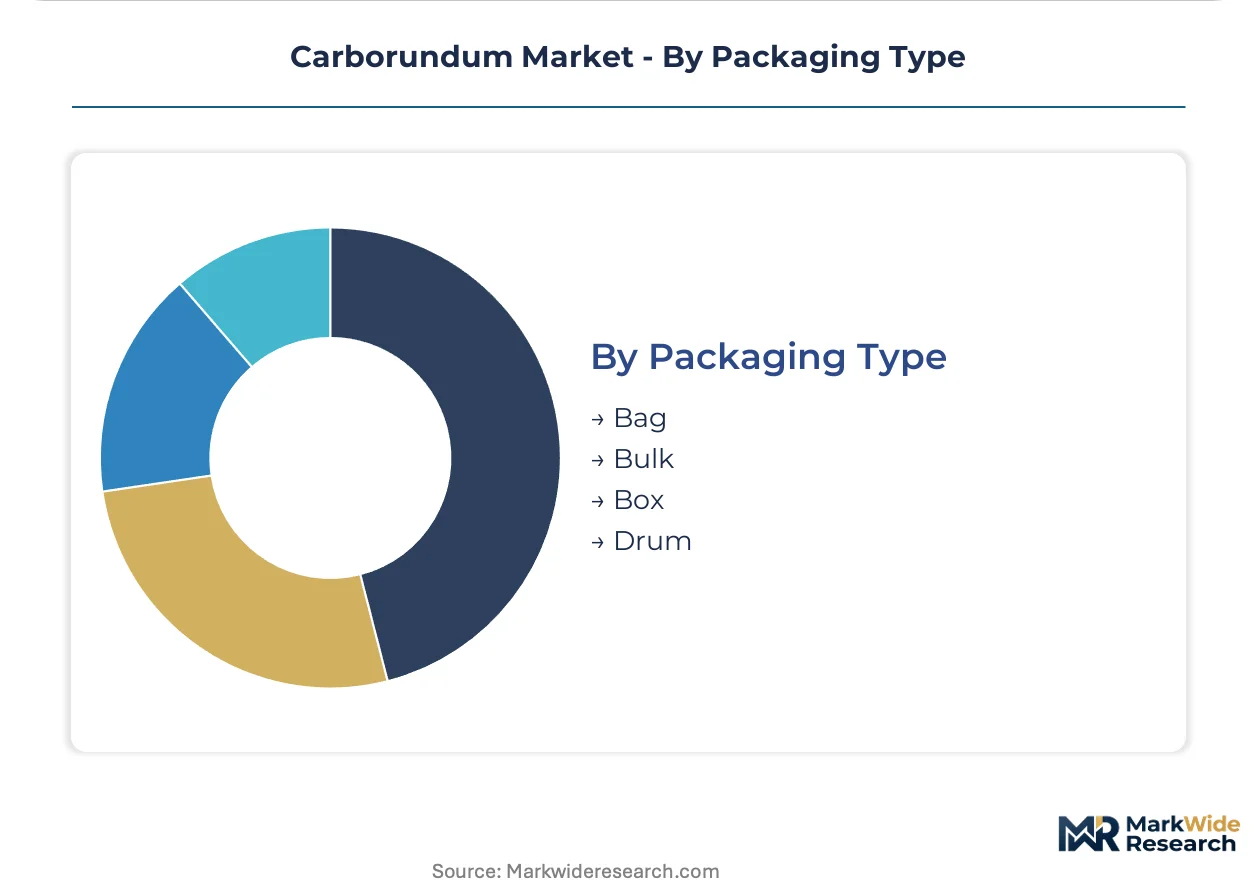
- Bag:Standard bag packaging is common for smaller quantities of carborundum, suitable for end-users with moderate consumption or specialized applications. This method facilitates easier manual handling.
- Bulk:Large-scale industrial users, such as foundries and refractory manufacturers, procure carborundum in bulk to minimize packaging waste and reduce unit costs. Bulk shipments are typical for high-volume orders.
- Box:Box packaging offers protection for more refined or fragile grades of carborundum, often used for smaller, higher-value shipments. This format is common for specialized abrasives.
- Drum:Drums provide a robust and secure packaging solution for various grades of carborundum, particularly when moisture protection or enhanced durability during transit is required.
Bulk packaging dominates industrial distribution, with Bag packaging serving smaller-scale requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast industrial base anchors the global carborundum market, influencing both production volumes and consumption patterns. Global demand for both black and green silicon carbide influences regional market dynamics. Specific national policies and technological advancements shape local market growth across key geographies.
China
Demand for carborundum stems from China's semiconductor self-sufficiency goals and its expanding renewable energy infrastructure. The nation's dual carbon goals stimulate massive domestic production and consumption of all carborundum grades. The Yangtze River Delta region drives electronics manufacturing and heavy industrial base expansion, integrating carborundum into numerous applications.
Germany
Electric vehicle power electronics and advanced ceramic applications generate significant demand for high-purity silicon carbide in Germany. The EU’s REACH regulation imposes stringent requirements for chemical substances, impacting carborundum producers accessing European markets. Bavaria supports automotive and high-tech manufacturing, driving innovation in SiC-based components.
United States
Metallurgy applications, foundry operations, and aerospace materials propel carborundum demand in the United States. US OSHA standards mandate workplace safety regarding abrasive dust exposure, influencing production and handling practices. Industrial centers in the Midwest integrate carborundum into steel production and advanced manufacturing processes.
Japan
High-purity green silicon carbide for EV power modules and advanced electronics drives market value in Japan. The Ministry of Economy, Trade and Industry (METI) supports advanced materials research and development, fostering SiC innovation. The Kansai region focuses on semiconductor and automotive component innovation, utilizing specialized carborundum grades.
South Korea
Electronics manufacturing and 5G telecommunications infrastructure require high-purity silicon carbide in South Korea. Government support for the semiconductor industry encourages domestic production and advanced material adoption. Gyeonggi Province leads semiconductor fabrication and display technologies, consuming substantial volumes of green silicon carbide.
Carborundum Market Key Industry Players
Capacity expansion dominates the current landscape, reflecting substantial investments in advanced SiC crystal growth facilities. This tiered market structure favors large-scale integrated producers with verified quality control systems. Strategic archetypes include integrated materials companies, specialized high-purity suppliers, and regional industrial suppliers. Capacity expansion and strategic partnerships are the dominant competitive moves influencing market dynamics.
Specialists in advanced ceramic applications like KYOCERA Corporation focus on high-performance materials and components. Saint-Gobain Ceramics Materials GmbH leverages its global manufacturing footprint to serve diverse industrial sectors. Carborundum Universal Ltd anchors its position through a diversified product portfolio, catering to multiple industrial end-uses across various grades.
| Leading Market Players |
|---|
| KYOCERA Corporation |
| AGSCO Corporation |
| ESK-SIC GmbH |
| The Dow Chemical Company |
| Xiamen Powerway Advanced Material Company Limited |
| Saint-Gobain Ceramics Materials GmbH |
| Grindwell Norton Ltd |
| Entegris Inc. |
| Carborundum Universal Ltd |
| Others |
Cost & Logistics Intelligence
Specialized workforce concentration in high-purity silicon carbide processing in Japan and Germany influences pricing-tier spreads, reflecting the scarcity of highly skilled labor and advanced technical expertise. This dynamic creates distinct value propositions across different carborundum grades.
Pricing Analysis
Warranty-bundled service contracts often accompany high-purity green silicon carbide sales, distinguishing them from commodity black silicon carbide. The dominant pricing model is contract-based long-term offtake for premium grades, while transactional per-unit sales prevail for industrial grades. Price differentiation stems from certification level, such as SEMI standards for electronics, and the customization level for specific applications. Pricing softness for black silicon carbide stems from oversupply within China. Electronics manufacturers exhibit low price sensitivity for high-purity grades, unlike foundries which are highly price-sensitive.
Supply Chain Analysis
High-purity silicon carbide wafer supply rests on advanced crystal growth facilities primarily located in Japan, Germany, and the United States. Raw material dependencies include high-purity silica and specific carbon sources. A structural risk is single-source vulnerability for specialized processing equipment. Distribution runs through direct sales channels for high-purity materials and bulk logistics for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carborundum market represents a vertical-integration race, with producers pursuing upstream control over high-purity silicon feedstock. This strategic imperative aims to secure essential raw materials for advanced electronics applications.
For Market Incumbents: Hedge against commodity price volatility by securing long-term power purchase agreements for Acheson furnace operations. Expand high-purity green silicon carbide capacity in Europe to mitigate geopolitical supply risks from China. The threat of new entrants with advanced crystal growth technologies necessitates continuous R&D investment in defect-free boule production.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for specialized SiC component manufacturers focusing on energy efficiency. Target the underserved market for hydrogen economy components, leveraging SiC's thermal and chemical resistance. A direct-to-OEM sales model for custom SiC parts in aerospace material science offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated specialty chemical producers given rising demand from electric vehicle powertrains. The long-term viability favors companies with proprietary crystal growth technologies and strong intellectual property in SiC wafer processing. Acquisition targets include mid-sized firms with verified quality control systems for high-purity SiC. The signal to watch is successful commercialization of 8-inch SiC wafers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Green SiC | Increases availability of critical material for electric vehicle power modules and 5G telecommunications. |
| Long-term Supply Agreements with OEMs | Secures stable demand for high-purity grades from major electronics and automotive firms. |
| R&D Investment in Crystal Growth | Reduces defect rates and increases wafer size, improving yield for semiconductor fabrication. |
| Strategic Partnerships for Raw Materials | Mitigates supply chain risks and ensures consistent quality of high-purity silica inputs. |
| Certification for New Applications | Opens market access for SiC in emerging sectors like hydrogen economy components and advanced composites. |
Research Approach
Document review covered national trade statistics, industry association reports, and company financial disclosures, complemented by interviews with material scientists, procurement leads at EV manufacturers, and foundry operations managers. This approach combined primary insights with secondary validation, employing both bottom-up market sizing and top-down revenue analysis.
Historical market data was cross-referenced with expert panel input to build the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and regional production capacity. Compound Annual Growth Rates were derived from an assessment of demand drivers and supply-side constraints. Key forecast inputs included electric vehicle production targets and semiconductor fabrication expansion plans.
The model assumes a particular technology adoption path for silicon carbide in power electronics; alternative pathways for gallium nitride would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Liquid Sandpaper Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Metal Abrasives Market
Abrasives
Polishing Chemicals Market
Abrasives
Boron Carbide Market
Abrasives
Sandblaster Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Vitrified Bonded Grinding Wheels Market
Abrasives
Grinding Wheels Market
Abrasives
Abrasive Cloth Market
Abrasives
Europe Abrasives Market
Abrasives
North America Abrasives Market
Abrasives
Middle East and Africa Abrasives Market
Abrasives
Coated Abrasives Market