
 RDP Powder Market | 2026-2036
RDP Powder Market Size, Share, and Industry Trends Forecast 2026-2036
RDP Powder Market Intelligence
CE marking under the EU Construction Products Regulation is bifurcating the competitive landscape into certified suppliers and regional aspirants. Wacker Chemie AG leverages its integrated silicone and polymer platform to sustain premium positioning across European specification markets. BASF SE anchors volume supply through backward integration into vinyl acetate monomer and captive emulsion polymerization capacity. Organik Kimya competes on cost-engineered styrene-acrylic grades for Middle Eastern and African export channels.
Redispersible polymer powder consists of spray-dried polymer emulsions, typically vinyl acetate-ethylene or styrene-acrylic copolymers with protective colloids, that re-disperse in water to restore original film-forming properties. The material functions primarily as a cement modifier, improving adhesion, flexural strength, and workability in dry-mix mortars, tile adhesives, and self-leveling compounds. Styrene-acrylic formulations command the widest construction application footprint due to hydrophobicity and alkali resistance, while ethylene-vinyl acetate grades retain cost advantages in emerging-market tile adhesive formulations. Industrial grade products dominate volume, though margin pools concentrate in construction-specified polymerized vinyl acetate variants meeting freeze-thaw durability standards.
REACH registration requirements in Europe and China's GB/T standards for cement admixtures constrain market entry for uncertified producers, elevating compliance costs but protecting incumbent positions. The US EPA and state-level air quality regulations on emulsion plant emissions further shape manufacturing location decisions for suppliers serving North American construction markets. Stakeholders must monitor evolving green building certification criteria and low-VOC mandates, as these will determine which polymer chemistries retain specification access across priority geographies.
Market Dynamics
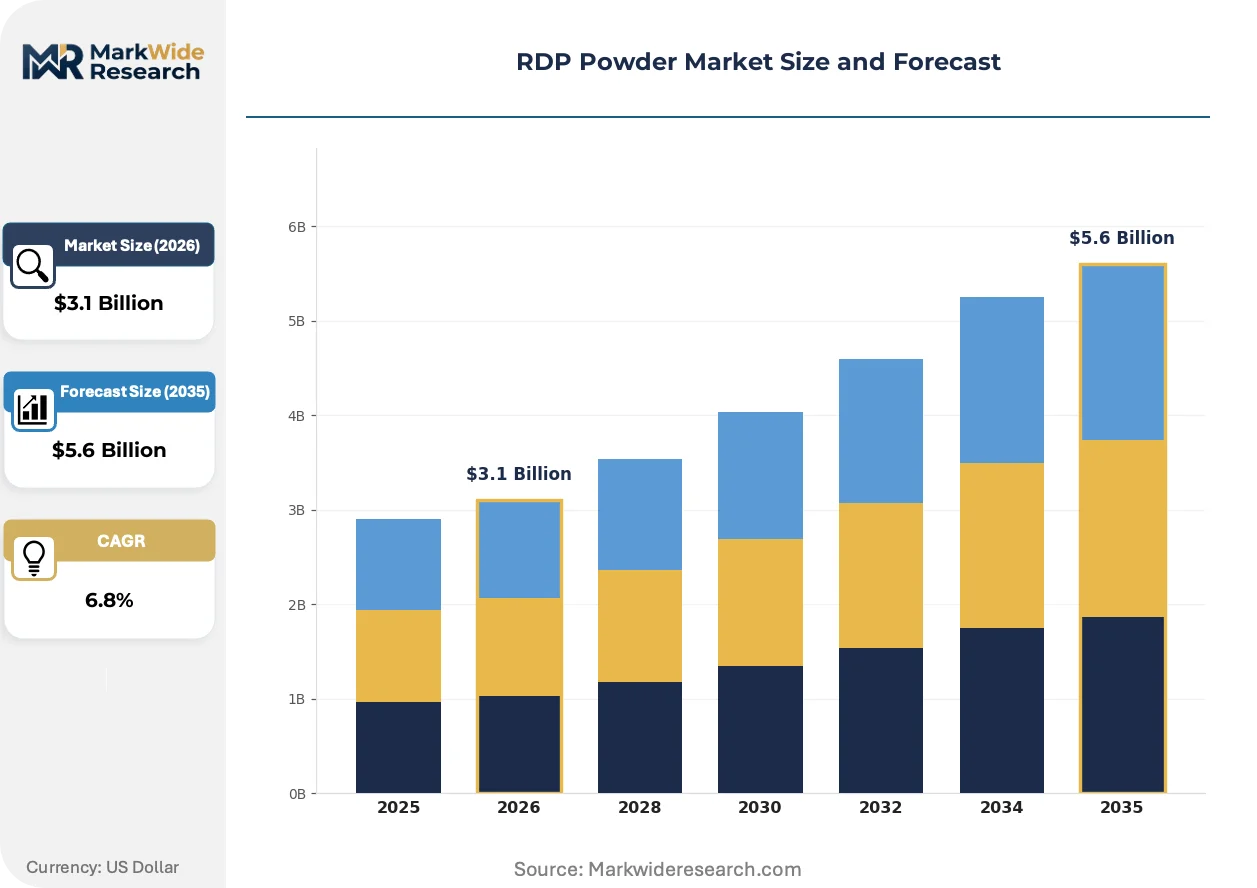
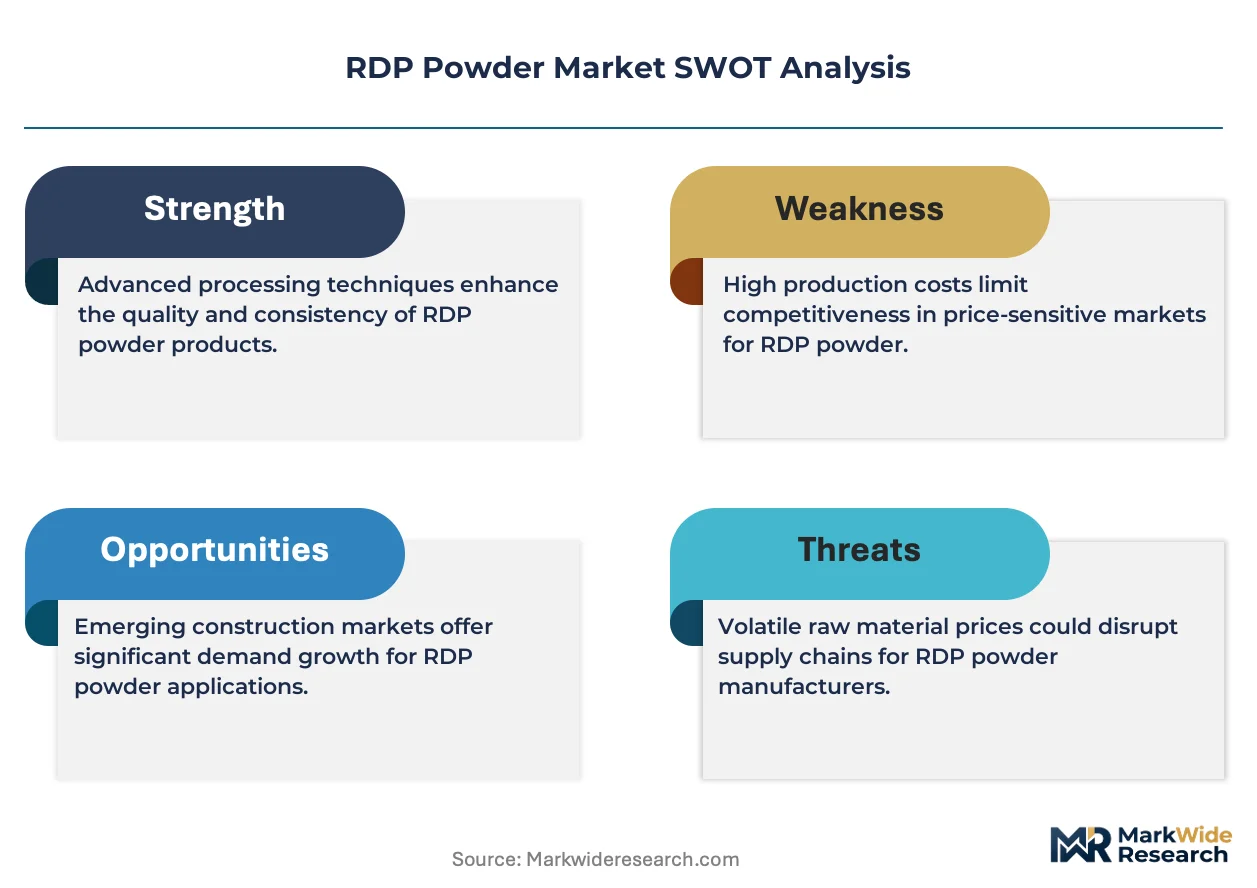
REACH compliance costs and China's GB/T cement admixture standards are compressing supplier margins while consolidating specification access among certified producers with captive emulsion capacity.
Growth Catalysts
- European low-VOC mandates:ECHA restrictions on solvent-based alternatives are redirecting dry-mix mortar formulation toward redispersible polymer powders in renovation and new-build applications.
- China's coastal manufacturing clusters:Zhejiang and Jiangsu province construction chemical hubs are driving specification-grade vinyl acetate-ethylene consumption for high-rise tile adhesive systems.
- Freeze-thaw durability requirements:North American building codes for exterior insulation and finish systems are mandating polymer-modified cementitious layers in cold-climate zones.
Market Restraints
- Vinyl acetate monomer volatility:Feedstock price swings tied to ethylene and acetic acid markets compress margin predictability for non-integrated compounders.
- Styrene supply concentration:Asian petrochemical complexes control over 60% of global styrene monomer output, creating geographic dependency for styrene-acrylic grade producers.
- Alkali resistance thresholds:High-pH cement environments degrade ethylene-vinyl acetate film integrity, limiting substitution potential in demanding substrate applications.
Strategic Opportunities
- India's western industrial corridor:Gujarat and Maharashtra state infrastructure programs are accelerating dry-mix mortar plant commissioning, creating specification-grade polymer demand.
- Self-leveling underlayment expansion:Commercial flooring renovation cycles in mature markets are consuming higher polymer loadings for rapid-setting compound performance.
- EU Green Deal embodied carbon tracking:Construction product environmental performance declarations are favoring bio-based protective colloid formulations in premium specification tiers.
Industry Challenges
- Spray-drying energy intensity:Natural gas-fired atomization systems face carbon cost pass-through pressures under EU ETS and emerging Asian carbon pricing schemes.
- CE marking timeline compression:Construction Products Regulation factory production control audits require 12-18 month certification cycles that delay market entry for reformulated chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RDP Powder Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerized Vinyl Acetate, Ethylene-Vinyl Acetate, Styrene-Acrylic, Others Application: Construction, Adhesives, Coatings, Textiles End User: Manufacturers, Contractors, Retailers, Distributors Grade: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade |
| Companies Covered | Dow Inc., Dairen Chemical Corporation, Wacker Chemie AG, Arkema S.A., Ashland Inc., BASF SE, Synthomer plc, Organik Kimya, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RDP Powder Market Strategic Shifts & Innovations
Formulation science and regulatory disclosure requirements are splitting competitive advantage between integrated petrochemical platforms and specialized compounding operations.
Low-emission vinyl acetate-ethylene copolymers with bio-based protective colloids are replacing conventional styrene-acrylic grades in interior dry-mix applications. German and Dutch construction chemical formulators are specifying these systems for school and healthcare projects with stringent indoor air quality protocols. The technology is bifurcating specification access between premium certified suppliers and commodity-grade regional producers lacking environmental product declaration coverage.
ECHA's expanding SVHC candidate list is forcing reformulation of residual monomer content in spray-dried emulsions. Industrial consequence includes accelerated R&D spending on post-polymerization stripping technologies and alternative protective colloid chemistries. Styrene-acrylic grades targeting exterior facade applications face the highest substitution pressure as downstream customers pre-empt regulatory listing with proactive chemistry switches.
Large-scale construction chemical distributors are consolidating procurement volumes through direct mill relationships, bypassing traditional polymer powder trading intermediaries. This channel compression is most visible in China's Yangtze River Delta, where provincial dry-mix mortar associations negotiate collective polymer supply agreements. Tier-two formulators now face working capital constraints as payment terms compress from 90 days to 45 days under distributor-direct models.
RDP Powder Market Segmentation
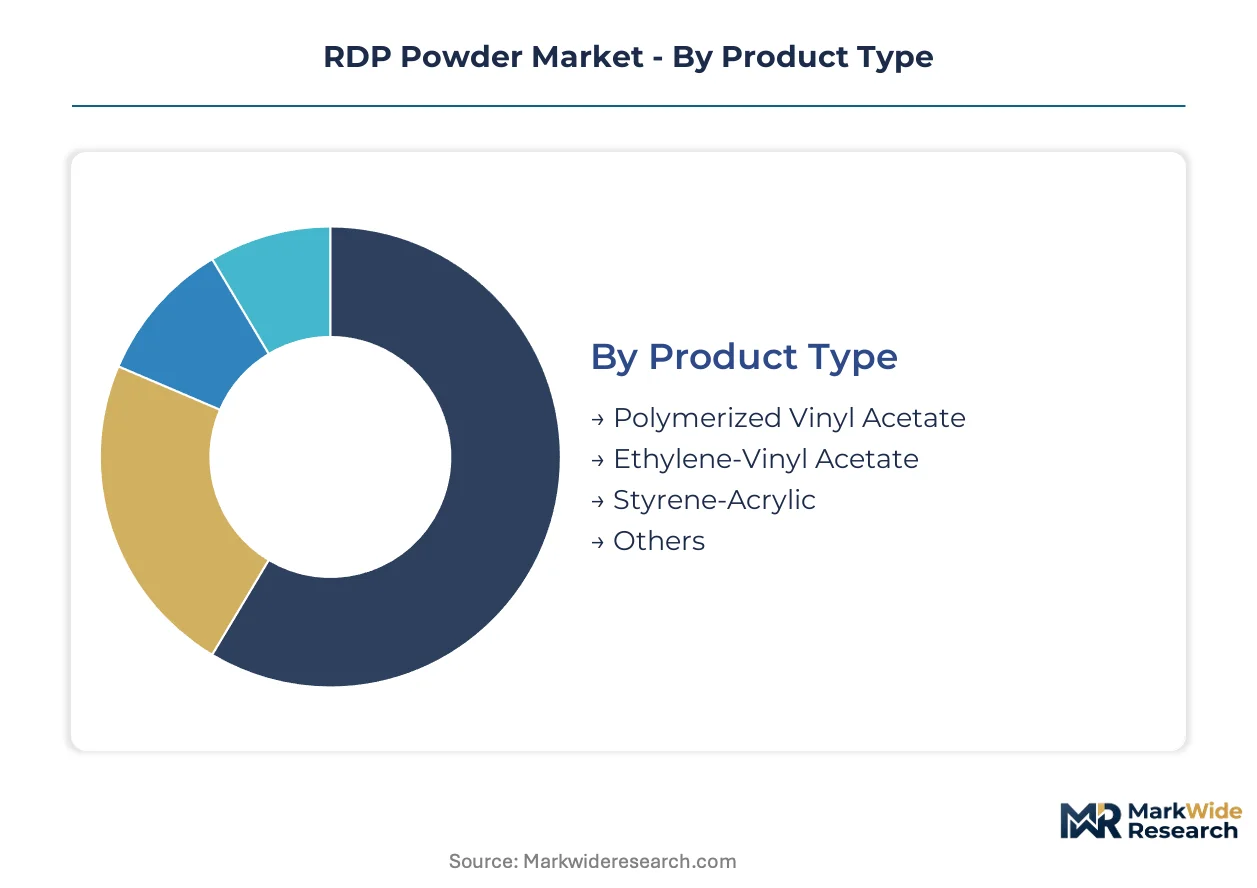
Segmentation in RDP powder markets reveals how polymer chemistry, application requirements, and regulatory compliance interact to determine pricing power and specification access. Distinct formulation tiers serve divergent end-use durability standards across construction and industrial applications.
Product Type:
Domestic consumption patterns favor styrene-acrylic and ethylene-vinyl acetate grades in China and India, while European markets import premium polymerized vinyl acetate variants for exterior facade systems.
- Polymerized Vinyl Acetate:Spray-dried vinyl acetate homopolymers and copolymers with superior alkali resistance and freeze-thaw durability. German and Dutch specification markets consume these grades for exterior insulation and finish systems requiring CE marking under the EU Construction Products Regulation. REACH compliance costs favor incumbent producers with captive emulsion capacity.
- Styrene-Acrylic:Hydrophobic copolymer systems dominating construction adhesive formulations through cost-engineered performance balance. China's Zhejiang and Jiangsu province manufacturing clusters drive volume consumption for high-rise tile adhesive systems in coastal urban development corridors. Asian petrochemical complexes control over 60% of global styrene monomer feedstock.
- Ethylene-Vinyl Acetate:Cost-advantaged grades for emerging-market dry-mix mortar applications with moderate durability requirements. Vinyl acetate monomer price volatility tied to ethylene and acetic acid markets compresses margin predictability.
- Others:Specialty acrylic and terpolymer formulations targeting niche textile and coating applications with specific film flexibility requirements.
Styrene-Acrylic holds the largest share; momentum sits with Polymerized Vinyl Acetate.
Application:
Cost tier differentiation separates specification-grade construction systems from commodity industrial binders.
- Construction:Cement modifier applications in dry-mix mortars, tile adhesives, and self-leveling compounds commanding premium pricing. India's Gujarat and Maharashtra state infrastructure programs are accelerating dry-mix mortar plant commissioning. GB/T cement admixture standards and REACH registration requirements constrain uncertified producer entry.
- Adhesives:Pressure-sensitive and construction adhesive formulations requiring tailored tack and cohesive strength profiles. ECHA restrictions on solvent-based alternatives redirect formulation toward redispersible polymer powders.
- Coatings:Architectural and industrial coating modifiers where film-forming properties enhance durability and substrate adhesion.
- Textiles:Nonwoven fabric binders and textile finishing applications with lower polymer loading requirements than construction systems.
Construction commands the highest value per kilogram; Adhesives are climbing fastest on regulatory substitution.
End User:
Procurement concentration among large-scale distributors is compressing payment terms and bypassing traditional trading intermediaries.
- Manufacturers:Construction chemical compounders and dry-mix mortar producers with direct mill relationships and collective supply agreements. China's Yangtze River Delta provincial dry-mix mortar associations negotiate volume contracts that squeeze tier-two formulator working capital.
- Contractors:Application-specified procurement in commercial flooring and exterior facade installation with performance-based material selection.
- Retailers:Small-volume distribution channels for renovation and DIY mortar applications with limited technical specification requirements.
- Distributors:Consolidating channel players compressing payment terms from 90 days to 45 days under direct mill models.
Manufacturers represent the dominant volume channel; Distributors are gaining share fastest through procurement consolidation.
Grade:
Margin pools concentrate in construction-specified variants meeting durability and disclosure standards, while industrial grades compete on scale economies.
- Industrial Grade:Volume-dominant category serving standard dry-mix mortar and adhesive applications without specialized certification requirements. Natural gas-fired spray-drying energy intensity faces carbon cost pass-through pressures under EU ETS.
- Food Grade:Packaging adhesive and coating applications requiring migration testing and compositional compliance with national food contact regulations.
- Pharmaceutical Grade:Tablet binding and controlled-release applications with stringent purity and residual monomer specifications.
- Cosmetic Grade:Personal care and topical formulation binders with microbial and heavy metal testing protocols.
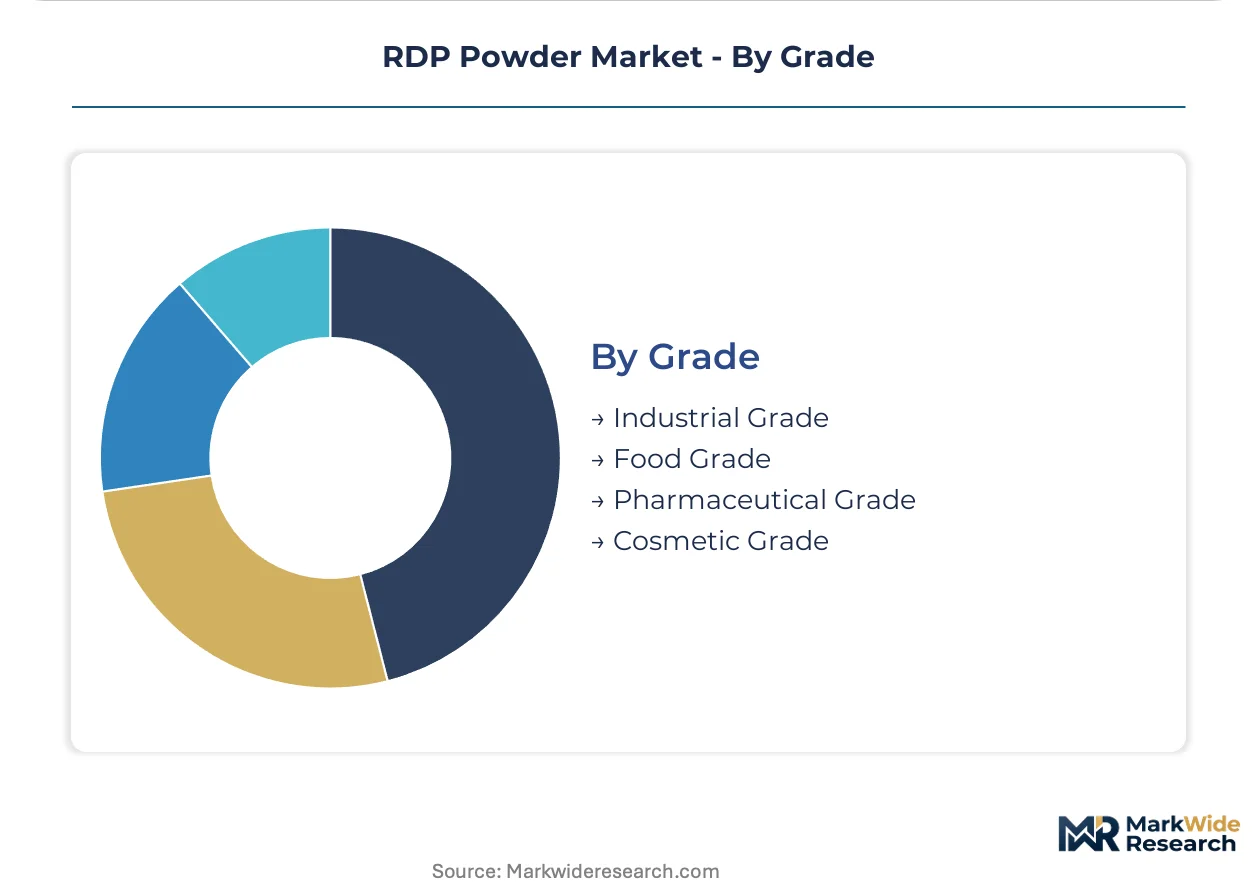
Industrial Grade holds the largest share; construction-specified Industrial Grade captures the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction chemical regulations and infrastructure investment programs are redrawing geographic demand patterns across major economies. National standards for cement admixtures and green building mandates now determine which polymer formulations secure specification access in each market.
China
High-rise residential and commercial development in coastal provinces sustains volume consumption of vinyl acetate-ethylene copolymers. GB/T standards for cement admixtures mandate alkali resistance testing that favors certified domestic producers. Zhejiang and Jiangsu province manufacturing clusters host the country's densest concentration of dry-mix mortar compounding facilities.
Germany
Exterior insulation and finish system renovation cycles drive specification-grade polymerized vinyl acetate demand for cold-climate durability. REACH registration requirements and CE marking under the EU Construction Products Regulation protect incumbent suppliers with captive emulsion capacity. The country's western chemical corridor maintains integrated production from vinyl acetate monomer through spray-dried powder.
United States
Commercial flooring renovation and exterior facade remediation projects consume higher polymer loadings in self-leveling underlayments. EPA and state-level air quality regulations on emulsion plant emissions shape manufacturing location decisions for suppliers. The Southeast and Texas Gulf Coast host expanding construction chemical compounding capacity serving domestic specification markets.
India
State infrastructure programs in Gujarat and Maharashtra accelerate dry-mix mortar plant commissioning for highway and urban housing projects. BIS certification requirements for construction chemicals constrain uncertified producer entry into specification-grade segments. The western industrial corridor attracts polymer powder distributors establishing direct mill relationships with formulators.
Saudi Arabia
Megaproject construction and green building initiative mandates under Vision 2030 redirect specification procurement toward low-VOC cement modifiers. The national regulator enforces construction product standards that favor imported polymerized vinyl acetate grades with environmental performance declarations. Riyadh and the Eastern Province concentrate demand from large-scale contractor procurement programs.
RDP Powder Market Key Industry Players
Listed leaders compete with private specialists across integrated petrochemical platforms and focused compounding operations. The supplier base stratifies between multinational chemical conglomerates with backward integration into vinyl acetate monomer and regional compounders sourcing emulsions from third parties. Three archetypes dominate: integrated petrochemical majors, construction chemical specialists with captive polymer capacity, and cost-focused regional compounders serving emerging markets. Competitive dynamics center on capacity expansion in high-growth Asian corridors and strategic partnerships to secure bio-based protective colloid supply chains.
Among integrated European chemical groups, Wacker Chemie AG and BASF SE exemplify the premium-tier archetype through combined silicone and polymer platform breadth. Organik Kimya occupies a position within the cost-engineered specialist tier, with geographic naming suggesting Turkish or Middle Eastern operational roots. These three entities represent the competitive spectrum from specification-grade certification holders to volume-focused regional suppliers.
| Leading Market Players |
|---|
| Dow Inc. |
| Dairen Chemical Corporation |
| Wacker Chemie AG |
| Arkema S.A. |
| Ashland Inc. |
| BASF SE |
| Synthomer plc |
| Organik Kimya |
| Celanese Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Chinese dry-mix mortar associations and integrated polymer producers lock in both vinyl acetate monomer supply access and price visibility across the forecast window. These arrangements insulate specification-grade buyers from spot market volatility while compressing margins for non-integrated compounders lacking backward integration into emulsion capacity.
Pricing Analysis
Certification level under REACH and GB/T standards creates the primary spread between premium polymerized vinyl acetate grades and commodity styrene-acrylic alternatives. Three-tier pricing structure across specification-certified, standard industrial, and economy-grade tiers reflects divergent compliance investment burdens. Pricing pressure stems from vinyl acetate monomer volatility tied to ethylene and acetic acid feedstock swings. Large-scale construction chemical manufacturers exhibit lowest price sensitivity due to specification lock-in, while tier-two formulators face acute working capital constraints under compressed payment terms.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European formulators sourcing Chinese emulsion intermediates. Manufacturing gravity centers on China, Germany, and India, with spray-drying capacity clustering near coastal vinyl acetate monomer production. Supply chains draw from ethylene, acetic acid, and styrene monomer feedstocks vulnerable to petrochemical complex concentration in Asian markets. Single-source vulnerability runs through Zhejiang and Jiangsu province protective colloid suppliers. Distribution runs through consolidating large-scale construction chemical distributors bypassing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates niche opportunities as ECHA's expanding SVHC list and China's dual carbon goals split demand between legacy and reformulated grades. Specialty formulators serving school and healthcare indoor air quality protocols represent the most defensible white-space positions.
For Market Incumbents: Compound specification-grade market share through captive emulsion capacity additions in Gujarat and Maharashtra to serve India's western industrial corridor infrastructure programs. Accelerate post-polymerization stripping technology R&D to pre-empt ECHA residual monomer restrictions. Channel control through direct mill relationships with provincial dry-mix mortar associations protects against distributor consolidation.
For New Entrants and Emerging Players: Bio-based protective colloid formulation services represent the critical service-layer gap where incumbents under-serve EU Green Deal procurement requirements. Target German and Dutch school and healthcare renovation specifications with low-emission vinyl acetate-ethylene copolymers. Partner with regional construction chemical formulators lacking environmental product declaration coverage to bypass CE marking timeline barriers.
For Investors and Strategic Acquirers: Regional compounders with BIS certification and established distributor relationships in India's western industrial corridor offer the most attractive acquisition target archetype. Long-term viability hinges on positioning for bio-based formulation transition rather than commodity scale. Monitor ECHA SVHC candidate list expansion velocity as the signal to watch for chemistry substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate Monomer | Captive supply from ethylene and acetic acid insulates margin predictability against feedstock volatility. |
| CE Marking Certification Investment | EU Construction Products Regulation compliance secures specification access in German and Dutch facade markets. |
| Bio-based Protective Colloid Transition | Environmental performance declarations align with EU Green Deal embodied carbon tracking requirements. |
| Direct Mill Relationship Expansion | Bypassing trading intermediaries captures procurement consolidation in China's Yangtze River Delta. |
| Post-polymerization Stripping Technology | Residual monomer reduction pre-empts ECHA SVHC listing and sustains styrene-acrylic grade viability. |
Research Approach
A standing panel of dry-mix mortar plant managers, construction chemical procurement leads, spray-drying operations directors, and EHS compliance officers provided ongoing calibration against market developments. Primary interview findings triangulated with secondary validation from customs trade data, Cefic construction chemical reports, SEC 10-K filings from listed polymer producers, and GB/T standard documentation. Bottom-up volume modeling across product type, application, and grade tiers converged with top-down macroeconomic anchoring.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated polymer chemistry, end-use durability requirements, certification tier, and regional regulatory cluster dimensions. CAGRs derived from annualized growth rate calculations applied to base-year sizing. Forecast inputs included infrastructure investment program announcements, dry-mix mortar plant commissioning timelines, and regulatory disclosure requirement phase-in schedules.
Forecasts assume regulatory continuity in REACH, GB/T, and BIS regimes; material policy shifts would require re-modeling. Vinyl acetate monomer price volatility, ETS carbon cost pass-through implementation, and CE marking timeline compression represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Fine Sandpaper Market
Abrasives
Grinding Wheels Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Polishing Chemicals Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Abrasive Rolls Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
Carbide Tools Market
Abrasives
Australia Abrasives Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Abrasive Cloth Market
Abrasives
Tungsten Carbide Market
Abrasives
Abrasive Base Paper Market
Abrasives
Chemical Deflasher Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Coated Abrasives Market