
 Metalworking Treating Fluid Market | 2026-2036
Metalworking Treating Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Metalworking Treating Fluid Market Analytics
German specialty chemical producers is pivoting toward high-performance synthetic formulations for precision machining. Quaker Houghton leverages its integrated metalworking chemistry portfolio across North American and European OEM supply chains. FUCHS Petrolub SE anchors its position through backward integration into base oil refining and additive compounding. ExxonMobil Corporation competes on manufacturing scale and captive supply of Group II/III base stocks for straight oil blends.
Metalworking treating fluids are engineered lubricants and coolants formulated with mineral oils, synthetic esters, or vegetable-base stocks combined with extreme-pressure additives, emulsifiers, and biocides, designed to reduce friction, dissipate heat, and extend tool life during machining operations. Semi-synthetic fluids dominate volume in general manufacturing due to their balance of cooling performance and cost, while synthetic fluids command premium positioning in aerospace grinding applications where thermal stability and waste minimization drive specification. Straight oils retain share in heavy-duty forming operations where lubricity requirements exceed cooling demands, and emulsifiable oils face substitution pressure from cleaner alternatives in European automotive machining.
EPA regulates metalworking fluid discharges under Clean Water Act effluent guidelines, while OSHA enforces permissible exposure limits for mist and volatile components in metal fabrication facilities. REACH restricts chlorinated paraffin use in EU-formulated products, forcing reformulation toward sulfur-phosphorus additive packages. China's MEE implements stricter wastewater standards for metalworking facilities in the Yangtze River Delta. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing fluid specifications across multinational production networks.
Market Dynamics
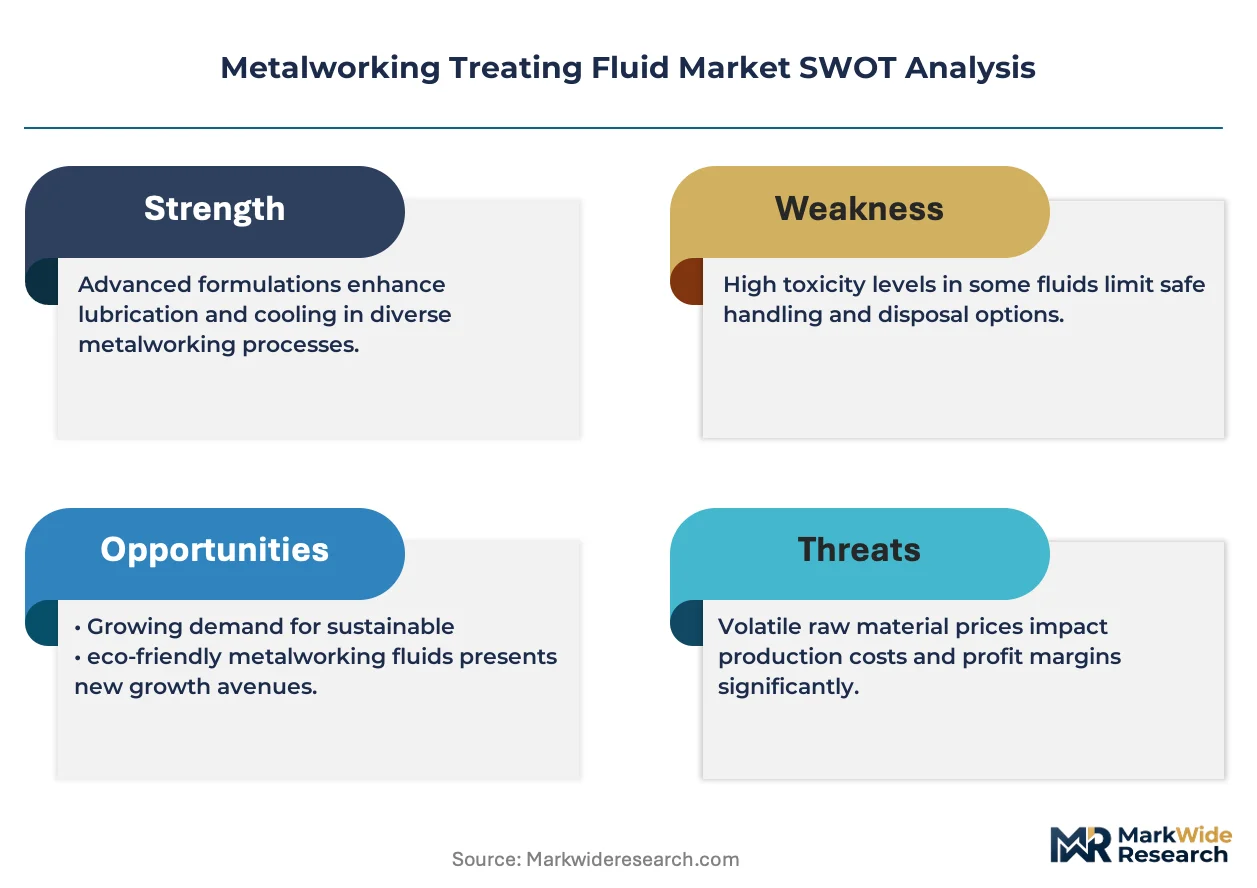
REACH restrictions on chlorinated paraffins are forcing wholesale reformulation across European supply chains, while China's MEE wastewater standards tighten discharge limits in the Yangtze River Delta manufacturing corridor. These dual regulatory pressures are compressing legacy formulation margins and accelerating R&D investment in sulfur-phosphorus additive packages.
Growth Catalysts
- EU Green Deal alignment:German automotive OEMs now specify bio-based metalworking fluids in supplier contracts, creating pull-through demand for vegetable-base stock formulations across precision machining operations.
- China's eastern manufacturing corridor:Concentrated machine tool investment in Jiangsu and Zhejiang provinces sustains volume consumption of semi-synthetic coolants for high-speed CNC operations.
- OSHA permissible exposure limits:Tighter mist concentration standards in US metal fabrication facilities drive replacement cycles toward low-mist synthetic formulations with advanced emulsifier chemistry.
Market Restraints
- Base oil supply concentration:Group II/III base stock production clusters in US Gulf Coast and Middle Eastern refining complexes expose formulators to feedstock price volatility and shipping cost spikes.
- Technical performance ceiling:Vegetable-base stocks still fail to match mineral oil thermal stability in extreme-pressure forming operations above 150°C tool surface temperatures.
- REACH registration burden:Novel biocide and extreme-pressure additive chemistries face multi-year ECHA evaluation timelines, delaying product launches by 18-24 months.
Strategic Opportunities
- India's PLI scheme for machine tools:Domestic manufacturing incentives in Tamil Nadu and Gujarat are seeding greenfield metalworking fluid demand among first-time CNC adopters.
- Minimum quantity lubrication convergence:Integration of near-dry machining with advanced synthetic mist delivery systems opens premium positioning in aerospace tight-tolerance grinding.
- Direct technical service models:Fluid suppliers bypass distributors to embed chemists at major automotive tier-1 machining facilities, capturing lifetime value through coolant management contracts.
Industry Challenges
- Biocide resistance management:Microbiological control specialists face escalating pseudomonas and mycobacterium tolerance, requiring continuous rotation of registered biocide actives.
- Waste fluid logistics reconfiguration:Centralized recycling infrastructure gaps force machine shops to manage dispersed collection networks, increasing compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metalworking Treating Fluid Market |
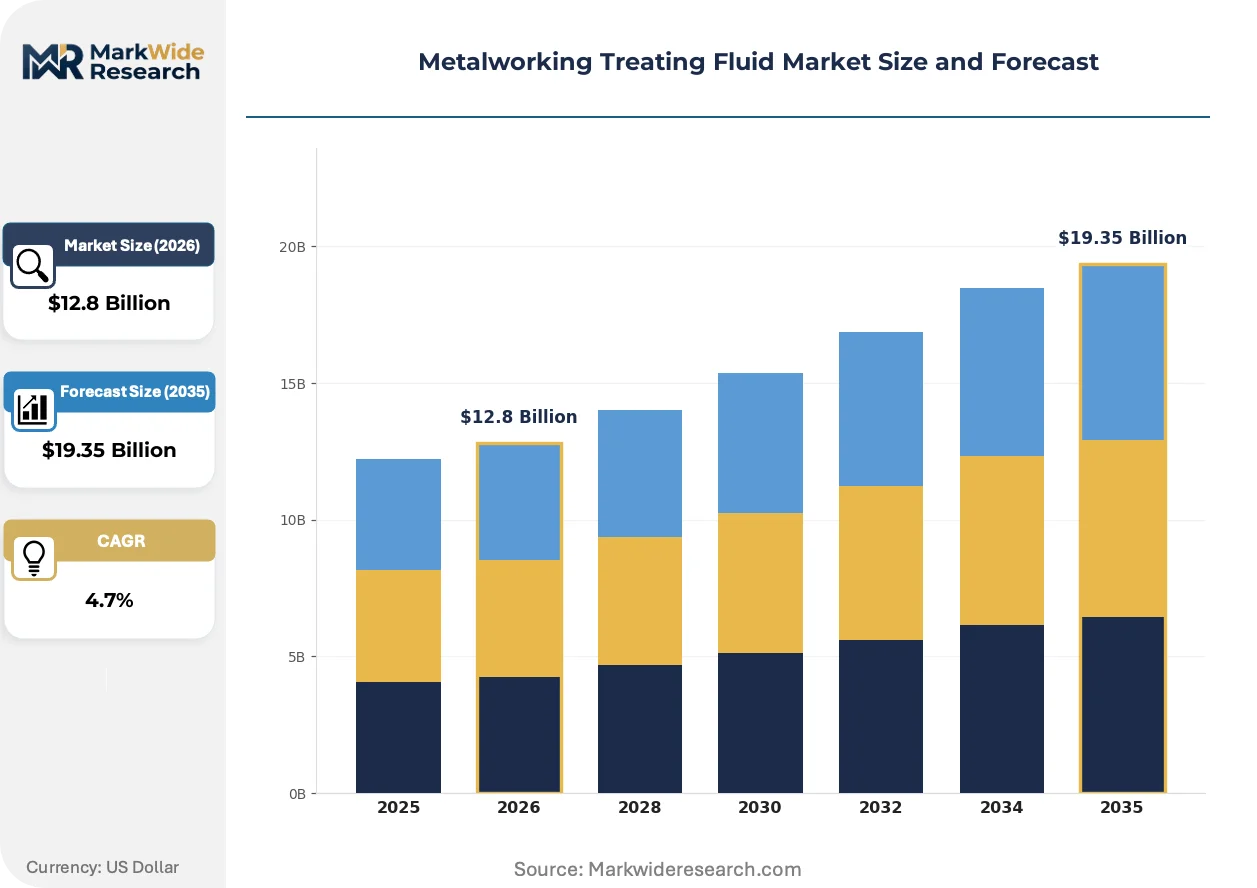
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiable Oils, Semi-Synthetic Fluids, Straight Oils, Synthetic Fluids Application: Machining, Grinding, Cutting, Forming End User: Aerospace, Automotive, Construction, General Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Quaker Houghton, FUCHS Petrolub SE, ExxonMobil Corporation, TotalEnergies SE, BP plc, Chevron Corporation, Idemitsu Kosan Co., Ltd., Blaser Swisslube AG, China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metalworking Treating Fluid Market Evolving Landscape
Synthetic ester chemistry is consolidating its position as the dominant platform for next-generation formulations, displacing both legacy mineral oils and first-generation vegetable bases in precision applications. Three interconnected developments are reshaping competitive positioning.
Hybrid synthetic-ester formulations are consolidating technical specification in aerospace grinding operations where thermal stability and waste minimization drive procurement decisions. Tier-1 suppliers to Boeing and Airbus supply chains now mandate synthetic coolants with documented carbon footprint data. This specification shift is compressing straight oil share in premium segments and forcing mineral oil specialists to acquire synthetic competency.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are eliminating a century-old extreme-pressure additive class from EU-formulated products. Formulators are pivoting toward sulfurized olefins and phosphorus ester packages, though these alternatives require higher treat rates and increase raw material costs. Japanese automotive machining facilities face parallel pressure as METI aligns domestic chemical regulation with EU precedent.
Automotive OEMs now bundle metalworking fluid procurement into integrated coolant management contracts spanning delivery, monitoring, and waste handling. Tier-1 suppliers to German transmission manufacturers prefer single-source accountability over fragmented chemical and service vendor relationships. This unbundling of product from service compresses distributor margins while rewarding formulators with in-house technical field teams.
Metalworking Treating Fluid Market Segmentation
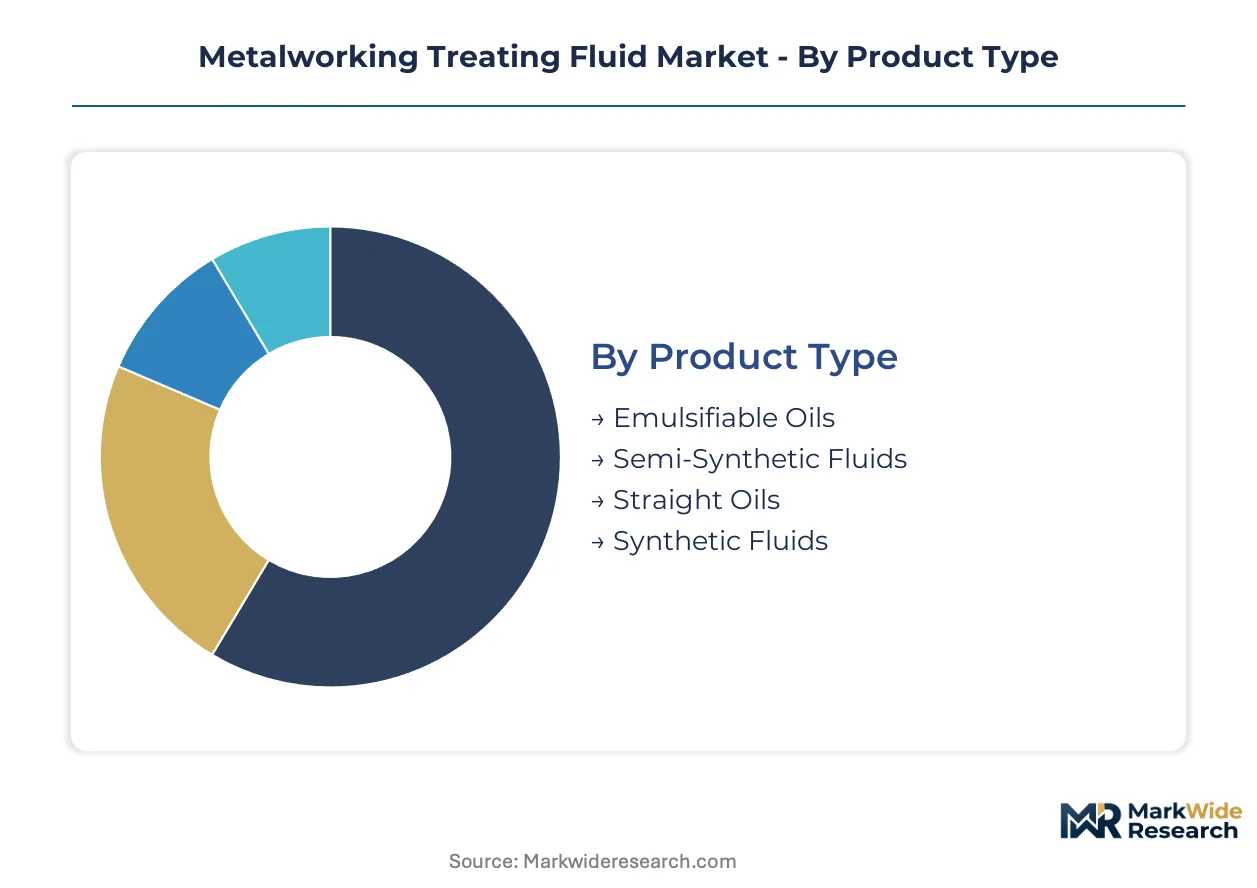
Metalworking treating fluid procurement cycles track closely with machine tool replacement timelines and regulatory compliance deadlines. Fluid specifications increasingly bundle chemistry with waste management services, collapsing traditional product-only purchasing models. Segmentation reveals where formulation investments concentrate versus where commoditization pressures dominate.
Product Type:
Upgrade cycles vary dramatically by chemistry platform, with regulatory phase-outs forcing premature replacement of legacy formulations before natural end-of-life.
- Semi-Synthetic Fluids:These water-based emulsions combine mineral oil content with synthetic additives to balance cooling efficiency and lubricity. Demand concentrates in China's Jiangsu and Zhejiang manufacturing corridors, where high-speed CNC operations favor their cost-performance ratio for general machining. MEE wastewater discharge standards are tightening acceptable oil-in-water limits, forcing reformulation toward lower-mineral-oil variants.
- Synthetic Fluids:Fully synthetic ester and polyalkylene glycol formulations deliver superior thermal stability and extended sump life without mineral oil content. Aerospace grinding operations in Germany and Japan specify these for tight-tolerance applications where thermal distortion risks exceed fluid cost premiums. EU Green Deal alignment is accelerating vegetable-base synthetic development for carbon footprint documentation.
- Straight Oils:Unemulsified mineral or synthetic base stocks serve heavy-duty forming where lubricity demands exceed cooling requirements. Die casting and deep drawing operations in US Midwest automotive stamping plants retain specification despite higher mist generation.
- Emulsifiable Oils:Traditional soluble oils face substitution pressure from semi-synthetics in European automotive machining, though legacy equipment in emerging manufacturing economies sustains residual demand.
Semi-synthetic fluids sit at the top of the volume ranking, with synthetic fluids climbing the fastest.
Application:
Process-specific thermal and friction profiles dictate additive package selection and coolant delivery system design.
- Machining:Turning, milling, and drilling operations consume the largest fluid volumes, with multi-axis CNC centers driving centralized coolant system investments. German automotive tier-1 suppliers now mandate minimum quantity lubrication compatibility in new equipment specifications.
- Grinding:Surface and cylindrical grinding generates extreme localized heat, requiring synthetic fluids with superior oxidation stability. Aerospace tight-tolerance applications in Japan command premium positioning for documented thermal performance data.
- Cutting:Sawing and cutoff operations favor semi-synthetic flood coolants for chip evacuation in high-volume steel service centers.
- Forming:Stamping, forging, and extrusion operations prioritize lubricity over cooling, sustaining straight oil specification despite OSHA mist exposure concerns.
Machining captures the largest share of consumption volume, while grinding offers the steepest expansion trajectory on aerospace specification upgrades.
End User:
Industry-specific certification requirements and warranty terms increasingly embed fluid chemistry into supplier qualification protocols.
- Automotive:Powertrain machining and stamping operations specify fluids through integrated coolant management contracts bundling chemistry, monitoring, and waste handling. German transmission manufacturers require bio-based content percentages in supplier scorecards.
- Aerospace:Grinding and superfinishing operations for turbine components demand synthetic fluids with full material compatibility documentation and carbon footprint certification.
- General Manufacturing:Job shops and contract manufacturers prioritize cost-efficient semi-synthetics with broad material compatibility across mixed-metal environments.
- Construction:Heavy equipment component machining sustains straight oil demand for large-part turning and boring operations.
Automotive represents the largest end-use segment by volume, with aerospace gaining share fastest on specification tightening.
Distribution Channel:
Channel structure is bifurcating between technical service-embedded direct relationships and transactional distributor volumes.
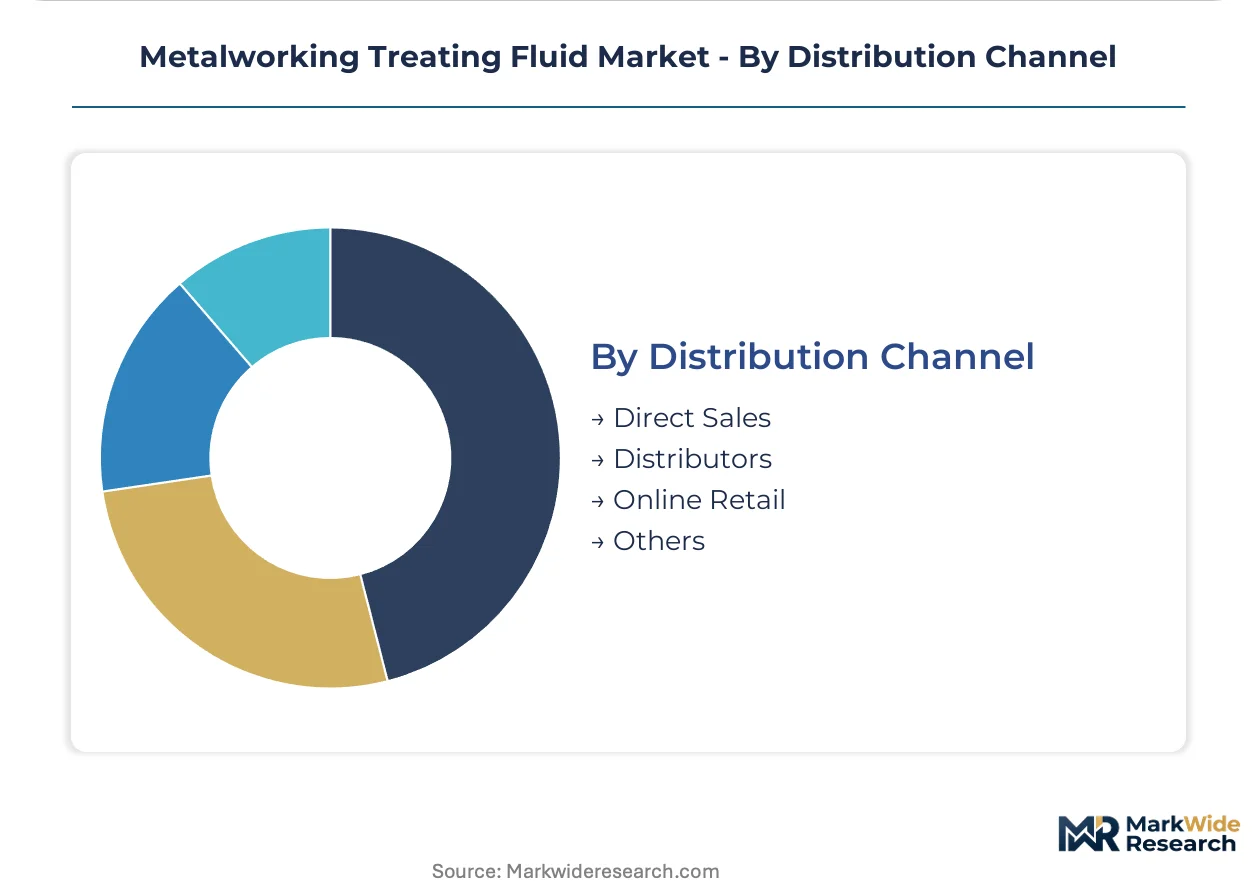
- Direct Sales:Fluid suppliers embed technical chemists at major automotive tier-1 facilities, capturing lifetime value through coolant management contracts spanning delivery, monitoring, and waste logistics.
- Distributors:Regional chemical distributors serve fragmented general manufacturing and job shop segments where technical service intensity does not justify direct coverage.
- Online Retail:E-commerce penetration remains limited to standardized maintenance volumes and small-shop replenishment, constrained by hazardous material shipping regulations.
- Others:Group purchasing organizations and integrated supply contractors capture institutional manufacturing accounts with centralized procurement mandates.
Direct sales leads channel value capture, though distributors retain volume dominance in geographically dispersed manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are fragmenting production networks, with formulators relocating blending capacity to jurisdictions where REACH-equivalent compliance costs remain lower. This migration pattern concentrates investment in manufacturing corridors with established machine tool density and permissive discharge regimes.
China
Machine tool investment in Jiangsu and Zhejiang provinces sustains volume consumption of semi-synthetic coolants for high-speed CNC operations. MEE implements stricter wastewater discharge standards in the Yangtze River Delta manufacturing corridor. Shanghai and Suzhou machining clusters now mandate lower-mineral-oil formulations to meet tightening oil-in-water limits.
Germany
Automotive OEMs in Stuttgart and Munich now specify bio-based metalworking fluids in supplier contracts, creating pull-through demand for vegetable-base stock formulations. REACH Annex XVII restrictions on short-chain chlorinated paraffins are eliminating legacy extreme-pressure additive classes. Bavarian precision machining facilities face wholesale reformulation toward sulfur-phosphorus packages.
United States
OSHA enforces tighter permissible exposure limits for mist concentration in metal fabrication facilities across Ohio and Michigan automotive stamping plants. EPA regulates fluid discharges under Clean Water Act effluent guidelines. The US Gulf Coast Group II/III base stock production clusters expose Midwest formulators to feedstock price volatility.
Japan
Aerospace grinding operations in Nagoya and Osaka command premium positioning for synthetic fluids with documented thermal performance data. METI aligns domestic chemical regulation with EU precedent on chlorinated paraffin restrictions. Chubu region turbine component manufacturers now mandate full material compatibility documentation.
India
Domestic manufacturing incentives under the PLI scheme for machine tools seed greenfield metalworking fluid demand in Tamil Nadu and Gujarat. First-time CNC adopters in these states prioritize cost-efficient semi-synthetics with broad material compatibility. BIS standards for industrial lubricants are tightening formulation disclosure requirements.
Metalworking Treating Fluid Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and minimum quantity lubrication compatibility as differentiation vectors. The vendor base stratifies between integrated petrochemical majors with captive base oil supply and specialty chemical formulators with embedded technical service capabilities. Three archetypes dominate: backward-integrated refiners controlling Group II/III feedstocks, synthetic ester specialists serving aerospace specification, and regional blenders competing on logistics proximity. Competitive moves concentrate on portfolio diversification into coolant management contracts and geographic expansion through technical field team deployment.
Within the integrated petrochemical tier, Quaker Houghton and FUCHS Petrolub SE exemplify formulators with backward integration into base oil refining and additive compounding. ExxonMobil Corporation occupies a scale-driven position anchored on captive supply of Group II/III base stocks for straight oil blends. These three entities represent contrasting strategic postures: technical service intensity, upstream supply control, and manufacturing scale.
| Leading Market Players |
|---|
| Quaker Houghton |
| FUCHS Petrolub SE |
| ExxonMobil Corporation |
| TotalEnergies SE |
| BP plc |
| Chevron Corporation |
| Idemitsu Kosan Co., Ltd. |
| Blaser Swisslube AG |
| China Petroleum & Chemical Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon footprint documentation gates qualified supply access and premium-tier pricing power for metalworking fluid formulators seeking aerospace and automotive OEM contracts. REACH-compliant sulfur-phosphorus additive packages command 15-25% raw material cost premiums over legacy chlorinated paraffin formulations, compressing margins for non-integrated blenders while rewarding backward-integrated producers with captive additive supply.
Pricing Analysis
Distributor margin compression dominates channel economics as integrated coolant management contracts disintermediate regional chemical distributors in automotive tier-1 supply chains. Three-tier pricing structure across premium synthetic esters, standard semi-synthetics, and economy-grade emulsifiable oils reflects certification burden and technical service intensity. Price differentiation hinges on bio-based content percentages and documented carbon footprint data for EU Green Deal alignment. Cost compression in semi-synthetic tiers is intensifying as Chinese MEE wastewater standards force reformulation toward lower-mineral-oil variants. General manufacturing job shops exhibit highest price sensitivity, while aerospace grinding operations show lowest sensitivity due to thermal performance warranty requirements.
Supply Chain Analysis
Freight cost spikes from US Gulf Coast and Middle Eastern Group II/III base stock clusters expose Midwest formulators to margin volatility during tanker rate surges. Supply concentrates in United States, China, and Germany for base oil refining and additive compounding capacity. Raw material dependencies include Group II/III mineral base stocks, synthetic ester feedstocks, and sulfur-phosphorus extreme-pressure additives. Single-source vulnerability in biocide actives intensifies as pseudomonas resistance forces continuous rotation of registered chemistries facing multi-year ECHA evaluation timelines. Distribution runs through direct technical service teams for automotive OEMs and regional distributors for fragmented general manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metalworking treating fluids function as a stable compounder anchored by mandatory regulatory reformulation cycles that sustain replacement demand regardless of machine tool investment cycles.
For Market Incumbents: Cement market position through backward integration into synthetic ester production and embedded technical field teams at German transmission manufacturers. Bio-based formulation certification investment defends against specialty chemical entrants exploiting EU Green Deal pull-through demand. Acquiring regional blending capacity in India's Tamil Nadu corridor captures PLI scheme machine tool adoption before first-time CNC users lock in supplier relationships. For New Entrants and Emerging Players: Capture white-space opportunity in India's Gujarat and Tamil Nadu greenfield machining clusters where first-time CNC adopters prioritize cost-efficient semi-synthetics without entrenched incumbent relationships. Minimum quantity lubrication compatibility for aerospace tight-tolerance grinding offers premium positioning against mineral oil specialists lacking synthetic competency. Go-to-market through direct coolant management contracts bundling chemistry, monitoring, and waste logistics bypasses distributor channel establishment costs. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with technical service capabilities because automotive OEM procurement consolidation favors single-source accountability over fragmented vendor relationships. Five-to-ten year viability rests on sulfur-phosphorus additive package expertise and bio-based formulation R&D pipelines. Acquisition target archetype: synthetic ester specialists with aerospace certification and embedded field chemist networks. Signal to watch: ECHA biocide registration backlog duration as indicator of formulation launch velocity for novel extreme-pressure chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Ester Production | Captures margin from REACH-driven reformulation toward sulfur-phosphorus additive packages in EU supply chains. |
| Embedded Technical Field Team Deployment | Secures lifetime value through coolant management contracts with German automotive tier-1 transmission manufacturers. |
| Bio-Based Formulation Certification Investment | Qualifies suppliers for EU Green Deal-aligned procurement scorecards mandating vegetable-base stock percentages. |
| Regional Blending Capacity in India | Positions for PLI scheme machine tool adoption in Tamil Nadu and Gujarat corridor demand growth. |
| Minimum Quantity Lubrication Compatibility Development | Opens premium aerospace grinding specification where thermal stability and waste minimization drive procurement decisions. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Primary interviews engaged plant managers at automotive stamping facilities, procurement leads at German transmission manufacturers, distribution channel partners serving general manufacturing job shops, and technical R&D directors at specialty chemical formulators. Secondary sources included ECHA REACH registration databases, US EPA Clean Water Act effluent guidelines, China MEE wastewater discharge standards, customs trade data for base oil imports, and SEC filings from integrated petrochemical majors. Bottom-up volume modeling triangulated against top-down market sizing from machine tool installation rates and fluid consumption coefficients.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product chemistry platform, application process type, end-use industry vertical, and regional regulatory cluster. Modeled dimensions included semi-synthetic versus synthetic versus straight oil formulation tiers, machining versus grinding versus forming process applications, automotive versus aerospace versus general manufacturing end-use splits, and country-specific compliance cost differentials. CAGRs derived from regression analysis against machine tool capital expenditure cycles, regulatory phase-out timelines, and OEM specification adoption curves. Industry-specific forecast inputs incorporated ECHA biocide registration pipeline durations and METI alignment schedules for chlorinated paraffin restrictions.
Regulatory phase-out acceleration, biocide resistance mutation rates, and base oil feedstock price volatility are the dominant revision risks to modeled trajectories. Forecasts embed assumptions regarding REACH enforcement consistency, MEE inspection intensity in the Yangtze River Delta, and OSHA permissible exposure limit revision timing. Stakeholders should weight assumptions against their own operating context and regional compliance burden exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Rotomolding Powder Market