
 Car Digital Video Recorder (DVR) Market | 2026-2036
Car Digital Video Recorder (DVR) Market Size, Share, and Industry Trends Forecast 2026-2036
Car Digital Video Recorder (DVR) Market Analysis
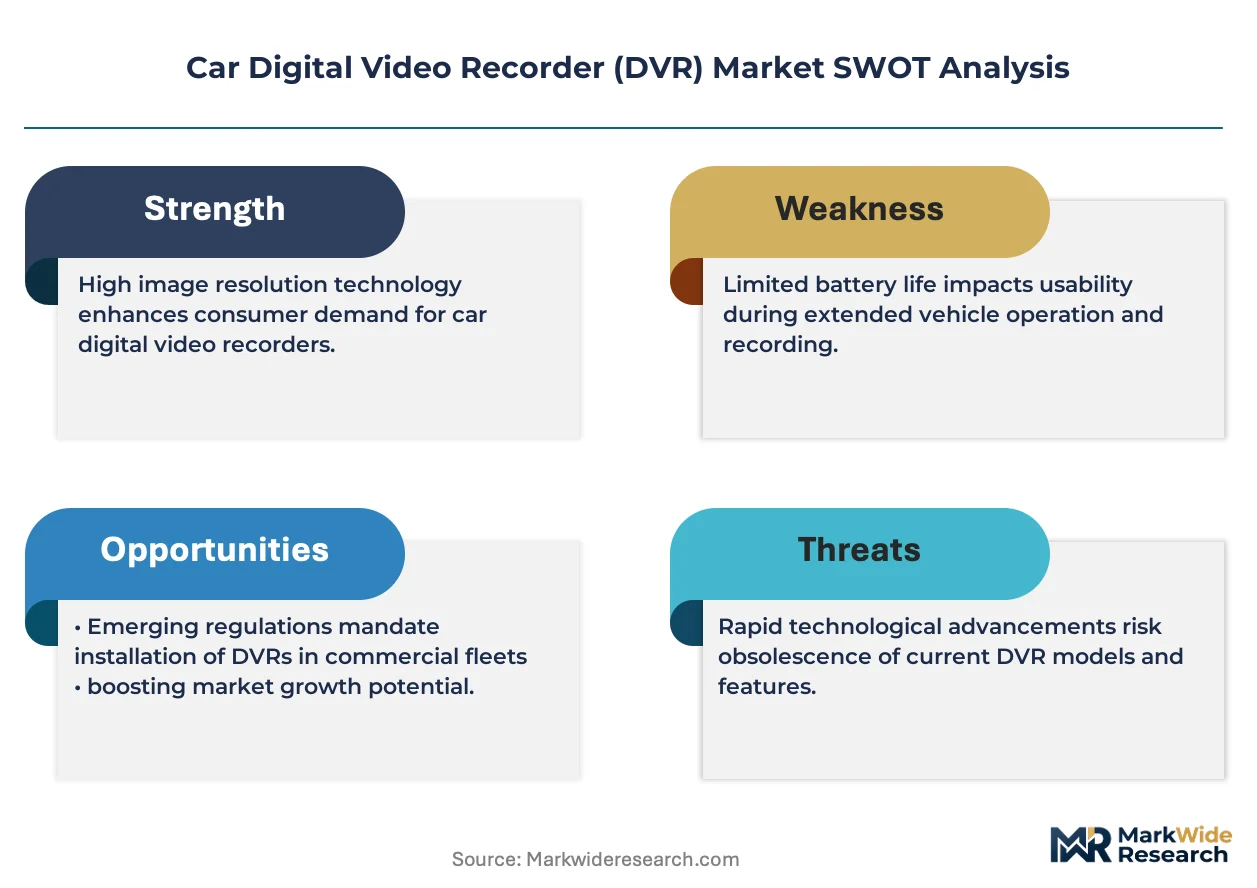
The EU Green Deal's embedded electronics sustainability criteria is pivoting procurement standards across European automotive supply chains. Garmin leverages its aviation-grade GPS heritage to anchor premium positioning in hardwired fleet installations. Nextbase competes through British design-led brand strength and direct retail channel control across Western Europe. Viofo specializes in cost-engineered 4K chipsets that sustain volume leadership in online aftermarket distribution.
A Car Digital Video Recorder is an onboard camera system that captures continuous video footage of road conditions, vehicle surroundings, and cabin interiors, typically recording at resolutions from HD through 4K onto solid-state storage with loop overwriting and G-sensor incident detection. Its primary commercial purpose is to provide evidentiary documentation for insurance claims, fleet safety audits, and law enforcement incident reconstruction. Dual-channel configurations now lead unit shipments as commercial fleet buyers prioritize front-and-rear coverage for comprehensive liability protection. Wi-Fi connectivity represents the fastest-growing technology segment, enabling real-time footage extraction without physical retrieval. The rideshare end-user category remains nascent but carries outsized margin potential due to driver-safety insurance mandates.
The National Highway Traffic Safety Administration in the United States and the European Union's General Data Protection Regulation jointly shape product standards, with NHTSA influencing crash-recording durability requirements and GDPR dictating passenger consent protocols and data retention limits for cabin-facing lenses. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility that determine market access for imported DVR chipsets. Stakeholders must monitor diverging privacy regimes between jurisdictions that will force modular hardware architectures capable of regional firmware compliance.
Market Dynamics
Fleet liability exposure and the EU AI Act's algorithmic accountability mandates are compressing product development cycles, forcing manufacturers to engineer modular hardware that can accommodate divergent privacy regimes without complete redesign.
Growth Catalysts
- Commercial fleet mandates:Large logistics operators now require dual-channel front-and-rear coverage for comprehensive incident documentation, creating sustained pull for integrated cabin-and-road recording systems.
- GDPR passenger consent protocols:The European Union's data retention limits for cabin-facing lenses have standardized privacy-by-design architectures that reduce compliance friction across multiple export markets.
- 4K Wi-Fi connectivity:Real-time footage extraction without physical retrieval is accelerating replacement cycles among rideshare drivers facing insurer-mandated safety documentation requirements.
Market Restraints
- MIIT electromagnetic compatibility certification:China's GB standards for imported DVR chipsets create technical barriers that delay market entry and increase testing expenditure for non-domestic suppliers.
- Solid-state storage cost volatility:NAND flash memory price fluctuations compress margin predictability for manufacturers targeting price-sensitive aftermarket segments.
- Smartphone dashcam substitution:Improved mobile camera stabilization and mounting accessories threaten entry-level dedicated recorder demand among casual consumer buyers.
Strategic Opportunities
- Rideshare insurance mandates:Driver-safety documentation requirements imposed by commercial auto insurers in North America and Western Europe represent an underpenetrated vertical with outsized margin potential.
- EU Green Deal sustainability criteria:Embedded electronics procurement standards are pivoting automotive supply chains toward repairable, recyclable designs that favor modular architecture specialists.
- Cloud-native firmware architecture:Over-the-air update capability converging with edge AI processing enables subscription-based feature unlocking and recurring revenue models.
Industry Challenges
- Firmware engineering talent scarcity:Expertise in real-time video encoding, G-sensor integration, and multi-jurisdiction privacy compliance resides within a limited pool of automotive embedded systems specialists.
- NHTSA crash-recording durability certification:Extended validation timelines for temperature, vibration, and impact resistance delay product launches and tie up capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Digital Video Recorder (DVR) Market |
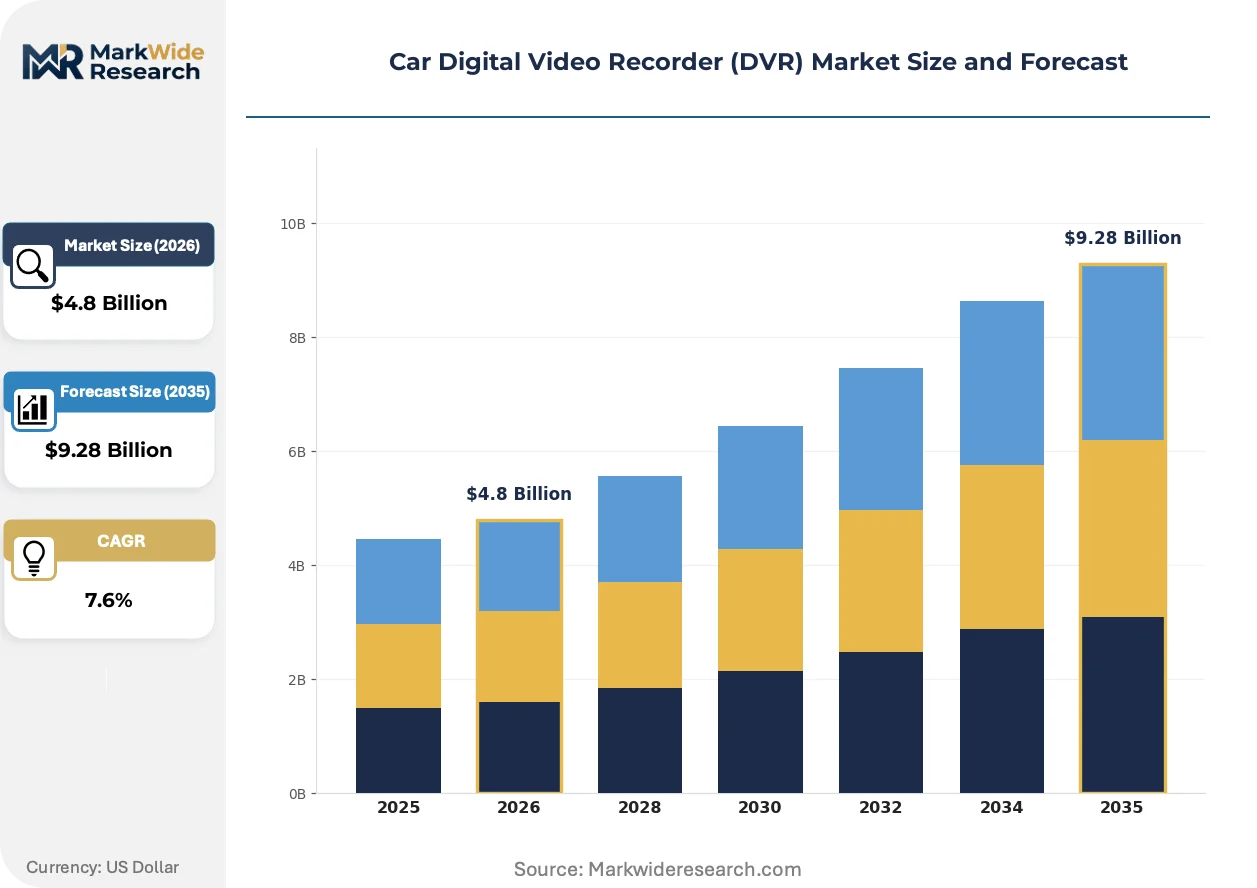
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
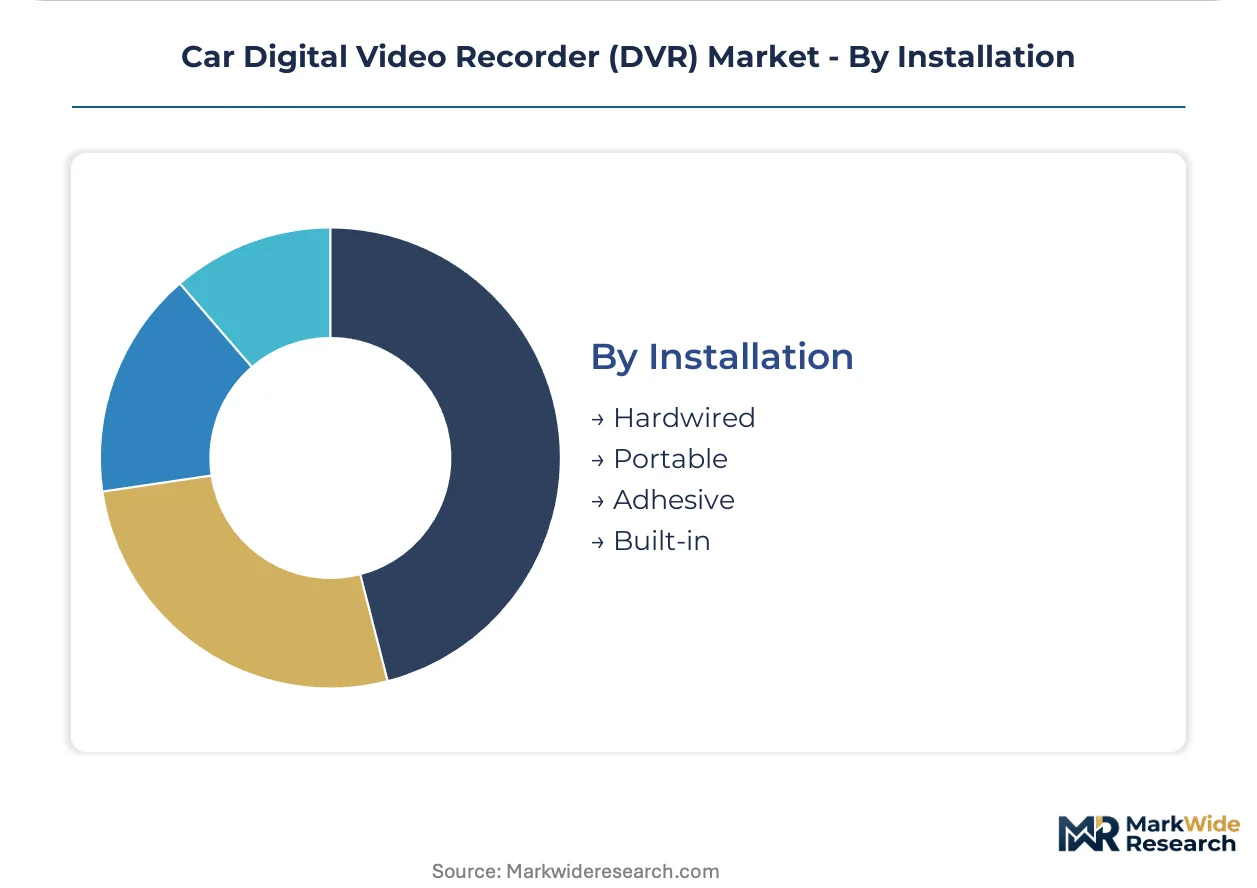
| Segmentation | Product Type: Front-Facing, Dual-Channel, Dash Cam, Rear-View Technology: HD, 4K, Wi-Fi, GPS End User: Personal Vehicles, Commercial Fleet, Law Enforcement, Rideshare Installation: Hardwired, Portable, Adhesive, Built-in |
| Companies Covered | Garmin, Alpine, Viofo, Redtiger, Escort, Vantrue, Kenwood, Nextbase, 70mai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Digital Video Recorder (DVR) Market Emerging Trajectories
Edge AI inference and cloud-native architectures are redistributing computational load between vehicle-mounted devices and remote servers, altering hardware specification priorities and opening service-based revenue models.
AI-powered incident detection is expanding into real-time driver behavior analysis and predictive risk scoring. Commercial fleet operators are adopting these systems fastest, with insurance carriers now requiring algorithmic documentation for premium discounts. This capability compression is shifting competitive advantage from pure hardware cost engineering toward software-defined feature differentiation.
The EU AI Act's risk classification framework for biometric identification systems is forcing cabin-facing lens manufacturers to implement explicit consent mechanisms and local processing constraints. Automotive OEMs serving European markets are responding by sourcing modular camera modules with firmware-configurable privacy modes that disable facial analysis in jurisdictions requiring such limitations.
Direct-to-consumer online channels are displacing traditional electronics retail for aftermarket DVR sales. Chinese manufacturers with domestic e-commerce expertise are capturing this shift most aggressively, while Western brands reliant on big-box distribution face margin compression and inventory risk. This channel rotation is most visible in North America and Western Europe, where Amazon marketplace algorithms favor review velocity over brand heritage.
Car Digital Video Recorder (DVR) Market Segmentation
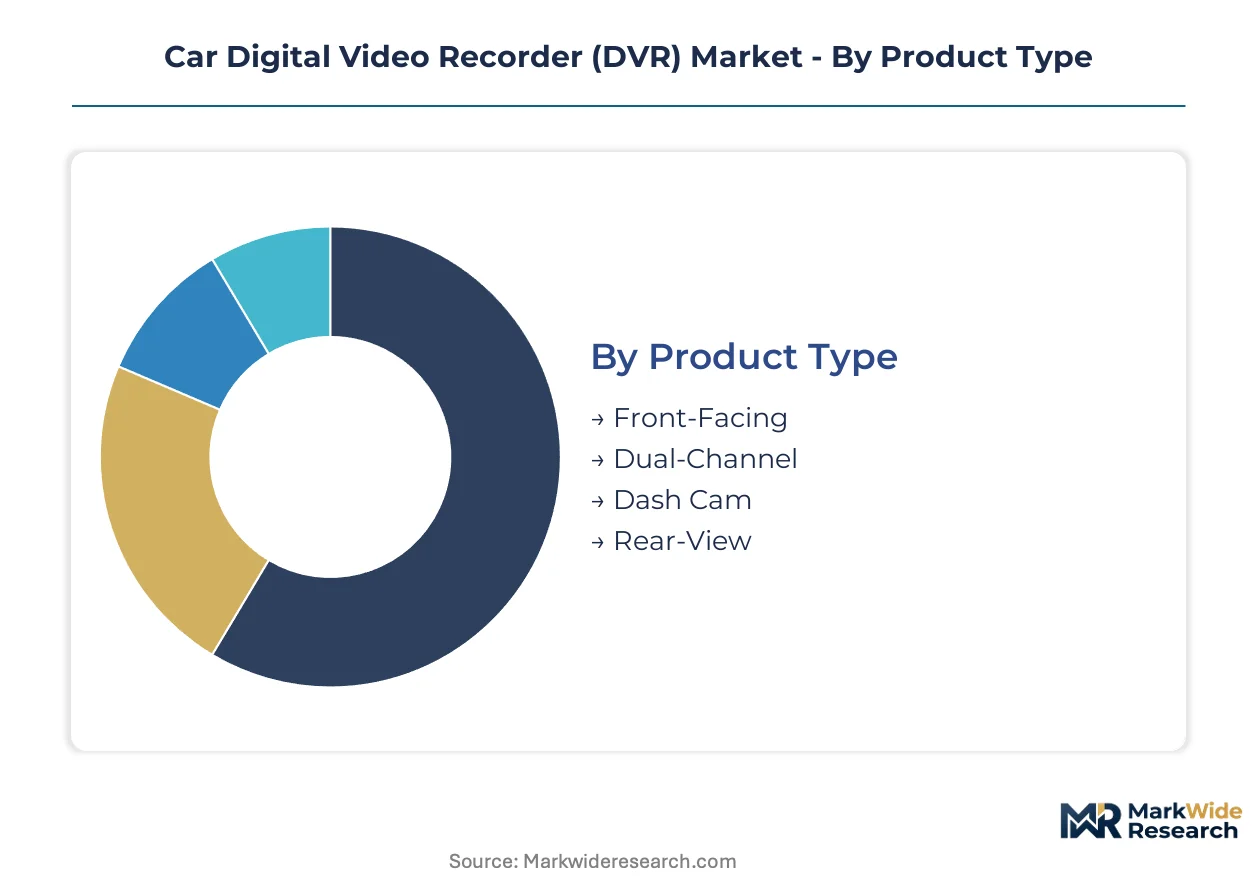
Segmentation in the Car DVR market determines procurement specifications across divergent liability regimes and installation constraints. Fleet operators prioritize dual-channel systems with hardwired power, while personal vehicle owners gravitate toward portable Wi-Fi models. Technology selection increasingly hinges on jurisdictional privacy requirements rather than pure image quality.
Product Type:
Capital intensity varies sharply across form factors, with dual-channel systems requiring dual image sensors, synchronized storage controllers, and complex thermal management in compact enclosures.
- Dual-Channel:Front-and-rear synchronized recording demands dual Sony or OmniVision image sensors, dual SD card controllers, and heat-dissipating metal housings. Commercial fleet operators in Germany and California mandate this configuration for comprehensive incident documentation under insurer requirements. NHTSA durability certification extends development timelines.
- Front-Facing:Single-lens systems with simplified PCB layouts and plastic enclosures dominate price-sensitive aftermarket channels. Chinese e-commerce platforms move the highest volumes of 1080p variants with basic loop recording.
- Dash Cam:Compact windshield-mounted units with suction or adhesive mounts serve the personal vehicle replacement market. Garmin and Nextbase anchor premium positioning through aviation-grade GPS integration.
- Rear-View:License-plate-frame or interior-mounted units with waterproofing and vibration resistance address specific blind-spot documentation needs. Adoption concentrates among commercial van operators in urban European centers.
Most installed capacity flows through Front-Facing. Expansion is steepest in Dual-Channel.
Technology:
Resolution and connectivity specifications segment procurement budgets, with 4K Wi-Fi commanding premium pricing while HD GPS units serve fleet standardization mandates.
- 4K:3840×2160 recording at 30fps requires H.265 encoding chipsets from Ambarella or Novatek, high-speed NAND storage, and robust thermal design. Rideshare drivers in North American markets face insurer mandates for high-resolution documentation. Viofo cost-engineering sustains volume leadership.
- Wi-Fi:Real-time footage extraction via smartphone apps eliminates physical SD card retrieval. Fleet safety managers in France and the Netherlands prioritize this capability for rapid incident response. GDPR consent logging adds firmware complexity.
- HD:1080p recording with H.264 compression remains the fleet standardization default. Logistics operators optimize storage economics through lower bitrates and extended retention periods.
- GPS:Embedded location and speed metadata supports insurance claim validation. European commercial insurers now require geotagged footage for premium discounts.
4K captures the highest revenue per unit. Wi-Fi is gaining share fastest among technology categories.
End User:
Customer type determines feature prioritization, with commercial fleets accepting higher upfront costs for durability and compliance while personal buyers optimize for ease of installation.
- Commercial Fleet:Logistics operators and delivery services mandate dual-channel coverage, hardwired installation, and cloud connectivity for centralized fleet management. GDPR passenger consent protocols and EU AI Act algorithmic accountability requirements shape procurement specifications. Amazon, DHL, and UPS set de facto standards through vendor qualification programs.
- Rideshare:Uber and Lyft drivers plus taxi operators face emerging insurance mandates for continuous cabin-and-road recording. This vertical carries outsized margin potential due to driver-safety documentation requirements. Regulatory fragmentation between US states and European countries complicates product standardization.
- Personal Vehicles:Individual consumers prioritize plug-and-play installation, smartphone app integration, and sub-$200 price points. Amazon marketplace algorithms favor review velocity over brand heritage.
- Law Enforcement:Police and emergency services demand tamper-evident recording, chain-of-custody metadata, and extended temperature operation. NHTSA crash-recording durability requirements apply.
Commercial Fleet absorbs the highest absolute spending. Rideshare shows the steepest expansion trajectory.
Installation:
Mounting method constrains power sourcing, tamper resistance, and aesthetic integration, with hardwired systems requiring professional installation and built-in variants demanding OEM supply chain qualification.
- Hardwired:Direct battery connection through fuse taps enables parking mode recording and eliminates cigarette lighter clutter. Fleet operators in Germany and the UK standardize on this approach for tamper resistance and clean cabin aesthetics. Professional installation adds labor cost.
- Built-in:Factory-integrated units embedded in rearview mirrors or headliners require automotive OEM supply chain qualification and multi-year durability validation. Chinese domestic manufacturers dominate this channel through partnerships with BYD, Geely, and NIO.
- Portable:Suction-cup or adhesive mounts with cigarette lighter power serve the aftermarket replacement cycle. Consumers in North America favor this flexibility for vehicle-to-vehicle transfer.
- Adhesive:Permanent 3M mounting tape attachment offers vibration resistance and low profile. Popular among rideshare drivers seeking unobtrusive cabin-facing positioning.
Portable maintains the largest installed base. Built-in is climbing the fastest as OEM integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Car Digital Video Recorder industry originated in Japanese automotive electronics manufacturing during the 1990s, with early adoption concentrated among taxi fleets in Tokyo and Osaka before spreading to commercial logistics operators across East Asia.
United States
Commercial fleet operators and rideshare drivers generate concentrated demand for dual-channel systems with cloud connectivity. NHTSA crash-recording durability requirements shape procurement specifications for law enforcement and emergency services. Detroit's automotive supplier corridor hosts integration partnerships between DVR manufacturers and Tier-1 OEMs.
China
Domestic manufacturers dominate global supply chains through cost-engineered 4K chipsets and direct-to-consumer e-commerce channels. MIIT electromagnetic compatibility certification creates technical barriers for imported components. Shenzhen's electronics manufacturing cluster produces the majority of Wi-Fi-enabled units for worldwide aftermarket distribution.
Germany
Logistics operators mandate hardwired dual-channel installations for comprehensive liability documentation under commercial auto insurance requirements. GDPR passenger consent protocols and EU AI Act algorithmic accountability standards drive privacy-by-design firmware architectures. Stuttgart's automotive engineering ecosystem influences durability validation protocols.
Japan
Precision manufacturing heritage supports premium positioning for GPS-integrated fleet installations. METI industrial standards guide electromagnetic compatibility testing for domestic and export markets. Nagoya's automotive supplier network provides qualified component sourcing for temperature-resistant designs.
United Kingdom
Direct retail channel control and design-led brand strength sustain premium aftermarket positioning. GDPR data retention limits for cabin-facing lenses standardize privacy-compliant product configurations. London's insurance brokerage sector drives rideshare driver adoption through safety documentation mandates.
Car Digital Video Recorder (DVR) Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the Car Digital Video Recorder landscape. Integrated manufacturers with captive semiconductor fabrication and in-house lens assembly occupy cost-leadership positions in high-volume segments. Asset-light specialists concentrate on firmware differentiation, cloud-native architectures, and subscription-based feature unlocking. Three strategic archetypes define competitive positioning: vertically integrated electronics conglomerates, modular component specialists, and software-defined platform operators. Geographic expansion through e-commerce marketplace optimization and strategic partnerships with automotive OEMs represent the dominant competitive moves.
Among North American technology integrators, Garmin and Escort exemplify premium-tier positioning through aviation-grade GPS heritage and radar detection expertise respectively. Viofo represents cost-engineered volume leadership within Chinese manufacturing specialists. Nextbase anchors British design-led brand strength across Western European retail channels. These three companies illustrate the geographic and strategic segmentation that structures competitive dynamics.
| Leading Market Players |
|---|
| Garmin |
| Alpine |
| Viofo |
| Redtiger |
| Escort |
| Vantrue |
| Kenwood |
| Nextbase |
| 70mai |
| Others |
Supply Flow & Price Mechanics
NAND flash memory spot prices cascade through Car DVR bill-of-materials into three distinct procurement tiers that separate fleet hardwired systems from portable aftermarket units and built-in OEM modules. Contract manufacturers in Shenzhen adjust production schedules within weeks of memory cost movements, transmitting volatility downstream through distributor markups and direct-to-consumer promotional cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aviation-grade GPS-integrated fleet installations from Wi-Fi-enabled rideshare units and basic 1080p front-facing recorders. Price differentiation rests on certification grade — NHTSA durability validation versus CE marking baseline — and volume scale through fleet procurement contracts. Pricing pressure stems from Chinese domestic manufacturers cost-engineering 4K chipsets for Amazon marketplace saturation. Commercial fleet operators demonstrate lowest price sensitivity due to insurance mandate compliance requirements, while personal vehicle buyers optimize aggressively around sub-$200 thresholds.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dongguan, and Hong Kong form the primary hub-and-spoke pattern for global aftermarket fulfillment, with satellite warehouses in Rotterdam and Los Angeles serving Western retail channels. Manufacturing concentrates in China, Taiwan, and South Korea for image sensors, encoding chipsets, and NAND flash assembly. The supply chain draws from Sony and OmniVision sensors, Ambarella and Novatek processors, and Samsung NAND modules. Single-source vulnerability in advanced node semiconductor fabrication presents structural risk. Distribution runs through direct-to-consumer e-commerce platforms displacing traditional electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Car DVR market functions as a stable compounder anchored by commercial fleet liability documentation mandates that sustain replacement cycles regardless of consumer discretionary pressure.
For Market Incumbents: Anticipate smartphone dashcam substitution threats at the entry-level by hardening premium positioning through aviation-grade GPS integration and cloud-native firmware architectures. Defensive consolidation should prioritize backward integration into encoding chipset design and captive supply of thermal management components to protect margin structures against NAND flash volatility. For New Entrants and Emerging Players: Begin with rideshare insurance mandates in North American and Western European markets, where driver-safety documentation requirements remain underpenetrated relative to fleet standardization. Target cloud connectivity and GDPR-compliant privacy-by-design firmware as the most penetrable technology wedge. Pursue direct-to-consumer e-commerce optimization over retail channel establishment. For Investors and Strategic Acquirers: Asymmetric upside sits with modular component specialists possessing firmware-configurable privacy architectures capable of EU AI Act compliance without hardware redesign. Long-term viability favors asset-light platform operators with subscription-based feature unlocking models over capital-heavy integrated manufacturers. Watch for inflection where commercial insurers mandate algorithmic incident documentation as a premium discount prerequisite.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Firmware Architecture | Enables over-the-air updates and subscription revenue models for fleet operators. |
| GDPR Privacy-by-Design Certification | Opens European rideshare and commercial fleet procurement to compliant suppliers. |
| Dual-Channel System Standardization | Aligns product roadmaps with insurer mandates from DHL, UPS, and Amazon qualification programs. |
| Direct-to-Consumer Channel Optimization | Captures Amazon marketplace algorithm preference for review velocity over brand heritage. |
| Edge AI Inference Integration | Supports real-time driver behavior analysis required for insurance premium discounts. |
Methodological Framework
Multiple input streams — fleet safety manager interviews, aftermarket distributor panel discussions, semiconductor procurement lead consultations, and regulatory affairs specialist exchanges — were reconciled against customs trade data, MIIT certification filings, NHTSA durability standards documentation, and Amazon marketplace sales velocity metrics. Bottom-up triangulation across component bill-of-materials and top-down validation through automotive OEM platform engineering disclosures anchored volume estimates.
Historical shipment patterns were cross-referenced against panel input from Tier 1 supplier procurement officers and aftermarket channel heads across the analysis window. Segmentation modeling incorporated product type, technology resolution tier, end-user category, and installation method dimensions. CAGRs were derived through regression analysis of replacement cycle compression and fleet mandate diffusion curves, with NAND flash price elasticity and Wi-Fi adoption velocity as industry-specific forecast inputs.
Caveats apply where MIIT electromagnetic compatibility certification delays, EU AI Act algorithmic accountability enforcement timing, or rideshare insurance mandate jurisdictional fragmentation could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market