
 Automotive Outside Rearview Mirrors (ORVM) Market | 2026-2036
Automotive Outside Rearview Mirrors (ORVM) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Outside Rearview Mirrors (ORVM) Market Outlook
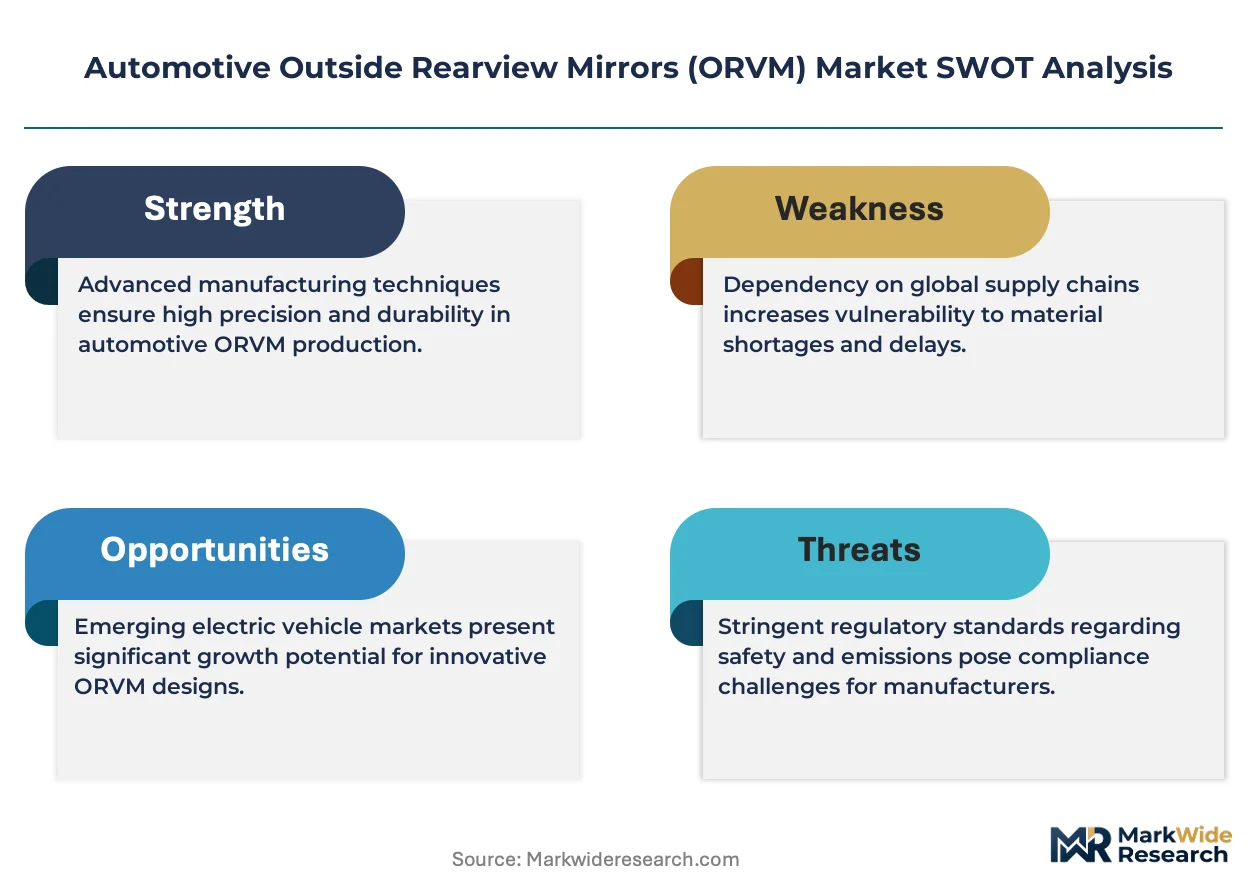
ECE R46 is broadening the cost-of-entry calculus for mirror suppliers entering European and aligned markets. Gentex Corporation leverages its electrochromic technology leadership to sustain premium positioning across North American and Asian OEM programs. Magna International anchors global volume through integrated mirror-module manufacturing at scale. Continental AG competes on camera-based replacement systems that navigate regulatory transition timelines.
Automotive outside rearview mirrors are optomechanical assemblies combining reflective glass substrates, polymer housings, and actuator mechanisms to provide regulated rearward visibility for vehicle operators. Units integrate heating elements, turn-signal indicators, and blind-spot detection sensors within aerodynamically shaped enclosures rated for vibration, impact, and environmental exposure. Conventional mirror technology still occupies the majority of unit volume, though digital camera-monitor systems are capturing specification share in premium European and Japanese OEM lineups where regulatory exemptions permit. Power-folding product types dominate factory-fitted installations across mid-range and luxury vehicle segments, while heated variants lead margin pools in cold-climate markets. Aftermarket replacement channels sustain steady demand for manual mirrors in aging vehicle parcs across emerging economies.
NHTSA's Federal Motor Vehicle Safety Standard 111 governs field-of-view requirements in the United States, while ECE R46 and Japan's JIS D 5705 establish parallel visibility and testing protocols. China's GB 15084 mandates mirror performance standards that MIIT enforces through vehicle type-approval processes, creating a three-bloc regulatory landscape that suppliers must navigate simultaneously. Stakeholders must monitor whether camera-monitor system exemptions expand beyond current regulatory carve-outs, as this determination will reshape capital allocation between traditional mirror glass and digital imaging supply chains.
Market Dynamics
Camera-monitor system exemptions under ECE R46 are fragmenting the traditional mirror supply chain as European OEMs accelerate digital rearview specifications across premium lineups.
Growth Catalysts
- Smart Mirror Adoption:Chinese domestic brands are expanding electrochromic and integrated sensor specifications across mid-range vehicle trims.
- ECE R46 Visibility Standards:Europe's regulatory framework permits camera-based replacement systems, creating new product categories for compliant suppliers.
- Heated Mirror Demand:Cold-climate markets in Scandinavia and Canada sustain aftermarket replacement cycles for thermally actuated mirror variants.
Market Restraints
- Glass Substrate Volatility:Raw material cost fluctuations for reflective coatings and polymer housings compress margin pools at tier-two suppliers.
- Regulatory Fragmentation:NHTSA FMVSS 111, ECE R46, and China's GB 15084 create parallel compliance costs without mutual recognition.
- Digital Substitution Threat:Camera-monitor systems eligible for ECE R46 exemptions displace conventional mirror glass in permitted vehicle categories.
Strategic Opportunities
- Underpenetrated Aftermarket:Aging vehicle parcs in India and Southeast Asia sustain manual mirror replacement demand through independent service channels.
- Integrated Sensor Convergence:Blind-spot detection and turn-signal indicator integration creates higher-value mirror-module specifications.
- MIIT Type-Approval Pathways:China's GB 15084 enforcement creates captive demand for locally certified mirror assemblies in domestic OEM programs.
Industry Challenges
- Optomechanical Engineering Talent:Shortage of specialists combining reflective glass science with automotive vibration and impact certification.
- Dual Certification Timelines:Simultaneous NHTSA and ECE homologation processes extend product launch cycles by 8-14 months.
- Legacy Actuator Integration:Power-folding mechanisms must interface with 15-year vehicle electrical architectures without redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Outside Rearview Mirrors (ORVM) Market |
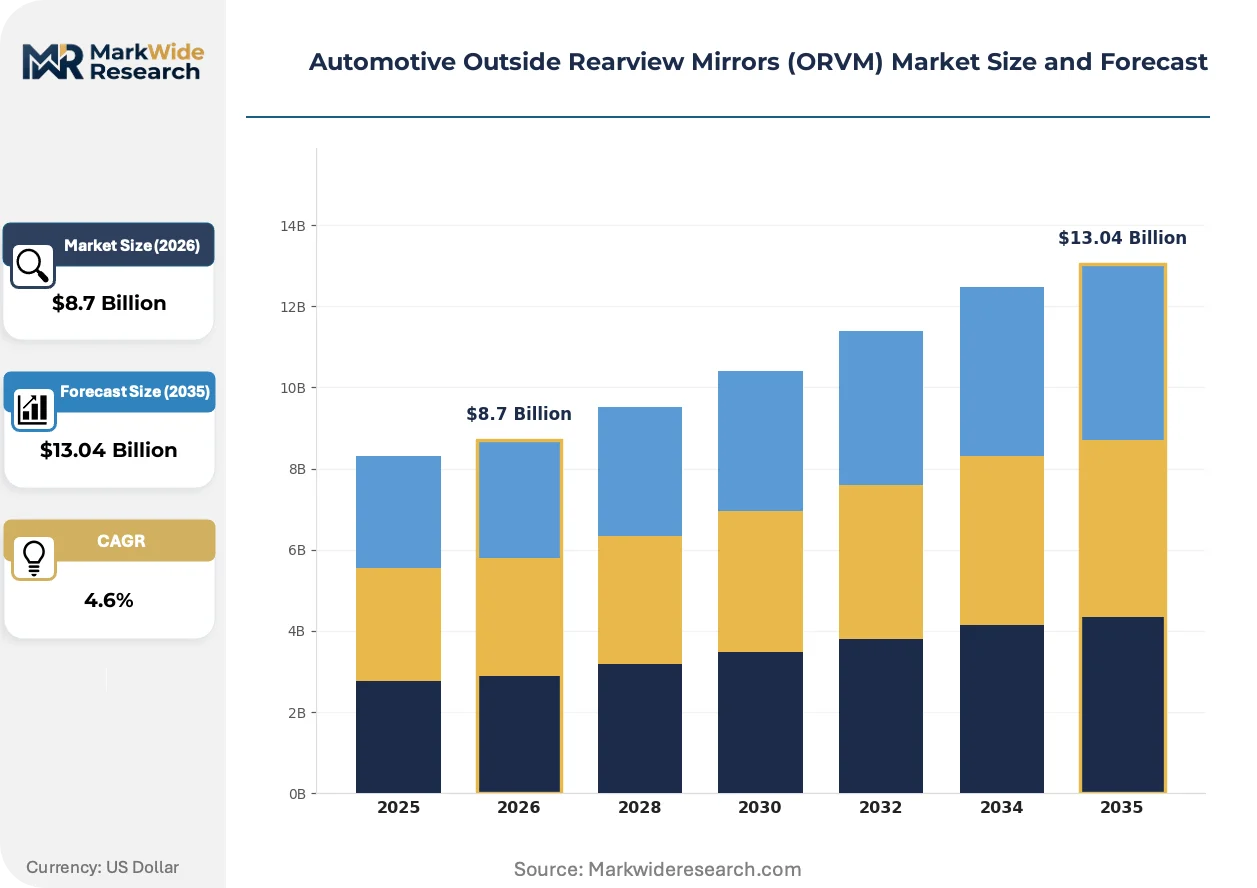
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Power, Heated, Folding Technology: Conventional, Digital, Electrocromic, 3D End User: OEMs, Aftermarket, Vehicle Assemblers, Dealerships Installation Type: Factory Fitted, Aftermarket Installation, Replacement, Premium |
| Companies Covered | Murakami Corporation, SL Corporation, Gentex Corporation, FLABEG Automotive Glass Group GmbH, Continental AG, Magna International Inc., Samvardhana Motherson Reflectec, Tokai Rika Co. Ltd., Ficosa International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Outside Rearview Mirrors (ORVM) Market Strategic Shifts
Digital imaging pipelines are displacing reflective glass substrates in regulatory-permitted segments, while actuator and heating element integration deepens within aerodynamically optimized housings.
Camera-monitor systems are modularizing the traditional mirror assembly by separating image capture from display functions. European and Japanese OEMs are specifying these systems in premium sedans and electric vehicles where ECE R46 exemptions apply. This architecture is compressing the supply chain by eliminating glass substrate vendors from certain bill-of-materials configurations.
Europe's ECE R46 amendment process is expanding camera-based system eligibility beyond current vehicle categories. The regulation's industrial consequence is redirecting supplier R&D budgets toward imaging sensor and display panel development. Premium OEM lineups in Germany and Sweden are responding fastest, with camera-monitor specifications appearing in flagship launches ahead of mass-market adoption.
Fleet procurement departments are consolidating mirror specifications across vehicle platforms to reduce service part complexity. Tier-one suppliers are responding with modular actuator and heating platforms that span multiple OEM programs. This consolidation is most visible in North American commercial vehicle segments, where standardized mirror modules reduce inventory carrying costs for large fleet operators.
Automotive Outside Rearview Mirrors (ORVM) Market Segmentation
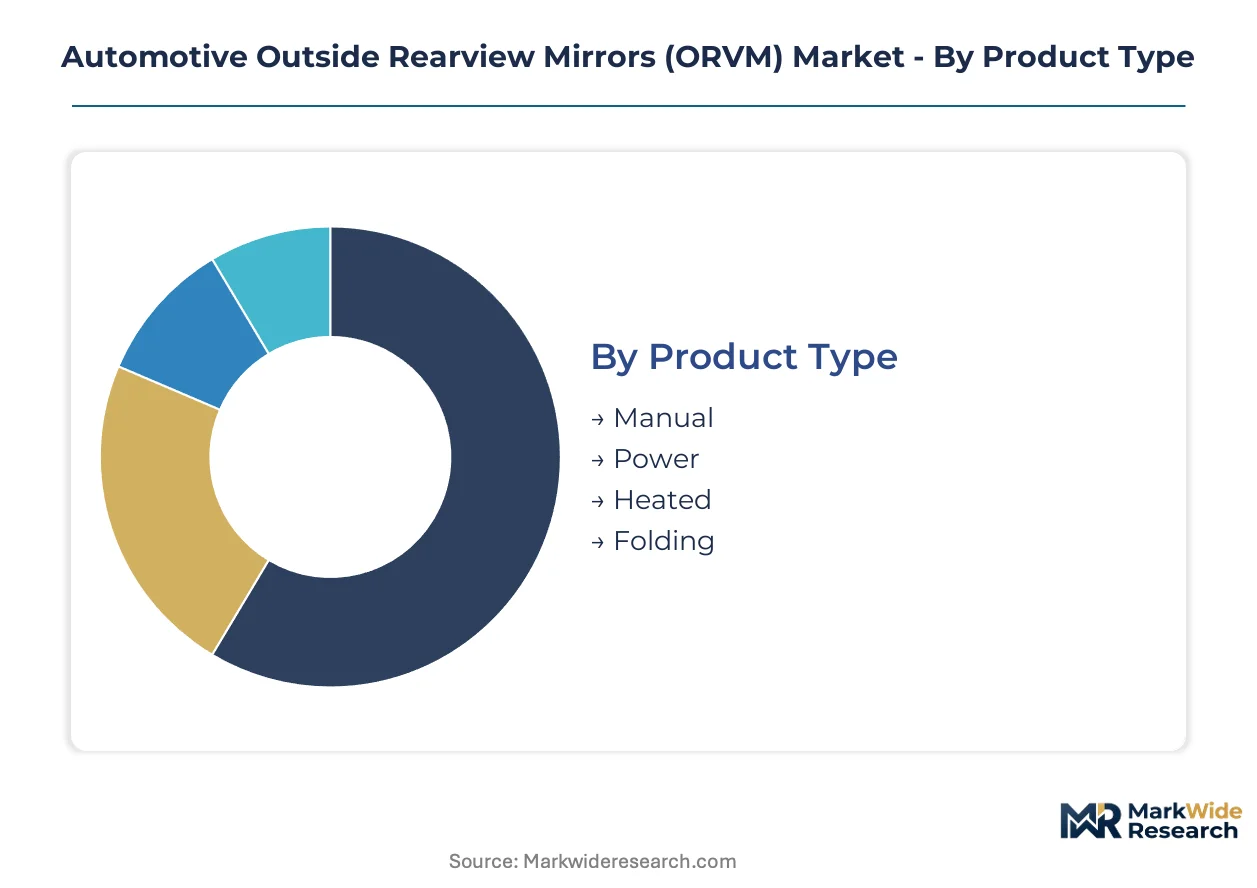
Automotive outside rearview mirrors fragment across four intersecting dimensions that reshape capital allocation and supplier positioning. Product type and technology choices determine tooling investments in glass substrates versus imaging sensors. End-user and installation channels govern inventory velocity and margin capture.
Product Type:
Capital intensity peaks with powered actuation mechanisms requiring precision motor assemblies and weather-sealed housing engineering.
- Manual:Simple pivot mechanisms with polymer housings dominate aging vehicle parcs and emerging economy aftermarket channels. Demand concentrates in India and Southeast Asia where cost-sensitive fleet operators prioritize repair economics over feature content.
- Power:Electrically actuated adjustment systems with integrated position memory require dedicated motor production lines and EMC certification. European and North American OEM programs specify these units across mid-range and luxury trims where consumer expectations for cabin convenience have hardened.
- Heated:Resistive element integration for defrosting functions adds thermal management complexity without major tooling escalation. Scandinavian and Canadian markets sustain steady replacement demand through cold-climate operational requirements.
- Folding:Power-retract mechanisms with collision detection sensors carry the highest per-unit component costs and warranty exposure. Premium vehicle lineups in Germany and Japan specify these for narrow urban parking environments.
Most installed capacity flows through Power. Expansion is steepest in Folding.
Technology:
Technology selection separates suppliers with captive glass-coating expertise from those pivoting toward imaging semiconductor supply chains.
- Conventional:Reflective glass substrates with prismatic day-night switching retain unit volume leadership across mass-market vehicle programs. Chinese domestic brands and entry-level OEM platforms in Brazil specify these for cost containment.
- Digital:Camera-monitor architectures eliminating reflective glass entirely demand imaging sensor partnerships and display panel integration. ECE R46 exemptions permit these systems in European premium electric vehicles where aerodynamic drag reduction carries range benefits.
- Electrochromic:Automatic dimming layers using gel-based light modulation require specialized coating chambers and humidity-controlled assembly. Gentex Corporation's technology leadership has concentrated premium program wins in North America.
- 3D:Stereoscopic imaging with depth-perception algorithms remains pre-commercial, with prototype deployments limited to German OEM research fleets. Technical validation timelines extend 24-36 months beyond current homologation frameworks.
Conventional technology anchors current revenue. Digital architectures are climbing the fastest.
End User:
Customer type determines payment terms, specification stability, and aftermarket channel access.
- OEMs:Original equipment manufacturers with multi-year program contracts and joint development agreements. Tooling amortization spans 5-7 year vehicle lifecycles with stringent PPAP validation requirements.
- Aftermarket:Independent distributors and service chains purchasing catalog parts without engineering development fees. Price transparency compresses margins but sustains volume in 8-15 year vehicle age cohorts.
- Vehicle Assemblers:Contract manufacturing operations for emerging market brands lacking captive component production. These customers prioritize logistics reliability and payment flexibility over technical differentiation.
- Dealerships:Authorized service networks with captive parts programs and warranty reimbursement authority. Inventory pooling arrangements reduce working capital requirements for tier-two suppliers.
OEMs absorb the majority of production capacity. Aftermarket channels are gaining share fastest.
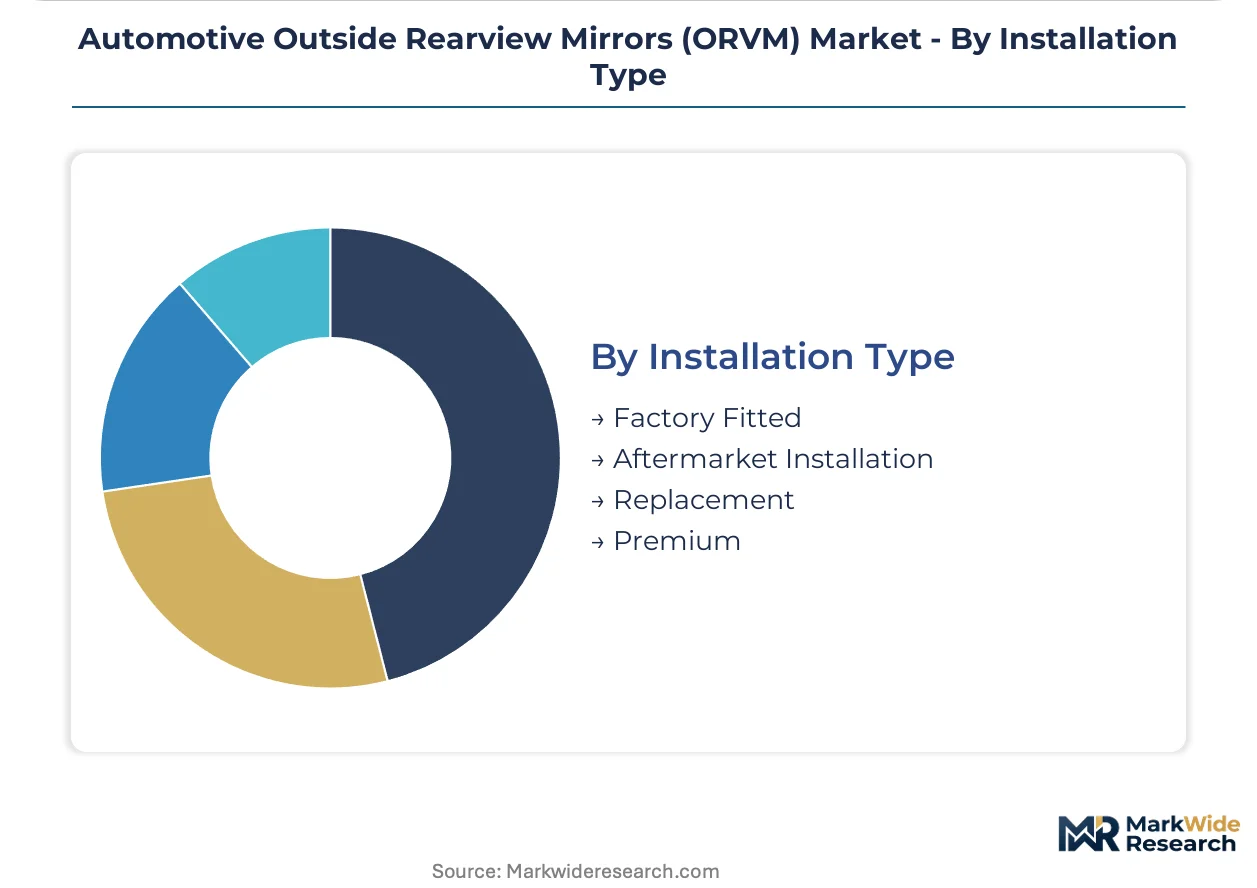
Installation Type:
Installation context dictates warranty liability periods and technical service requirements.
- Factory Fitted:Line-sequenced delivery to assembly plants with zero-defect quality protocols. These programs require supplier presence within 300km of vehicle production facilities.
- Aftermarket Installation:Post-vehicle-purchase upgrades through independent service providers. Technical support infrastructure and installation training become competitive differentiators.
- Replacement:Crash damage and wear-item substitution with insurance reimbursement pathways. Cycle times compress to 48-hour fulfillment for collision repair networks.
- Premium:Dealer-installed accessory packages with extended warranty coverage and cosmetic customization options. These specifications carry 40-60% margin premiums over base replacement units.
Factory Fitted commands the largest volume position. Premium installation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters around Stuttgart, Nagoya, and Detroit anchor mirror system development for major OEM programs. Regulatory divergence across NHTSA, ECE R46, and GB 15084 forces suppliers to maintain parallel certification capabilities. Production footprints track vehicle assembly concentration with just-in-time delivery requirements.
China
Domestic brands BYD and Geely are accelerating smart mirror specifications across mid-range electric vehicle trims. MIIT enforces GB 15084 through type-approval processes that favor locally certified suppliers. The Yangtze River Delta cluster around Shanghai hosts Magna and Samvardhana Motherson facilities serving SAIC and Tesla Gigafactory Shanghai.
Germany
Premium OEMs BMW and Mercedes-Benz are specifying camera-monitor systems under ECE R46 exemptions for flagship electric sedans. KBA administers homologation timelines that extend 8-14 months for dual US-Europe certification. Baden-Württemberg's Stuttgart region concentrates Continental AG and Bosch engineering centers developing imaging sensor architectures.
United States
Fleet operators and rental car companies are consolidating mirror specifications to reduce service part complexity. NHTSA's FMVSS 111 governs field-of-view requirements without current camera-monitor exemptions. Michigan's Detroit-Warren corridor anchors Gentex Corporation's electrochromic technology development for Ford and GM programs.
Japan
Tokai Rika and Murakami Corporation supply integrated mirror modules to Toyota and Honda with embedded blind-spot sensors. METI coordinates JIS D 5705 standards alignment with ECE R46 amendments. The Nagoya industrial corridor concentrates actuator mechanism production for export to Southeast Asian assembly plants.
India
Maruti Suzuki and Tata Motors are expanding power-folding mirror specifications across compact SUV segments. BIS adoption of UN ECE regulations is streamlining export certification for tier-one suppliers. The Chennai-Bangalore corridor hosts Samvardhana Motherson Reflectec facilities serving Renault-Nissan and Hyundai Motor India.
Automotive Outside Rearview Mirrors (ORVM) Market Competitive Environment
The competitive structure tilts toward integrated mirror-module specialists with captive OEM relationships. Three player archetypes dominate: electrochromic technology leaders, scale-driven module integrators, and camera-based system pioneers. Strategic moves concentrate on sensor integration partnerships and regulatory transition positioning between glass substrates and digital imaging pipelines.
Among Japanese specialists, Murakami Corporation and Tokai Rika Co. Ltd. exemplify the integrated module archetype with long-standing supply relationships to domestic OEMs. Gentex Corporation occupies a position representing electrochromic technology leadership in North American premium programs. Continental AG and Magna International sit within the scale-driven tier, anchoring global volume through diversified OEM portfolios.
| Leading Market Players |
|---|
| Murakami Corporation |
| SL Corporation |
| Gentex Corporation |
| FLABEG Automotive Glass Group GmbH |
| Continental AG |
| Magna International Inc. |
| Samvardhana Motherson Reflectec |
| Tokai Rika Co. Ltd. |
| Ficosa International SA |
| Others |
Value Chain & Pricing Dynamics
European premium OEM procurement consolidation around camera-monitor systems under ECE R46 exemptions has compressed supplier margins through bundled module pricing that eliminates discrete glass substrate transactions. Tier-one integrators now capture value through sensor-display integration rather than component markups, reshaping how tier-two suppliers negotiate contract terms.
Pricing Analysis
Bundled camera-monitor modules versus unbundled conventional mirror assemblies split pricing architectures across regulatory zones. Three-tier pricing structure across premium electrochromic, standard power-folding, and economy manual levels differentiates by certification grade and sensor integration depth. Cost compression in cold-climate heated variants is intensifying because resistive element suppliers face polymer housing volatility. Fleet procurement departments exhibit lowest price sensitivity due to lifecycle cost framing, while independent aftermarket distributors operate on thinnest margins.
Supply Chain Analysis
Freight costs from Chinese glass-coating facilities to European assembly plants have elevated regional sourcing premiums for reflective substrate supply. Manufacturing concentrates in China, Germany, and Mexico to satisfy just-in-time delivery windows for major OEM programs. Production draws from float glass feedstock, precision motor assemblies, and imaging sensor wafers as critical inputs. Single-source vulnerability in electrochromic gel formulations creates supply risk for automatic dimming specifications. Distribution runs through tier-one module integrators that manage sequencing logistics directly to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECE R46 camera-monitor exemptions in Europe contrast with NHTSA's glass-mirror mandate in the United States, creating divergent R&D allocation strategies across supplier footprints.
For Market Incumbents: Lock in electrochromic technology leadership through captive coating capacity expansion before digital substitution accelerates under expanding regulatory exemptions. Defend OEM program access by backward integration into imaging sensor partnerships that satisfy dual-homologation requirements. Prioritize certification investment in MIIT type-approval pathways to secure Chinese domestic brand volume. For New Entrants and Emerging Players: Launch via aftermarket distribution partnerships targeting India's aging vehicle parc where manual mirror replacement cycles sustain independent service channel revenue. White-space exists in Southeast Asian power-folding retrofit programs for compact SUV fleets. Pursue vehicle assembler relationships with emerging market brands lacking captive component production as the most penetrable entry vector. For Investors and Strategic Acquirers: Tier-one automotive electronics suppliers are the most active acquirer in this space as camera-monitor convergence accelerates. Long-term viability hinges on regulatory transition timelines between glass substrates and digital imaging pipelines. Signal to monitor: ECE R46 amendment scope expansion beyond current premium vehicle categories as inflection indicator for capital reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Camera-Monitor System Certification | ECE R46 compliance unlocks premium European OEM specifications ahead of mass-market adoption curves. |
| Electrochromic Coating Capacity Expansion | Gentex Corporation's technology leadership demonstrates margin capture potential in North American premium programs. |
| MIIT Type-Approval Investment | GB 15084 certification creates captive demand from BYD and Geley electric vehicle lineups. |
| Integrated Sensor Module Development | Blind-spot detection embedding raises per-unit value for Magna International's mirror-platform contracts. |
| Aftermarket Channel Partnership | Samvardhana Motherson Reflectec's India footprint illustrates logistics reliability advantages in replacement cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and regulatory interpretation variance. Primary engagement with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed specification trend validation. Secondary sources included vehicle production databases, IHS Markit registration data, NHTSA FMVSS 111 dockets, ECE R46 amendment documentation, and MIIT type-approval records. Bottom-up segment modeling and top-down market sizing triangulated around convergent estimates.
Segment-weighting across product type, technology architecture, end-user category, and installation channel drove analytical framework construction over the projection horizon. Vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions shaped demand decomposition. CAGRs emerged from installed base turnover analysis and specification rate penetration curves. Forecast inputs incorporated regulatory exemption expansion scenarios and raw material cost fluctuation bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated camera-monitor adoption or prolonged NHTSA glass-mirror mandate maintenance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive 3D Surface Display Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Weatherstrip Market