
 India Automotive Lighting Market | 2026-2036
India Automotive Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Lighting Market Insights
The Automotive Industry Standard AIS-008 revision from India's Ministry of Road Transport and Highways is expanding compliance requirements for headlamp photometric performance, compelling tier-1 suppliers to redesign optical architectures. Lumax Industries Limited leverages its Chakan manufacturing base to sustain proximity supply relationships with domestic OEMs. Varroc Engineering Limited anchors its position through backward integration into reflector metallization and lens molding. Koito Manufacturing Co., Ltd. competes on technology transfer from its parent, occupying the premium LED projector segment for utility vehicles.
Automotive lighting encompasses electromechanical assemblies that generate, direct, and modulate visible electromagnetic radiation for vehicle illumination, signaling, and conspicuity, typically operating across 12-24V DC architectures with lumen outputs ranging from 300 lm for marker lamps to 3,000+ lm for adaptive driving beams. LED technology leads unit economics as thermal management advances and chip-on-board packaging cuts bill-of-materials costs, while halogen persists in two-wheeler price-sensitive tiers where replacement frequency sustains aftermarket volume. OEM channels dominate value capture given design-in cycles and validation protocols, though fleet operator direct procurement is gaining traction as total-cost-of-ownership analytics penetrate commercial vehicle operations.
Bureau of Indian Standards certification under IS 15500, Central Motor Vehicles Rules enforcement by state transport authorities, and PLI scheme incentives for advanced automotive electronics collectively shape product development roadmaps and factory location decisions. The Automotive Research Association of India conducts homologation testing that gates market access, compressing timelines for foreign design adaptations. Stakeholders must monitor BIS alignment with UN ECE regulations to anticipate harmonization-driven specification changes.
Market Dynamics
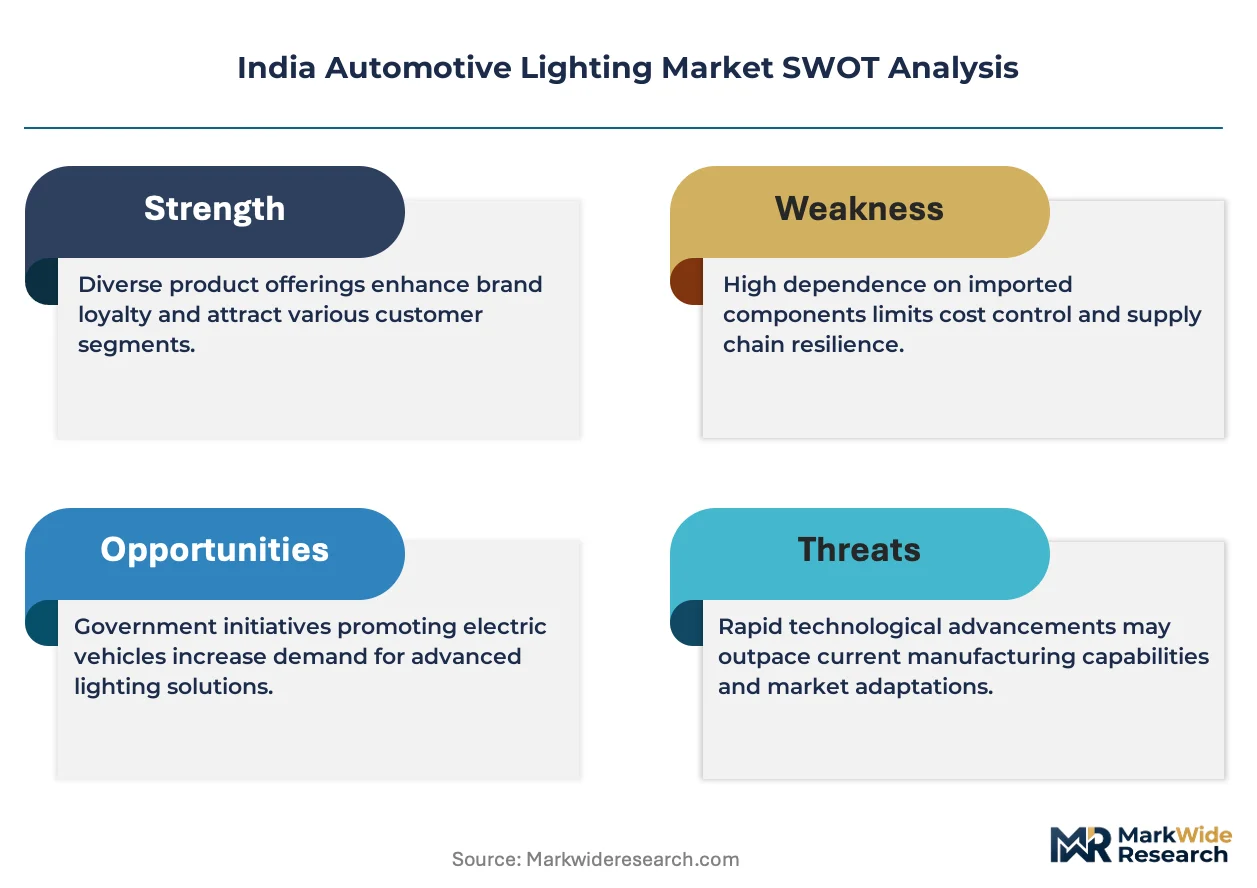
LED thermal management breakthroughs are compressing replacement cycles across India's commercial vehicle fleet, while BIS energy-efficiency mandates force synchronous redesigns across tier-1 supplier portfolios.
Growth Catalysts
- PLI scheme incentives:India's Production Linked Incentive scheme for advanced automotive electronics subsidizes domestic LED module assembly, lowering capital barriers for local manufacturing scale-up.
- Maharashtra corridor concentration:Pune-Aurangabad's OEM assembly density creates procurement gravity, pulling lighting suppliers into captive supply relationships with shorter logistics loops.
- Chip-on-board packaging:Thermal efficiency gains from COB architectures cut bill-of-materials costs, enabling LED penetration into price-sensitive two-wheeler tiers previously served by halogen.
Market Restraints
- Reflector metallization supply concentration:Backward integration into vacuum-deposited aluminum coatings remains limited to three domestic suppliers, creating single-source vulnerability for optical component sourcing.
- Homologation timeline compression:ARAI testing protocols for AIS-008 compliance extend validation cycles by 4-6 months, delaying revenue recognition for redesigned headlamp architectures.
- Copper thermal substrate volatility:LED module baseplate materials face price swings tied to global copper concentrate markets, squeezing gross margins on fixed-price OEM contracts.
Strategic Opportunities
- Tamil Nadu electronics manufacturing cluster:Sriperumbudur's semiconductor packaging ecosystem offers untapped LED driver IC integration capacity for lighting system suppliers seeking vertical control.
- Adaptive driving beam regulatory alignment:BIS consideration of UN ECE R123 amendments for matrix LED headlamps creates first-mover advantage for suppliers with pre-validated optical designs.
- Fleet operator direct procurement:Total-cost-of-ownership analytics penetration among logistics operators opens bypass channels around traditional OEM-aftermarket distribution hierarchies.
Industry Challenges
- Optical simulation talent scarcity:Ray-tracing expertise for photometric compliance modeling concentrates in ARAI-affiliated labs, constraining supplier in-house validation capacity.
- Legacy 12V architecture integration:Higher-lumen LED modules demand voltage booster circuits that complicate wiring harness compatibility with existing vehicle electrical platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Lighting Market |
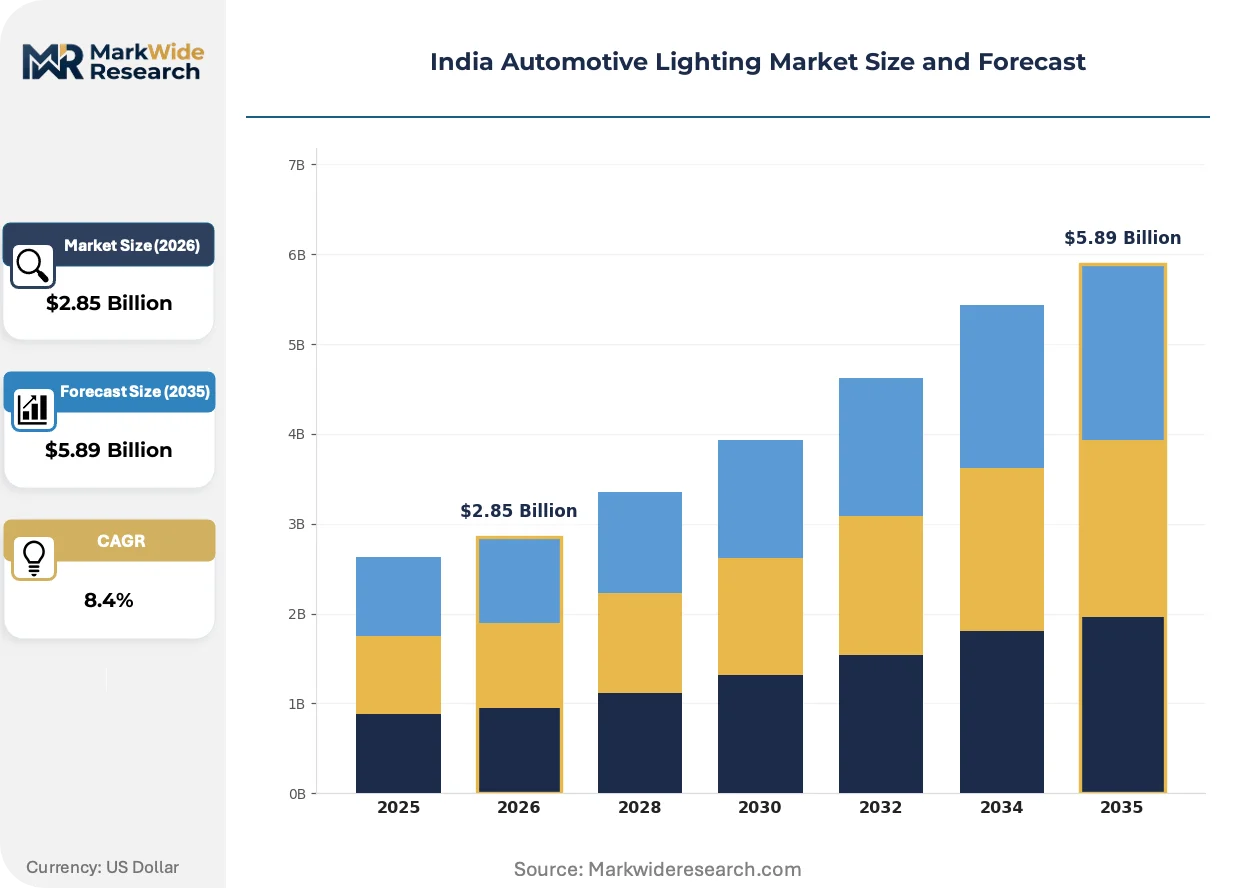
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlamps, Taillights, Fog Lights, Daytime Running Lights Technology: LED, Halogen, Xenon, OLED End User: OEMs, Aftermarket, Fleet Operators, Commercial Vehicles Application: Passenger Cars, Two-Wheelers, Trucks, Buses |
| Companies Covered | Osram India Private Limited, Koito Manufacturing Co., Ltd., Lumax Industries Limited, Varroc Engineering Limited, Magneti Marelli S.p.A., Uno Minda Limited, Valeo India Private Limited, Fiem Industries Ltd., Hella India Lighting Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Lighting Market Trends and Innovations
Photonic engineering advances are collapsing the performance gap between premium projector systems and standard reflector designs, redistributing value capture across supplier tiers.
Matrix LED technology is expanding into mid-segment utility vehicles as micro-optic arrays enable glare-free high-beam functionality without mechanical shutter mechanisms. Mahindra & Mahindra's Scorpio-N and similar UV platforms now specify partial-matrix modules previously reserved for luxury imports. This capability migration is compressing price premiums for adaptive lighting, forcing tier-1 suppliers to differentiate through software-defined beam patterns rather than hardware complexity alone.
AIS-008 revision enforcement by India's Ministry of Road Transport and Highways mandates stricter cutoff line precision and expanded test points for headlamp photometric distribution. Tier-1 suppliers must redesign optical architectures to meet these expanded compliance requirements, with particular impact on projector lens curvature specifications. The regulation accelerates obsolescence of legacy reflector designs that cannot achieve the required beam sharpness without complete tooling replacement.
Commercial fleet operators in Gujarat and Karnataka are consolidating lighting procurement through direct supplier contracts rather than aftermarket distributor networks. These buyers now specify lumen maintenance warranties and predictive replacement schedules based on operating hour analytics. The shift disintermediates traditional parts retailers and transfers inventory carrying costs to lighting manufacturers willing to consign stock at fleet depots.
India Automotive Lighting Market Segmentation
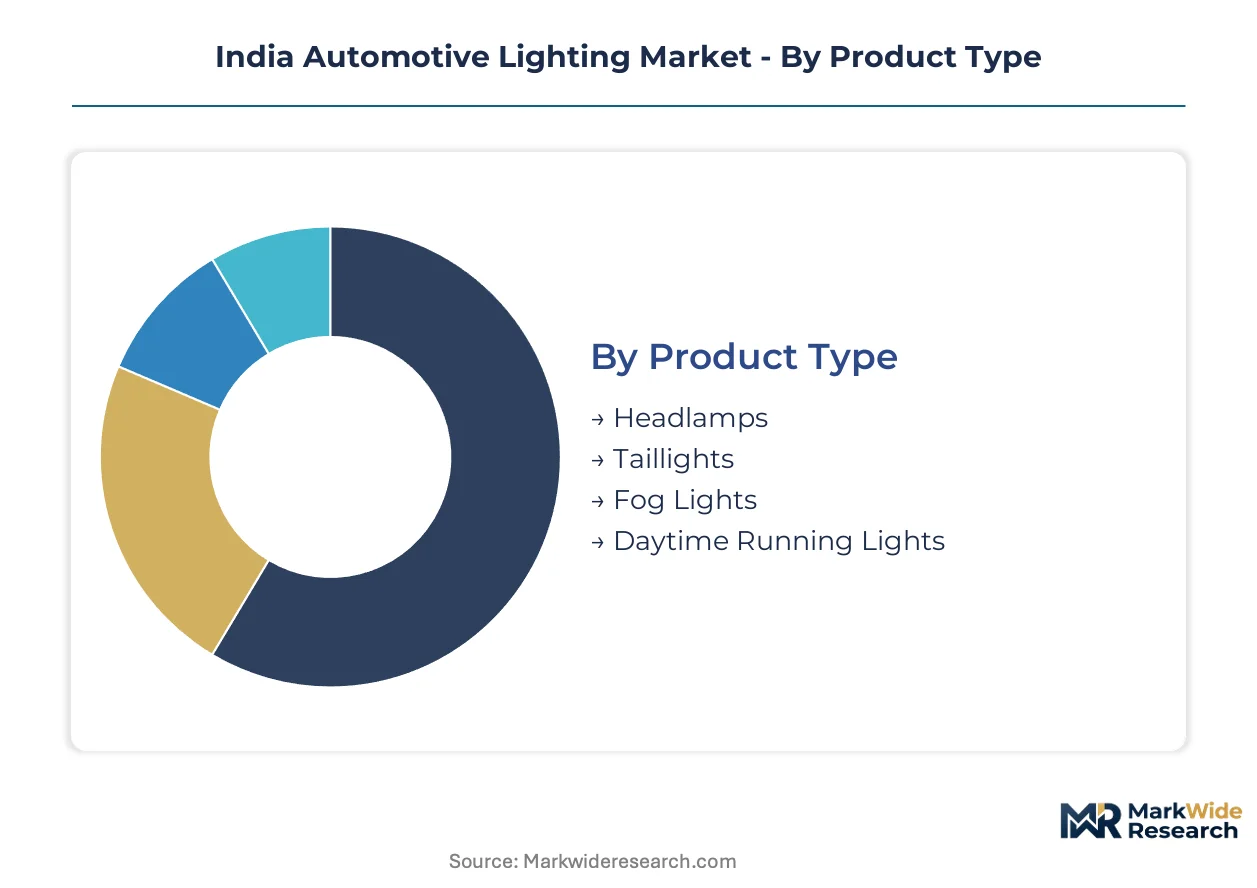
Segmentation in India's automotive lighting market reveals how capital deployment, regulatory pressure, and vehicle electrification reshape supplier priorities. Each dimension—product, technology, end user, and application—carries distinct margin profiles and tooling requirements that determine competitive positioning.
Product Type:
Headlamps demand the heaviest upfront capital commitment due to precision optical tooling and ARAI homologation testing cycles.
- Headlamps:Projector and reflector assemblies incorporating precision-molded polycarbonate lenses and metallized substrates. Maharashtra's Pune-Aurangabad corridor concentrates procurement for UV and passenger car platforms where AIS-008 compliance mandates optical redesigns.
- Taillights:LED strip and combination lamp modules with sequential signaling capability. Tamil Nadu's Sriperumbudur electronics cluster feeds driver IC integration for premium passenger car specifications.
- Fog Lights:Auxiliary beam units optimized for low-visibility conditions with wide dispersion patterns.
- Daytime Running Lights:Low-power conspicuity modules increasingly mandated under CMVR safety provisions.
Headlamps absorb the bulk of installed capacity; Daytime Running Lights are expanding most quickly.
Technology:
Technology choice determines thermal management investment and semiconductor content, with LED requiring the most sophisticated substrate engineering.
- LED:Chip-on-board and discrete emitter architectures with aluminum or copper thermal baseplates. Fleet operators in Gujarat and Karnataka drive retrofit demand as operating hour analytics justify lumen maintenance warranties.
- Halogen:Tungsten-halogen filament technology in standardized H4 and H7 formats. Two-wheeler OEMs in Maharashtra specify these for entry price points where replacement frequency sustains aftermarket volume.
- Xenon:High-intensity discharge systems with ballast-controlled arc discharge.
- OLED:Organic electroluminescent panels enabling thin-form taillight signatures.
LED commands dominant production share; OLED is gaining share fastest among emerging architectures.
End User:
Customer type shapes contract structure, with OEM channels locking in design-in validation cycles and fleet buyers demanding outcome-based procurement terms.
- OEMs:Design-in supply relationships with tier-1 suppliers validated through ARAI homologation. Maharashtra's captive supply networks shorten logistics loops for just-in-sequence delivery to assembly plants.
- Aftermarket:Replacement channel serving independent workshops and retail distributors. Price-sensitive halogen volume concentrates here for two-wheeler and aging passenger car parc.
- Fleet Operators:Direct procurement contracts with lumen maintenance warranties and predictive replacement schedules.
- Commercial Vehicles:Heavy-duty specifications for trucks and buses with vibration-resistant housing designs.
OEMs absorb the bulk of installed capacity; Fleet Operators are climbing the fastest as total-cost-of-ownership analytics penetrate logistics operations.
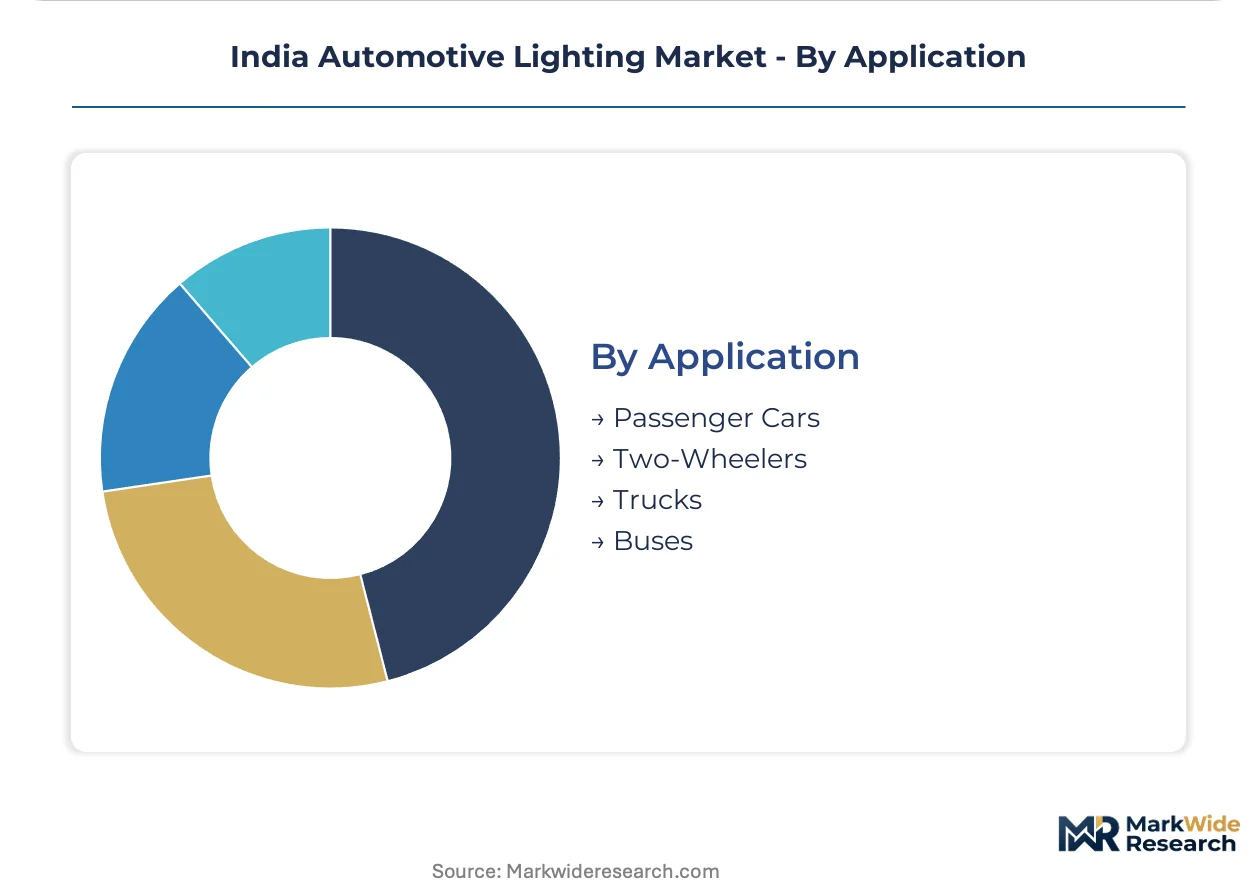
Application:
Application segments diverge in specification intensity, with passenger cars requiring the most complex adaptive lighting features.
- Passenger Cars:Multi-module front and rear lighting with matrix LED and partial-matrix functionality. Mahindra & Mahindra's Scorpio-N and similar UV platforms now specify partial-matrix modules previously reserved for luxury imports.
- Two-Wheelers:Compact headlamp and taillight units prioritizing cost efficiency and durability. Halogen persists here where chip-on-board LED cost curves have not yet displaced incumbent technology.
- Trucks:High-lumen forward lighting with extended beam throw for highway operation.
- Buses:Interior and exterior lighting packages with emergency egress illumination requirements.
Passenger Cars absorb the bulk of installed capacity; Trucks are expanding most quickly as commercial fleet renewal accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors India's automotive lighting procurement through its dense OEM assembly concentration along the Pune-Aurangabad corridor. This Maharashtra industrial belt generates captive supply relationships that compress logistics loops for just-in-sequence delivery. State-level industrial policies and Central Motor Vehicles Rules enforcement create localized regulatory gravity that shapes factory location decisions across tier-1 supplier networks.
Maharashtra
Passenger car and utility vehicle OEMs in Pune-Aurangabad drive concentrated demand for headlamp and taillight modules. The state's industrial promotion schemes subsidize capital equipment for LED assembly lines. Chakan's supplier park hosts Lumax Industries Limited's manufacturing base, sustaining proximity relationships with domestic vehicle manufacturers.
Gujarat
Commercial fleet operators in Ahmedabad-Surat consolidate direct procurement contracts with lumen maintenance warranties. Gujarat's port infrastructure enables faster import clearance for LED driver ICs and thermal substrates. Sanand's automotive zone attracts lighting suppliers seeking western India distribution reach.
Karnataka
Bengaluru's commercial vehicle fleet operators adopt predictive replacement schedules based on operating hour analytics. The state's electronics manufacturing clusters under the PLI scheme feed semiconductor packaging capacity for lighting system integration. Hosur's industrial belt concentrates two-wheeler lighting demand where halogen replacement cycles sustain aftermarket volume.
Tamil Nadu
Sriperumbudur's semiconductor ecosystem offers LED driver IC integration capacity for lighting suppliers seeking vertical control. Tamil Nadu's industrial policy incentives target advanced automotive electronics manufacturing. Oragadam's supplier parks host module assembly operations serving Chennai-based OEMs.
Haryana
Manesar's automotive corridor generates demand for heavy-duty truck lighting with vibration-resistant housing designs. Haryana's freight logistics density supports fleet operator procurement consolidation. The state's proximity to Delhi-NCR aftermarket distribution channels enables rapid spare parts replenishment.
India Automotive Lighting Market Competitive Landscape
The competitive structure tilts toward integrated tier-1 suppliers with captive OEM relationships. Domestic players with backward integration into reflector metallization and lens molding defend margin positions against multinational technology licensors. Two strategic archetypes dominate: integrated domestic manufacturers with full optical component production, and technology-transfer-dependent affiliates of global lighting specialists. Capacity expansion near OEM assembly clusters and portfolio diversification into LED electronics represent the prevailing competitive moves.
Among India-based integrated manufacturers, Lumax Industries Limited and Varroc Engineering Limited exemplify the domestic archetype with captive supply relationships. Koito Manufacturing Co., Ltd. occupies the multinational technology-transfer position, representing premium LED projector specialization. These three anchors illustrate how geographic proximity to Maharashtra's automotive corridor and optical component integration depth determine competitive positioning.
| Leading Market Players |
|---|
| Osram India Private Limited |
| Koito Manufacturing Co., Ltd. |
| Lumax Industries Limited |
| Varroc Engineering Limited |
| Magneti Marelli S.p.A. |
| Uno Minda Limited |
| Valeo India Private Limited |
| Fiem Industries Ltd. |
| Hella India Lighting Ltd. |
| Others |
Pricing and Supply Chain Analysis
Copper thermal substrate indices cascade through LED module baseplate costs into three-tier pricing structures across premium, standard, and economy levels. OEMs in Maharashtra's Pune-Aurangabad corridor absorb volatility through long-term offtake agreements, while aftermarket channels transmit spot-price swings directly to replacement buyers.
Pricing Analysis
Lumen maintenance warranties anchor value-based pricing for fleet operator contracts, with Gujarat and Karnataka logistics buyers specifying predictive replacement schedules tied to operating hour analytics. Price differentiation rests on ARAI homologation certification tier and thermal management performance grade, with premium projector modules commanding wider margins than reflector assemblies. Cost compression in standard-tier LED retrofits is intensifying because chip-on-board packaging cuts bill-of-materials costs. Two-wheeler OEMs in Maharashtra exhibit highest price sensitivity, while commercial fleet operators prioritize total-cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for vacuum-deposited aluminum reflector coatings mandate qualification across Lumax Industries Limited, Varroc Engineering Limited, and Koito Manufacturing Co., Ltd. facilities. Geographic supply concentration centers on India for lens molding and module assembly, Taiwan and South Korea for LED driver ICs, and Japan for premium optical components. Raw material dependencies include copper thermal baseplates, polycarbonate resin, and aluminum metallization feedstock. Single-source vulnerability in reflector metallization creates supply chain risk. Distribution runs through captive OEM supply relationships with just-in-sequence delivery to Maharashtra assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. India's AIS-008 revision from the Ministry of Road Transport and Highways creates a barrier-to-entry moat for tier-1 suppliers with validated optical architectures and ARAI homologation capacity.
For Market Incumbents: Anchor defensive positioning through backward integration into reflector metallization and lens molding to protect margin structures against commodity volatility. Capacity addition in Tamil Nadu's Sriperumbudur electronics cluster captures LED driver IC integration opportunities. Threat from matrix LED technology migration demands software-defined beam pattern investment to differentiate beyond hardware complexity. For New Entrants and Emerging Players: E-commerce fleet procurement platforms offer direct-channel routes around traditional OEM-aftermarket distribution hierarchies. White-space targets include Gujarat and Karnataka commercial vehicle operators consolidating lighting procurement through lumen maintenance warranties. Tamil Nadu semiconductor packaging ecosystem presents the most penetrable geography for vertical integration into LED electronics. Go-to-market angle should emphasize predictive replacement analytics and consignment inventory at fleet depots. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated domestic manufacturers with captive OEM relationships in Maharashtra's automotive corridor. Long-term viability over the projection horizon hinges on BIS alignment with UN ECE regulations for matrix LED headlamp compliance. Acquisition target archetype: tier-1 suppliers with ARAI-affiliated photometric validation capacity and backward integration into optical components. Signal to watch: BIS consideration of UN ECE R123 amendments for adaptive driving beam regulatory alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reflector Metallization | Captive supply of vacuum-deposited aluminum coatings insulates margin structures from single-source vulnerability. |
| LED Driver IC Integration in Tamil Nadu | Sriperumbudur semiconductor packaging ecosystem enables vertical control over lighting electronics supply. |
| ARAI Homologation Capacity Expansion | Accelerated validation timelines compress revenue recognition delays for redesigned headlamp architectures. |
| Fleet Operator Direct Procurement Partnerships | Gujarat and Karnataka logistics buyers bypass traditional distribution hierarchies through outcome-based contracts. |
| Software-Defined Beam Pattern Development | Matrix LED capability migration forces differentiation beyond hardware complexity in mid-segment utility vehicles. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and BIS certification records formed the secondary backbone, supplemented by customs records tracking LED module and thermal substrate imports. Primary interviews with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator maintenance directors combined with secondary validation through bottom-up and top-down triangulation. The analysis cross-referenced ARAI homologation timelines with PLI scheme incentive disbursements to calibrate supply-side capacity expansion assumptions.
Bottom-up modeling aggregated segment-level volume and value outputs across product type, technology, end user, and application dimensions, while top-down approaches validated aggregate market scale against vehicle production forecasts and content-per-vehicle estimates. CAGRs were derived from regression analysis of historical replacement cycles and projected technology penetration curves. Industry-specific forecast inputs included copper thermal substrate price volatility coefficients and BIS regulatory harmonization timelines with UN ECE standards.
The model holds under steady BIS enforcement of AIS-008 compliance and continued PLI scheme subsidy disbursement; deviation in copper concentrate market volatility or UN ECE regulatory alignment delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market