
 Automotive Connectivity Control Unit Market | 2026-2036
Automotive Connectivity Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Connectivity Control Unit Market Outlook
Aftermarket service revenue is reshaping margin capture across the automotive connectivity value chain. DENSO Corporation leverages its embedded systems heritage to sustain dominance in gateway module production for Japanese OEMs. Continental AG anchors European supply through specialized telematics control units that comply with UNECE cybersecurity mandates. Robert Bosch GmbH competes on manufacturing scale, operating integrated semiconductor-to-module facilities that reduce external dependency.
The automotive connectivity control unit is an embedded electronic module that manages vehicle-to-everything communication protocols, typically integrating multi-core processors with ASIL-D functional safety ratings and supporting over-the-air firmware updates. Its primary purpose is to enable secure data exchange between powertrain controllers, infotainment systems, and external cloud services while maintaining real-time deterministic performance. Telematics control units lead product type demand as fleet operators mandate remote diagnostics and stolen vehicle tracking. Ethernet technology displaces legacy CAN bus architectures in premium segments where camera and lidar data throughput requirements exceed megabit thresholds. Cloud-based deployment grows fastest among electric vehicle startups seeking subscription monetization paths.
NHTSA guidelines in the United States and UNECE WP.29 regulations in Europe mandate cybersecurity management systems and software update capabilities as type-approval prerequisites, forcing module redesigns and supplier certification investments. Japan's METI promotes connected vehicle standards through its SIP-adus automated driving program, creating procurement preferences for domestic Tier-1 modules. Stakeholders must monitor divergence between regional data sovereignty requirements and semiconductor supply resilience as dual constraints on platform architecture decisions.
Market Dynamics
Automotive connectivity control units face mounting pressure from UNECE WP.29 cybersecurity mandates that force hardware redesign cycles to compress from five years to eighteen months. Module suppliers must simultaneously certify ASIL-D functional safety and ISO/SAE 21434 security management, collapsing traditional development timelines.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:European type-approval requirements for software update management systems and intrusion detection create compulsory retrofit demand across existing vehicle fleets.
- Fleet Telematics Expansion:Commercial vehicle operators in Germany and the United States mandate remote diagnostics and predictive maintenance, pulling high-bandwidth gateway modules into mid-duty truck segments.
- Ethernet Backbone Migration:Sensor fusion requirements for lidar and camera arrays in premium electric vehicles drive 1 Gbps+ data throughput specifications that legacy CAN architectures cannot satisfy.
Market Restraints
- Semiconductor Supply Concentration:Advanced multi-core processors with automotive-grade qualification depend on Taiwan-based foundry capacity, exposing module production to single-point failure risks.
- Homologation Cost Escalation:Dual certification against ECE R10 electromagnetic compatibility and UNECE cybersecurity management systems raises non-recurring engineering outlays by multiples for Tier-2 suppliers.
- Functional Safety-Performance Tradeoff:ASIL-D redundancy requirements impose deterministic latency floors that constrain real-time processing headroom for over-the-air update orchestration.
Strategic Opportunities
- Software-Defined Vehicle Platforms:Electric vehicle startups in the United States pursue subscription-based feature activation, creating recurring revenue attachment for connectivity modules with flexible compute partitioning.
- India PLI Scheme for Automotive Electronics:Production-linked incentive structures for advanced automotive technology components attract module assembly investments serving domestic OEM export programs.
- V2X Infrastructure Deployment:Japan's SIP-adus automated driving program funds roadside unit installations that require compatible onboard communication controllers in participating vehicle populations.
Industry Challenges
- Embedded Security Engineering Talent Scarcity:ISO/SAE 21434-certified systems architects command premium compensation, constraining supplier scaling velocity.
- Legacy Powertrain Integration Friction:Controller area network gateways in internal combustion platforms resist seamless migration to service-oriented Ethernet architectures without full electrical system redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Connectivity Control Unit Market |
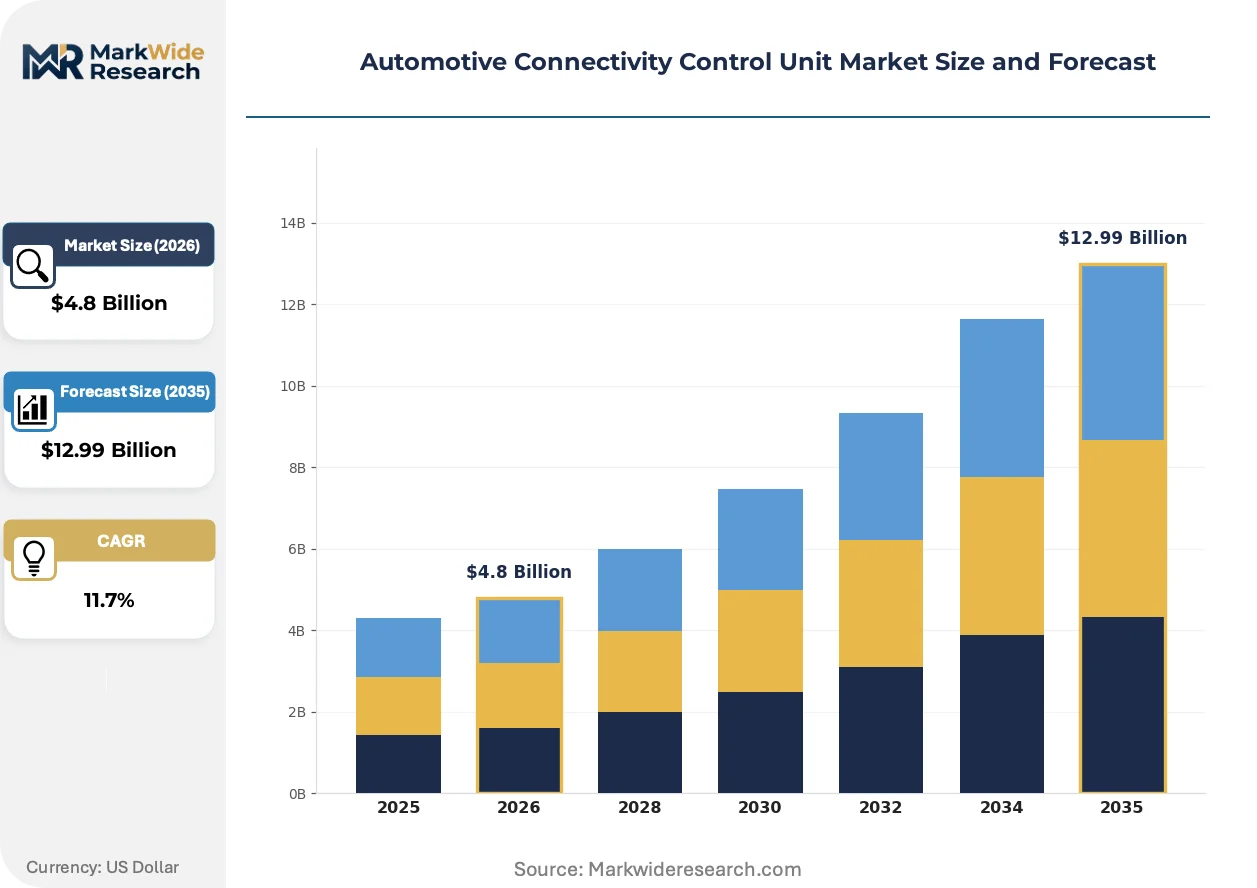
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics Control Unit, Body Control Module, Head Unit, Gateway Module Technology: Bluetooth, Wi-Fi, Cellular, Ethernet End User: Original Equipment Manufacturers, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Deployment: On-Premises, Cloud-Based, Hybrid, Integrated |
| Companies Covered | DENSO Corporation, Panasonic Corporation, Continental AG, Alpine Electronics, Inc., Visteon Corporation, Robert Bosch GmbH, Aptiv PLC, NXP Semiconductors, HARMAN International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Connectivity Control Unit Market Strategic Shifts
Module architecture is pivoting from fixed-function gateways to software-defined platforms that partition safety-critical and infotainment workloads on shared silicon. This convergence compresses supplier tier boundaries and forces semiconductor vendors into direct OEM relationships.
Ethernet-based vehicle networking is migrating from proprietary automotive PHY implementations to standardized IEEE 802.3ch multi-gigabit physical layers. Premium electric vehicle platforms in Germany and California adopt 2.5/5/10 Gbps switched backbones to accommodate raw camera and radar data streams without pre-processing compression. This shift collapses the traditional domain controller hierarchy into zonal architectures that consolidate connectivity, power distribution, and sensor aggregation at each vehicle corner.
NHTSA guidelines in the United States now incorporate UNECE WP.29 cybersecurity provisions by reference, creating transatlantic regulatory convergence for software update capabilities. Module suppliers must implement cryptographic hardware security modules and secure boot chains as baseline features rather than premium options. Japanese OEMs serving both markets accelerate unified platform development to avoid regional SKU fragmentation.
Fleet procurement contracts increasingly specify outcome-based uptime guarantees rather than unit-based hardware purchases. Commercial vehicle operators in the United States negotiate total cost-per-mile connectivity subscriptions that bundle hardware, cellular data, and predictive analytics. This model transfers obsolescence risk to Tier-1 suppliers and rewards module designs with field-upgradable compute resources.
Automotive Connectivity Control Unit Market Segmentation
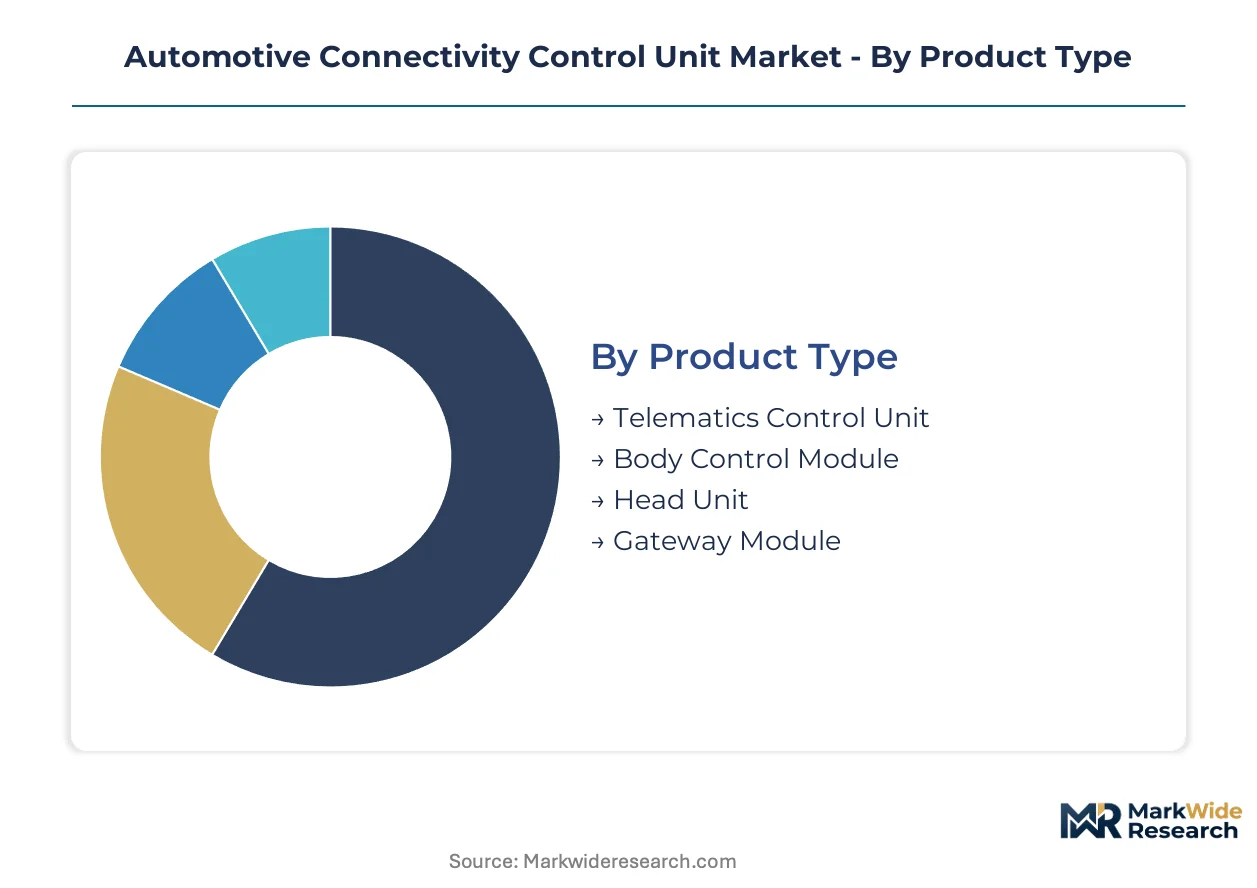
Connectivity module procurement splits sharply between long-cycle hardware platforms and rapidly evolving software stacks. Understanding segment velocity helps suppliers calibrate R&D allocation against certification timelines and fleet operator refresh rates.
Product Type:
Telematics control units and gateway modules turn over fastest as cybersecurity mandates force redesigns, while head units and body control modules follow slower vehicle platform cycles.
- Telematics Control Unit:Embedded module integrating cellular modems with GPS receivers and accelerometers for remote diagnostics and stolen vehicle tracking. Fleet operators in Germany and the United States mandate these units for commercial vehicle compliance, pulling demand into mid-duty truck segments where predictive maintenance contracts dominate procurement.
- Gateway Module:Centralized routing hub translating between legacy CAN buses and Ethernet backbones while enforcing domain isolation. Japanese OEMs prioritize gateway modules with ASIL-D ratings for autonomous driving platforms, creating procurement concentration around METI's SIP-adus program requirements.
- Body Control Module:Distributed controller managing door locks, lighting, and climate interfaces with limited external connectivity.
- Head Unit:Infotainment-integrated module combining touchscreen interfaces with smartphone projection protocols.
Gateway modules anchor the volume base while telematics control units gain share at the steepest rate.
Technology:
Cost tiers separate premium Ethernet deployments from commodity wireless protocols, with cellular occupying the mid-tier where subscription revenue justifies hardware investment.
- Ethernet:Switched IEEE 802.3ch backbone operating at 1 Gbps and above to transport uncompressed camera and lidar data streams. Premium electric vehicle platforms in Germany adopt multi-gigabit architectures that collapse traditional domain hierarchies into zonal designs at each vehicle corner.
- Cellular:4G LTE and 5G NR modems enabling over-the-air firmware updates and cloud telemetry pipelines. Fleet operators negotiate outcome-based uptime guarantees that bundle cellular data with predictive analytics, transferring obsolescence risk to Tier-1 suppliers.
- Bluetooth:Short-range wireless protocol for smartphone pairing and key fob authentication.
- Wi-Fi:Higher-throughput wireless for in-vehicle hotspot services and dealer diagnostic tools.
Cellular technology anchors the volume base while Ethernet gains share at the steepest rate.
End User:
Customer type determines margin structure, with fleet operators commanding outcome-based pricing and aftermarket providers competing on installation speed.
- Fleet Operators:Commercial vehicle managers procuring connectivity as total cost-per-mile subscriptions rather than capital hardware. United States-based logistics companies specify remote diagnostics and predictive maintenance as contract prerequisites, forcing module designs with field-upgradable compute resources.
- Original Equipment Manufacturers:Vehicle brand owners integrating modules at platform design phase with seven-to-ten-year production commitments. German OEMs co-locate engineering centers with Tier-1 suppliers to compress development timelines for UNECE WP.29 compliance.
- Aftermarket Providers:Independent installers serving vehicle owners outside warranty periods with retrofit telematics.
- Vehicle Assemblers:Contract manufacturers requiring module standardization across multiple brand portfolios.
Original equipment manufacturers anchor the volume base while fleet operators gain share at the steepest rate.
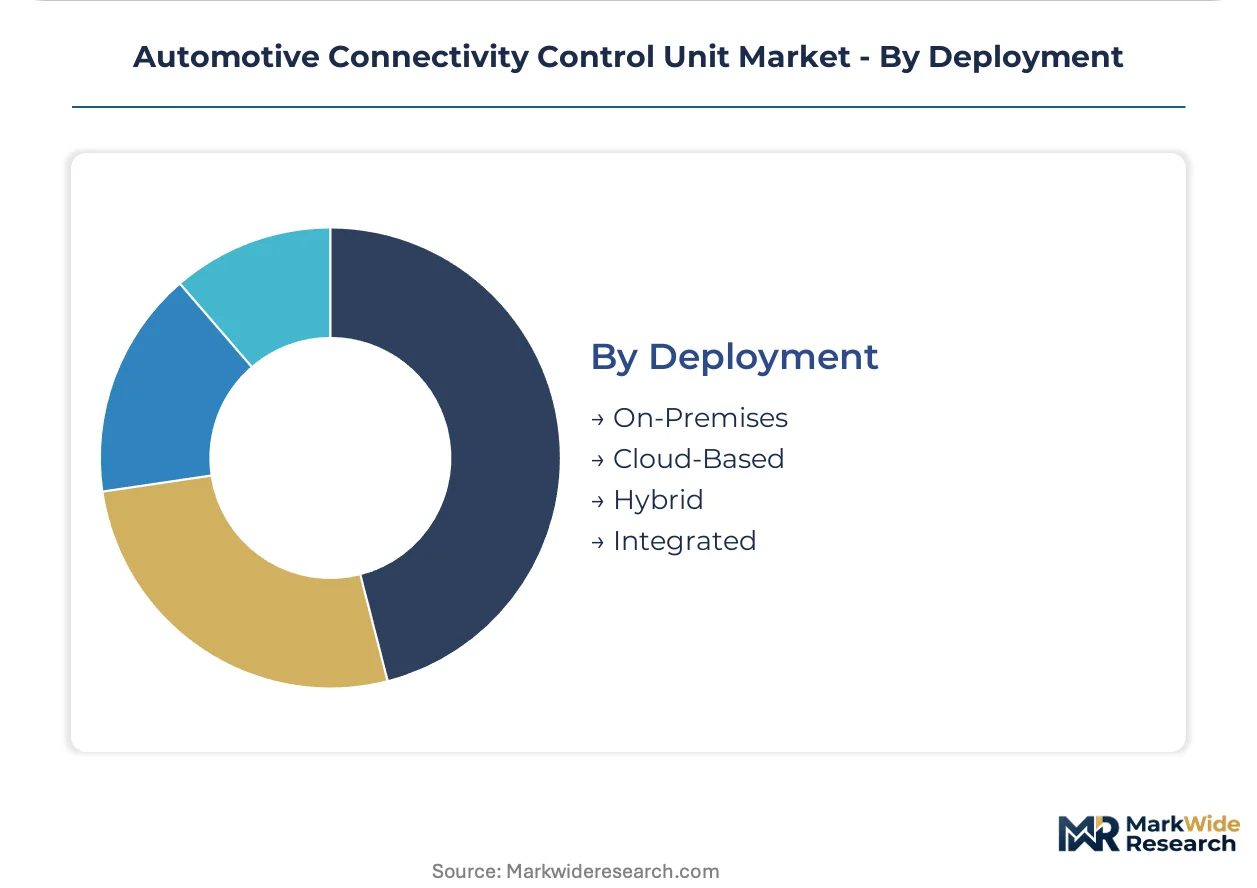
Deployment:
Maturity gradients separate established on-premises architectures from emerging cloud-native platforms favored by electric vehicle startups.
- Cloud-Based:Fully managed connectivity stack with edge computing offloaded to remote data centers. Electric vehicle startups in the United States pursue subscription-based feature activation, creating recurring revenue attachment for modules with flexible compute partitioning and over-the-air orchestration capabilities.
- Hybrid:Split architecture running safety-critical functions locally while pushing analytics to cloud infrastructure. This configuration satisfies NHTSA guidelines for cybersecurity management systems without full dependency on external connectivity.
- On-Premises:Self-hosted infrastructure maintained by fleet operators with dedicated data sovereignty requirements.
- Integrated:Module embedded within broader vehicle domain controller with shared silicon resources.
Hybrid deployment anchors the volume base while cloud-based configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany demonstrate the lowest price elasticity, accepting premium hardware costs for UNECE-compliant modules, while aftermarket providers in India compete primarily on installation speed and unit economics. This demand-elasticity contrast shapes supplier investment allocation across development centers.
United States
Commercial vehicle fleets mandate remote diagnostics and predictive maintenance subscriptions, pulling high-bandwidth gateway modules into mid-duty truck segments. NHTSA guidelines incorporate UNECE WP.29 cybersecurity provisions by reference, creating transatlantic regulatory convergence. Engineering clusters in Michigan and California co-locate Tier-1 development centers with electric vehicle startups pursuing software-defined architectures.
Germany
Premium electric vehicle platforms adopt multi-gigabit Ethernet backbones to accommodate uncompressed camera and lidar data streams. ECE R10 electromagnetic compatibility and UNECE WP.29 cybersecurity mandates force eighteen-month hardware redesign cycles. Stuttgart and Ingolstadt host concentrated supplier engineering centers compressing development timelines for domestic OEM compliance programs.
Japan
METI's SIP-adus automated driving program creates procurement preferences for domestic Tier-1 modules with ASIL-D functional safety ratings. Japanese OEMs serving both United States and European markets accelerate unified platform development to avoid regional SKU fragmentation. Nagoya and Tokyo corridors anchor gateway module production for autonomous driving platforms.
China
Domestic electric vehicle manufacturers pursue subscription-based feature activation, creating recurring revenue attachment for modules with flexible compute partitioning. MIIT promotes connected vehicle standards through national intelligent vehicle innovation centers. Shenzhen and Shanghai clusters concentrate semiconductor-to-module integration facilities reducing external dependency.
India
Production-linked incentive structures for advanced automotive technology components attract module assembly investments serving domestic OEM export programs. Fleet operators in logistics corridors negotiate total cost-per-mile connectivity subscriptions transferring obsolescence risk to Tier-1 suppliers. Tamil Nadu and Gujarat host emerging electronics manufacturing zones targeting automotive tier supply.
Automotive Connectivity Control Unit Market Competitive Environment
Diversified industrial conglomerates and specialized automotive electronics suppliers split the market into distinct capability tiers. Tier-1 system integrators with embedded systems heritage dominate gateway module production for established OEM relationships. Semiconductor-to-module vertically integrated players compete on manufacturing scale and supply security. The dominant competitive moves involve co-location of engineering centers with major vehicle assemblers and accelerated certification investments for dual ASIL-D and ISO/SAE 21434 compliance.
Within the diversified conglomerate tier, DENSO Corporation and Robert Bosch GmbH exemplify players leveraging manufacturing scale and captive semiconductor capabilities. Continental AG occupies a position representing European regulatory specialization, anchoring supply through telematics control units aligned with UNECE mandates. These three entities sit within distinct strategic postures: Japanese heritage in embedded systems, German vertical integration, and European compliance engineering.
| Leading Market Players |
|---|
| DENSO Corporation |
| Panasonic Corporation |
| Continental AG |
| Alpine Electronics, Inc. |
| Visteon Corporation |
| Robert Bosch GmbH |
| Aptiv PLC |
| NXP Semiconductors |
| HARMAN International |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at Taiwan-based automotive-grade foundries compresses supplier bargaining power and inflates module pricing premiums for ASIL-D certified silicon. Tier-1 suppliers pass input cost volatility through to OEMs via long-term offtake agreements with price-adjustment clauses, while fleet operators absorb premium hardware costs in exchange for outcome-based uptime guarantees.
Pricing Analysis
After-sales service revenue from predictive maintenance subscriptions drives lifetime value capture for connectivity module suppliers. Pricing stratifies across ASIL-D certified premium tiers, ISO/SAE 21434 security-compliant mid-tiers, and economy gateway modules serving aftermarket retrofit demand. Cost compression in economy tiers intensifies because Chinese module assemblers leverage PLI scheme subsidies to undercut European pricing. Fleet operators demonstrate the lowest price sensitivity, accepting premium hardware costs for UNECE WP.29 compliant modules with field-upgradable compute resources.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit capacity expansion for automotive multi-core processors at Taiwan and South Korea foundries. Module production draws from Taiwan for advanced node silicon, Germany for automotive-grade assembly and testing, and Japan for ASIL-D certified microcontroller supply. Raw material dependencies include automotive-grade epoxy resins, high-reliability ceramic capacitors, and multi-layer printed circuit board substrates. Single-source vulnerability concentrates at Taiwan-based foundries serving 5nm and 7nm automotive processor demand. Distribution runs through Tier-1 system integrators co-located with OEM engineering centers in Stuttgart, Nagoya, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
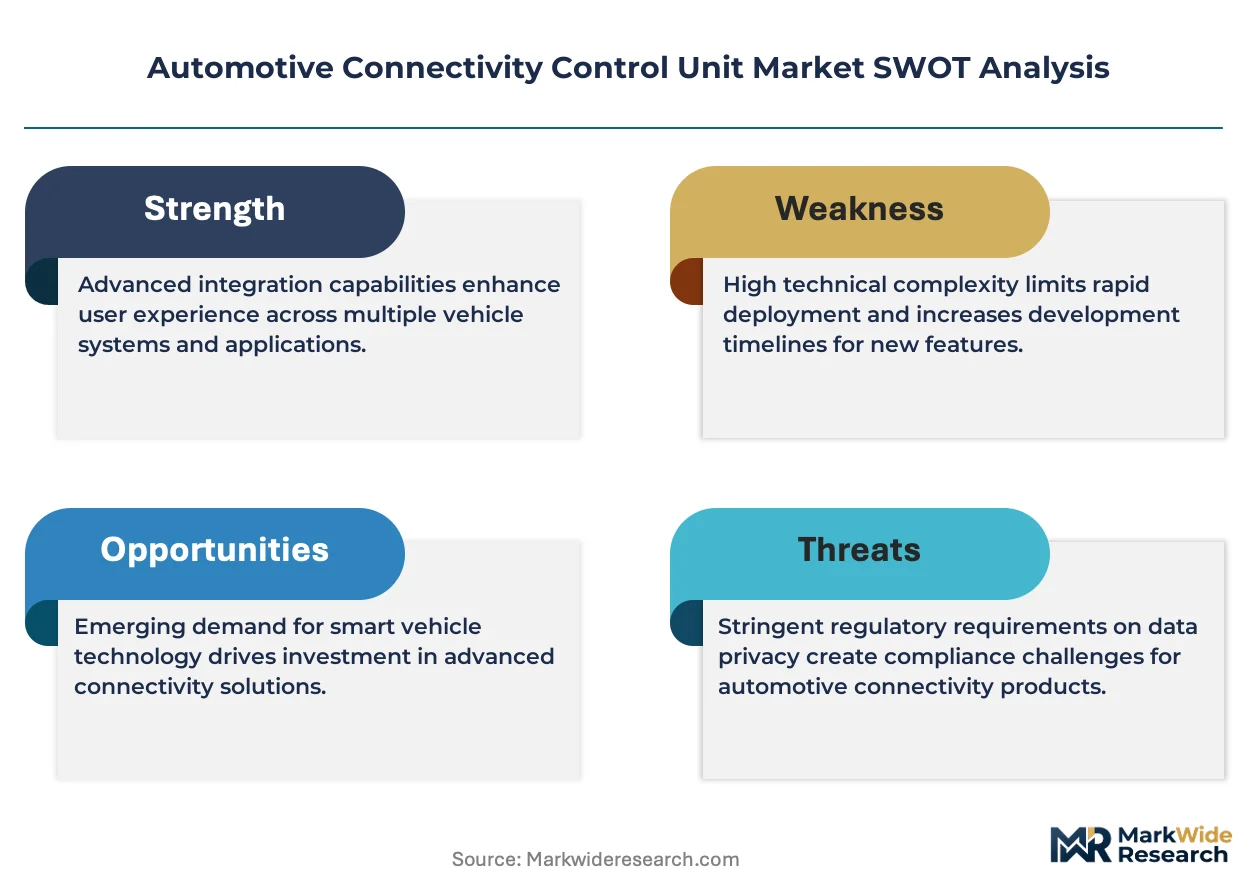
ISO/SAE 21434 certified security architects represent the critical capability gap constraining supplier scaling velocity, with fewer than five thousand qualified engineers available across the major automotive electronics clusters. Module suppliers must secure this talent pool before UNECE WP.29 mandates force eighteen-month redesign cycles across all product tiers.
For Market Incumbents: Build certification moats around dual ASIL-D and ISO/SAE 21434 compliance to lock out Tier-2 competitors facing homologation cost escalation. Deepen backward integration into automotive-grade semiconductor packaging to reduce Taiwan foundry dependency. Co-locate security engineering centers with German OEMs to compress UNECE WP.29 development timelines below competitor benchmarks. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme subsidized module assembly serving domestic OEM export programs. Target aftermarket retrofit telematics for commercial vehicle fleets in United States logistics corridors where predictive maintenance contracts dominate procurement. Pursue direct OEM relationships with electric vehicle startups seeking cloud-based deployment with subscription monetization paths. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers with fleet operator outcome-based contracts transferring obsolescence risk from buyers. Long-term viability hinges on software-defined vehicle platform positioning with flexible compute partitioning capabilities. Acquisition targets should demonstrate captive semiconductor supply relationships or ASIL-D certification infrastructure. Watch for inflection signals in Ethernet backbone adoption rates across premium electric vehicle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables subscription-based feature activation for electric vehicle startups in California and Germany. |
| ASIL-D Certification Infrastructure | Accelerates UNECE WP.29 compliance timelines for Japanese OEM unified platform development. |
| Geographic Manufacturing Footprint | Locates module assembly in India's Tamil Nadu electronics zones to serve PLI export programs. |
| Semiconductor Supply Agreement | Secures automotive-grade processor allocation from Taiwan foundries amid capacity constraints. |
| Charging Infrastructure Partnership | Integrates V2X communication controllers with Japan's SIP-adus roadside unit deployment. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operator telematics managers; and secondary validation through vehicle production databases, IHS Markit registration data, SEC automotive electronics filings, and UNECE regulatory submission records. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Forecast inputs considered vehicle electrification penetration, Ethernet backbone adoption across premium segments, and fleet telematics mandate expansion. Segmentation dimensions modeled include product type hierarchy, technology protocol migration, end-user procurement model, and deployment architecture evolution. CAGRs were derived from installed base growth rates and content-per-vehicle trajectories across the projection horizon.
Stress conditions across semiconductor supply availability, regulatory certification timeline compression, and fleet operator subscription conversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about UNECE WP.29 implementation schedules and Taiwan foundry capacity expansion plans. Material shifts in export control regimes or automotive cybersecurity mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market