
 Automotive Split-View Camera Module Market | 2026-2036
Automotive Split-View Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Split-View Camera Module Market Analysis
The premium-commodity split in automotive split-view camera modules is rebalancing around image-processing fidelity and thermal stability rather than pixel count alone. Denso Corporation leverages its captive semiconductor capacity to control sensor-to-module integration. Bosch competes through its dominance in radar-camera fusion architectures for European OEMs. Continental anchors its position with manufacturing scale across multiple vehicle classes.
Automotive split-view camera modules integrate dual-lens arrays with synchronized image sensors to generate composite surround-view outputs for driver assistance and parking systems; typical assemblies operate across temperature ranges from minus forty to eighty-five degrees Celsius with latency below fifty milliseconds. The multi-view camera segment leads unit shipments as automakers consolidate four discrete cameras into unified processing chains. High-definition technology captures the fastest growth trajectory, displacing analog architectures in new vehicle platforms. OEM end users concentrate procurement volume, while aftermarket suppliers occupy margin-diluted replacement channels.
NHTSA mandates rear-visibility standards for light vehicles sold in the United States, while Euro NCAP protocols reward split-view coverage with safety-score premiums that OEMs prioritize in platform design. ECE R46 regulations govern mirror-replacement camera systems across European type approvals, creating compliance barriers for non-certified suppliers. Stakeholders must monitor how software-defined vehicle architectures shift image-processing loads from dedicated modules to centralized compute domains.
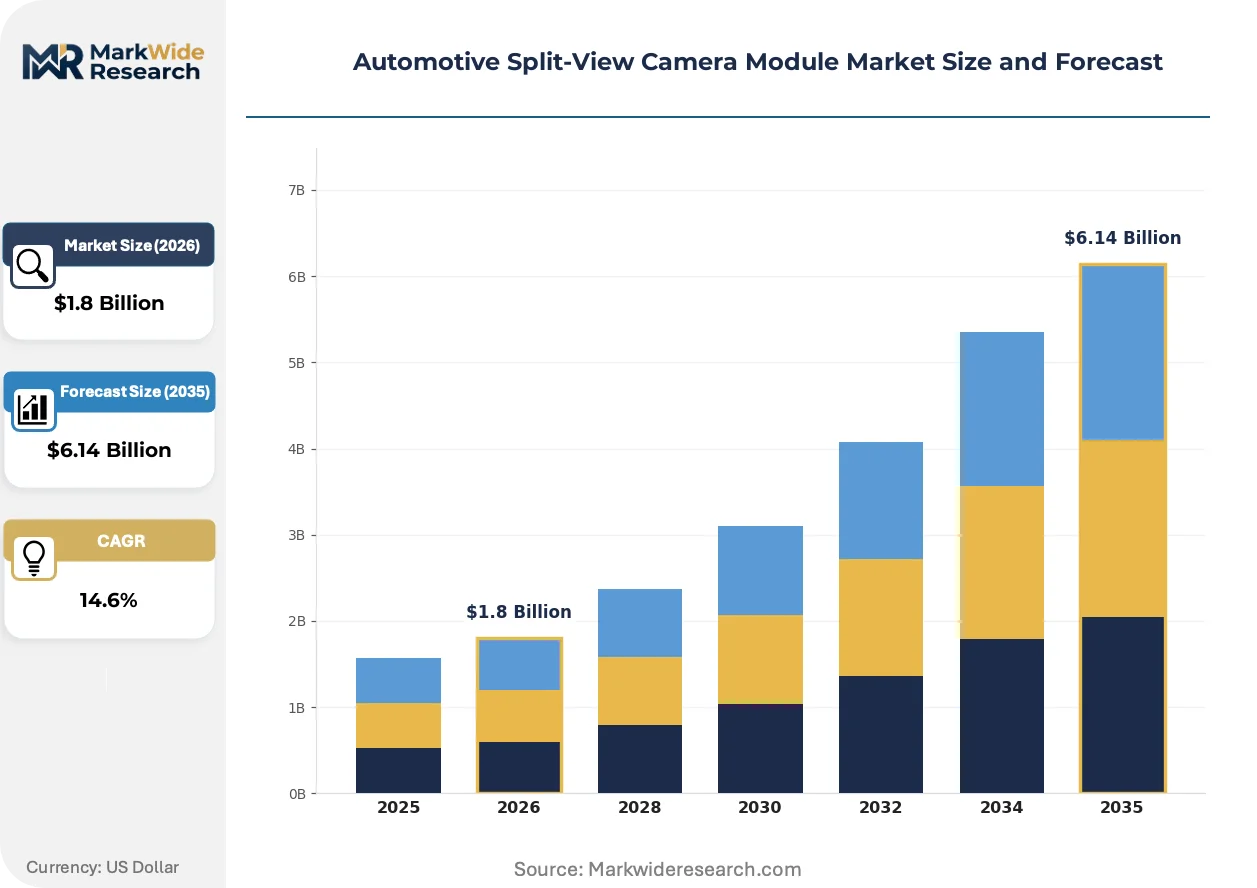
Market Dynamics
OEM consolidation of camera processing into centralized compute domains is compressing module margins while elevating software integration requirements. Tier-one suppliers now compete on thermal management and latency optimization rather than lens specifications alone.
Growth Catalysts
- Euro NCAP Safety Protocols:The rating system's surround-view coverage premiums incentivize OEMs to specify split-view architectures across platform refreshes. German premium manufacturers anchor this specification cascade.
- NHTSA Rear-Visibility Mandates:Federal compliance requirements for light vehicles sustain baseline demand for multi-camera systems in the United States market. Module suppliers certify to FMVSS 111 standards.
- Electric Vehicle Platform Proliferation:Dedicated EV architectures integrate split-view modules at design phase rather than retrofitting legacy chassis. Battery-electric drivetrains accommodate expanded sensor arrays without thermal interference from exhaust systems.
Market Restraints
- Image Sensor Supply Concentration:Wafer fabrication for automotive-grade CMOS sensors concentrates in East Asian foundries. Geopolitical friction elevates inventory carrying costs for European module assemblers.
- ECE R46 Certification Barriers:Mirror-replacement camera systems require type-approval testing that extends development cycles. Non-certified suppliers face exclusion from European OEM supply chains.
- Software-Defined Vehicle Disintermediation:Centralized compute architectures shift image processing from dedicated modules to domain controllers. Hardware-only suppliers risk margin compression as software value capture migrates upstream.
Strategic Opportunities
- Level 2+ Autonomy Specification:Highway assist systems demand redundant camera coverage with sub-50-millisecond latency. Tier-one suppliers can anchor long-term contracts through early platform integration.
- India Automotive Production:Domestic OEMs and joint ventures localize camera module sourcing under PLI scheme incentives. Component suppliers establish captive plants in Tamil Nadu and Gujarat clusters.
- Thermal-Stability Differentiation:Extended temperature-range operation from minus forty to one hundred five degrees Celsius enables positioning in premium EV segments. Materials innovation in encapsulation compounds supports this specification tier.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-B compliance for camera modules demands specialized verification engineering. Talent scarcity in automotive safety architecture extends program timelines.
- Legacy Vehicle Integration:Retrofit compatibility with analog-era wiring harnesses complicates aftermarket deployment. Module suppliers maintain dual-output architectures to address installed-base heterogeneity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Split-View Camera Module Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Camera, Frontview Camera, Sideview Camera, Multi-View Camera Technology: Analog, Digital, Infrared, High Definition Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Manufacturers, Automotive Designers |
| Companies Covered | Denso Corporation, Panasonic Corporation, Bosch, Autoliv, Aptiv, Continental, Magna International, Mobileye, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Split-View Camera Module Market Emerging Trajectories
Image-processing migration from edge modules to centralized domain controllers is redefining supplier value capture. Module differentiation now hinges on thermal performance and synchronization precision rather than standalone processing capability.
High-definition digital interfaces are overtaking legacy analog transmission protocols in new vehicle platforms. The MIPI CSI-2 standard enables uncompressed video streams at reduced wiring weight. European OEMs specify this architecture for Level 2+ highway assist systems. Module suppliers without digital IP portfolios face specification exclusion.
Euro NCAP's 2023 test protocol revision elevated surround-view coverage weighting in overall safety scoring. OEMs responded by mandating split-view modules on base trim configurations. The regulatory pressure propagates through supply chains as volume-tier manufacturers accelerate multi-camera adoption.
Buyer concentration among platform-engineering teams compresses supplier negotiation cycles. OEMs now bundle camera module procurement with domain controller sourcing. German and Swedish automakers lead this consolidation pattern, favoring suppliers with radar fusion expertise. Module specialists without sensor fusion capabilities confront margin erosion.
Automotive Split-View Camera Module Market Segmentation
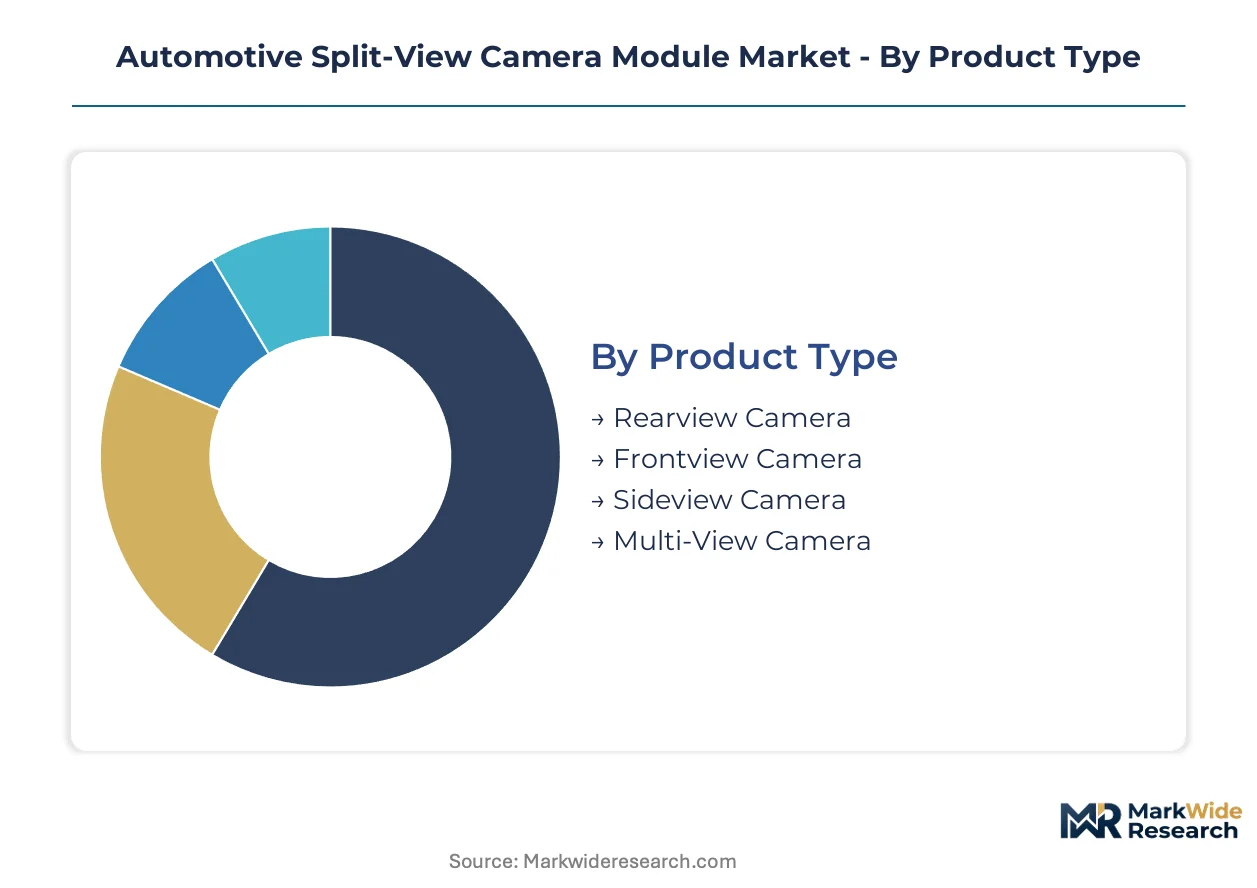
Segmentation in automotive split-view camera modules reveals how procurement patterns diverge between volume-tier manufacturers and premium platform engineers. Technology choices and application requirements reshape supplier qualification criteria across each dimension.
Product Type:
Volume concentration favors consolidated multi-lens architectures over discrete single-function modules.
- Rearview Camera:Single-lens assemblies with wide-angle optics deliver statutory backup visibility. NHTSA FMVSS 111 compliance sustains baseline procurement across United States light vehicle production lines.
- Multi-View Camera:Synchronized quad-lens arrays feed unified processing chains for surround-view synthesis. German premium OEMs specify these architectures for Level 2+ highway assist platforms.
- Frontview Camera:Forward-facing modules with narrow field-of-view support adaptive cruise and lane-keeping functions.
- Sideview Camera:Door-mounted or mirror-integrated lenses enable blind-spot monitoring and parking assistance.
Mature deployment sits with rearview cameras. Newer deployment is concentrated in multi-view systems.
Technology:
Digital interfaces are displacing legacy analog transmission as OEMs consolidate wiring harness complexity.
- High Definition:Uncompressed digital streams via MIPI CSI-2 interfaces reduce latency below fifty milliseconds. Euro NCAP safety scoring premiums accelerate specification across European platform refreshes.
- Digital:Standard-definition digital architectures balance cost and performance for mid-market vehicle segments.
- Analog:Composite video output persists in aftermarket replacement channels and legacy vehicle retrofits.
- Infrared:Near-infrared sensitive sensors enable low-light pedestrian detection for nighttime driving assistance.
Established production runs on analog and standard digital. Steepest expansion trajectory belongs to high-definition architectures.
Application:
Electric vehicle platforms integrate camera modules at design phase rather than adapting legacy chassis constraints.
- Electric Vehicles:Dedicated battery-electric architectures accommodate expanded sensor arrays without exhaust system thermal interference. OEM procurement concentrates in Germany and China production facilities.
- Luxury Vehicles:Multi-camera surround-view systems with sub-50ms latency anchor premium trim specifications.
- Passenger Vehicles:Volume-tier manufacturers accelerate multi-camera adoption following Euro NCAP protocol revisions.
- Commercial Vehicles:Fleet operators specify rearview and sideview modules for maneuvering safety in urban delivery routes.
Conventional deployment dominates passenger vehicle segments. Emerging deployment clusters in electric vehicle platforms.
End User:
Procurement authority concentrates with platform engineering teams that bundle camera sourcing with domain controller contracts.
- OEMs:Original equipment manufacturers specify split-view architectures during vehicle platform development. German and Swedish automakers lead consolidation of camera and radar fusion procurement.
- Vehicle Manufacturers:Contract assemblers and joint ventures localize sourcing under India PLI scheme incentives in Tamil Nadu and Gujarat clusters.
- Aftermarket Suppliers:Replacement channel distributors face margin compression from dual-output architecture requirements for legacy compatibility.
- Automotive Designers:Styling studios influence lens housing integration and mirror-replacement camera aesthetics.
Primary volume flows through OEMs. Aftermarket channels capture replacement demand with diluted margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European specification activity for split-view camera modules, where premium OEM engineering teams mandate surround-view architectures for Level 2+ autonomy platforms. Procurement concentration in southern Germany cascades through supply chains to module assemblers across the continent and Asia.
United States
NHTSA FMVSS 111 compliance sustains baseline demand for rearview and multi-camera systems across Detroit Three and transplant production lines. The regulation mandates rear-visibility standards for light vehicles sold nationwide. Module suppliers cluster near assembly plants in Michigan, Ohio, and the Southeast manufacturing corridor to minimize logistics latency.
Germany
BMW, Mercedes-Benz, and Volkswagen Group engineering teams specify split-view modules with sub-50-millisecond latency for highway assist systems. Euro NCAP safety scoring premiums accelerate multi-camera adoption across platform refreshes. Suppliers concentrate manufacturing and R&D in Baden-Württemberg and Bavaria to serve premium OEM procurement offices.
China
Domestic EV manufacturers BYD and NIO integrate quad-lens surround-view systems at the design phase of dedicated battery-electric platforms. MIIT regulations govern automotive electronics certification and data security for camera-equipped vehicles. Production clusters in Shanghai's Yangtze River Delta and Shenzhen's Pearl River Delta dominate module assembly capacity.
Japan
Toyota and Honda procurement teams emphasize thermal stability specifications spanning minus forty to one hundred five degrees Celsius for hybrid and electric platforms. METI industrial policy supports domestic sensor-to-module integration capabilities. Suppliers maintain engineering centers in Aichi Prefecture's Chubu region near Nagoya automotive headquarters.
India
Maruti Suzuki and Hyundai Motor India localize camera module sourcing under PLI scheme incentives for automotive components. BIS certification requirements and DGFT import regulations shape supplier qualification timelines. Manufacturing plants concentrate in Tamil Nadu's Sriperumbudur-Oragadam belt and Gujarat's Sanand-Vithalapur corridor to serve domestic OEM assembly.
Automotive Split-View Camera Module Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermal performance and synchronization precision specifications. The supplier base organizes into three tiers: integrated electronics conglomerates with captive semiconductor capacity, specialized automotive Tier-1 module assemblers, and regional contract manufacturers serving aftermarket channels. Consolidation pressures intensify as OEMs bundle camera procurement with domain controller contracts. Dominant competitive moves include backward integration into sensor wafer sourcing and strategic partnerships with centralized compute platform vendors.
Within the integrated electronics tier, Denso Corporation and Bosch exemplify archetypes combining captive semiconductor fabrication with module assembly scale. Panasonic Corporation occupies a position bridging component supply and finished module production for transnational OEM programs. These three anchors represent divergent strategic postures: Denso emphasizes sensor-to-system vertical control, Bosch prioritizes radar-camera fusion integration, and Panasonic leverages consumer electronics manufacturing scale for automotive qualification.
| Leading Market Players |
|---|
| Denso Corporation |
| Panasonic Corporation |
| Bosch |
| Autoliv |
| Aptiv |
| Continental |
| Magna International |
| Mobileye |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Image-processing engineering talent clusters in Baden-Württemberg and Aichi Prefecture compress labor-cost differentials between European and Japanese module suppliers. This concentration narrows pricing-tier spreads across premium thermal-stability specifications and standard-grade multi-view assemblies.
Pricing Analysis
Latency-performance guarantees anchor value-based pricing for highway-assist camera modules. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 ASIL-B certification status and thermal-range specifications. Cost compression in standard-grade multi-view assemblies intensifies as OEMs bundle procurement with domain-controller contracts. Volume-tier passenger vehicle manufacturers exhibit highest price sensitivity; German premium OEMs prioritize sub-50-millisecond latency over unit cost.
Supply Chain Analysis
India's PLI scheme automotive-component incentives reshape sourcing patterns for module assemblers serving Maruti Suzuki and Hyundai Motor India. Wafer fabrication for automotive-grade CMOS sensors centers on Taiwan and South Korea; encapsulation compounds and lens housings feed from German and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in East Asian foundry capacity for image sensors. Distribution runs through Tier-1 supplier direct contracts with OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECE R46 mirror-replacement certification creates a compliance moat that elevates qualified suppliers above commodity assemblers. This cost-of-compliance dynamic concentrates procurement authority with type-approved module specialists.
For Market Incumbents: Extend thermal-stability specifications to minus-forty-to-one-hundred-five-degree Celsius operation for premium EV platform capture. Deepen backward integration into sensor wafer sourcing to offset East Asian foundry concentration risk. Fortify radar-camera fusion engineering capabilities as OEMs consolidate procurement bundles.
For New Entrants and Emerging Players: Enter via India's Tamil Nadu and Gujarat manufacturing clusters under PLI scheme localization requirements. Target domestic OEM joint ventures with cost-optimized standard-definition digital modules. Pursue BIS certification pathways ahead of DGFT import regulation enforcement.
For Investors and Strategic Acquirers: Re-rating potential sits with ASIL-B-certified module assemblers given Euro NCAP safety-score premium propagation. Long-term viability favors suppliers with captive semiconductor integration and domain-controller partnership exposure. Monitor MIIT automotive electronics certification timelines as inflection signals for China market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces module variant complexity for OEMs consolidating multi-camera architectures. |
| Software-Defined Vehicle Investment | Shifts value capture from edge modules to centralized compute domain partnerships. |
| Geographic Manufacturing Footprint | PLI scheme incentives in India and MIIT regulations in China reshape plant location decisions. |
| Battery Supply Agreement | EV platform proliferation demands thermal-stability specifications without exhaust-system interference. |
| Charging Infrastructure Partnership | Surround-view parking assistance integrates with automated charging positioning systems. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, and NHTSA FMVSS 111 compliance filings, complemented by interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and thermal-management R&D directors. Secondary validation drew from SEC automotive segment disclosures, Euro NCAP protocol documentation, and ECE R46 type-approval records. Bottom-up unit shipment estimates triangulated against top-down OEM platform content analysis.
Segment-level projections across vehicle class, propulsion architecture, and regional production clusters fed into consolidated market sizing. CAGRs derived from regression analysis of historical adoption curves against regulatory mandate timelines and EV platform launch schedules. Image-sensor foundry capacity expansion plans and Euro NCAP scoring weight revisions served as key forecast sensitivity inputs across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption of East Asian wafer supply and accelerated software-defined vehicle architecture migration. Automotive safety regulation enforcement intensity and PLI scheme incentive continuity represent material assumption dependencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market