
 Car DVR Market | 2026-2036
Car DVR Market Size, Share, and Industry Trends Forecast 2026-2036
Car DVR Market Analysis
Multi-source component procurement is restructuring supply economics across the Car DVR industry. Nextbase leverages its UK design heritage to sustain premium positioning in European retail channels. Thinkware anchors its competitive stance through integrated thermal management and Korean domestic manufacturing scale.
A Car DVR is a windshield- or dashboard-mounted digital video recorder capturing continuous footage through CMOS or CCD image sensors, typically storing data on microSD cards or solid-state drives with loop-overwrite functionality; its primary purpose is to provide objective incident documentation for insurance claims, traffic disputes, and fleet liability management. Dual-channel DVR systems lead unit volume as consumers and fleet operators demand simultaneous front-cabin and rear-road coverage, while cloud-based technology segments capture disproportionate margin pools through recurring subscription revenue attached to real-time upload and remote access capabilities. Analog technology persists in emerging price-sensitive tiers though digital signal processing now dominates mid-range and premium configurations.
FCC certification requirements govern wireless transmission modules in US-market devices, while EU REACH and RoHS frameworks restrict hazardous substances in solder and PCB substrates sold across European member states. South Korea's MFDS and KCC standards shape product safety and electromagnetic compatibility benchmarks for domestic manufacturers exporting throughout Asia-Pacific. Stakeholders must monitor evolving data privacy mandates governing cloud footage retention periods and cross-border server localization as regulatory fragmentation intensifies between major automotive electronics markets.
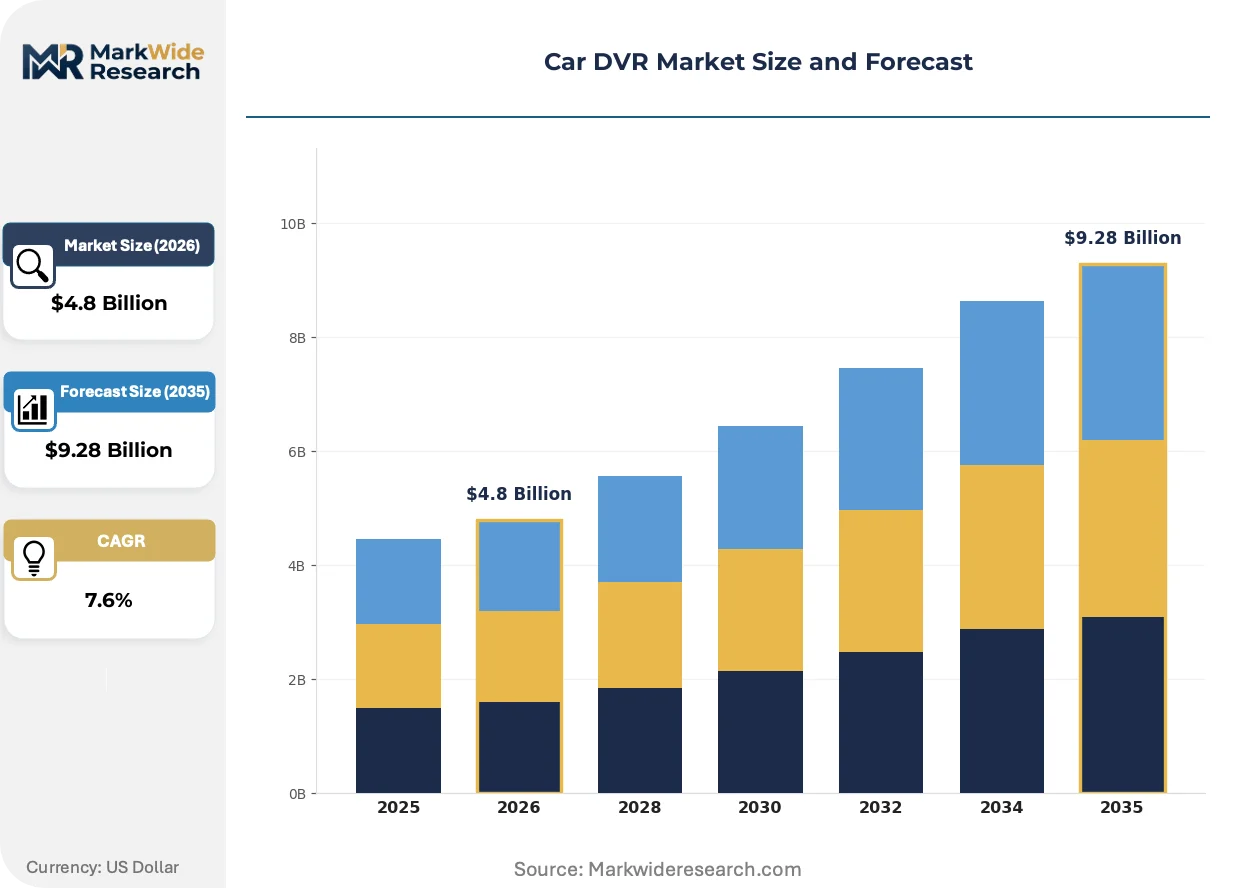
Market Dynamics
China's MIIT has tightened GB standards for in-vehicle electronics, forcing manufacturers to redesign sensor architectures and encrypted storage systems while fleet operators mandate video documentation for liability reduction.
Growth Catalysts
- GB Standards Revision:China's MIIT mandates higher-resolution sensors and encrypted storage, pushing domestic and foreign manufacturers toward premium product tiers to maintain market access.
- Fleet Liability Mandates:Commercial transport operators across North America and Europe now require continuous video documentation, expanding the addressable base beyond consumer retail channels.
- Semiconductor Supply Chain Concentration:South Korean domestic brands leverage advanced foundry partnerships to dominate dual-channel and cloud-connected premium segments.
Market Restraints
- CMOS Sensor Cost Volatility:Price swings in high-resolution image sensors compress margins for mid-tier manufacturers dependent on external procurement.
- Korean Manufacturing Concentration:Thermal management and domestic assembly scale advantages create supply-side lock-in that disadvantages regional competitors.
- EU REACH Compliance Burden:Hazardous substance restrictions in solder and PCB substrates force reformulation cycles that delay European market entry.
Strategic Opportunities
- Cloud Subscription Models:Recurring revenue from real-time upload and remote access capabilities captures disproportionate margin pools beyond hardware sales.
- India Fleet Modernization:Underpenetrated commercial transport sectors present white space for dual-channel systems as domestic logistics operators professionalize.
- FCC Certification Pathway:Wireless transmission module approvals unlock US retail distribution for integrated LTE-enabled devices.
Industry Challenges
- Firmware Encryption Expertise Gap:Shortage of embedded security engineers delays GB-compliant product launches for second-tier manufacturers.
- Cross-Border Data Localization:Fragmented cloud footage retention mandates between EU GDPR, South Korean KCC, and emerging Middle Eastern frameworks complicate platform architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car DVR Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-View DVR, Rear-View DVR, Dual-Channel DVR, 360-Degree DVR Technology: Analog, Digital, Wireless, Cloud-Based Feature: Night Vision, Loop Recording, G-Sensor, Parking Mode End User: Personal Vehicles, Fleet Operators, Insurance Companies, Aftermarket Providers |
| Companies Covered | Garmin Ltd., Cobra Electronics Corporation, Nextbase, Thinkware, BlackVue, Shenzhen Firstscene Technology Co.,Ltd, Rexing Inc, AUTO-VOX, DOD Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car DVR Market Emerging Trajectories
Video processing architectures and connectivity protocols are fragmenting across price tiers, with premium systems diverging toward integrated thermal management and cloud-native platforms while analog persists at the entry level.
Edge-based AI inference engines are modularizing dashcam functionality, enabling real-time incident detection and driver behavior analysis without continuous cloud uplink. Fleet operators in Germany and Japan are piloting these systems for insurance premium reduction. The technology is modularizing what was previously a passive recording device into an active safety system, compressing upgrade cycles from replacement to firmware refresh.
EU REACH and RoHS frameworks are restricting hazardous substances in solder alloys and PCB substrates, forcing Asian contract manufacturers to reformulate assembly processes. European-bound products now require dedicated production lines with alternative metallurgy. Premium dual-channel units with extended temperature ratings face the steepest compliance cost escalation.
Commercial buyers are consolidating procurement around integrated fleet management platforms that bundle DVR hardware with telematics and fuel monitoring. This bundling is displacing standalone retail purchases through automotive distributors. The shift is most visible in North American long-haul trucking, where procurement teams now specify video documentation as a line item within broader vehicle connectivity contracts.
Car DVR Market Segmentation
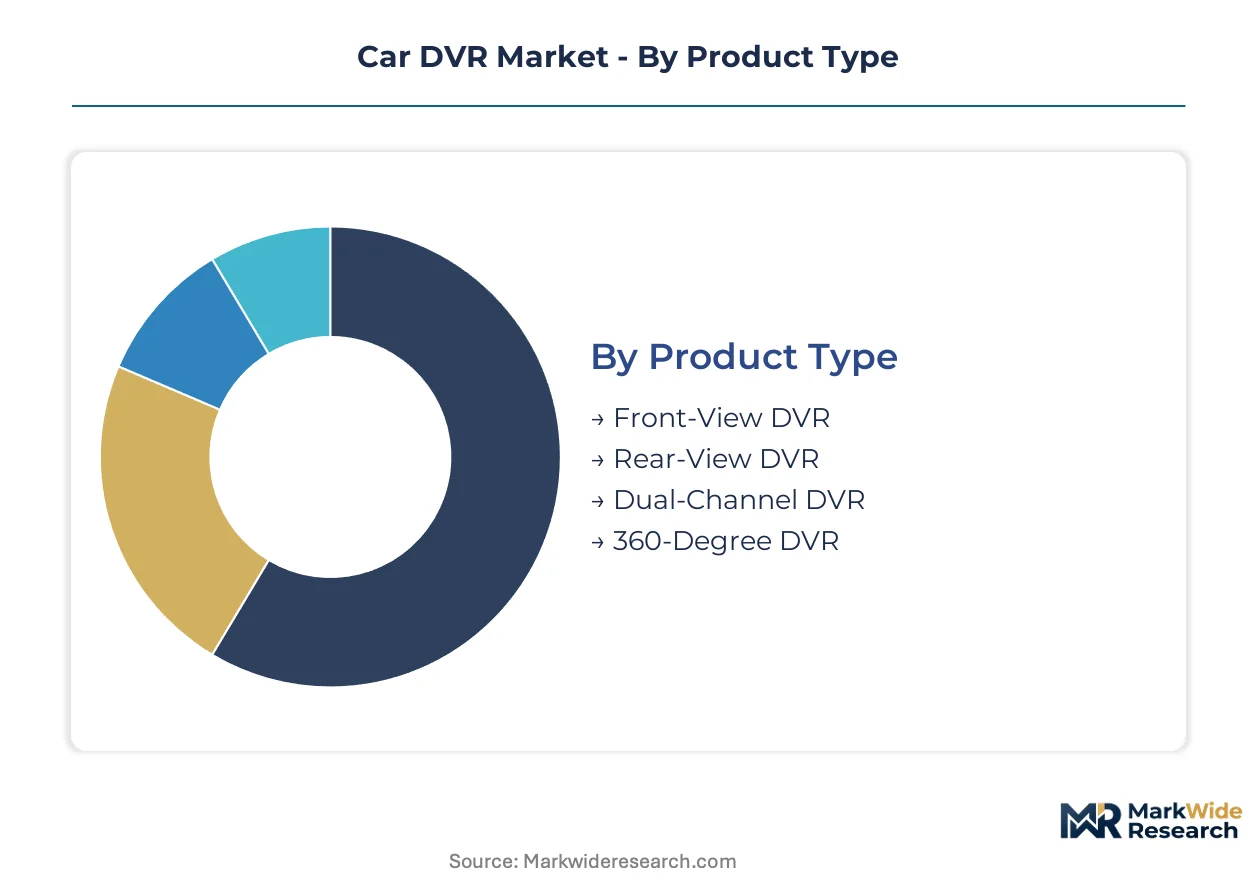
Car DVR segmentation reflects divergent buyer priorities across safety documentation, fleet liability management, and insurance risk assessment. Product architecture choices cascade through supply chain requirements, certification pathways, and margin structures differently for each tier.
Product Type:
Standardization dominates entry-level single-channel units while premium configurations demand extensive customization around sensor placement and thermal envelope design.
- Front-View DVR:Single-lens systems capture road-facing footage through wide-angle CMOS sensors with 1080p to 4K resolution options. Fleet operators in Germany specify these for basic liability coverage in light commercial vehicles where rear documentation remains secondary.
- Dual-Channel DVR:Synchronized front and rear recording through independent image processors demands dual thermal management zones and doubled storage bandwidth. South Korean foundry partnerships supply the integrated SoCs that enable this architecture at competitive unit economics.
- Rear-View DVR:Dedicated backup-focused units serve aftermarket retrofit demand where front systems are factory-installed.
- 360-Degree DVR:Multi-sensor fusion systems stitch four or more camera feeds for comprehensive surround documentation.
Most installed capacity flows through Front-View DVR. Expansion is steepest in Dual-Channel DVR.
Technology:
Cost tier stratification separates legacy analog assembly from digital signal processing and cloud-native platforms requiring ongoing infrastructure investment.
- Digital:CMOS-based signal processing with H.265 compression dominates mid-range and premium hardware, enabling higher resolution at equivalent storage footprints. China's MIIT GB standards revisions mandate encryption layers that digital architectures accommodate more readily than legacy alternatives.
- Cloud-Based:LTE or Wi-Fi enabled real-time upload shifts revenue models toward recurring subscription structures. EU GDPR compliance for cross-border footage storage adds architectural complexity that favors established platform operators with dedicated European server infrastructure.
- Analog:CCD-based legacy systems persist in price-sensitive emerging markets with minimal regulatory enforcement.
- Wireless:Bluetooth and Wi-Fi Direct modules enable smartphone pairing for local footage retrieval without cellular subscription.
Digital technology commands the largest production volume. Cloud-Based technology is gaining share fastest.
Feature:
Application context determines which capabilities shift from premium add-on to baseline expectation across consumer and commercial segments.
- G-Sensor:Accelerometer-triggered incident flagging automatically protects footage segments from loop overwrite when collision forces exceed calibrated thresholds. Insurance companies in Japan require G-Sensor certification for premium reduction programs, making this feature mandatory in that market.
- Parking Mode:Low-power standby monitoring with motion detection or impact sensing extends documentation to vandalism and hit-and-run scenarios when vehicles are unoccupied. Battery management and voltage protection circuitry add BOM cost that fleet operators accept for comprehensive asset protection.
- Night Vision:Infrared illumination or starlight sensor sensitivity enhances low-light capture quality.
- Loop Recording:Continuous overwrite functionality with user-defined segment lengths forms the baseline storage management approach.
G-Sensor penetration is deepest across installed base. Parking Mode is climbing the fastest.
End User:
Customer type segmentation reveals divergent procurement patterns between individual retail purchase and integrated fleet platform contracting.
- Fleet Operators:Commercial transport and logistics companies specify DVR systems through telematics platform RFPs rather than standalone hardware procurement. North American long-haul trucking consolidation around video documentation mandates is accelerating replacement cycles and favoring dual-channel systems with integrated driver-facing cabin monitoring.
- Insurance Companies:Risk carriers subsidize or mandate installation to reduce claim dispute costs and enable usage-based premium modeling. Partnership programs with hardware manufacturers create volume commitments that shape product roadmaps toward standardized data formats and API accessibility.
- Personal Vehicles:Individual consumers purchase through retail channels and e-commerce platforms with feature-driven selection criteria.
- Aftermarket Providers:Independent installers and automotive service chains handle retrofit installation for vehicles without factory-equipped documentation systems.
Fleet Operators represent the fastest-expanding buyer segment. Insurance Companies are driving standardization most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as Chinese producers absorb GB standard compliance costs while Southeast Asian contract manufacturers capture orders from brands seeking REACH reformulation avoidance. Production migration follows divergence between MIIT encryption mandates and EU hazardous substance restrictions.
China
MIIT's tightened GB standards for in-vehicle electronics compel domestic and foreign manufacturers toward higher-resolution sensors and encrypted storage architectures. Shenzhen and Dongguan clusters house vertically integrated assembly operations serving both domestic fleet operators and export markets. Yangtze River Delta foundries supply the CMOS image processors enabling 4K capture at competitive unit economics.
South Korea
Domestic brands leverage advanced semiconductor supply chains to dominate premium dual-channel and cloud-connected product tiers. MFDS and KCC standards shape electromagnetic compatibility benchmarks for manufacturers exporting throughout Asia-Pacific. Seoul Capital Area design houses integrate thermal management expertise with foundry partnerships from Busan-Ulsan.
United States
FCC certification requirements govern wireless transmission modules in devices with LTE or Wi-Fi connectivity, creating approval bottlenecks for integrated fleet telematics systems. Long-haul trucking operators in Texas and California now mandate video documentation as standard procurement terms. Midwest distribution channels handle aftermarket retrofit volume for light commercial vehicles.
Germany
EU REACH and RoHS frameworks restrict hazardous substances in solder alloys and PCB substrates, forcing dedicated production lines with alternative metallurgy for European-bound products. Fleet operators specify dual-channel systems with integrated driver-facing cabin monitoring through platform RFPs. Bavaria-based automotive electronics distributors consolidate procurement around bundled telematics contracts.
India
Underpenetrated commercial transport sectors present white space for dual-channel systems as domestic logistics operators professionalize and BIS standards gradually align with global automotive electronics benchmarks. Maharashtra and Gujarat warehousing corridors drive fleet modernization demand. Delhi-NCR aftermarket channels handle retrofit installation for price-sensitive owner-operator segments.
Car DVR Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native platform differentiation and fleet management integration. The vendor base stratifies across three tiers: premium brands with semiconductor foundry partnerships, mid-range specialists with regional certification expertise, and price-focused assemblers serving emerging markets. Two strategic archetypes dominate: integrated platform operators bundling hardware with recurring subscription revenue, and component-agnostic contract manufacturers flexing capacity across OEM brands. Competitive moves concentrate on M&A for cloud infrastructure capabilities and strategic partnerships with fleet telematics providers.
Among UK-heritage design houses, Nextbase exemplifies premium retail channel positioning through European consumer electronics distribution. Thinkware represents the integrated manufacturing archetype, anchoring competitive stance through Korean domestic production scale and thermal management specialization. Shenzhen Firstscene Technology Co., Ltd. occupies the contract manufacturing tier, serving brand owners with flexible assembly capacity and MIIT compliance pathway expertise.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Cobra Electronics Corporation |
| Nextbase |
| Thinkware |
| BlackVue |
| Shenzhen Firstscene Technology Co.,Ltd |
| Rexing Inc |
| AUTO-VOX |
| DOD Tech |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FCC-licensed cloud-connected units and entry-level analog devices splits both pricing power and component sourcing across entirely separate supplier ecosystems. Premium dual-channel systems with encrypted storage architectures command hardware-plus-subscription structures, while commodity single-lens units compete on Shenzhen assembly floor pricing. Fleet procurement teams now specify video documentation as bundled telematics line items, compressing standalone retail margins and forcing distributors toward value-added installation services.
Pricing Analysis
Distributor margin layers absorb the steepest compression as fleet operators consolidate procurement through integrated telematics platform RFPs rather than aftermarket retail channels. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native subscription bundles from digital hardware-only sales and legacy analog configurations. Price differentiation rests on GB encryption compliance and thermal management certification, with MIIT-mandated redesign cycles adding non-recurring engineering costs that squeeze mid-tier manufacturers most severely. Cost compression in entry-level CMOS assemblies intensifies because Korean foundry partnerships lock in premium SoC supply, leaving regional assemblers exposed to spot-market sensor volatility.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dongguan, and Busan-Ulsan anchor hub-and-spoke fulfillment patterns for European and North American aftermarket channels. Manufacturing concentration centers on China, South Korea, and Vietnam, with Yangtze River Delta foundries supplying CMOS image processors and Seoul Capital Area design houses contributing thermal management IP. Raw material dependencies include high-resolution sensors, encrypted storage modules, and lead-free solder alloys reformulated for EU REACH compliance. Single-source vulnerability runs through Korean integrated SoC suppliers serving dual-channel architectures. Distribution runs through Bavaria-based automotive electronics distributors for European fleet contracts and Midwest aftermarket channels for US light commercial retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Car DVR market compounds steadily as fleet liability mandates embed video documentation into standard commercial vehicle procurement terms. Regulatory encryption requirements and thermal management specifications create defendable moats for compliant manufacturers.
For Market Incumbents: Deploy firmware encryption expertise as a defensive lever against second-tier manufacturers facing GB compliance delays. Deepen captive supply of MIIT-certified storage architectures to outpace redesign cycles forced by China's evolving standards. Anchor channel control through exclusive telematics platform partnerships that displace standalone retail purchases in North American long-haul trucking procurement.
For New Entrants and Emerging Players: Edge-based AI inference engines without continuous cloud uplink offer a technology-first wedge into German and Japanese fleet insurance premium reduction programs. Target India's underpenetrated commercial transport corridors as the most penetrable geography, where domestic logistics professionalization outpaces established vendor footprints. Pursue direct fleet operator relationships bypassing automotive distributor markup layers entirely.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platform operators capturing recurring subscription revenue attached to real-time upload capabilities. Long-term viability favors integrated hardware-software vendors with dedicated European server infrastructure for GDPR-compliant footage retention. Watch fleet telematics bundling penetration as the inflection signal indicating standalone hardware commoditization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | GDPR-compliant server localization unlocks EU fleet contracts against cross-border data fragmentation. |
| GB Standards Compliance Investment | Encrypted storage certification maintains China market access as MIIT tightens in-vehicle electronics rules. |
| Fleet Telematics Integration | Video documentation bundling displaces standalone retail through North American trucking procurement consolidation. |
| Edge AI Module Development | Real-time incident detection without cellular subscription reduces fleet operator total cost of ownership. |
| Korean Foundry Alliance | Integrated SoC supply secures dual-channel thermal management advantages against regional competitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with fleet procurement directors, automotive electronics distributors, semiconductor foundry account managers, and regulatory compliance officers with secondary validation. Primary fieldwork drew from customs records, MIIT certification filings, FCC equipment authorization databases, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Historical reference periods anchored volume and value projections through the forecast horizon, with CAGR derivation reflecting segment-specific adoption curves. Modeling dimensions spanned product type, technology architecture, feature configuration, and end-user procurement pattern. Forecast inputs incorporated fleet telematics bundling penetration rates and encryption compliance cost trajectories specific to automotive electronics certification cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation between GDPR, KCC, and emerging Middle Eastern data localization frameworks. Outputs reflect documented assumptions around CMOS sensor cost trajectories and fleet operator professionalization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Motor Racing Telematics Market