
 ENT Laser Devices Market | 2026-2036
ENT Laser Devices Market Size, Share, and Industry Trends Forecast 2026-2036
ENT Laser Devices Market Analysis
ENT surgeon training capacity is redrawing competitive boundaries in laser-based interventions. Lumenis leverages decades of platform development to sustain its installed base across academic medical centers. Alma Lasers competes through flexible diode configurations that anchor outpatient clinic adoption. Asclepion Laser Technologies GmbH specializes in precision wavelengths for stapedotomy and laryngeal microsurgery, occupying a defensible niche in European otology.
ENT laser devices generate coherent light at specific wavelengths—typically 810 nm to 10,600 nm—to cut, coagulate, or vaporize soft and hard tissues in the ear, nose, and throat with minimal thermal spread to adjacent structures. CO2 lasers dominate vocal cord and laryngeal applications due to their superior precision and shallow penetration depth, while diode lasers lead functional endoscopic sinus surgery because of fiber optic deliverability and lower capital cost. Pulsed wave technology commands premium positioning in tympanoplasty and stapedectomy where thermal damage control determines audiological outcomes, whereas continuous wave systems serve high-volume tonsillectomy and turbinate reduction procedures in ambulatory settings.
FDA 510(k) pathways and the EU MDR conformity assessment govern device commercialization, with the latter extending clinical evidence requirements for reusable laser handpieces and fiber delivery systems. The EPA regulates mercury-containing laser cooling systems still present in legacy installations, while OSHA laser safety standards mandate protective protocols in hospital procedure suites. Stakeholders must monitor evolving MDR notified body capacity constraints and CMS reimbursement determinations for office-based laser procedures as these will determine deployment economics across care settings.
Market Dynamics
ENT laser procurement is decomposing around wavelength specificity as otolaryngology departments demand modular platforms that swap CO2, diode, and fiber sources without full system replacement.
Growth Catalysts
- EU MDR conformity pathways:Streamlined notified body assessments for reusable fiber delivery systems accelerate hospital capital cycles in Germany and France.
- Ambulatory surgery center expansion:Lower-cost diode laser configurations anchor outpatient adoption across United States metropolitan markets.
- Head-and-neck cancer screening protocols:Elevated detection rates in Japan sustain installed base growth for precision laryngeal platforms.
Market Restraints
- Mercury cooling system legacy:EPA hazardous waste regulations impose decommissioning costs on hospitals operating pre-2010 CO2 laser installations.
- Fiber optic supply concentration:German and Japanese specialty glass manufacturers control high-purity silica sourcing for 810-980 nm delivery systems.
- Thermal damage control limits:Continuous wave systems face substitution pressure from pulsed alternatives in tympanoplasty applications.
Strategic Opportunities
- Office-based reimbursement expansion:CMS determinations for turbinate reduction procedures unlock freestanding clinic demand in United States secondary markets.
- AI-integrated beam profiling:Convergence of machine vision and laser control systems enables real-time tissue recognition in laryngeal microsurgery.
- Direct-to-hospital digital procurement:Manufacturer-hosted configuration platforms bypass traditional distributor markups for academic medical center purchases.
Industry Challenges
- Laser safety officer certification:OSHA compliance mandates strain hospital staffing for procedure suite supervision.
- EU MDR technical documentation:Extended clinical evidence requirements delay reusable handpiece recertification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Laser Devices Market |
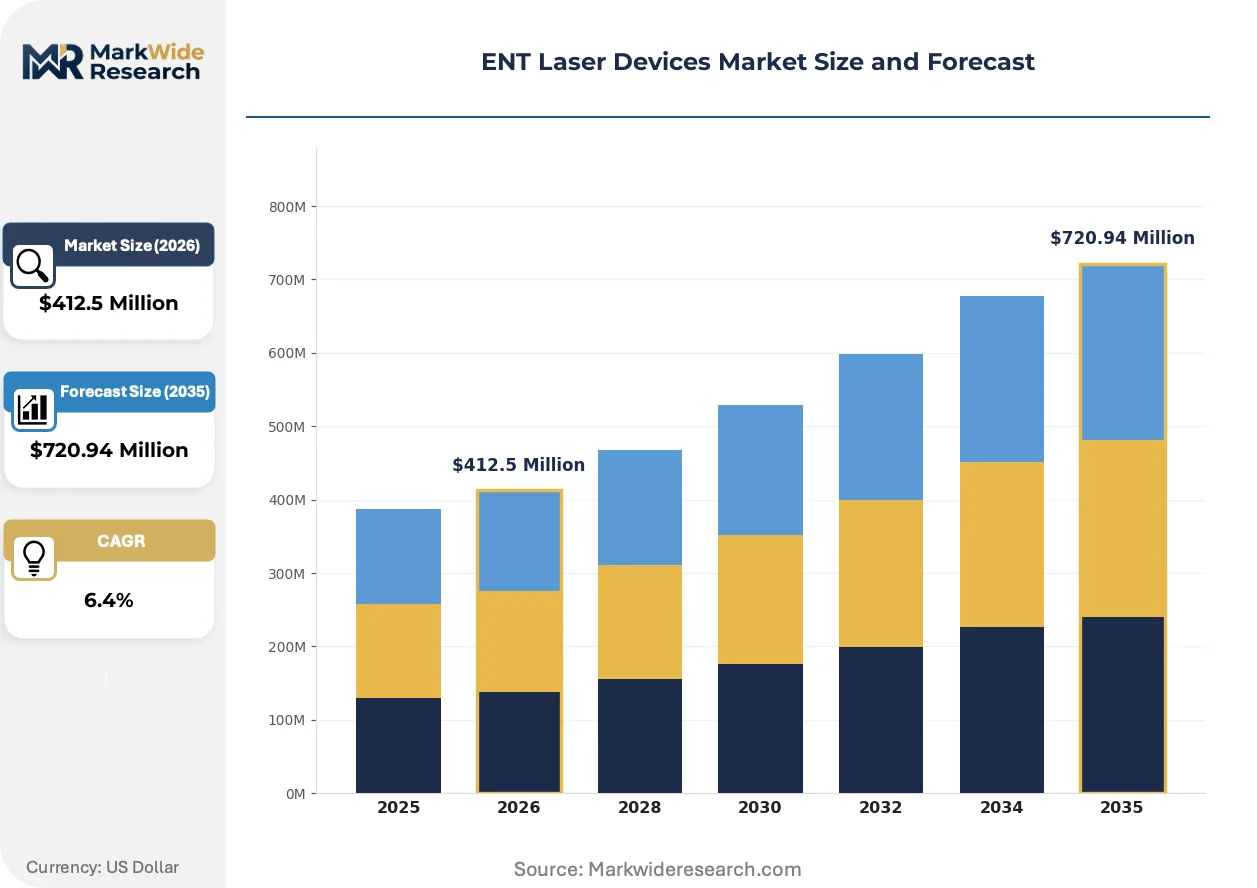
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, CO2 Lasers, YAG Lasers, Argon Lasers Application: Sinus Surgery, ENT Oncology, Vocal Cord Surgery, Ear Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Labs Technology: Continuous Wave, Pulsed Wave, Hybrid Technology, Fiber Optic |
| Companies Covered | Lumenis, Alma Lasers, Asclepion Laser Technologies GmbH, biolitec AG, Boston Scientific Corporation, Convergent Laser Technologies, ARC Laser GmbH, GIGAA LASER, Anthony Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Laser Devices Market Emerging Trajectories
Wavelength modularity and intelligent beam delivery are redrawing competitive boundaries as otolaryngology departments prioritize platform flexibility over single-source specialization.
Super-pulsed CO2 technology is decomposing the traditional trade-off between cutting precision and coagulation depth. Academic medical centers in the United States and Germany are adopting these systems for vocal cord procedures at accelerated replacement cycles. The technology is compressing demand for legacy continuous wave platforms while enabling same-session lesion excision and hemostasis.
EU MDR Article 10 clinical evaluation requirements are extending evidence burdens for reusable laser handpieces and fiber delivery systems. Notified body capacity constraints in Germany and the Netherlands are stretching conformity assessment timelines. European manufacturers are responding with single-use fiber strategies that bypass reusable device classification.
Service unbundling is separating hardware ownership from maintenance and fiber supply contracts. Ambulatory surgery centers in United States secondary markets are shifting toward per-procedure consumable purchasing rather than capital acquisition. This pattern concentrates in independent otolaryngology groups operating outside hospital ownership structures.
ENT Laser Devices Market Segmentation
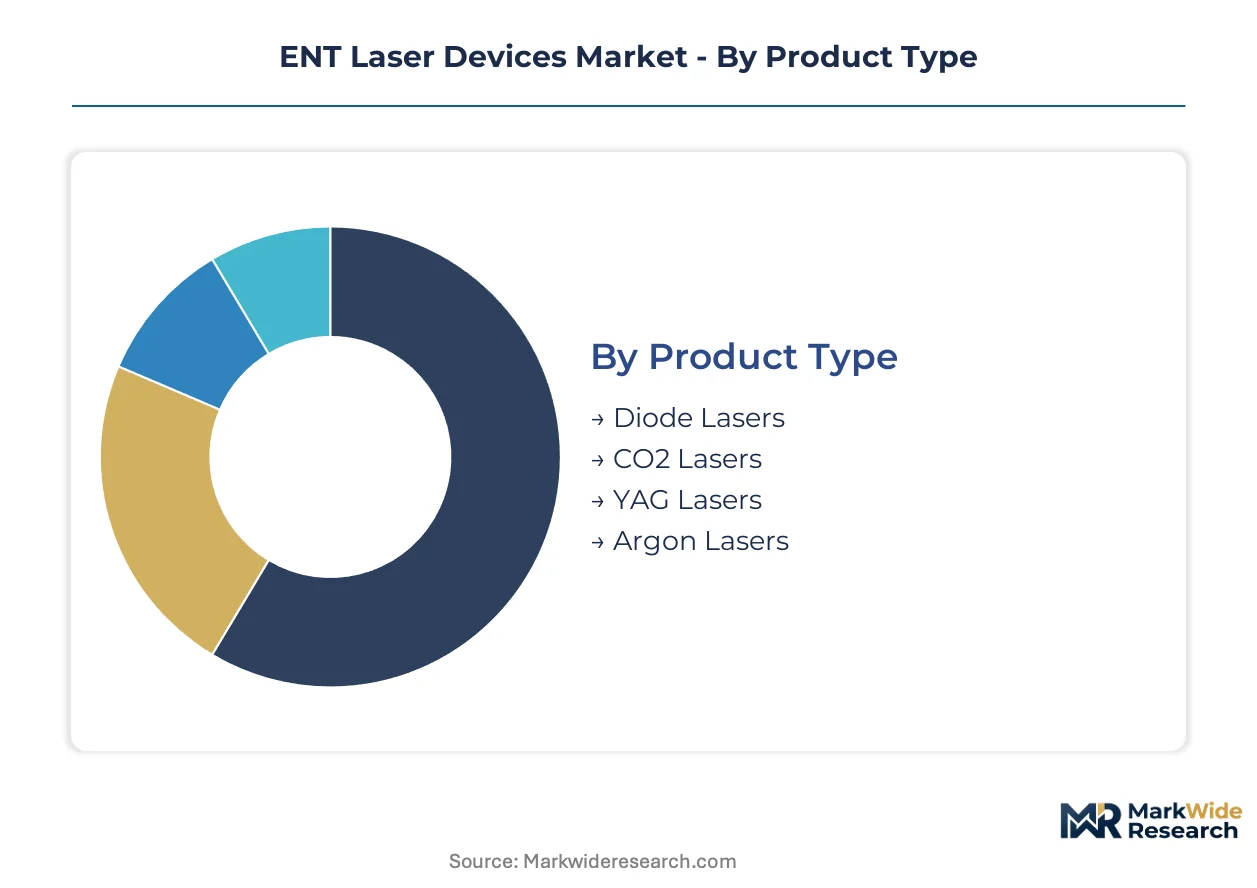
Wavelength specificity and thermal control requirements fragment procurement decisions across ENT departments. Surgeons select platforms based on tissue penetration needs, forcing manufacturers to modularize around discrete energy delivery modes rather than universal systems.
Product Type:
FDA 510(k) clearance pathways diverge sharply by laser medium, with CO2 systems facing stricter biocompatibility documentation for reusable handpieces under evolving EPA mercury handling rules.
- Diode Lasers:Semiconductor-based systems operating at 810-980 nm deliver through flexible fiber optics for functional endoscopic sinus surgery. Demand concentrates in United States ambulatory surgery centers where lower capital costs and compact footprints support outpatient clinic economics.
- CO2 Lasers:Gas discharge systems at 10,600 nm provide superior precision with shallow penetration for vocal cord and laryngeal applications. Japanese tertiary hospitals sustain installed base expansion through elevated head-and-neck cancer screening protocols that demand precision lesion excision.
- YAG Lasers:Solid-state neodymium-doped systems at 1064 nm penetrate deeper for turbinate reduction and base-of-tongue procedures.
- Argon Lasers:Ion gas systems at 488-514 nm serve niche retinal and middle ear applications with specialized wavelength requirements.
Established volume favors CO2 Lasers; emerging adoption favors Diode Lasers.
Application:
Reimbursement tiering by procedure site—hospital outpatient versus freestanding clinic—shapes platform selection more than clinical indication alone.
- Sinus Surgery:Functional endoscopic procedures dominate diode laser utilization for turbinate reduction and polypectomy. United States metropolitan markets show concentration in independent otolaryngology groups seeking same-day discharge economics.
- ENT Oncology:Laryngeal and oropharyngeal tumor resection demands precision thermal control. German academic medical centers anchor demand for super-pulsed CO2 systems that enable lesion excision with simultaneous hemostasis.
- Vocal Cord Surgery:Phonosurgery and benign lesion removal prioritize superficial penetration depth.
- Ear Surgery:Tympanoplasty and stapedectomy require pulsed wave thermal management to preserve audiological outcomes.
Sinus Surgery commands the steepest expansion trajectory; ENT Oncology maintains premium pricing power.
End User:
Capital deployment cycles compress as procurement shifts from ownership models toward per-procedure consumable purchasing in independent practice settings.
- Hospitals:Tertiary otolaryngology departments in academic medical centers anchor CO2 and YAG platform adoption. Germany and Japan concentrate demand where aging demographics sustain complex head-and-neck procedure volumes.
- Clinics:Independent otolaryngology practices in United States secondary markets favor diode configurations for office-based turbinate reduction. CMS reimbursement determinations for these procedures unlock freestanding demand outside hospital ownership structures.
- Ambulatory Surgical Centers:Corporate-owned facilities prioritize rapid turnover and lower capital commitment.
- Diagnostic Labs:Limited direct laser utilization; primarily support pre-operative imaging and biopsy confirmation.
Procurement gravity centers on Hospitals; Clinics are gaining share fastest.
Technology:
EU MDR Article 10 clinical evaluation requirements extend evidence burdens for reusable handpieces, accelerating single-use fiber strategies that bypass recertification timelines.
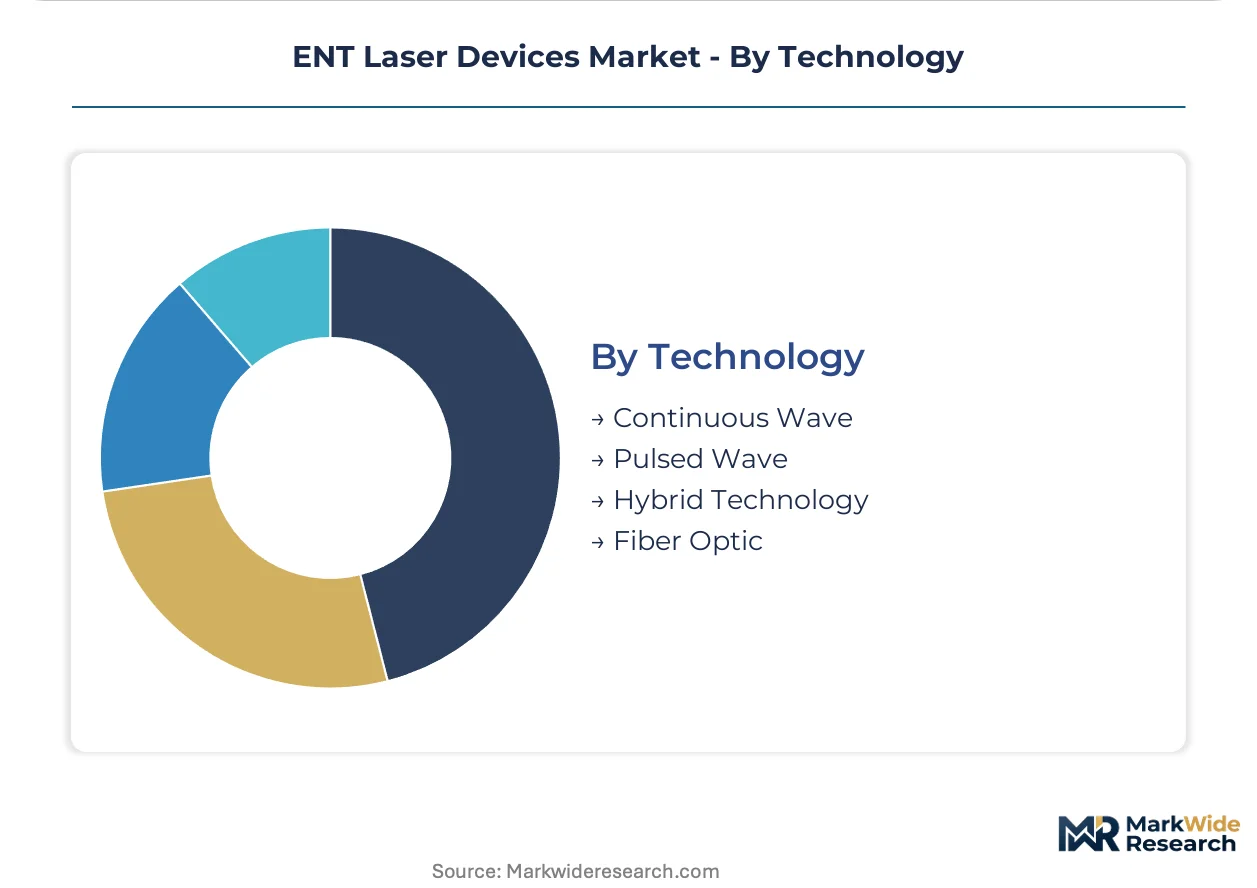
- Continuous Wave:Uninterrupted energy delivery serves high-volume tonsillectomy and turbinate reduction in ambulatory settings. United States ambulatory surgery centers favor these systems for procedural throughput and lower per-case cost structures.
- Pulsed Wave:Controlled energy bursts minimize thermal spread for tympanoplasty and stapedectomy where cochlear preservation determines outcomes. Japanese otology specialists anchor demand for these premium configurations.
- Hybrid Technology:Switchable continuous and pulsed modes offer intraoperative flexibility across multiple procedure types.
- Fiber Optic:Silica-based delivery systems enable endoscopic access through flexible or rigid scopes.
Continuous Wave dominates transaction volume; Pulsed Wave commands margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Japanese hospitals prioritize precision thermal control for head-and-neck oncology, while United States ambulatory centers favor lower-cost diode configurations for high-volume outpatient procedures.
United States
Ambulatory surgery centers in metropolitan markets drive diode laser adoption for turbinate reduction and polypectomy. FDA 510(k) clearance pathways for minimally invasive ENT tools compress procurement timelines. Independent otolaryngology groups in Texas and Florida anchor demand for office-based laser economics outside hospital ownership structures.
Germany
Academic medical centers sustain super-pulsed CO2 platform replacement cycles for laryngeal microsurgery. EU MDR notified body assessments in Berlin and Munich extend evidence requirements for reusable fiber handpieces. The Baden-Württemberg medical technology cluster concentrates precision wavelength development for stapedotomy applications.
Japan
Elevated head-and-neck cancer screening protocols sustain installed base growth for precision laryngeal platforms. PMDA regulatory pathways govern commercialization of pulsed wave systems for tympanoplasty. Tokyo and Osaka tertiary hospitals anchor demand for thermal damage control in cochlear preservation procedures.
United Kingdom
NHS procurement frameworks favor modular platforms that reduce capital replacement frequency. MHRA conformity assessment aligns with EU MDR technical documentation requirements for reusable delivery systems. London teaching hospitals concentrate demand for hybrid continuous-pulsed systems across multiple procedure types.
France
Hospital outpatient departments prioritize fiber optic deliverability for functional endoscopic sinus surgery. ANSM regulatory oversight extends to single-use fiber strategies that bypass reusable device classification. The Paris-Saclay medical cluster drives adoption of AI-integrated beam profiling for real-time tissue recognition.
ENT Laser Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling platform development and the latter dominating wavelength-specific applications. Market structure reflects consolidation around academic medical center relationships alongside fragmentation in ambulatory-focused diode configurations. Two strategic archetypes predominate: legacy platform developers with decades of installed base maintenance, and flexible configuration specialists targeting outpatient clinic economics. Competitive moves center on service unbundling that separates hardware ownership from consumable supply contracts, plus direct-to-hospital digital procurement platforms that bypass traditional distributor markups.
Within the precision wavelength specialist tier, Asclepion Laser Technologies GmbH represents German-engineered niche positioning for otology applications, while Alma Lasers exemplifies flexible diode configuration strategies that anchor ambulatory adoption. Lumenis occupies a position among legacy platform developers with sustained academic medical center relationships across multiple continents.
| Leading Market Players |
|---|
| Lumenis |
| Alma Lasers |
| Asclepion Laser Technologies GmbH |
| biolitec AG |
| Boston Scientific Corporation |
| Convergent Laser Technologies |
| ARC Laser GmbH |
| GIGAA LASER |
| Anthony Products Inc. |
| Others |
Supply Flow & Price Mechanics
EU MDR conformity assessments for reusable fiber delivery systems simultaneously gate supplier qualification and stratify price tiers across German and French hospital procurement frameworks. This regulatory threshold forces manufacturers to absorb clinical evidence costs into platform pricing while creating certification-based differentiation between established and emerging suppliers.
Pricing Analysis
Long-term service contracts dominate ENT laser procurement as academic medical centers in Germany and Japan favor multi-year maintenance and fiber supply agreements over spot purchasing. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling, with super-pulsed CO2 systems commanding premiums over continuous wave alternatives. Cost compression in diode laser configurations intensifies as ambulatory surgery centers in United States metropolitan markets prioritize per-procedure economics. Independent otolaryngology groups in Texas and Florida exhibit highest price sensitivity, while Tokyo tertiary hospitals prioritize thermal precision over capital cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for silica fiber optics sourced from Japanese and German specialty glass manufacturers. High-purity silica for 810-980 nm delivery systems draws from concentrated suppliers in Germany and Japan, with mercury-containing cooling components for legacy CO2 lasers resting on EPA-regulated hazardous waste handling. Single-source vulnerability concentrates in fiber optic supply, with distribution running through regional medical device distributors and direct-to-hospital digital platforms that bypass traditional markups for academic medical center purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-integrated beam profiling and wavelength modularity are disrupting competitive boundaries as otolaryngology departments prioritize platform flexibility over single-source specialization. EU MDR Article 10 clinical evaluation requirements accelerate this inflection by extending evidence burdens for reusable handpieces.
For Market Incumbents: Consolidate academic medical center relationships through super-pulsed CO2 platform upgrades that displace legacy continuous wave installations. Deepen backward integration into fiber optic supply chains to mitigate Japanese and German specialty glass concentration. Defend against flexible diode specialists by anchoring service unbundling contracts that separate hardware ownership from consumable purchasing. For New Entrants and Emerging Players: Office-based reimbursement gaps in United States secondary markets offer white-space entry points where CMS determinations for turbinate reduction procedures unlock freestanding clinic demand. Target independent otolaryngology groups in Texas and Florida with compact diode configurations optimized for same-day discharge economics. Pursue direct-to-hospital digital procurement channels that bypass distributor markups and accelerate capital cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ambulatory-focused diode configurations as per-procedure consumable purchasing displaces ownership models. Long-term viability favors platforms with wavelength modularity and AI-integrated control systems over single-wavelength specialization. Target acquisition candidates with established EU MDR technical documentation for reusable handpieces. Monitor CMS reimbursement determinations for office-based laser procedures as the critical signal for demand inflection in United States secondary markets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for super-pulsed CO2 platforms in United States academic centers. |
| CE Marking Pathway | Unlocks German and French hospital procurement under streamlined EU MDR notified body assessments. |
| Hospital System Partnership | Secures installed base expansion through multi-year service contracts with Tokyo tertiary hospitals. |
| Software Companion Development | Enables AI-integrated beam profiling for real-time tissue recognition in laryngeal microsurgery. |
| Reimbursement Strategy | Positions diode laser platforms for CMS-covered turbinate reduction in United States ambulatory settings. |
Methodological Framework
Operator-level perspectives from ENT surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews across academic medical centers in Germany, Japan, and the United States combined with secondary validation from FDA 510(k) filings, EU MDR notified body assessments, CMS reimbursement determinations, and hospital procurement databases. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Sensitivity analysis tested forecast robustness across the projection horizon by varying wavelength adoption rates, EU MDR compliance timelines, and ambulatory surgery center expansion scenarios. The analytical framework modeled segmentation across laser medium, application type, end-user setting, and technology mode. CAGRs derived from installed base growth trajectories, replacement cycle compression, and procedure volume elasticity. Industry-specific inputs included head-and-neck cancer screening protocol expansion in Japan and office-based reimbursement determinations in United States secondary markets.
Underlying assumptions cover stable EU MDR notified body capacity, continued EPA mercury handling compliance for legacy installations, and sustained CMS reimbursement for office-based procedures, with deviation risk concentrated in fiber optic supply disruptions and regulatory timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Hearing Implants Market
ENT
Hearing Loss Disease Treatment Market
ENT
Denmark Hearing Aids Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Europe Speech Therapy Market
ENT
Nasal Sampling Lines Market
ENT
Interventional ENT Devices Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Nasal Polyps Treatment Market
ENT
Europe Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Global Audiological Devices Market
ENT
Hearing Amplifiers Market
ENT
Surgical ENT Devices Market
ENT
ENT Devices Market