
 Endoscopic Submucosal Dissection Market | 2026-2036
Endoscopic Submucosal Dissection Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Submucosal Dissection Market Analysis
Gastrointestinal oncology departments is restructuring patient flow as early-stage tumor resection shifts toward outpatient settings. Olympus Corporation dominates electrosurgical knife portfolios across Asia-Pacific tertiary centers. FUJIFILM Holdings Corporation extends visualization system reach through hybrid imaging platforms that integrate narrow-band imaging with standard white-light endoscopy. Boston Scientific Corporation anchors North American distribution networks for disposable ESD accessories.
Endoscopic submucosal dissection is a minimally invasive endoluminal surgical technique that employs specialized electrosurgical knives to dissect the submucosal layer beneath gastrointestinal lesions, enabling en bloc resection of tumors up to several centimeters in diameter without full-thickness wall penetration. The procedure requires high-definition imaging with magnification capability, precise electrosurgical current modulation, and carbon dioxide insufflation systems to maintain operative field stability during prolonged dissection. Knives command concentrated margin pools due to single-use consumption patterns and proprietary tip geometries that resist generic replication. Robotic-assisted technology is gaining fastest traction in European university hospitals where operator training curves limit conventional ESD diffusion. Visualization systems remain mature with incremental upgrades to 4K resolution and AI-enhanced polyp detection rather than disruptive platform changes.
Japan's PMDA and METI enforce JIS standards for endoscope reprocessing and electromagnetic compatibility that shape equipment procurement specifications across domestic hospitals. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for reusable electrosurgical instruments that lengthen approval timelines for novel knife designs. FDA premarket notification pathways for ESD devices emphasize electrical safety testing and biocompatibility validation under ISO 10993 frameworks. Stakeholders must monitor reimbursement parity between ESD and surgical resection across national health technology assessment bodies to anticipate volume shifts between ambulatory and inpatient settings.
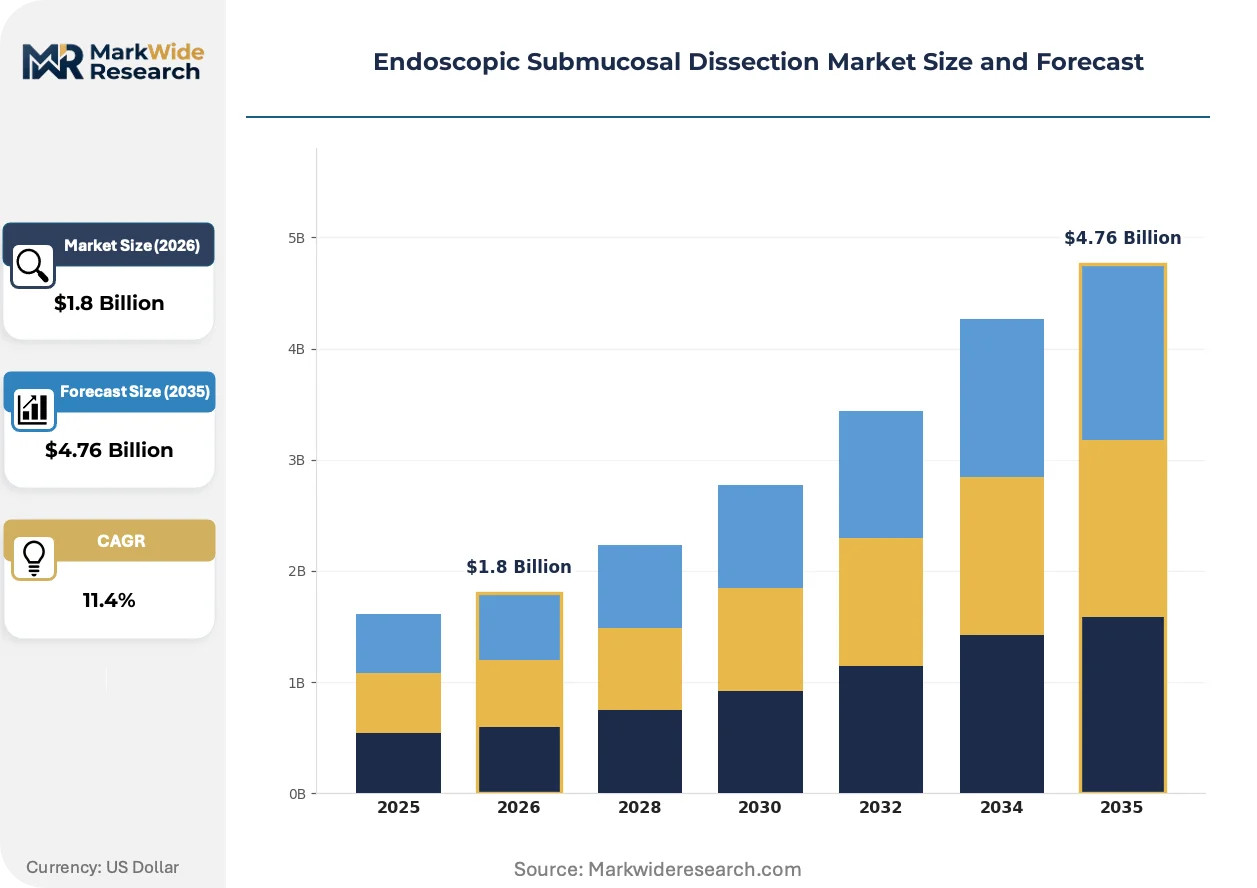
Market Dynamics
Japan's PMDA reprocessing mandates and South Korea's MFDS electromagnetic compatibility standards are compressing equipment replacement cycles while elevating procurement specifications across tertiary centers. These regulatory pressures intersect with ambulatory surgical center expansion to reshape capital allocation patterns.
Growth Catalysts
- Japan's JIS T 3255 reprocessing standard:Mandatory endoscope sterilization protocols shorten replacement intervals and sustain recurring equipment demand across domestic hospitals.
- Ambulatory surgical center proliferation:Outpatient gastrointestinal procedure volumes in Germany and South Korea accelerate same-day ESD adoption outside traditional inpatient settings.
- Hybrid imaging platforms:Narrow-band imaging integration with standard white-light systems expands lesion detection sensitivity and drives visualization system upgrades.
Market Restraints
- Single-use electrosurgical knife dependency:Proprietary tip geometries and concentrated margin pools limit generic substitution and inflate per-procedure supply costs.
- EU MDR clinical evidence requirements:Enhanced documentation burdens for reusable electrosurgical instruments extend approval timelines for novel knife designs.
- Operator training curve constraints:Prolonged skill acquisition periods restrict ESD diffusion beyond specialized tertiary centers in most geographies.
Strategic Opportunities
- Robotic-assisted ESD platforms:European university hospitals deploy automated dissection systems to bypass conventional operator training barriers.
- Carbon dioxide insufflation system upgrades:Operative field stability demands during prolonged submucosal dissection create replacement cycles for legacy insufflator fleets.
- AI-enhanced polyp detection modules:Machine learning integration with 4K visualization systems offers differentiation beyond incremental resolution improvements.
Industry Challenges
- Electrosurgical current modulation expertise:Precise energy delivery during submucosal dissection requires specialized training that outpaces workforce pipeline expansion.
- Reimbursement parity verification:National health technology assessment bodies maintain divergent ESD versus surgical resection payment schedules that distort site-of-care decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Submucosal Dissection Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Knives, Accessories, Visualization Systems End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Conventional Endoscopic, Robotic-Assisted, Hybrid Systems, Minimally Invasive Application: Gastrointestinal Disorders, Tumor Resection, Biopsy Procedures, Benign Lesion Removal |
| Companies Covered | Boston Scientific Corporation, Karl Storz SE & Co. KG, Olympus Corporation, STERIS, CONMED Corporation, FUJIFILM Holdings Corporation, HOYA Corporation, Cook Group, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Submucosal Dissection Market Emerging Trajectories
Robotic assistance, regulatory harmonization pressures, and ambulatory care migration are restructuring how ESD capabilities deploy across healthcare systems. These forces compress traditional boundaries between inpatient and outpatient settings.
Robotic-assisted ESD platforms is decentralizing procedural capability from elite tertiary centers toward community hospitals with limited conventional ESD expertise. European university hospitals in Germany and the Netherlands deploy these systems to circumvent operator training bottlenecks. The technology is decentralizing geographic concentration of complex en bloc resection capacity.
Japan's PMDA maintains stringent electromagnetic compatibility certifications under METI oversight that shape domestic procurement specifications. These requirements elevate equipment replacement costs while blocking non-compliant imports. Domestic manufacturers leverage JIS standard alignment to defend installed base positions against foreign competitors.
Hospital purchasing consortia now bundle ESD device procurement with multi-year service agreements and training commitments. Traditional distributor networks face compression as direct manufacturer relationships with ambulatory surgical centers expand. This pattern is most visible in South Korea's concentrated hospital system and Germany's regional purchasing alliances.
Endoscopic Submucosal Dissection Market Segmentation
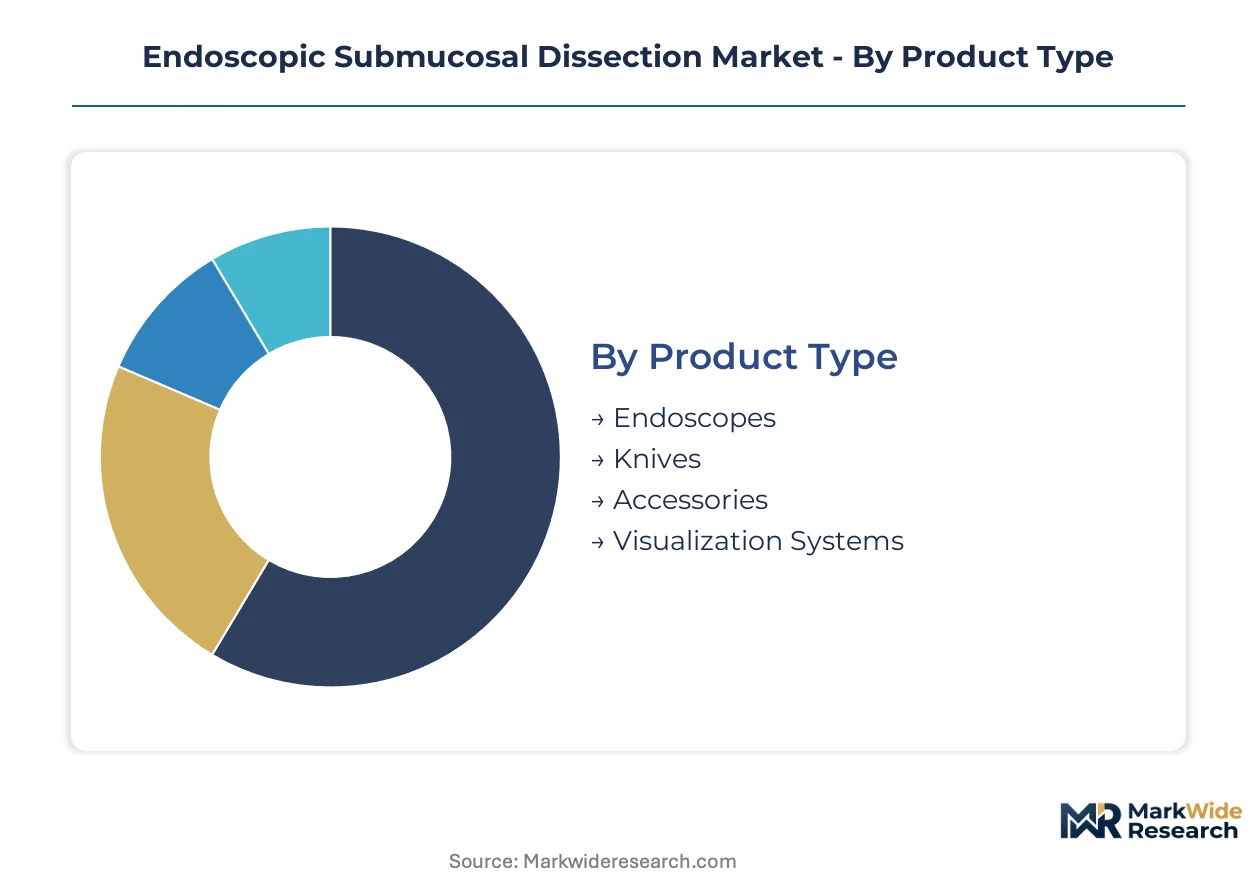
ESD market segmentation reveals how procurement priorities diverge across care settings and procedural complexity. Equipment specifications, reimbursement pathways, and operator training requirements create distinct demand profiles that reshape vendor go-to-market strategies.
Product Type:
Capital intensity and consumption patterns separate buyers into recurring revenue versus one-time procurement camps.
- Endoscopes:High-definition platforms with magnification capability and narrow-band imaging integration command premium positioning in Japanese tertiary centers. PMDA electromagnetic compatibility certifications under METI oversight compress replacement cycles and sustain domestic manufacturer preference.
- Knives:Single-use electrosurgical instruments with proprietary tip geometries resist generic substitution and generate concentrated margin pools. Ambulatory surgical centers in Germany and South Korea drive volume expansion as outpatient gastrointestinal procedures gain preference.
- Accessories:Carbon dioxide insufflation systems and electrosurgical generators maintain operative field stability during prolonged dissection.
- Visualization Systems:4K resolution upgrades with AI-enhanced polyp detection modules offer differentiation beyond incremental hardware improvements.
Knives lead volumes today; visualization systems are gaining share fastest.
End User:
Site-of-care migration restructures purchasing authority and service agreement terms across the customer base.
- Hospitals:Tertiary centers in Japan and South Korea concentrate complex en bloc resection capacity and maintain dedicated ESD training programs. JIS T 3255 reprocessing mandates elevate equipment specifications and sustain recurring replacement demand.
- Ambulatory Surgical Centers:Same-day procedure preference in Germany accelerates capital allocation toward compact, portable ESD platforms. EU MDR clinical evidence requirements for reusable instruments extend procurement decision timelines.
- Specialty Clinics:Focused gastrointestinal practices in urban clusters deploy hybrid imaging systems for lesion detection sensitivity.
- Research Institutions:European university hospitals pilot robotic-assisted platforms to circumvent conventional operator training barriers.
Hospitals dominate installed base; ambulatory surgical centers are expanding most quickly.
Technology:
Automation readiness and training curve compression determine adoption feasibility across operator skill distributions.
- Conventional Endoscopic:Standard electrosurgical knife platforms with manual dissection require prolonged skill acquisition that restricts diffusion beyond specialized centers. Japan's concentrated screening programs for early gastric cancer sustain highest procedural volumes.
- Robotic-Assisted:Automated dissection systems with precise motion scaling deploy in European university hospitals to bypass operator training bottlenecks. Germany and the Netherlands lead pilot programs for community hospital decentralization.
- Hybrid Systems:Integrated platforms combining conventional and robotic capabilities offer transitional pathways for mixed operator environments.
- Minimally Invasive:Reduced wall penetration risk and faster recovery profiles align with outpatient reimbursement incentives.
Conventional endoscopic technology holds majority share; robotic-assisted platforms show steepest expansion trajectory.
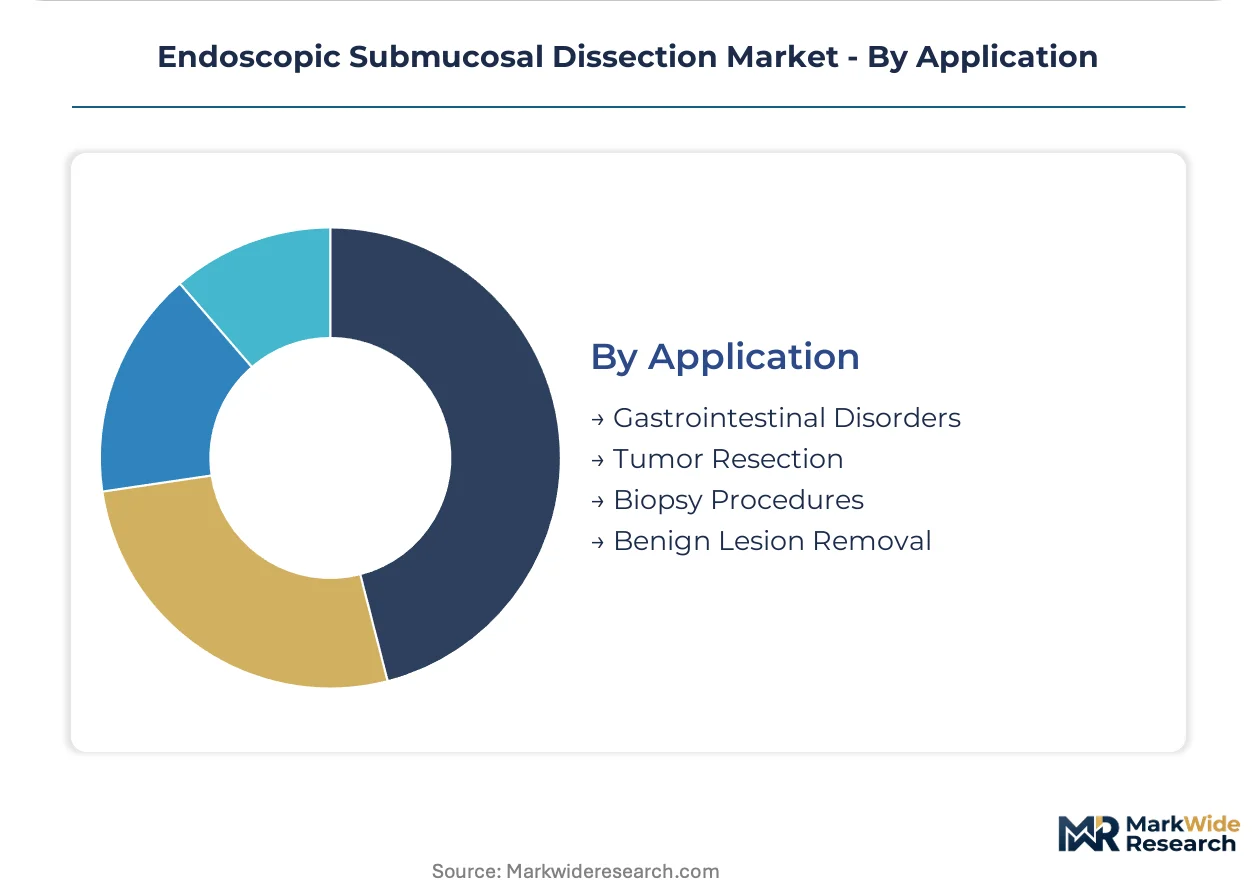
Application:
Lesion pathology and malignancy risk stratification drive equipment configuration and reimbursement pathway selection.
- Gastrointestinal Disorders:Early gastric cancer screening programs in Japan and South Korea generate highest procedural volumes and sustain specialized training pipelines. PMDA and MFDS regulatory alignment shapes domestic procurement specifications.
- Tumor Resection:En bloc resection of lesions up to several centimeters demands high-definition imaging with precise electrosurgical current modulation. Reimbursement parity verification with surgical resection distorts site-of-care decisions across national health technology assessment bodies.
- Biopsy Procedures:Diagnostic sampling applications require less specialized equipment and support broader geographic deployment.
- Benign Lesion Removal:Lower-complexity procedures suit ambulatory settings and accelerate same-day discharge protocols.
Tumor resection leads revenue contribution; gastrointestinal disorder screening shows fastest volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is compressing equipment replacement cycles in high-compliance jurisdictions while channeling procurement toward domestic manufacturers. Cost-of-compliance gaps between Japan's stringent PMDA standards and emerging markets reshape vendor market access strategies.
Japan
Early gastric cancer screening programs and aging demographics sustain the world's highest ESD procedural volumes. PMDA enforces JIS T 3255 sterilization protocols and METI electromagnetic compatibility certifications that elevate replacement costs and block non-compliant imports. Tokyo-Osaka tertiary centers concentrate specialized training pipelines and maintain dedicated ESD units.
Germany
Ambulatory surgical center expansion accelerates same-day gastrointestinal procedure migration from inpatient settings. EU MDR clinical evidence requirements for reusable electrosurgical instruments extend approval timelines and procurement decision cycles. Bavaria and North Rhine-Westphalia anchor regional purchasing alliances that bundle device procurement with multi-year service agreements.
South Korea
National health insurance reimbursement parity between ESD and surgical resection drives procedural volume growth outside traditional hospital settings. MFDS electromagnetic compatibility standards align with Japanese specifications, creating procurement specification convergence. Seoul Capital Area hospitals concentrate hybrid imaging platform deployments and AI-enhanced polyp detection pilots.
United States
FDA premarket notification pathways emphasize electrical safety testing and ISO 10993 biocompatibility validation for ESD device clearance. Reimbursement fragmentation across commercial payers and Medicare Advantage distorts site-of-care decisions toward hospital outpatient departments. Greater Boston and Pacific Northwest research institutions pilot robotic-assisted platforms to circumvent operator training barriers.
Netherlands
University hospitals in the Randstad region deploy robotic-assisted ESD systems to decentralize complex resection capability toward community hospitals. EU Green Deal procurement criteria increasingly shape capital equipment specifications for energy-efficient visualization systems. Eindhoven's medical technology cluster anchors electrosurgical generator manufacturing and carbon dioxide insufflation system development.
Endoscopic Submucosal Dissection Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with single-use consumables concentrating margin pools around proprietary geometries while capital equipment fragments across imaging and energy platforms. The vendor base organizes into three archetypes: integrated endoscopy system houses, electrosurgical instrument specialists, and disposable accessory pure-plays. Consolidation pressure runs highest among visualization system providers seeking AI differentiation, while knife segments resist integration due to concentrated proprietary margins. Competitive moves center on multi-year service bundling and direct ambulatory surgical center relationships that bypass traditional distributor networks.
Among Asia-Pacific integrated system houses, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions spanning visualization platforms and electrosurgical portfolios. Boston Scientific Corporation anchors North American distribution infrastructure for disposable ESD accessories. These three exemplify divergent strategic postures: Japanese manufacturers leverage regulatory alignment with PMDA standards to defend domestic installed bases, while US-based players prioritize ambulatory channel expansion through direct purchasing relationships.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Karl Storz SE & Co. KG |
| Olympus Corporation |
| STERIS |
| CONMED Corporation |
| FUJIFILM Holdings Corporation |
| HOYA Corporation |
| Cook Group |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Robotic-assisted dissection platform adoption in European university hospitals simultaneously compresses training cost economics and concentrates procurement authority toward integrated system vendors. This technology transition elevates capital equipment bundling while fragmenting single-use consumable sourcing across ambulatory surgical centers.
Pricing Analysis
Distributor margin compression runs deepest in single-use electrosurgical knife segments where proprietary tip geometries sustain manufacturer pricing power. Three-tier pricing structure across premium Olympus-FUJIFILM platforms, mid-tier regional suppliers, and economy generic alternatives stratifies procurement decisions. Cost compression in standard-definition visualization systems intensifies as 4K upgrade cycles accelerate. Ambulatory surgical centers exhibit highest price sensitivity; Japanese tertiary centers anchored by JIS compliance requirements show least.
Supply Chain Analysis
Precision electrosurgical instrument manufacturing workforce availability concentrates in Japan's Tokyo-Osaka corridor, Germany's Eindhoven-Tuttlingen axis, and South Korea's Seoul Capital Area. Supply draws from specialized ceramic tip substrates, medical-grade stainless steel alloys, and carbon dioxide insufflation compressor components. Single-source vulnerability in proprietary knife geometries elevates procurement risk for non-integrated buyers. Distribution runs through manufacturer-direct relationships with ambulatory surgical centers and regional purchasing alliances in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by ambulatory surgical center migration toward premium JIS-compliant platforms with bundled training commitments.
For Market Incumbents: Cement installed base positions through backward integration into electrosurgical generator manufacturing and exclusive multi-year service agreements with Japanese tertiary centers. Threat from robotic-assisted platform entrants demands accelerated AI-enhanced polyp detection R&D investment. Channel control via direct ambulatory surgical center relationships neutralizes distributor margin extraction. For New Entrants and Emerging Players: Enter via compact carbon dioxide insufflation system segments where legacy fleet replacement cycles create white-space. German regional purchasing alliances and South Korean same-day procedure centers represent most penetrable geographies. Go-to-market angle: energy-efficient visualization platforms aligned with EU Green Deal procurement criteria. For Investors and Strategic Acquirers: Roll-up economics work for disposable accessory pure-plays because concentrated margin pools in proprietary knife geometries resist integrated system house absorption. Five-to-ten year viability hinges on reimbursement parity expansion across national health technology assessment bodies. Signal to watch: FDA premarket notification pathway acceleration for novel electrosurgical instrument designs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements compress approval timelines for reusable instruments entering German markets. |
| Hospital System Partnership | Direct relationships with Seoul Capital Area centers bypass traditional distributor networks in South Korea. |
| Software Companion Development | AI-enhanced polyp detection modules differentiate 4K visualization platforms beyond incremental resolution gains. |
| Reimbursement Strategy | Parity verification with surgical resection across Medicare Advantage plans shapes US site-of-care decisions. |
| FDA Submission | Electrical safety testing under ISO 10993 frameworks clears premarket notification for novel knife geometries. |
Methodological Framework
Bottom-up ambulatory surgical center procedure modeling reconciled against top-down electrosurgical instrument shipment tracking forms the analytical core. Primary interviews with gastrointestinal oncology department heads, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers cross-validated against secondary sources including FDA 510(k) filings, PMDA approval databases, EU MDR notified body certificates, and hospital procurement contract repositories.
Input-output matrices map electrosurgical knife consumption rates to endoscope installation bases across product type, end user, technology, and application segmentation dimensions. CAGRs derive from regression-weighted procedure volume projections and equipment replacement cycle analysis. Forecast inputs incorporate JIS T 3255 reprocessing mandate compliance costs and MFDS electromagnetic compatibility standard adoption curves.
The model holds under stable reimbursement parity conditions; deviation in national health technology assessment body payment schedule revisions would shift site-of-care migration trajectories. Material deviation in PMDA regulatory stringency or EU MDR clinical evidence burden warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Esophageal Stents Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Global Endoscopes Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market