
 Americas Medical Suction Device Market | 2026-2036
Americas Medical Suction Device Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Medical Suction Device Market Outlook
ISO 13485 certification is redrawing competitive boundaries in the Americas Medical Suction Device Market, forcing smaller suppliers to either upgrade quality management systems or exit hospital procurement channels. Cardinal Health leverages its distribution density across North American health systems to sustain contract renewal rates. Medela AG anchors its position through specialized vacuum technology leadership in neonatal and wound care segments. Drive DeVilbiss Healthcare competes aggressively on portable device portability and home care channel penetration.
Medical suction devices are electromechanical or pneumatic instruments engineered to generate controlled negative pressure, typically ranging from 80 to 550 mmHg, for the evacuation of fluids, secretions, or gases from body cavities during surgical intervention, emergency airway management, or post-operative recovery. Portable suction devices dominate ambulatory and emergency deployment scenarios due to their battery-operated mobility and reduced infrastructure dependency. Wall-mounted suction units retain institutional preference in operating theaters where continuous, high-volume evacuation capacity supports complex surgical procedures. Electric technology leads the technology dimension, though battery-operated variants are gaining traction in pre-hospital emergency medical services where power independence determines clinical utility.
FDA 510(k) premarket notification requirements govern device commercialization in the United States, while Health Canada's Medical Devices Bureau enforces parallel standards north of the border; both frameworks elevate barrier-to-entry for non-compliant manufacturers. Brazil's ANVISA registration pathway adds another compliance layer for suppliers targeting Latin America's largest hospital procurement market. Stakeholders must monitor evolving battery safety standards and cross-border harmonization initiatives between U.S. and Canadian regulators to anticipate certification cost shifts and timeline compression.
Market Dynamics
ISO 13485 certification requirements are compressing supplier participation in hospital procurement channels across the Americas, forcing quality management system upgrades that favor established manufacturers with dedicated regulatory affairs infrastructure over smaller competitors.
Growth Catalysts
- ANVISA Registration Pathway:Brazil's streamlined medical device registration is accelerating market entry for compliant suppliers targeting Latin America's largest hospital procurement corridor.
- Ambulatory Surgery Center Expansion:Outpatient procedural volume growth across the United States is driving fleet expansion for portable suction devices in same-day surgical settings.
- Battery Chemistry Advancements:Lithium-ion energy density improvements are extending operational runtime for pre-hospital emergency medical services deployments.
Market Restraints
- FDA 510(k) Compliance Burden:Premarket notification requirements impose substantial documentation costs and timeline uncertainty for non-established manufacturers seeking U.S. commercialization.
- Raw Material Concentration:Rare earth magnet supply for electric suction motor assemblies concentrates in Asian processing facilities, exposing manufacturers to geopolitical supply disruption.
- Pneumatic Infrastructure Dependency:Wall-mounted suction units require hospital-grade compressed air systems that limit deployment flexibility in older clinical facilities.
Strategic Opportunities
- Home Care Channel Penetration:Post-acute care transition programs in the United States are creating demand for lightweight, patient-operated suction devices outside institutional settings.
- Health Canada Harmonization:Cross-border regulatory alignment initiatives between U.S. and Canadian authorities are reducing dual-certification costs for North American market access.
- Wound Care Segment Specialization:Negative pressure wound therapy integration with standard suction platforms offers margin expansion through clinical application diversification.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Device servicing and preventive maintenance programs face staffing constraints as health systems compete for qualified technical personnel.
- Legacy System Integration:New electric suction platforms must interface with existing hospital electrical and alarm infrastructure, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Medical Suction Device Market |
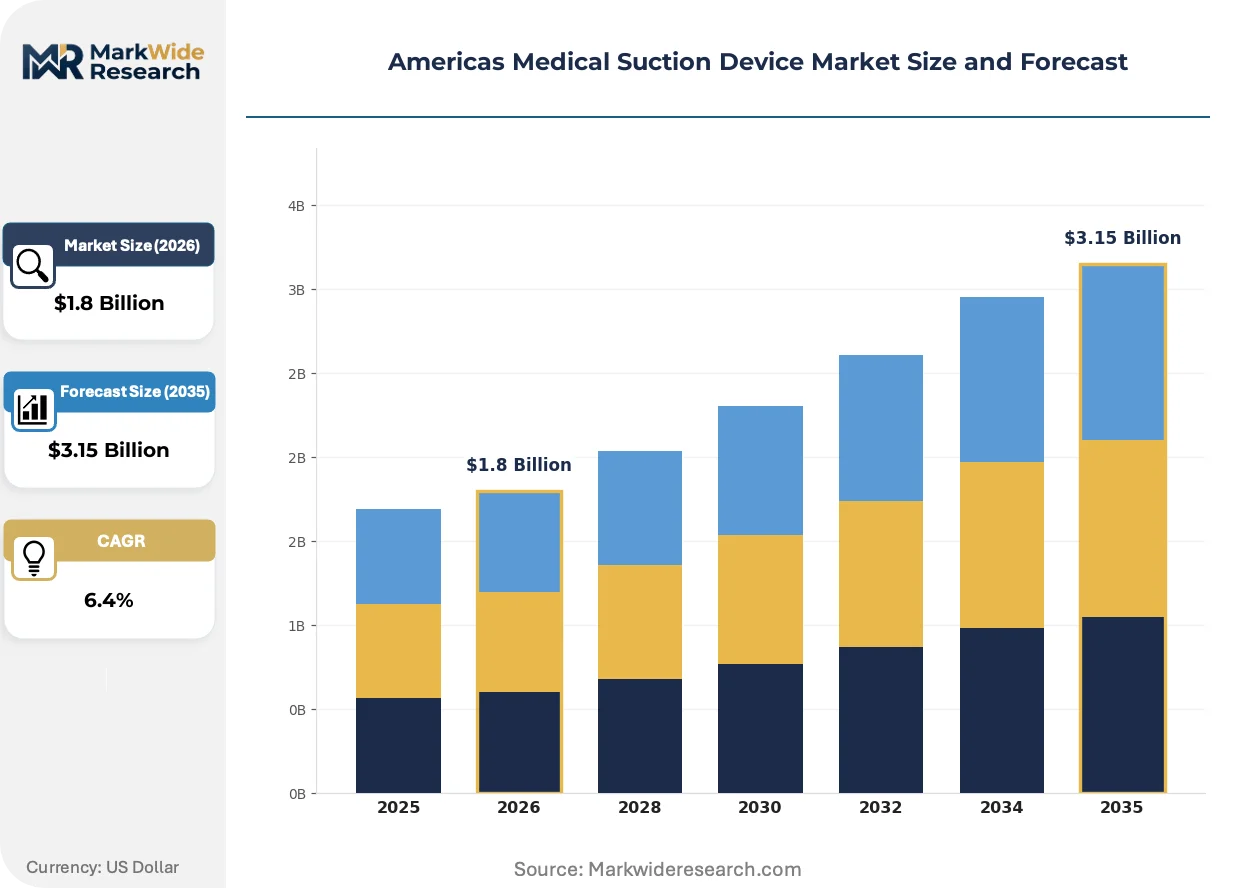
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable Suction Devices, Wall-Mounted Suction Units, Electric Suction Pumps, Surgical Suction Instruments End User: Hospitals, Ambulatory Surgery Centers, Emergency Medical Services, Home Care Technology: Electric, Manual, Battery-Operated, Pneumatic Application: Respiratory Care, Gastrointestinal Care, Surgical Procedures, Wound Care |
| Companies Covered | Precision Medical, Inc., Drive DeVilbiss Healthcare, Medela AG, ZOLL Medical Corporation, Laerdal Medical, Allied Healthcare Products, Inc., Cardinal Health, Inc., Olympus Corporation, Amsino International, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Medical Suction Device Market Strategic Shifts
Suction device architecture is splitting along mobility and power-source lines as clinical settings diversify. Manufacturers are responding with parallel development tracks rather than universal platforms.
Smart battery management systems with integrated charge-state monitoring and thermal protection are bifurcating the portable device category. Emergency medical services operators in the United States are prioritizing these intelligent power platforms for ambulance deployment. The technology is compressing warranty liability exposure while extending service intervals, reshaping aftermarket revenue models.
FDA alignment with Health Canada's Medical Devices Bureau on electrical safety standards is reducing redundant testing requirements for cross-border suppliers. Manufacturers targeting both markets now pursue coordinated submission strategies rather than sequential national approvals. Canadian hospital procurement authorities are accelerating acceptance of U.S.-cleared devices with validated bi-national certification packages.
Consolidated purchasing organizations are consolidating vendor rosters across multi-hospital health systems in the southeastern United States. Single-source contracts for suction device categories are displacing department-level procurement autonomy. Brazil's private health networks are replicating this concentration model, negotiating enterprise agreements that bundle maintenance and consumable supply obligations.
Americas Medical Suction Device Market Segmentation
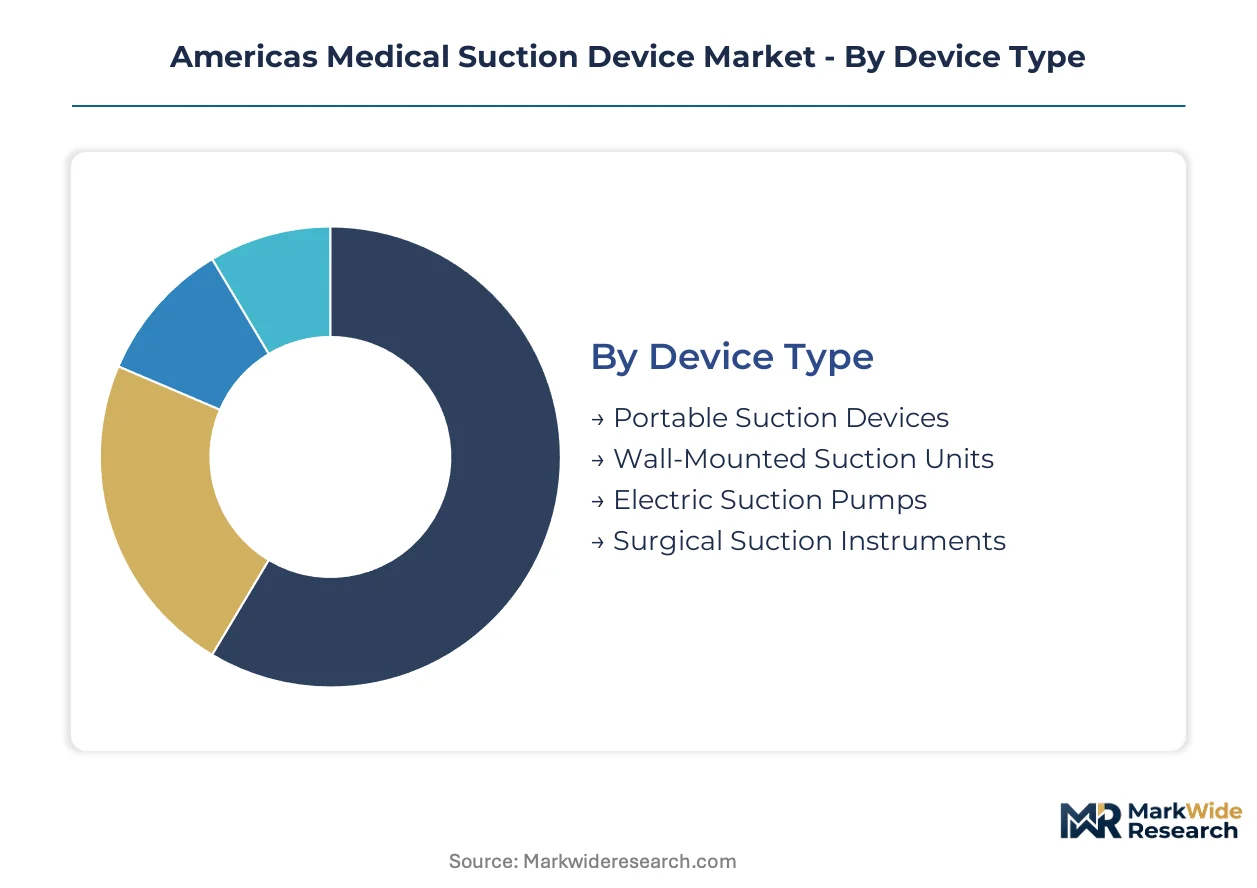
Medical suction device procurement patterns diverge sharply across clinical settings, with mobility requirements and power infrastructure availability determining hardware selection. Manufacturers must align product architectures with specific end-use workflows rather than pursuing universal platform designs.
Device Type:
Margin pools concentrate in portable configurations where battery technology differentiation commands pricing premiums and recurring consumable attachments generate aftermarket revenue streams.
- Portable Suction Devices:Battery-operated units weighing under 5 kg dominate pre-hospital emergency deployments across the United States and Brazilian metropolitan corridors. Demand concentrates in ambulance fleets and air medical services where power independence determines clinical utility during patient transport. Lithium-ion energy density improvements are extending operational runtime beyond 45 minutes, compressing warranty liability exposure for EMS operators.
- Wall-Mounted Suction Units:Fixed installations delivering continuous 80-550 mmHg negative pressure retain institutional preference in operating theaters throughout North American hospital systems. Demand concentrates in surgical suites performing complex procedures requiring sustained high-volume evacuation capacity. Compressed air infrastructure dependency limits deployment flexibility in older clinical facilities across Latin America.
- Electric Suction Pumps:Mains-powered stationary units serve central supply roles in medium-sized hospitals with reliable electrical infrastructure.
- Surgical Suction Instruments:Procedure-specific handpieces and cannulas integrate with standard suction platforms for specialized evacuation tasks.
Wall-mounted suction units hold installed capacity across hospital systems. Portable suction devices are rotating up the share rankings as ambulatory care networks expand.
End User:
Procurement authority is fragmenting across customer types, with consolidated purchasing organizations displacing department-level autonomy in multi-hospital networks while home care channels demand simplified patient-operated designs.
- Hospitals:Large health systems in the southeastern United States negotiate enterprise agreements bundling maintenance and consumable supply obligations. Demand concentrates in surgical services and intensive care units where 24/7 suction availability supports critical care workflows. ISO 13485 certification requirements favor established manufacturers with dedicated regulatory affairs infrastructure.
- Ambulatory Surgery Centers:Same-day surgical facilities across the United States are expanding portable device fleets as outpatient procedural volumes climb. Demand concentrates in ophthalmology, orthopedics, and gastroenterology suites requiring rapid setup and breakdown capabilities. Battery-operated mobility reduces infrastructure dependency in leased clinical spaces.
- Emergency Medical Services:Pre-hospital providers prioritize intelligent battery management systems with integrated charge-state monitoring for ambulance deployment.
- Home Care:Post-acute care transition programs create demand for lightweight, patient-operated suction devices outside institutional settings.
Hospitals anchor procurement volume. Ambulatory Surgery Centers are gaining share fastest as outpatient migration accelerates.
Technology:
Power source selection determines regulatory pathway complexity and service interval economics, with electric platforms facing stricter electrical safety testing than pneumatic alternatives.
- Electric:Mains-powered electromechanical pumps deliver consistent negative pressure for institutional settings with reliable grid infrastructure. Demand concentrates in North American hospitals where FDA 510(k) clearance and Health Canada alignment requirements elevate compliance investment. Cross-border harmonization initiatives are reducing redundant testing burdens for bi-national certification packages.
- Battery-Operated:Lithium-ion platforms with smart thermal protection are bifurcating the portable category for emergency medical services deployment. Demand concentrates in U.S. ambulance fleets where intelligent power management compresses warranty liability exposure. Smart battery systems extend service intervals and reshape aftermarket revenue models toward predictive maintenance.
- Manual:Hand-powered aspirators serve backup and resource-constrained environments requiring no external power source.
- Pneumatic:Compressed air-driven units leverage existing hospital infrastructure but limit deployment flexibility.
Electric technology holds installed base dominance. Battery-operated configurations are climbing the fastest as pre-hospital emergency services modernize.
Application:
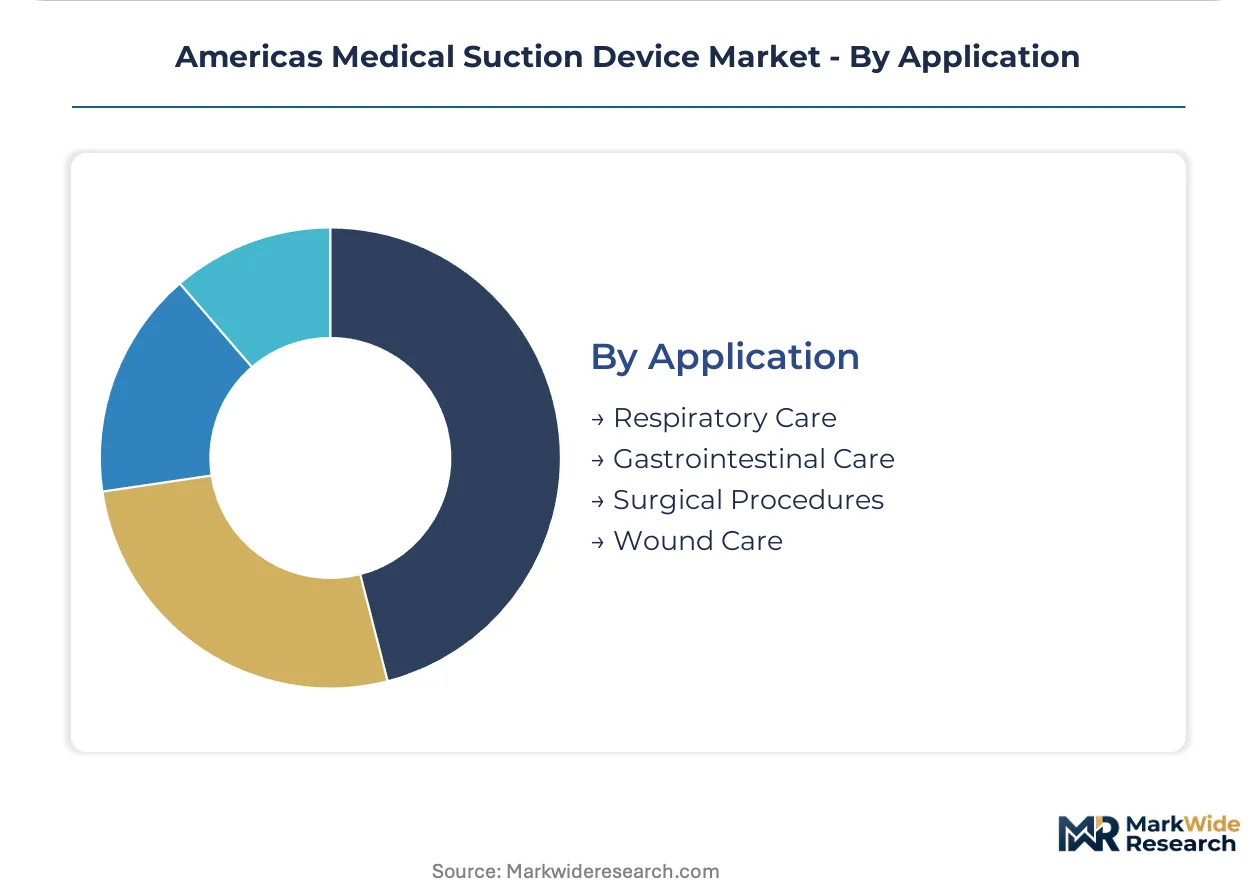
Clinical workflow integration requirements vary substantially across procedure types, with surgical applications demanding highest evacuation capacity and wound care enabling margin expansion through negative pressure therapy convergence.
- Surgical Procedures:Operating theater deployments require sustained high-volume fluid and tissue evacuation across general, orthopedic, and cardiovascular specialties. Demand concentrates in Brazil's southeastern hospital corridor where private health networks are modernizing surgical infrastructure. ANVISA registration compliance accelerates market entry for suppliers targeting Latin America's largest procurement market.
- Wound Care:Negative pressure wound therapy integration with standard suction platforms offers clinical application diversification and margin expansion. Demand concentrates in post-acute care settings across the United States where reimbursement incentives support advanced wound management. Specialized vacuum technology leadership anchors competitive positioning in this segment.
- Respiratory Care:Airway clearance applications in emergency and critical care settings prioritize rapid suction activation.
- Gastrointestinal Care:Endoscopic and enteric decompression procedures require controlled low-pressure evacuation capabilities.
Surgical applications hold procedure volume leadership. Wound care is rotating up the share rankings as negative pressure therapy adoption broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authorities and ambulatory surgery center operators concentrate device demand across distinct metropolitan corridors. Brazil's private health networks, U.S. southeastern health systems, and Canadian hospital procurement authorities each shape regional competitive dynamics through divergent certification requirements and infrastructure investment cycles.
United States
FDA 510(k) premarket notification requirements govern commercialization pathways for electromechanical suction platforms. Ambulatory surgery centers in Texas and Florida are expanding portable device fleets as outpatient procedural volumes climb. Southeastern hospital procurement authorities negotiate enterprise agreements bundling maintenance obligations across multi-hospital networks.
Brazil
ANVISA registration compliance accelerates market entry for suppliers targeting Latin America's largest hospital procurement corridor. Private health networks in São Paulo and Rio de Janeiro are modernizing surgical infrastructure across southeastern hospital clusters. Battery-operated portable units gain traction in metropolitan ambulance fleets serving dense urban populations.
Canada
Health Canada's Medical Devices Bureau enforces electrical safety standards parallel to FDA requirements, elevating barrier-to-entry for non-compliant manufacturers. Cross-border harmonization initiatives with U.S. regulators reduce redundant testing burdens for bi-national certification packages. Ontario and Quebec hospital procurement authorities accelerate acceptance of U.S.-cleared devices with validated certification packages.
Mexico
COFEPRIS medical device registration adds compliance layering for suppliers targeting hospital procurement channels in Mexico City and Monterrey metropolitan areas. Northern border state health systems prioritize equipment compatibility with U.S. referral networks. Manufacturing cost advantages attract assembly operations for portable suction device components serving North American distribution.
Americas Medical Suction Device Market Competitive Environment
Player mix skews toward diversified health systems suppliers and specialized vacuum technology firms rather than pure-play suction device manufacturers. Market structure concentrates around three strategic tiers: established distributors with regulatory affairs infrastructure, specialized neonatal and wound care technology leaders, and portable device specialists competing on battery-operated mobility. Dominant competitive moves include ISO 13485 certification upgrades that compress smaller supplier participation and cross-border harmonization strategies that reduce dual-certification costs for North American market access.
Among diversified health systems suppliers, Cardinal Health leverages distribution density across North American procurement channels. Drive DeVilbiss Healthcare and Medela AG occupy distinct positioning vectors—portable device mobility specialization versus vacuum technology leadership in clinical segments. Precision Medical, Inc. and Allied Healthcare Products, Inc. represent mid-tier fabrication specialists competing on regulatory compliance velocity rather than scale economies. These archetypes illustrate how certification infrastructure and channel access determine sustainable positioning more than manufacturing scale alone.
| Leading Market Players |
|---|
| Precision Medical, Inc. |
| Drive DeVilbiss Healthcare |
| Medela AG |
| ZOLL Medical Corporation |
| Laerdal Medical |
| Allied Healthcare Products, Inc. |
| Cardinal Health, Inc. |
| Olympus Corporation |
| Amsino International, Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, compressing participation to manufacturers with dedicated quality management infrastructure while allowing certified incumbents to command premiums through regulatory compliance bundling.
Pricing Analysis
Cost-plus contracts with rare earth magnet price indexation dominate procurement agreements for electric suction motor assemblies. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared devices with bi-national certification from single-market approvals and non-certified alternatives. Cost compression in the standard tier is intensifying because Brazilian private health networks are consolidating vendor rosters. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraint, while southeastern U.S. hospital systems show lowest sensitivity given bundled maintenance obligations.
Supply Chain Analysis
China and Japan anchor rare earth magnet processing and lithium-ion cell manufacturing for battery-operated portable units. Electric suction motor assemblies draw from Asian processing facilities for neodymium and dysprosium feedstock. Single-source vulnerability concentrates in rare earth separation capacity, exposing manufacturers to export restriction risk. Distribution runs through Cardinal Health's North American logistics network and regional medical device distributors serving Brazilian metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital infrastructure modernization cycles are driving recovery as deferred surgical capacity investments release pent-up procurement demand across the Americas.
For Market Incumbents: Secure ISO 13485 certification maintenance as the priority defensive move against emerging competitors lacking quality management infrastructure. Deepen backward integration into battery pack assembly to capture lithium-ion cost compression and compress warranty liability exposure. Channel control through GPO contract renewals anchors positioning against price-aggressive portable specialists. For New Entrants and Emerging Players: ANVISA's streamlined registration pathway offers fastest certification fast-track for Latin American market entry. Target Brazil's southeastern private health networks where surgical infrastructure modernization outpaces established supplier capacity. Home care channel penetration provides white-space expansion as post-acute transition programs create demand for patient-operated designs outside institutional procurement channels. For Investors and Strategic Acquirers: FDA-Health Canada harmonization on electrical safety standards reshapes the acquisition landscape by reducing dual-certification costs and accelerating cross-border revenue scalability. Mid-tier fabrication specialists with regulatory compliance velocity represent prime acquisition targets over scale-dependent manufacturers. Watch ANVISA registration backlog clearance rates as inflection indicator for Brazilian market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Upgrade | Quality management infrastructure gates hospital procurement channel access across North American health systems. |
| Bi-National Certification Package | FDA-Health Canada alignment reduces redundant testing burdens for cross-border market penetration. |
| Smart Battery System Integration | Intelligent power management compresses warranty liability for EMS operators and extends service intervals. |
| ANVISA Registration Fast-Track | Streamlined pathway accelerates market entry for suppliers targeting Latin America's largest hospital procurement corridor. |
| Home Care Channel Development | Post-acute transition programs create demand for lightweight, patient-operated suction devices outside institutional settings. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and emergency medical services fleet operators. Secondary validation drew from FDA 510(k) premarket notification databases, Health Canada Medical Devices Bureau filings, ANVISA registration records, and hospital procurement contract disclosures. Bottom-up device shipment estimates triangulated against top-down health system capital expenditure patterns.
Across the analysis window, volume and value outputs reflect segmented modeling across device type, end user, technology, and application dimensions with regional regulatory cluster overlays. CAGRs derive from procedure volume elasticity to surgical infrastructure investment cycles and outpatient migration trends. Forecast inputs incorporate lithium-ion energy density improvement curves and ANVISA registration processing velocity assumptions.
Decision-makers should treat outputs as directional under stable regulatory harmonization and raw material supply continuity assumptions; material deviation would warrant model refresh. Specific risk factors include rare earth export restriction escalation and biomedical engineering talent scarcity compressing preventive maintenance program scalability. Recalibration cycles align with material shifts in battery chemistry advancement and cross-border certification alignment initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
South Korea ECG Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Cranial Perforator Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market