
 Vortex Mixer Market | 2026-2036
Vortex Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Vortex Mixer Market Outlook
Trained biomedical technicians and certified laboratory equipment specialists is redrawing competitive boundaries in the vortex mixer landscape. Scilogex leverages its vertical integration in brushless motor assembly to control cost structures across entry-level and mid-tier units. Thermo Fisher Scientific anchors its position through extensive direct sales networks that reach institutional buyers in North America and Europe. IKA Works differentiates via precision engineering heritage, sustaining premium positioning in pharmaceutical quality control applications.
A vortex mixer is an orbital shaking instrument that generates rapid circular motion at speeds typically ranging from hundreds to thousands of revolutions per minute, using a rubber cup or platform to suspend and homogenize liquid samples in tubes or flasks. Its primary purpose is to achieve rapid, reproducible mixing of reagents, cell suspensions, and chemical solutions without introducing mechanical shear damage. Digital vortex mixers now command the fastest expansion within the product type dimension, as programmable speed and time parameters align with GLP documentation requirements in regulated laboratories. Multi-tube configurations concentrate margin pools, since pharmaceutical and genomics workflows demand parallel processing capacity that analog units cannot deliver. Sample preparation dominates application-level demand, though biological research is gaining share as CRISPR workflows and cell culture protocols proliferate across research institutes.
FDA 21 CFR Part 11 compliance requirements shape digital vortex mixer specifications in United States pharmaceutical laboratories, while EU MDR and REACH frameworks constrain material selection and validation documentation for European market access. ISO 9001 and ISO 13485 certifications function as baseline qualifiers for OEM partnerships with clinical diagnostics manufacturers. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility directives in Europe recast motor efficiency standards and end-of-life recycling obligations for laboratory equipment portfolios.
Market Dynamics
Digital control interfaces and brushless motor technologies are displacing legacy analog designs across institutional laboratories, compressing replacement cycles and elevating performance specifications for sample preparation workflows.
Growth Catalysts
- FDA 21 CFR Part 11:Compliance mandates in United States pharmaceutical laboratories accelerate digital vortex mixer adoption for GLP documentation and audit trails.
- CRISPR workflows:Proliferating gene-editing protocols in biological research institutes expand multi-tube configuration requirements for parallel sample processing.
- Brushless motor efficiency:Reduced maintenance demands and extended operational lifespans align with high-throughput automation needs in genomics facilities.
Market Restraints
- Rare earth magnet supply:Brushless motor production depends on neodymium concentrate, with processing concentrated in China creating input cost volatility.
- EU MDR validation timelines:Extended conformity assessment procedures for clinical diagnostics integration delay product launches in European markets.
- Manual vortexing persistence:Budget-constrained academic laboratories retain handheld analog units as substitutes for automated platforms.
Strategic Opportunities
- India biopharma expansion:CDSCO regulatory harmonization and PLI scheme incentives attract contract research organization investment in analytical instrumentation.
- Cloud-connected diagnostics:Integration of IoT-enabled vortex mixers with laboratory information management systems creates recurring service revenue streams.
- Extended producer responsibility:EU directives on end-of-life equipment recycling position remanufacturing specialists for circular economy participation.
Industry Challenges
- Biomedical technician certification:Shortage of factory-trained service personnel constrains aftermarket support capacity for digital platform maintenance.
- ISO 13485 compliance costs:Small-scale OEMs face capital intensity for quality management system certification required by clinical diagnostics manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vortex Mixer Market |
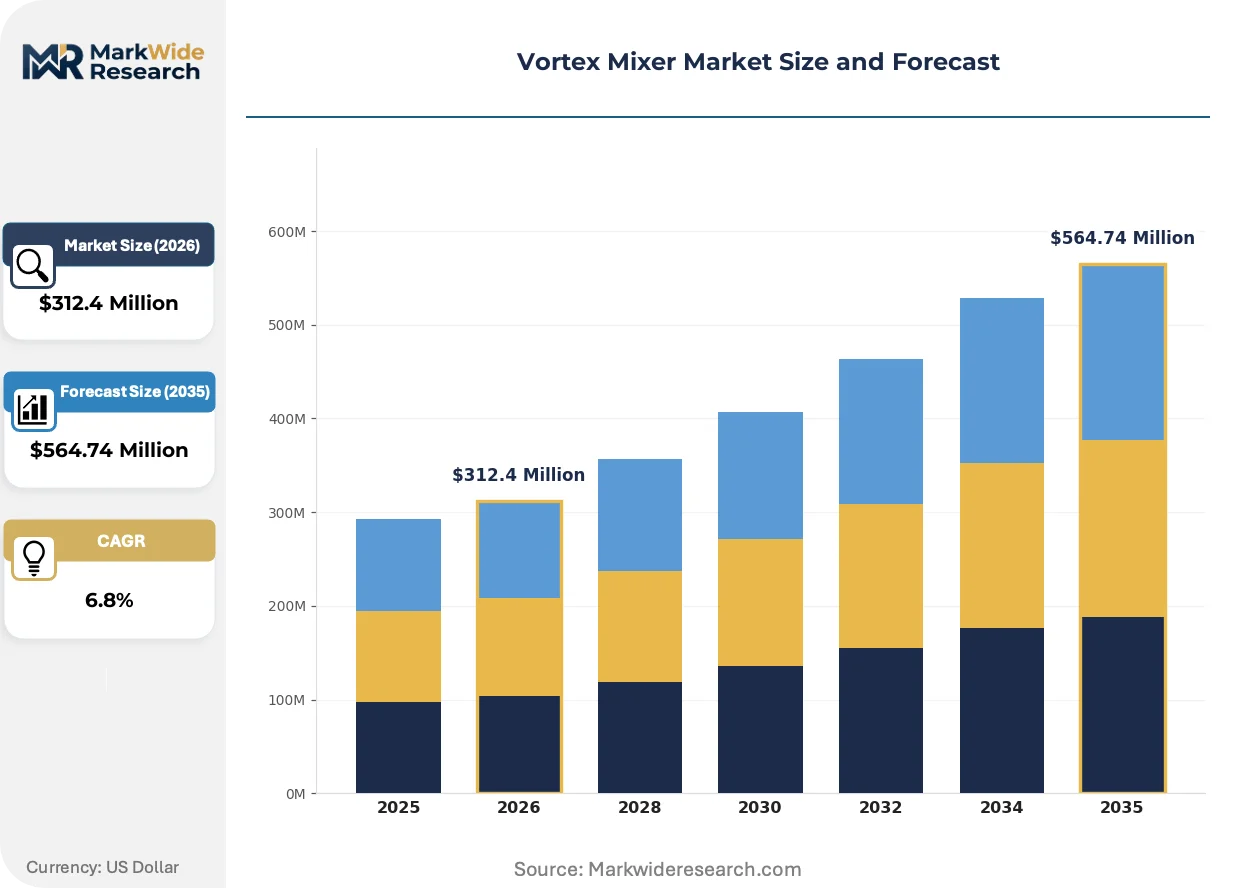
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Vortex Mixer, Digital Vortex Mixer, Analog Vortex Mixer, Multi-Tube Vortex Mixer End User: Laboratories, Research Institutes, Clinical Facilities, Educational Organizations Application: Sample Preparation, Chemical Analysis, Biological Research, Quality Control Distribution Channel: Online Retail, Direct Sales, Medical Supply Distributors, Laboratory Equipment Stores |
| Companies Covered | Scilogex, VELP Scientifica, Thermo Fisher Scientific, Heidolph Instruments, VWR International, Eppendorf, Biosan, IKA Works, Benchmark Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vortex Mixer Market Strategic Shifts
Programmable speed parameters and multi-position platforms are redefining instrument specifications, while connectivity features and sustainability mandates reshape competitive differentiation across laboratory equipment portfolios.
Brushless DC motor technology is fragmenting the traditional vortex mixer architecture by eliminating mechanical commutation wear points. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these platforms for validated dissolution testing protocols. The shift compresses maintenance intervals from quarterly to annual schedules, reducing total cost of ownership calculations for procurement committees.
REACH substance restrictions on rubber cup elastomers are forcing material substitutions in European market access strategies. ECHA candidate list updates for phthalate plasticizers require reformulation of consumable contact surfaces. German and French laboratory distributors now demand full material disclosure documentation as a baseline qualification for tender participation.
Consolidated purchasing through group procurement organizations is concentrating buyer power among United States health system networks. Independent laboratory supply distributors lose share to direct manufacturer contracts with integrated delivery networks. The pattern is most pronounced in academic medical centers consolidating research infrastructure spending under centralized capital allocation committees.
Vortex Mixer Market Segmentation
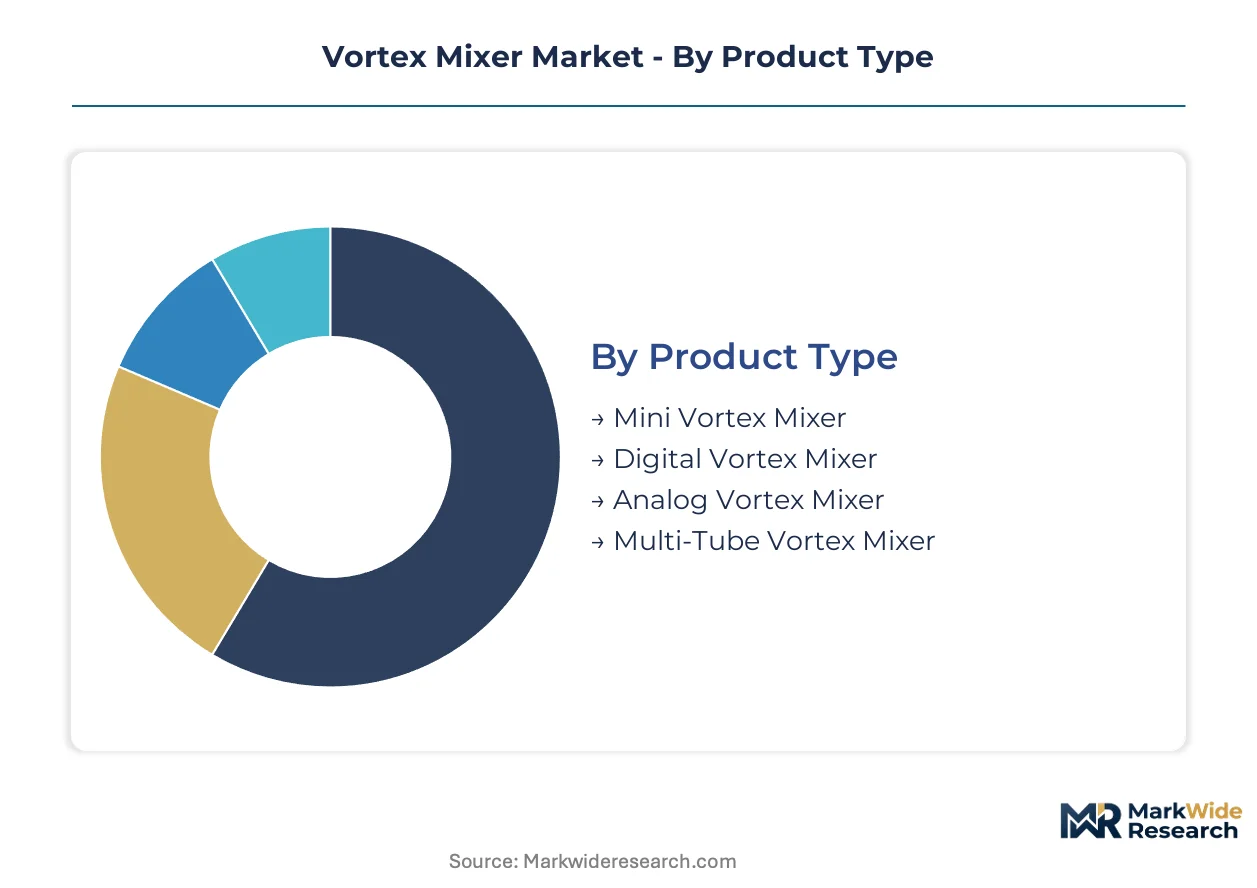
Segmentation in the vortex mixer market exposes how procurement patterns diverge across institutional budgets, regulatory requirements, and workflow automation levels. Understanding these splits enables suppliers to align motor technology investments with the specific performance tiers each buyer segment demands.
Product Type:
Margin pools concentrate in programmable platforms where GLP documentation commands pricing premiums over mechanical alternatives.
- Digital Vortex Mixer:Programmable speed and time parameters enable validated protocols with electronic audit trails. FDA 21 CFR Part 11 compliance requirements in United States pharmaceutical laboratories accelerate displacement of analog units. Brushless motor architectures reduce maintenance intervals from quarterly to annual schedules.
- Multi-Tube Vortex Mixer:Parallel processing configurations accommodate high-throughput genomics workflows and pharmaceutical quality control batches. Germany and Switzerland lead adoption for dissolution testing protocols where reproducibility standards are stringent. CRISPR sample preparation demands are expanding configuration requirements.
- Mini Vortex Mixer:Compact footprint serves space-constrained academic laboratories and field research deployments.
- Analog Vortex Mixer:Mechanical speed control persists in budget-constrained educational settings where documentation requirements are minimal.
Digital vortex mixer holds installed capacity. Multi-tube vortex mixer is rotating up the share rankings.
End User:
Procurement authority patterns split between centralized health system networks and fragmented academic purchasing committees.
- Laboratories:Commercial and institutional testing facilities demand validated equipment with ISO 9001 certification for OEM partnerships. Consolidated purchasing through United States group procurement organizations concentrates buyer power among integrated delivery networks.
- Clinical Facilities:Diagnostic laboratories require ISO 13485 quality management systems for regulatory compliance. EU MDR validation timelines delay product launches but deepen supplier relationships with conformity assessment bodies.
- Research Institutes:CRISPR and cell culture protocol proliferation drives multi-tube configuration demand.
- Educational Organizations:Capital constraints sustain analog unit retention despite digital platform advantages.
Laboratories command volume leadership. Clinical facilities are climbing the fastest in procurement value per installation.
Application:
Workflow standardization intensity determines whether buyers accept premium pricing for programmable platforms.
- Sample Preparation:Dominates application-level demand across genomics, proteomics, and clinical diagnostics workflows. Biological research institutes in China are expanding procurement to support high-throughput automation needs.
- Quality Control:Pharmaceutical manufacturing requires validated mixing protocols with full documentation trails. German quality control laboratories specify brushless motor platforms for dissolution testing reproducibility.
- Biological Research:Gene-editing protocol proliferation expands multi-tube requirements.
- Chemical Analysis:Standardized reagent mixing sustains steady analog unit replacement cycles.
Sample preparation anchors current installed base. Quality control is gaining share fastest as regulatory documentation requirements tighten.
Distribution Channel:
Channel economics reflect whether buyers prioritize technical consultation or transactional efficiency.
- Direct Sales:Extensive manufacturer networks reach institutional buyers in North America and Europe with factory-trained biomedical technicians. Consolidated academic medical center purchasing favors direct contracts over distributor intermediation.
- Medical Supply Distributors:German and French laboratory distributors now demand full REACH material disclosure documentation as baseline tender qualifications.
- Online Retail:Entry-level and replacement unit procurement shifts toward digital channels.
- Laboratory Equipment Stores:Local service relationships persist for maintenance-dependent analog platforms.
Direct sales holds relationship density. Medical supply distributors are rotating up the share rankings through regulatory compliance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance requirements in United States pharmaceutical laboratories anchor the dominant geography, while brushless motor adoption and biopharma R&D spending concentrate procurement authority across Germany, China, and Switzerland.
United States
Integrated delivery networks and academic medical centers consolidate research infrastructure spending under centralized capital allocation committees. FDA 21 CFR Part 11 mandates accelerate digital vortex mixer displacement of analog units for GLP documentation. The Greater Boston and San Francisco Bay Area biotech clusters drive multi-tube configuration demand for CRISPR workflows.
Germany
Pharmaceutical quality control laboratories specify brushless motor platforms for validated dissolution testing protocols. REACH substance restrictions on rubber cup elastomers force material disclosure documentation for tender participation. The Rhine-Main and Baden-Württemberg industrial regions concentrate precision engineering heritage in laboratory equipment manufacturing.
China
Biological research institutes expand procurement to support high-throughput automation needs in genomics facilities. Dual carbon goals and extended producer responsibility frameworks recast motor efficiency standards for laboratory equipment portfolios. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters deepen clinical diagnostics infrastructure replacement cycles.
Switzerland
Pharmaceutical manufacturing quality control demands validated mixing protocols with full documentation trails. Swissmedic regulatory frameworks align with EU MDR validation timelines for clinical diagnostics integration. The Basel and Zurich metropolitan areas sustain premium positioning for precision-engineered laboratory instrumentation.
India
Contract research organization investment in analytical instrumentation expands with CDSCO regulatory harmonization and PLI scheme incentives. Budget-constrained academic laboratories retain analog units despite digital platform advantages. The Maharashtra and Karnataka biopharma corridors attract multinational laboratory equipment distributors establishing direct sales networks.
Vortex Mixer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the vortex mixer landscape. The vendor base fragments across precision engineering specialists, diversified life sciences conglomerates, and regional fabrication houses serving price-sensitive segments. Two strategic archetypes dominate: brushless motor technology leaders capturing pharmaceutical quality control accounts, and vertically integrated manufacturers controlling cost structures in entry-level markets. M&A activity concentrates among laboratory equipment distributors seeking direct manufacturer relationships, while capacity expansion focuses on multi-tube platform production for genomics workflow automation.
Within the precision engineering tier, IKA Works and Heidolph Instruments exemplify German heritage positioning in validated pharmaceutical applications. Scilogex anchors the cost-structured segment through captive supply of brushless motor components. Thermo Fisher Scientific occupies a position as the diversified conglomerate archetype with extensive institutional reach across North American and European direct sales networks.
| Leading Market Players |
|---|
| Scilogex |
| VELP Scientifica |
| Thermo Fisher Scientific |
| Heidolph Instruments |
| VWR International |
| Eppendorf |
| Biosan |
| IKA Works |
| Benchmark Scientific |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates supplier qualification for clinical diagnostics OEM partnerships while simultaneously stratifying price tiers across premium, standard, and economy levels. Buyers in pharmaceutical quality control laboratories accept substantial premiums for validated equipment with full documentation trails, whereas academic procurement committees prioritize unit economics over certification depth.
Pricing Analysis
United States pharmaceutical laboratories pay 40-60% premiums over Indian academic buyers for equivalent brushless motor platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-compliant digital units from analog alternatives, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier intensifies because Chinese manufacturers exploit captive motor production, though margins are tightening across mid-tier segments as consolidated purchasing through group procurement organizations concentrates buyer leverage.
Supply Chain Analysis
Inventory buffers for neodymium magnet assemblies stretch lead times to 12-16 weeks during supply disruptions. Brushless motor production draws from China, Germany, and Japan, with rare earth concentrate processing concentrated in Chinese refining facilities creating single-source vulnerability for permanent magnet supply. Distribution runs through direct manufacturer contracts with integrated delivery networks in North America and medical supply distributors in Europe bundling REACH compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement cycle compression in institutional laboratories signals cyclical recovery as biopharma R&D spending rebounds from prior-year capital constraints.
For Market Incumbents: Shield installed base relationships by embedding factory-trained biomedical technicians within high-volume pharmaceutical accounts, and deepen backward integration into brushless motor component supply to offset rare earth price volatility threatening margin structures. For New Entrants and Emerging Players: CDSCO regulatory harmonization fast-tracks market access for contract research organization supply in Maharashtra and Karnataka biopharma corridors, with white-space concentration in multi-tube platform demand from genomics automation workflows and cloud-connected diagnostics integration as the most penetrable angle. For Investors and Strategic Acquirers: EU MDR validation timeline extensions reshape the acquisition landscape by stranding non-compliant inventory and creating distressed asset opportunities; long-term viability centers on precision engineering specialists with validated pharmaceutical quality control positioning, with the signal to watch being brushless motor platform adoption rates in German dissolution testing laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Expansion | Eliminates quarterly maintenance intervals, reducing total cost of ownership for pharmaceutical procurement committees. |
| Cloud-Connected Diagnostics Integration | Creates recurring service revenue through IoT-enabled laboratory information management system connectivity. |
| REACH Compliance Documentation Bundling | Secures tender participation eligibility with German and French laboratory distributors demanding full material disclosure. |
| Biomedical Technician Certification Investment | Addresses aftermarket support capacity constraints constraining digital platform maintenance scalability. |
| Multi-Tube Configuration Scale-Up | Captures CRISPR workflow automation demand from biological research institutes in Greater Boston and San Francisco Bay Area clusters. |
Study Parameters
Operator-level perspectives from biomedical technicians, laboratory equipment procurement managers, pharmaceutical quality control directors, and clinical diagnostics OEM partnership leads anchored the qualitative base. Primary interview findings combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, ISO certification databases, and hospital procurement system records. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against end-user installation surveys.
Sensitivity analysis tested forecast robustness across brushless motor adoption scenarios and biopharma capital expenditure cycles. Segmentation dimensions modeled include product type, end user category, application workflow, and distribution channel structure across the projection horizon. CAGRs derived from instrument replacement cycle analysis, with genomics facility automation intensity and regulatory compliance mandate timing as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained biopharma R&D spending and stable rare earth magnet supply; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Pipette Controllers Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Neurostimulation Market
Medical Devices
Ultrasound Probe Market