
 AI Capsule Endoscopy Reading Platform Market | 2026-2036
AI Capsule Endoscopy Reading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
AI Capsule Endoscopy Reading Platform Market Insights
Israeli algorithm developers and South Korean device manufacturers is consolidating around hybrid hardware-software offerings for gastrointestinal diagnostics. Medtronic leverages its established capsule endoscopy installed base to distribute AI reading modules through existing hospital contracts. CapsoVision differentiates through proprietary 360-degree capsule imaging technology paired with automated lesion detection workflows. Jinshan Science & Technology anchors production cost advantages for capsule hardware destined for price-sensitive Asian healthcare systems.
An AI capsule endoscopy reading platform processes wireless capsule endoscope image streams using convolutional neural networks to detect bleeding, polyps, and mucosal lesions at frame rates exceeding two images per second with sensitivity thresholds comparable to specialist gastroenterologists. The platform's primary commercial purpose is reducing diagnostic reading time from approximately one hour to under ten minutes while standardizing detection accuracy across operator experience levels. Cloud-based platforms are capturing the fastest expansion as hospital IT departments prioritize interoperability with picture archiving systems and remote specialist consultation networks. Deep learning architectures dominate technology deployment, though pattern recognition modules retain relevance in resource-constrained settings where simplified algorithm footprints reduce computational requirements.
FDA premarket notification pathways for computer-aided detection devices and the EU Medical Device Regulation Class IIa classification requirements shape product development timelines and clinical validation obligations for platform developers. The European Medicines Agency coordinates with notified bodies on post-market surveillance protocols for AI diagnostic algorithms that continuously learn from new patient data. Stakeholders must monitor evolving reimbursement decisions from the Centers for Medicare and Medicaid Services regarding Category III CPT codes for AI-assisted endoscopy interpretation.
Market Dynamics
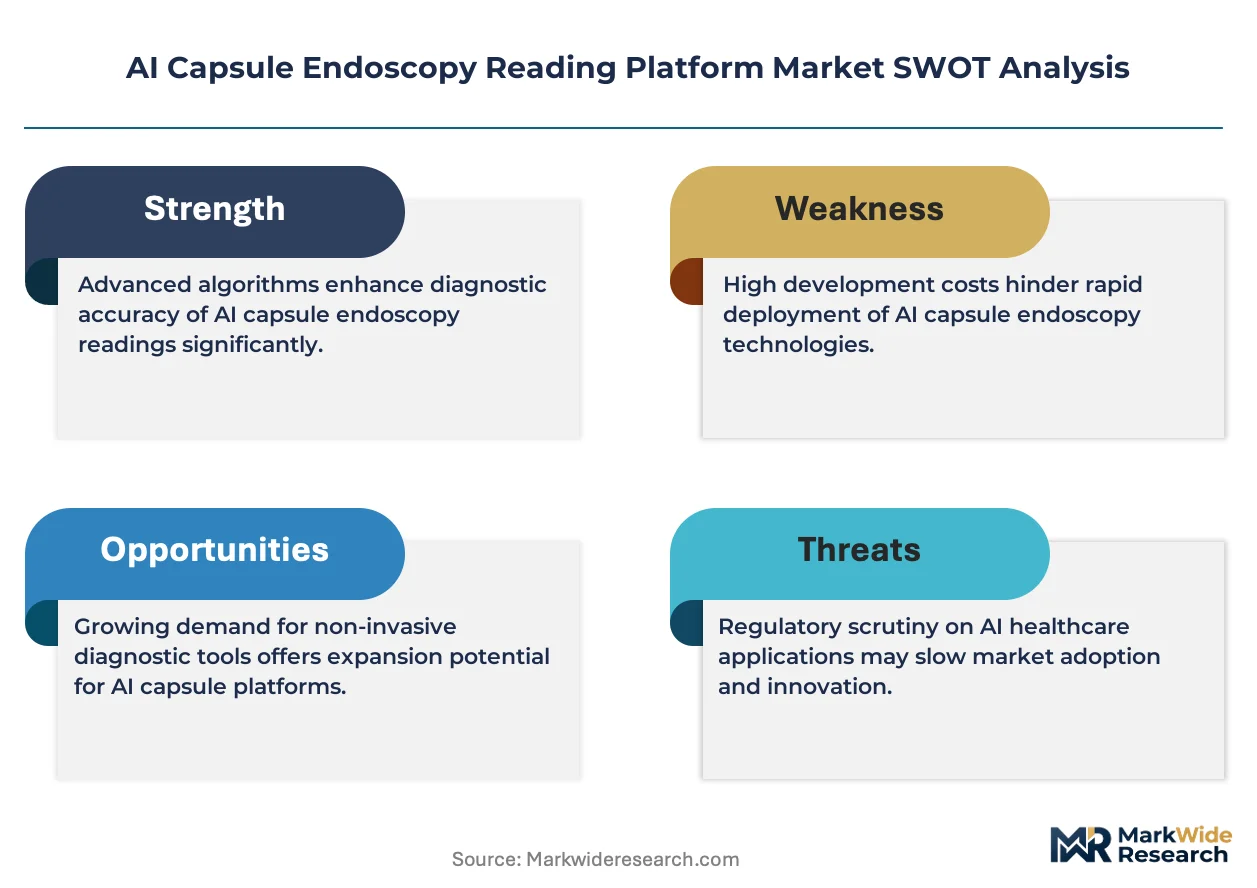
Cloud-native deployment architectures are compressing hospital procurement cycles for AI diagnostic platforms, as IT departments prioritize interoperability with existing picture archiving infrastructure over on-premise installation.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's premarket notification framework for computer-aided detection devices accelerates commercialization timelines for algorithm developers seeking US market entry.
- Small Bowel Imaging Reimbursement:Category III CPT codes for AI-assisted endoscopy interpretation create sustainable revenue streams for gastroenterology clinics adopting automated reading platforms.
- Convolutional Neural Network Maturation:Deep learning architectures processing capsule image streams at two-plus frames per second achieve sensitivity thresholds matching specialist gastroenterologists.
Market Restraints
- EU MDR Class IIa Compliance Costs:The European Medical Device Regulation imposes extensive clinical validation obligations and notified body review fees that strain mid-cap algorithm developers.
- Israeli Algorithm Supply Concentration:A disproportionate share of lesion detection software originates from Tel Aviv-area developers, creating geopolitical and single-source vulnerability risks.
- Legacy PACS Integration Friction:Hospital picture archiving systems running decade-old DICOM standards require expensive middleware bridges to receive AI platform outputs.
Strategic Opportunities
- Price-Sensitive Asian Healthcare Systems:Jinshan Science & Technology's production cost advantages position Chinese-manufactured capsule hardware for volume expansion across Southeast Asian public hospitals.
- 360-Degree Imaging Convergence:CapsoVision's proprietary omnidirectional capsule technology paired with automated detection workflows addresses blind spots in conventional forward-facing endoscopy.
- Remote Specialist Consultation Networks:Cloud-based platforms enable teleradiology partnerships between urban academic medical centers and rural diagnostic facilities lacking on-site gastroenterology coverage.
Industry Challenges
- Continuous Learning Algorithm Governance:Post-market surveillance protocols for AI diagnostic systems that autonomously update from new patient data remain undefined across FDA and EMA jurisdictions.
- Gastroenterologist Workflow Resistance:Tenured specialists in established academic medical centers exhibit adoption friction toward automated reading platforms perceived as devaluing clinical expertise.
- Computational Infrastructure Capex:Real-time lesion detection at required frame rates demands GPU clusters that exceed capital budgets of independent ambulatory surgery centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Capsule Endoscopy Reading Platform Market |
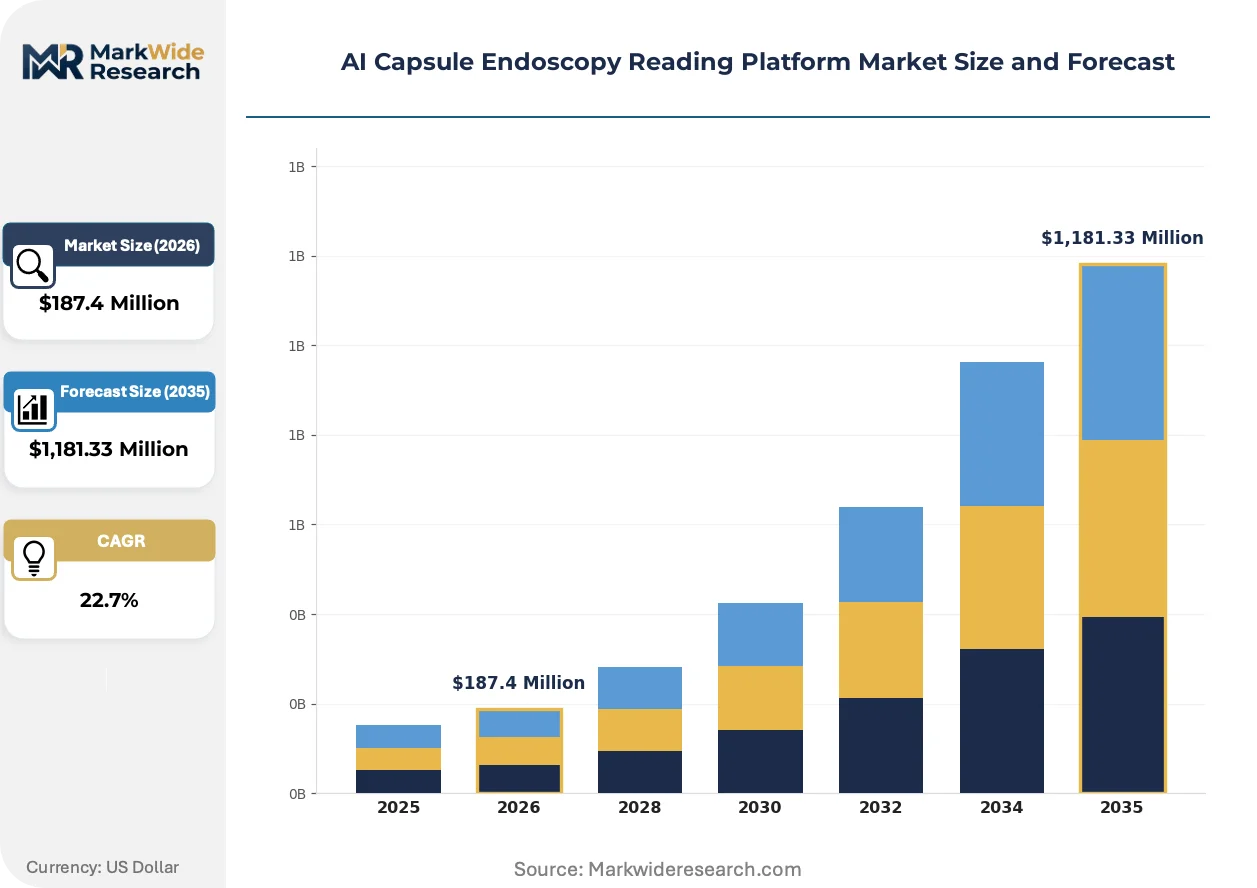
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Platform, Integrated System, On-Premise Solution Technology: Deep Learning, Machine Vision, Natural Language Processing, Pattern Recognition, Neural Networks Application: Gastrointestinal Bleeding Detection, Polyp Identification, Crohn’s Disease Monitoring, Ulcer Diagnosis, Tumor Localization End User: Medical Imaging Centers, Ambulatory Surgical Centers, Gastroenterology Clinics, Diagnostic Laboratories |
| Companies Covered | AnX Robotica, Medtronic, Olympus, CapsoVision, IntroMedic, Jinshan Science & Technology, DigestAID, RF System, Ankon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Capsule Endoscopy Reading Platform Market Trends and Innovations
Algorithm developers are pivoting from detection-only models toward integrated diagnostic workflows that embed clinical decision support directly into electronic health record systems.
Transformer-based architectures are expanding into capsule endoscopy image analysis, replacing convolutional neural networks for sequence modeling across thousands of frames per examination. Academic medical centers in Germany and Japan are piloting these models for polyp detection. The technology is expanding into cloud-native platforms that compress specialist review time from hours to minutes.
The EU AI Act's risk classification framework for medical device software imposes conformity assessment requirements on AI diagnostic algorithms that exceed traditional CE marking obligations. Developers must maintain technical documentation and quality management systems subject to notified body audit. High-risk system providers are responding by segregating European training datasets from other geographies to ensure regulatory compliance.
Hospital procurement departments are unbundling hardware and software purchasing decisions for capsule endoscopy systems. Large integrated delivery networks now negotiate AI reading platform licenses separately from capsule device contracts, displacing bundled vendor relationships. This pattern is most visible in United States multi-hospital systems where centralized IT governance overrides individual physician preferences.
AI Capsule Endoscopy Reading Platform Market Segmentation
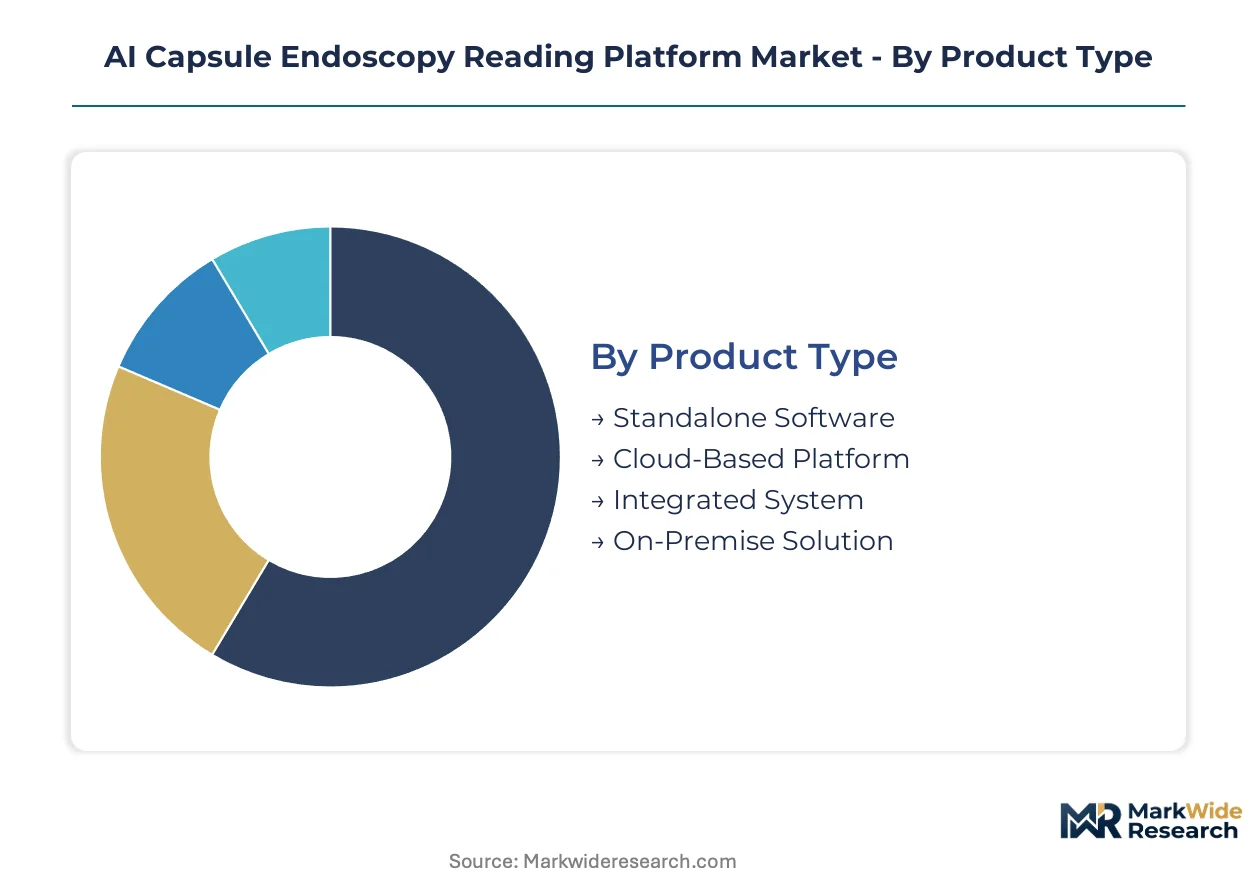
Platform architecture determines procurement complexity and integration burden for hospital IT departments. Deployment mode shapes total cost of ownership and regulatory compliance pathways. Understanding segment boundaries clarifies where algorithm developers compete on speed versus depth of clinical integration.
Product Type:
Standalone deployments operate outside existing PACS infrastructure, while embedded configurations demand deeper hospital system integration.
- Standalone Software:Modular applications process capsule image streams through discrete workstations without permanent EHR coupling. Gastroenterology clinics in Germany favor this architecture for pilot programs testing algorithm accuracy before enterprise commitment.
- Cloud-Based Platform:Browser-accessible systems leverage remote GPU clusters for real-time lesion detection at sub-ten-minute reading speeds. United States multi-hospital systems prioritize these for centralized IT governance and teleradiology partnerships.
- Integrated System:Hardware-software bundles from capsule manufacturers embed AI reading modules within proprietary capture devices. Medtronic distributes through existing hospital contracts, compressing procurement cycles.
- On-Premise Solution:Local server installations satisfy data residency requirements in Japanese healthcare systems where cloud transfer faces institutional resistance.
Volume placements concentrate in Cloud-Based Platform; the faster expansion belongs to Integrated System.
Technology:
Algorithm sophistication tiers separate resource-intensive deep learning from lightweight pattern recognition suitable for edge deployment.
- Deep Learning:Multi-layer convolutional neural networks process thousands of frames per examination with sensitivity matching specialist gastroenterologists. Academic medical centers in Japan pilot transformer architectures replacing CNNs for sequence modeling.
- Machine Vision:Traditional computer vision extracts geometric features from mucosal surfaces without training data intensity of neural approaches. Southeast Asian public hospitals deploy these where GPU infrastructure remains capital-constrained.
- Natural Language Processing:Automated report generation converts lesion coordinates into structured clinical narratives for EHR insertion.
- Pattern Recognition:Rule-based algorithms detect bleeding through color thresholding at computational footprints compatible with tablet-grade processors.
- Neural Networks:Shallow architectures balance detection accuracy against hardware requirements for ambulatory surgical center budgets.
Procurement volumes favor Deep Learning; Pattern Recognition climbs fastest in price-sensitive installations.
Application:
Clinical use case specificity determines algorithm training data requirements and regulatory validation scope.
- Gastrointestinal Bleeding Detection:Algorithms flag active hemorrhage and occult blood through colorimetric analysis of small bowel frames. United States reimbursement frameworks for Category III CPT codes concentrate demand here.
- Polyp Identification:Morphological classification distinguishes adenomatous from hyperplastic lesions for surveillance interval recommendations. German screening programs drive validation investments.
- Crohn's Disease Monitoring:Mucosal healing assessment algorithms quantify ulcer burden across longitudinal examinations.
- Ulcer Diagnosis:Deeper neural architectures differentiate peptic from inflammatory etiologies through vascular pattern recognition.
- Tumor Localization:Mass detection workflows prioritize sensitivity over specificity given oncologic stakes.
Placement volumes cluster in Gastrointestinal Bleeding Detection; Polyp Identification gains share fastest through screening program expansion.
End User:
Site-of-care economics shape acceptable price points and workflow integration depth.
- Medical Imaging Centers:High-volume teleradiology operations amortize platform costs across multiple referring hospital systems. United States metropolitan clusters concentrate this segment.
- Ambulatory Surgical Centers:Limited capital budgets favor lightweight software configurations with minimal IT infrastructure requirements.
- Gastroenterology Clinics:Specialist-owned practices prioritize reading speed improvements that expand daily examination throughput without additional physician hires.
- Diagnostic Laboratories:Pathology-integrated operations seek lesion detection outputs that streamline histological correlation workflows.
Adoption concentrates in Gastroenterology Clinics; Medical Imaging Centers expand most quickly through consolidation of regional reading services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tel Aviv anchors algorithm development density for lesion detection software, while Seoul concentrates capsule hardware manufacturing and Osaka hosts transformer architecture pilot programs. These three localities generate disproportionate intellectual property and production capacity for gastrointestinal AI diagnostics.
United States
Gastroenterology clinics in metropolitan clusters expand automated reading platform procurement to manage rising small bowel examination volumes. FDA 510(k) premarket notification pathways accelerate commercialization timelines for algorithm developers seeking market entry. Boston-area academic medical centers pilot integrated diagnostic workflows embedding clinical decision support into electronic health record systems.
Germany
Screening program expansion drives validation investments for polyp identification algorithms across statutory health insurance networks. EU Medical Device Regulation Class IIa classification requirements impose clinical validation obligations that strain mid-cap developers. Munich and Heidelberg host notified body coordination with the European Medicines Agency on post-market surveillance protocols.
Japan
Data residency requirements in hospital systems sustain demand for on-premise solution architectures resistant to cloud transfer. PMDA consultation pathways shape product development timelines for domestic algorithm developers. Tokyo and Osaka academic medical centers pilot transformer-based architectures replacing convolutional neural networks for sequence modeling across thousands of frames per examination.
China
Price-sensitive public healthcare systems in Southeast Asian export markets absorb Jinshan Science & Technology's production cost advantages for capsule hardware. NMPA medical device registration requirements govern software-as-a-medical-device classification for cloud-native platforms. Yangtze River Delta manufacturing clusters concentrate hardware assembly for regional distribution.
South Korea
Device manufacturers consolidate around hybrid hardware-software offerings for gastrointestinal diagnostics targeting domestic and export markets. MFDS regulatory pathways align with international standards to facilitate cross-border commercialization. Seoul metropolitan area production facilities supply capsule endoscopy systems to Asian healthcare systems prioritizing integrated system procurement.
AI Capsule Endoscopy Reading Platform Market Competitive Landscape
Global majors compete with regional champions across hardware-software integration depth, creating a tiered structure where bundled vendors face unbundling pressure from specialized algorithm developers. The vendor base separates into three strategic archetypes: established endoscopy device manufacturers extending into AI modules, pure-play algorithm developers licensing detection software, and hybrid hardware-software integrators from East Asian manufacturing clusters. Dominant competitive moves include strategic partnerships between capsule manufacturers and AI developers, plus geographic expansion through teleradiology network partnerships.
Among established medical device multinationals, Medtronic leverages its installed base to distribute reading modules through existing hospital contracts, exemplifying the hardware-anchored archetype. CapsoVision occupies a position within the technology-differentiated tier through proprietary imaging configurations paired with automated workflows. Jinshan Science & Technology anchors the cost-optimized manufacturing archetype, representing production advantages for price-sensitive healthcare system procurement.
| Leading Market Players |
|---|
| AnX Robotica |
| Medtronic |
| Olympus |
| CapsoVision |
| IntroMedic |
| Jinshan Science & Technology |
| DigestAID |
| RF System |
| Ankon Technologies |
| Others |
Pricing and Supply Chain Analysis
GPU memory module spot prices cascade through AI capsule endoscopy platform manufacturing, compressing margins for deep learning hardware configurations while amplifying cost advantages for pattern recognition software tiers targeting Southeast Asian public hospitals.
Pricing Analysis
Service bundling separates premium cloud-native deployments with continuous algorithm updates from unbundled on-premise licenses requiring separate maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, CE marking tier, and after-sales technical support depth. Pricing pressure stems from Jinshan Science & Technology's hardware cost leadership forcing margin compression in integrated system bundles. Ambulatory surgical centers exhibit highest price sensitivity due to capital budget constraints, while United States multi-hospital systems absorb premium tiers for centralized IT governance.
Supply Chain Analysis
Specialized machine learning engineer availability in Tel Aviv, Seoul, and Shenzhen constrains algorithm development capacity for lesion detection software pipelines. Hardware assembly draws from Yangtze River Delta manufacturing clusters for capsule device components and South Korean sensor foundries for CMOS imaging modules. Single-source vulnerability concentrates in Israeli algorithm development houses supplying detection software to multiple device manufacturers. Distribution runs through hospital procurement departments unbundling hardware and software purchasing decisions, displacing traditional bundled vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cluster infrastructure scarcity props pricing power for cloud-native platform providers, creating supply-constrained conditions favoring incumbents with established remote computing capacity.
For Market Incumbents: Hedge against algorithm commoditization by deepening integration into electronic health record systems through clinical decision support modules. Defensive consolidation should prioritize FDA 510(k) clearance expansion into polyp identification to offset bleeding detection margin pressure from pure-play software entrants. Capacity addition in Japanese on-premise architectures addresses data residency requirements resistant to cloud migration. For New Entrants and Emerging Players: Launch via teleradiology network partnerships connecting urban academic medical centers with rural diagnostic facilities lacking on-site gastroenterology coverage. White-space targets include Southeast Asian public hospitals prioritizing pattern recognition software for tablet-grade processor compatibility, and German screening program expansion driving polyp identification algorithm demand. Go-to-market positioning should emphasize computational footprint reduction for resource-constrained settings. For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid hardware-software integrators with established MFDS regulatory pathways facilitating cross-border commercialization into Asian healthcare systems. Long-term viability over the extended projection horizon hinges on continuous learning algorithm governance frameworks resolving FDA and EMA post-market surveillance ambiguities. Monitor EMA notified body audit backlogs as inflection indicator for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Clears algorithm variants for polyp identification beyond bleeding detection, unlocking Category III CPT code reimbursement. |
| CE Marking Under EU MDR Class IIa | Satisfies notified body clinical validation obligations for European commercialization of transformer-based architectures. |
| Hospital System Partnership | Secures centralized IT procurement contracts within United States multi-hospital networks prioritizing interoperability. |
| Software Companion Development | Embeds automated lesion detection into CapsoVision's proprietary 360-degree imaging workflows for blind spot elimination. |
| Reimbursement Strategy | Positions cloud-based platforms for CMS Category III CPT code coverage decisions on AI-assisted endoscopy interpretation. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR notified body technical documentation, and PMDA consultation pathway records, complemented by interviews with gastroenterology clinic directors, hospital IT procurement officers, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement registries, and medical device trade flow data. Bottom-up capsule hardware shipment estimates triangulated against top-down algorithm licensing revenue aggregates.
Segment-level outputs across the analysis window reflect deployment mode, technology architecture, clinical application specificity, and end-user site-of-care economics. CAGRs derived from logistic diffusion curves modeling AI diagnostic adoption against specialist gastroenterologist workforce constraints. Transformer architecture pilot program data from Osaka and Heidelberg academic medical centers informed technology transition assumptions.
Regulatory clearance delays, reimbursement framework modifications, and continuous learning algorithm governance ambiguities are the dominant revision risks to modeled adoption trajectories. Forecasts reflect documented assumptions regarding FDA 510(k) pathway velocity and EU MDR notified body capacity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market
Medical Imaging
Carotid Ultrasound Imaging Market