
 Global Abutment Implants Market | 2026-2036
Global Abutment Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Abutment Implants Market Foresight
Digital CAD/CAM milling is rewriting abutment production workflows, collapsing turnaround times from weeks to same-day chairside delivery. Straumann leverages its proprietary intraoral scanning ecosystem to lock in restorative workflow control across premium dental clinics. Nobel Biocare anchors its position through deep backward integration into titanium blank manufacturing, ensuring supply security for high-precision custom abutments. ZimVie competes aggressively on price in the screw-retained segment, targeting mid-tier oral surgery centers with standardized platform solutions.
An abutment implant is a prosthetic connector that attaches to an endosseous implant fixture, typically machined from grade 5 titanium or yttria-stabilized tetragonal zirconia polycrystal, to support a final dental restoration while transferring occlusal loads to the underlying bone structure. Titanium abutments dominate current volume due to proven osseointegration performance and machinability, though zirconia variants command premium positioning in anterior aesthetic zones where soft tissue translucency matters. Screw-retained connections lead in full-arch restoration applications where retrievability protects against peri-implant complications, while cement-retained designs persist in single-tooth replacement where emergence profile customization drives prosthodontist preference.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape market access timelines, with notified bodies demanding extensive biocompatibility testing under ISO 10993 protocols for novel surface treatments. Japan's PMDA maintains distinct standards for immediate-loading claims, forcing manufacturers to run separate clinical validation cohorts for that indication. Stakeholders must monitor how FDA draft guidance on patient-matched guides affects regulatory boundaries between standard and custom abutment classifications, as this distinction determines whether digital workflows qualify for streamlined premarket notification or require full PMA submission.
Market Dynamics
Digital CAD/CAM workflows are compressing production cycles from weeks to hours, forcing manufacturers to reconfigure supply chains around chairside delivery capabilities or risk displacement by vertically integrated dental technology platforms.
Growth Catalysts
- Immediate-loading protocol expansion:German and South Korean dental clinics are accelerating same-day restoration adoption, driving demand for high-torque abutment designs validated under accelerated osseointegration protocols.
- EU MDR biocompatibility enforcement:CE marking requirements under ISO 10993 protocols are filtering out non-compliant suppliers, creating concentration benefits for certified titanium blank manufacturers.
- Aging metropolitan corridors:Japan's Tokyo-Osaka corridor and Brazil's São Paulo private surgery networks are generating concentrated demand for aesthetic zirconia abutments in anterior zones.
Market Restraints
- Grade 5 titanium supply concentration:Aerospace and medical device competition for titanium sponge is squeezing raw material availability, with spot pricing volatility transmitted to abutment blank producers.
- PMDA separate-cohort requirements:Japan's distinct immediate-loading validation standards force redundant clinical trials, extending time-to-market by 18-24 months for novel surface treatments.
- Cement-retained complication liability:Peri-implantitis risks from residual cement are driving prosthodontists toward screw-retained alternatives, compressing margins on legacy cement-retained inventory.
Strategic Opportunities
- Brazil's private dental networks:Underpenetrated mid-tier oral surgery centers outside São Paulo offer volume expansion for standardized platform solutions with localized technical support.
- FDA patient-matched guide boundaries:Draft guidance on custom versus standard abutment classifications creates regulatory arbitrage potential for digital workflows qualifying for streamlined 510(k) pathways.
- Intraoral scanner-abutment convergence:Chairside milling systems paired with proprietary scan bodies enable same-day restorative workflows, capturing premium pricing in high-throughput metropolitan clinics.
Industry Challenges
- CAD/CAM technician scarcity:Dental laboratory consolidation is shrinking the pool of technicians capable of complex emergence profile customization, creating bottlenecks for aesthetic zone cases.
- EU MDR technical documentation burden:Notified body backlogs and expanded clinical evidence requirements are delaying CE mark renewals, freezing product line extensions for mid-cap manufacturers.
- Legacy ERP integration friction:Dental clinics adopting chairside milling face workflow disruption from incompatible practice management systems, slowing technology adoption curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Abutment Implants Market |
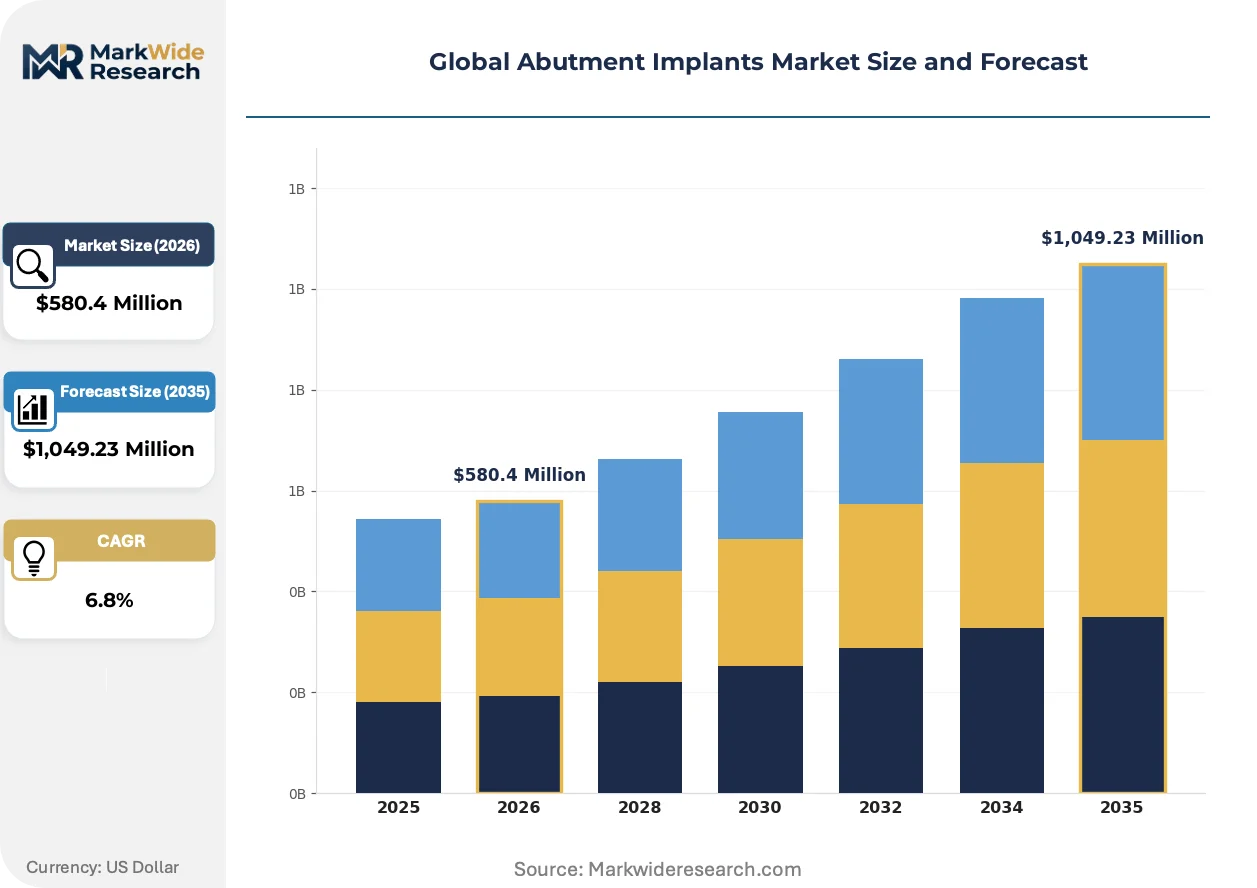
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $1,049.23 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium, Zirconia, Hybrid, Ceramic, Polymer Connection Type: Screw-Retained, Cement-Retained, Morse Taper, External Hexagon Application: Single Tooth Replacement, Full Arch Restoration, Immediate Loading, Orthodontic Anchorage End User: Dental Clinics, Oral Surgery Centers, Prosthodontists, Dental Laboratories |
| Companies Covered | Straumann, Nobel Biocare, Dentsply Sirona, Zimmer Biomet, ZimVie, Osstem Implant, BioHorizons, Zest Dental Solutions, Envista Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Abutment Implants Market Shifts & Advancements
Workflow digitization is collapsing traditional boundaries between implant placement and final restoration, with real-time manufacturing capabilities reshaping competitive positioning across the value chain.
Monolithic zirconia abutments are migrating from laboratory-milled batch production to chairside same-day delivery in premium dental clinics equipped with intraoral scanning and five-axis milling units. Prosthodontists in Japan's major metropolitan centers are adopting these workflows fastest, compressing patient chair time from three appointments to single-visit protocols. This migration from centralized production to distributed manufacturing is eroding traditional dental laboratory intermediaries and capturing margin previously allocated to outsourcing.
FDA draft guidance on patient-matched surgical guides is tightening boundaries between standard and custom abutment regulatory classifications, with 510(k) pathway eligibility hinging on geometric parameter constraints. Manufacturers must now pre-submission to determine whether digital design workflows qualify for streamlined notification or trigger full PMA requirements. High-precision custom abutment producers with established quality management systems are responding by bifurcating product portfolios into regulatory-grade and patient-matched categories.
Consolidated buying by multi-location dental service organizations is displacing individual practice procurement, with centralized implant committees standardizing abutment platform selections across clinic networks. Straumann and Nobel Biocare are capturing these accounts through exclusive supply agreements bundling hardware, software, and consumables. This concentration is most visible in Germany's corporatized dental clinic chains, where procurement standardization is locking out smaller platform competitors.
Global Abutment Implants Market Segmentation
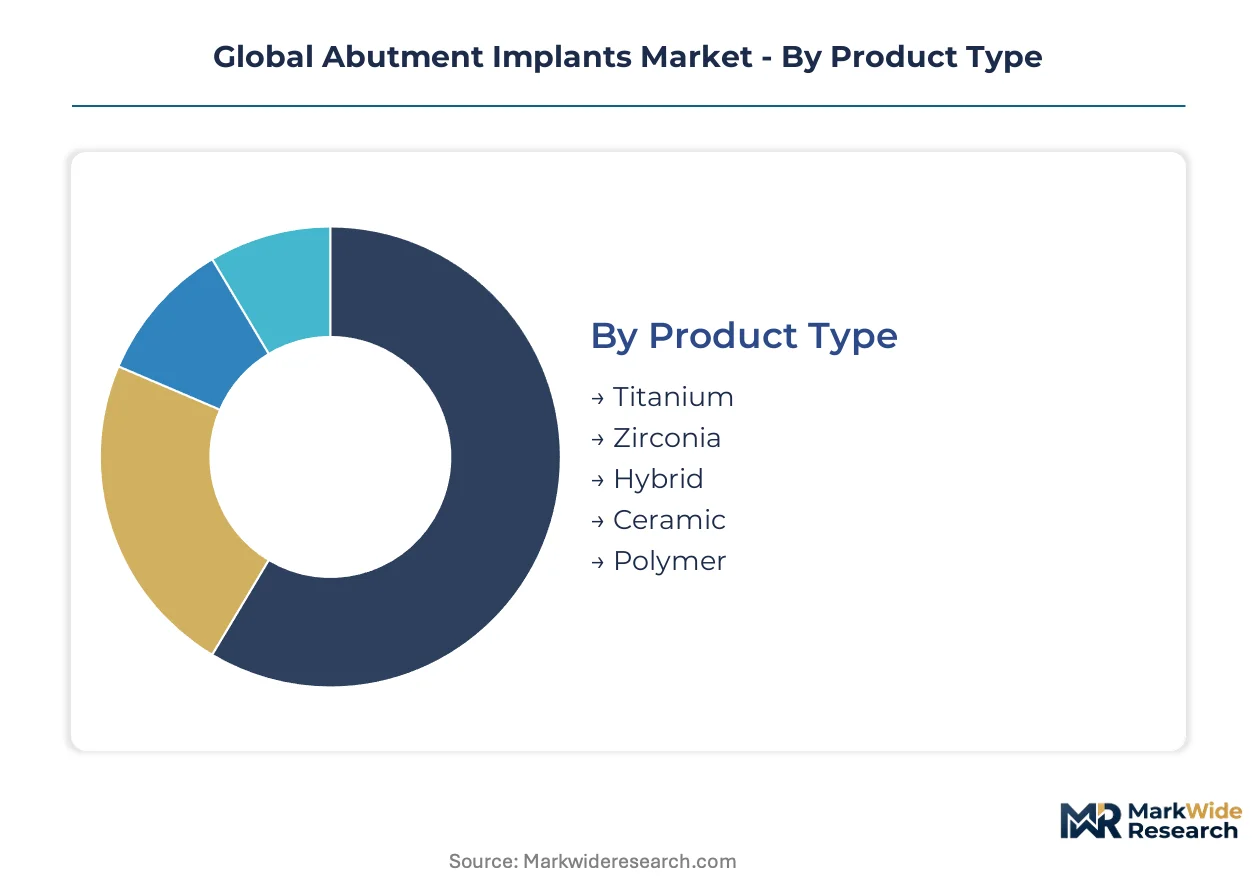
Abutment implant segmentation reveals divergent service intensity requirements across material grades and connection geometries. Titanium platforms demand extensive technical support for torque protocol training, while zirconia workflows require intensive chairside customization assistance. Understanding these support burdens clarifies where manufacturers must build field engineering capacity versus standardized distribution.
Product Type:
After-sales service intensity escalates with material brittleness and customization complexity, driving divergent field support models across the product spectrum.
- Titanium:Grade 5 titanium alloy dominates current surgical volumes due to proven osseointegration kinetics and machinability across five-axis milling platforms. German dental clinics and São Paulo private surgery networks concentrate demand for high-torque immediate-loading variants validated under accelerated protocols. By volume, titanium leads. By growth pace, zirconia is ahead.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal commands premium positioning in anterior aesthetic zones where soft tissue translucency determines prosthodontist selection. Japan's Tokyo-Osaka metropolitan corridor generates concentrated demand for monolithic chairside-milled solutions with same-day delivery capability.
- Hybrid:Titanium base-zirconia superstructure combinations balance retrievability with aesthetic performance in high-visibility restoration cases.
- Ceramic:Alumina-based alternatives serve niche allergic-sensitivity protocols requiring metal-free prosthetic architectures.
- Polymer:Polyetheretherketone and polymethyl methacrylate variants occupy temporary and provisional restoration applications with lower mechanical load requirements.
Service engineering teams allocate disproportionate training resources to zirconia emergence profile customization, while titanium platforms leverage standardized torque protocols that scale efficiently.
Connection Type:
Margin structures compress toward standardized platform geometries as procurement committees consolidate multi-location clinic networks around interoperable inventory.
- Screw-Retained:Internal hexagon and conical connection designs enable prosthetic retrievability that protects against peri-implantitis complications in full-arch reconstructions. South Korean dental clinics are accelerating adoption of same-day screw-retained protocols with immediate-loading validation.
- Cement-Retained:Customizable emergence profiles retain prosthodontist preference for single-tooth anterior replacements despite residual cement complication risks.
- Morse Taper:Cold-weld friction-fit connections distribute occlusal loads through mechanical interlocking rather than screw preload alone.
- External Hexagon:Legacy platform geometry persists in value-tier inventory systems where backward compatibility constrains upgrade pathways.
Procurement concentration favors screw-retained standardization, while cement-retained maintains position in boutique aesthetic practices.
Application:
Clinical validation requirements fragment by loading protocol, with immediate-loading claims demanding separate regulatory cohorts that extend time-to-market.
- Single Tooth Replacement:Emergence profile customization drives prosthodontist preference for cement-retained or custom-milled screw-retained solutions in anterior zones. Brazil's private dental surgery networks outside São Paulo show underpenetrated mid-tier expansion potential for standardized platform solutions.
- Full Arch Restoration:All-on-four and all-on-six protocols require high-torque abutment designs with validated fatigue resistance under immediate-loading conditions.
- Immediate Loading:Accelerated osseointegration protocols compress treatment timelines from months to hours, demanding surface treatment biocompatibility documentation under ISO 10993 and PMDA distinct standards.
- Orthodontic Anchorage:Temporary anchorage device applications utilize mini-implant abutments for skeletal anchorage in orthodontic tooth movement.
Volume concentration sits with single-tooth protocols, while full-arch restoration climbs fastest on immediate-loading protocol expansion.
End User:
Workflow digitization is collapsing traditional boundaries between implant placement and final restoration, reshaping channel economics across the value chain.
- Dental Clinics:Chairside milling adoption in premium metropolitan practices is capturing margin previously allocated to dental laboratory intermediaries. Japan's major urban centers lead this migration toward distributed manufacturing.
- Oral Surgery Centers:Mid-tier facilities concentrate demand for standardized screw-retained platforms with localized technical support and volume pricing.
- Prosthodontists:Aesthetic zone specialization drives demand for zirconia custom abutments with complex emergence profile requirements.
- Dental Laboratories:Centralized production faces erosion as intraoral scanner-abutment convergence enables same-day chairside delivery.
Channel power is shifting toward corporatized clinic networks with centralized procurement committees, displacing individual practice purchasing autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German abutment exports supply immediate-loading protocols across South Korean and Japanese dental networks, while Brazilian manufacturers feed Latin American private surgery demand.
Germany
Corporatized dental clinic chains in Berlin and Munich concentrate procurement power through centralized implant committees. KBA medical device traceability requirements enforce titanium blank documentation across the supply chain. The Stuttgart-Rhine-Neckar metropolitan region hosts precision milling operations serving same-day restoration workflows.
Japan
Aging demographics in the Tokyo-Osaka corridor drive aesthetic zirconia demand for anterior zone replacements. PMDA maintains distinct validation standards for immediate-loading claims, forcing separate clinical cohorts. Nagoya's dental technology cluster advances chairside monolithic zirconia milling for single-visit protocols.
South Korea
Seoul Capital Area clinics accelerate screw-retained full-arch adoption with validated high-torque designs. MFDS biocompatibility enforcement under ISO 10993 protocols filters supplier qualification. Busan-Ulsan manufacturing bases export precision titanium blanks to regional dental networks.
Brazil
São Paulo private surgery networks generate concentrated demand for standardized platform solutions with localized support. ANVISA medical device registration timelines extend market access for novel surface treatments. Mid-tier oral surgery centers outside São Paulo remain underpenetrated for screw-retained inventory systems.
United States
Multi-location dental service organizations consolidate buying power across metropolitan corridor networks. FDA draft guidance on patient-matched guide classifications shapes 510(k) pathway eligibility for digital workflows. Greater Boston and Pacific Northwest technology clusters advance intraoral scanner-abutment convergence for chairside delivery.
Global Abutment Implants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: premium platform integrators with proprietary scanning ecosystems, mid-tier standardized solution providers, and regional fabrication specialists. M&A activity concentrates among multi-location dental service organization suppliers, while technology licensing agreements proliferate around chairside milling software.
Among Swiss-based platform integrators, Straumann and Nobel Biocare occupy positions controlling restorative workflow ecosystems through bundled hardware-software-consumable offerings. ZimVie exemplifies the mid-tier standardized solution archetype targeting price-sensitive oral surgery centers with screw-retained inventory platforms. These three companies represent divergent competitive vectors: ecosystem lock-in versus supply security versus aggressive price positioning.
| Leading Market Players |
|---|
| Straumann |
| Nobel Biocare |
| Dentsply Sirona |
| Zimmer Biomet |
| ZimVie |
| Osstem Implant |
| BioHorizons |
| Zest Dental Solutions |
| Envista Holdings Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in South Korean titanium blank milling is compressing supplier margins and forcing tier-two producers toward aggressive spot-market pricing to maintain utilization rates, while premium German manufacturers defend position through certified immediate-loading protocols that command sustained premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects generational technology gaps: next-generation chairside-milled zirconia commands premium positioning, current-generation titanium platforms occupy standard tiers, and legacy external-hexagon inventory faces economy pricing. Price differentiation hinges on ISO 10993 biocompatibility certification tier and volume scale through dental service organization contracts. Pricing pressure stems from ZimVie's aggressive screw-retained positioning in mid-tier oral surgery centers. Mid-tier procurement committees exhibit highest price sensitivity; premium metropolitan prosthodontists demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with Busan-Ulsan precision mills, Stuttgart-Rhine-Neckar five-axis specialists, and Nagoya ceramic fabrication clusters. Geographic supply concentration centers on South Korea, Germany, and Japan for high-torque titanium blanks; Brazil and China feed standardized platform inventory. Raw material dependencies include grade 5 titanium sponge, yttria-stabilized zirconia powder, and PEEK polymer feedstock. Single-source vulnerability in aerospace-competitive titanium sponge creates procurement risk. Distribution runs through corporatized dental clinic networks with centralized procurement committees displacing traditional laboratory intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from torque protocol training and emergence profile customization is expanding faster than hardware sales, creating durable recurring income streams for manufacturers who embed field engineering capacity into clinic workflows.
For Market Incumbents: Harden supply security through backward integration into titanium blank manufacturing or exclusive long-term offtake agreements with Busan-Ulsan mills. Deepen regulatory moats by pre-positioning quality management systems for FDA patient-matched guide boundary shifts that could reclassify digital workflows toward PMA pathways. Channel control through proprietary intraoral scanning ecosystems locks in restorative workflow capture against emerging platform competitors. For New Entrants and Emerging Players: Mid-tier oral surgery centers in Brazil's Belo Horizonte and Porto Alegre corridors represent the most penetrable entry point, with underpenetrated screw-retained inventory systems and localized technical support gaps. Immediate-loading validation services for PMDA distinct cohorts offer regulatory arbitrage potential. Go-to-market angle: partner with regional dental service organizations seeking second-source platform alternatives to Straumann-Nobel duopoly. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chairside milling software and five-axis precision fabrication assets. Long-term viability favors acquisition targets with established ISO 10993 notified body relationships and demonstrated immediate-loading clinical validation. Signal to watch: FDA final guidance on patient-matched guide classifications that determines whether digital abutment workflows qualify for streamlined 510(k) or trigger full PMA submission requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | EU MDR technical documentation investments filter out mid-cap competitors, concentrating market access among certified titanium blank manufacturers. |
| Hospital System Partnership | Multi-location dental service organization exclusive supply agreements bundle hardware, software, and consumables to lock out platform competitors. |
| Software Companion Development | Proprietary intraoral scanner-abutment convergence enables same-day chairside delivery workflows that capture margin from laboratory intermediaries. |
| FDA Submission Strategy | Pre-submission determinations on patient-matched guide classifications clarify whether digital workflows qualify for streamlined 510(k) or require PMA. |
| Reimbursement Strategy | Immediate-loading protocol coverage expansion in Japan's metropolitan corridors accelerates adoption of high-torque abutment designs. |
Research Methodology
Initial hypotheses were tested against primary input from prosthodontists, dental clinic procurement directors, biomedical engineers at precision milling operations, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, PMDA submission records, and hospital procurement databases. Bottom-up volume modeling across material grades and connection geometries triangulated with top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning material type, connection geometry, loading protocol, and end-user channel. CAGRs were derived from regression analysis against aging demographic trajectories and immediate-loading protocol adoption curves. Industry-specific forecast inputs included ISO 10993 biocompatibility certification timelines and PMDA separate-cohort validation requirements.
Practitioners should monitor FDA final guidance on patient-matched guide classifications, EU MDR notified body backlog resolution, and titanium sponge spot pricing volatility for early signals of forecast revision. Quarterly review of immediate-loading protocol reimbursement decisions and dental service organization procurement standardization trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Cervical Fusion Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Phlebotomy Equipments Market