
 Neurotechnology Market | 2026-2036
Neurotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Neurotechnology Market Outlook
Hospital procurement groups is rotating toward brain-computer interface platforms as payer coverage for neuromodulation broadens. Neuralink sustains R&D intensity through in-house electrode fabrication and surgical robotics integration. Synchron competes via its endovascular implant approach that avoids open craniotomy. INBRAIN Neuroelectronics leverages graphene-based electrode arrays to differentiate on signal resolution and biocompatibility.
Neurotechnology encompasses devices and systems that interface directly with the nervous system through electrical, magnetic, or chemical signaling, typically operating at microvolt to millivolt sensitivity ranges with electrode impedances below 100 kΩ for chronic implants. Its primary commercial purpose is to restore, modulate, or augment neural function in therapeutic and diagnostic contexts. Neurostimulation devices occupy the largest revenue pool given established reimbursement for chronic pain and movement disorders, while brain-computer interfaces represent the fastest-expanding segment as regulatory pathways for severe paralysis indications mature. Electrode systems concentrate margin capture among materials specialists controlling thin-film manufacturing and biocompatible coating processes.
FDA breakthrough device designation and EU MDR conformity assessment shape competitive timelines by accelerating review for novel neuromodulation platforms while demanding extensive clinical evidence for implantable systems. Japan's PMDA Sakigake framework offers priority review for neurotechnology with no domestic precedent, redirecting early commercialization strategies toward Tokyo and Osaka hospital networks. Stakeholders must monitor reimbursement coding decisions by CMS and analogous bodies in Germany and Japan, as these determine whether hospital budgets absorb next-generation systems or defer procurement until cost-effectiveness data matures.
Market Dynamics
Hospital procurement groups are rotating toward brain-computer interface platforms as payer coverage for neuromodulation broadens, compressing traditional device sales cycles and forcing electrode manufacturers to reconfigure commercial teams around value-based contracting.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for novel neuromodulation platforms compress product development cycles, enabling faster clinical validation for severe paralysis indications.
- Graphene-based electrode arrays:Advanced materials achieving signal resolution improvements are displacing traditional silicon substrates in chronic implant applications.
- Japan's PMDA Sakigake framework:Priority review pathways for neurotechnology with no domestic precedent redirect early commercialization strategies toward Tokyo and Osaka hospital networks.
Market Restraints
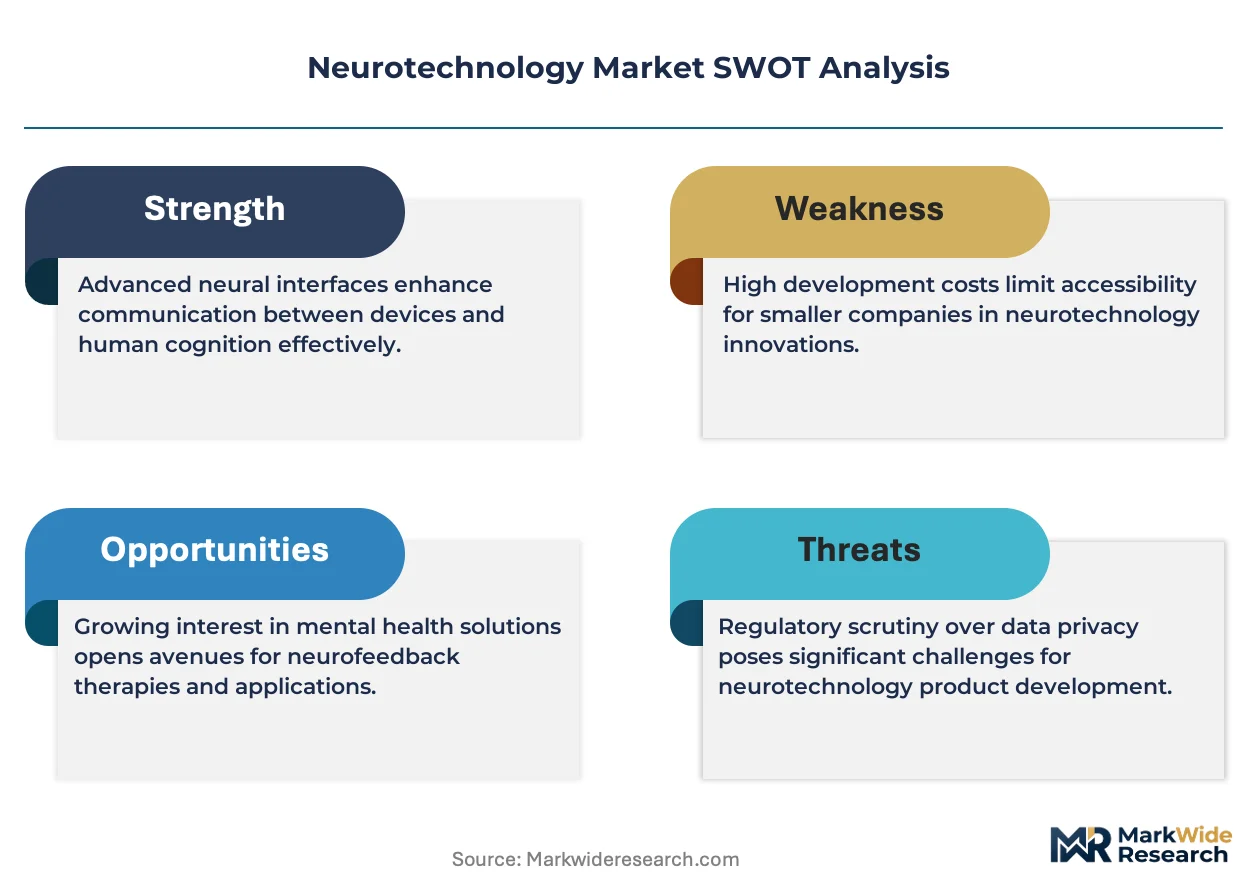
- Platinum-iridium supply concentration:Electrode material sourcing depends on limited refining capacity in South Africa and Russia, creating input cost volatility for implantable device manufacturers.
- EU MDR clinical evidence requirements:Extensive post-market surveillance mandates for implantable systems extend conformity assessment timelines and strain smaller manufacturers' regulatory budgets.
- Non-invasive neuromodulation alternatives:Transcranial magnetic stimulation and focused ultrasound systems threaten market share for surgical implant categories in chronic pain management.
Strategic Opportunities
- Underpenetrated German outpatient neuromodulation:Ambulatory surgical centers in Bavaria and North Rhine-Westphalia lack dedicated reimbursement codes for next-generation spinal cord stimulation systems.
- Closed-loop adaptive algorithms:Convergence of machine learning with real-time neural signal processing enables personalized stimulation parameter adjustment without clinician intervention.
- CMS transitional pass-through payments:Temporary reimbursement enhancement for breakthrough devices creates a 24-36 month window for hospital budget capture before standard coding assignment.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing for novel polymer coatings requires 18-24 month validation cycles that misalign with venture capital funding horizons.
- Neural signal processing talent scarcity:Device manufacturers compete with technology firms for engineers with expertise in real-time embedded systems and electrophysiology.
- Legacy hospital IT integration:Brain-computer interface data streams require HL7 FHIR compatibility upgrades that strain biomedical engineering departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurotechnology Market |
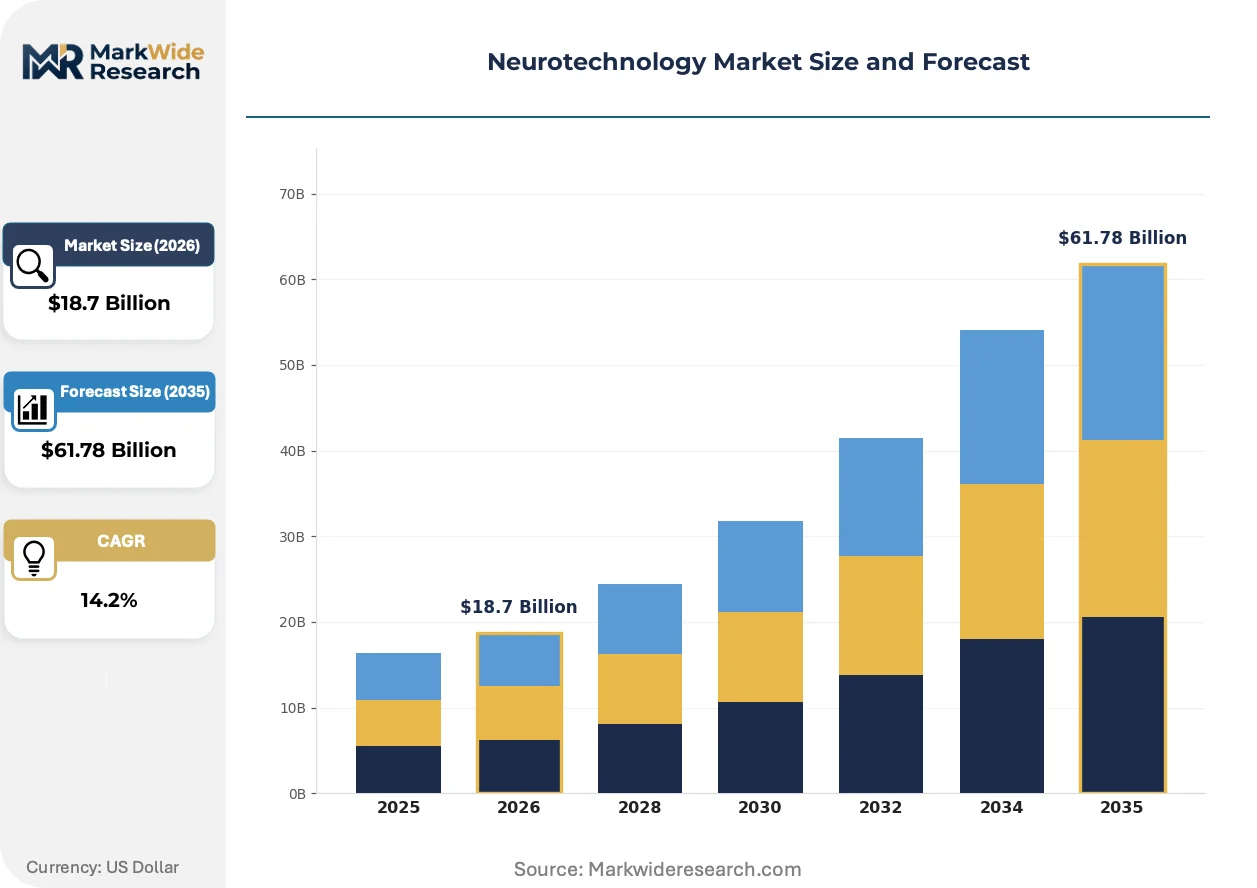
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuroprosthetics, Neurostimulation Devices, Brain-Computer Interfaces, Electrode Systems Therapy Area: Chronic Pain, Neurological Disorders, Rehabilitation, Cognitive Enhancement End User: Clinics, Research Institutions, Hospitals, Home Care Technology: Transcranial Magnetic Stimulation, Deep Brain Stimulation, Functional Electrical Stimulation, Electrophysiology |
| Companies Covered | Synchron, INBRAIN Neuroelectronics, Neuralink, Ceribell, Insightec, Science Corporation, Neurable, Neuromod Devices, Paradromics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurotechnology Market Strategic Shifts
Electrode miniaturization and biocompatible coating advances are compressing form factors while extending device longevity, fundamentally altering competitive positioning among materials specialists and surgical robotics integrators.
Graphene-based neural interfaces are displacing conventional metal electrode arrays in chronic implant applications. Academic medical centers in the United States and Germany are piloting these systems for epilepsy monitoring and movement disorder therapy. The shift is forcing traditional electrode manufacturers to accelerate thin-film process development or cede high-margin chronic implant segments to materials science entrants.
The EU MDR's reinforced clinical evidence requirements for active implantable devices are extending conformity assessment timelines by 12-18 months for novel neuromodulation platforms. Manufacturers are responding by front-loading pivotal trials and establishing European authorized representative structures earlier in development. Japan's PMDA has reciprocally tightened equivalence pathways, affecting devices seeking Sakigake priority review.
Hospital value analysis committees are consolidating vendor selection authority previously dispersed among individual neurosurgeons and neurologists. Integrated delivery networks in the United States now mandate standardized neuromodulation platforms across multiple facilities, displacing physician preference item procurement. This concentration is most visible in California and Texas health systems where capitated contracts for movement disorder episodes drive device standardization.
Neurotechnology Market Segmentation
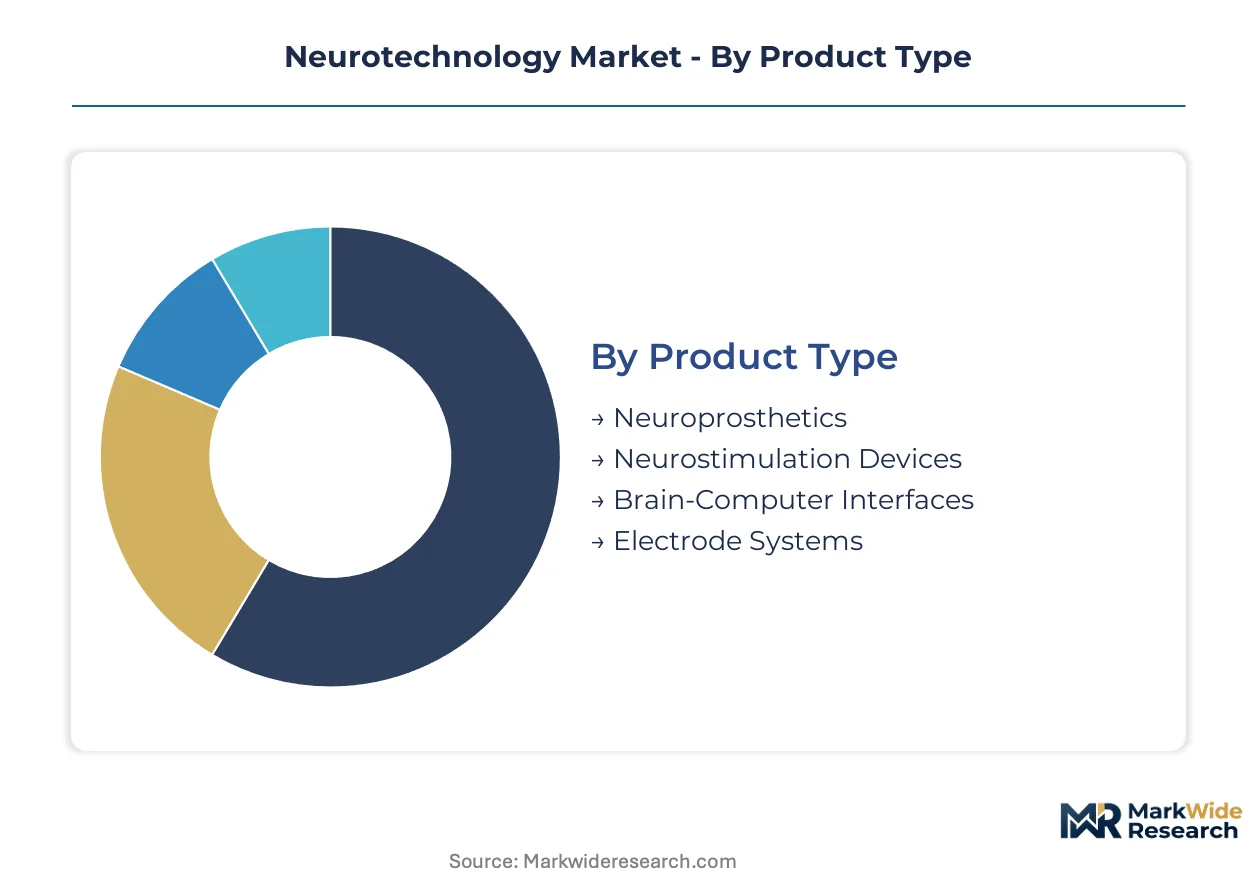
Segmentation in neurotechnology reveals distinct procurement patterns across institutional buyers and therapeutic applications. Hospital systems prioritize implantable systems with established reimbursement codes, while research institutions drive demand for experimental interfaces. Understanding these divides shapes go-to-market timing and regulatory investment priorities.
Product Type:
Neurostimulation devices and brain-computer interfaces concentrate manufacturing in the United States and Germany, while electrode systems flow from specialized materials suppliers in Japan and South Korea. Neuroprosthetics production spans multiple geographies with regional regulatory tailoring.
- Neurostimulation Devices:Implantable pulse generators and leads delivering electrical modulation to targeted neural tissue, operating at microampere current ranges with impedance-matched electrode interfaces. Demand clusters in German hospital systems and US academic medical centers where CMS and statutory health insurance reimbursement for chronic pain and movement disorders is codified. Supply chains depend on platinum-iridium electrode sourcing from South African refiners.
- Brain-Computer Interfaces:Direct neural signal acquisition and decoding platforms enabling motor or communication restoration for paralysis patients, requiring surgical implantation or endovascular deployment. US hospital procurement groups are rotating toward these platforms as FDA breakthrough designations accelerate coverage discussions; Japanese PMDA Sakigake pathways attract early commercialization investment toward Tokyo and Osaka networks.
- Neuroprosthetics:Artificial limbs and sensory substitution devices with integrated neural control interfaces.
- Electrode Systems:Thin-film arrays and biocompatible coatings from materials specialists in Japan and South Korea, supplying device integrators globally.
Neurostimulation devices hold the largest share; momentum sits with brain-computer interfaces.
Therapy Area:
Cost tiers separate established indications with mature reimbursement from experimental applications requiring out-of-pocket or grant funding. Chronic pain and neurological disorder therapies command premium pricing through hospital procurement, while cognitive enhancement operates at lower price points with direct-to-consumer or wellness clinic channels.
- Chronic Pain:Spinal cord stimulation and peripheral nerve modulation for refractory neuropathic and nociceptive conditions, with established CPT coding in US Medicare and German DRG systems. Hospital value analysis committees in California and Texas health systems mandate standardized platforms across integrated delivery networks, compressing vendor selection timelines.
- Neurological Disorders:Deep brain stimulation for Parkinson's disease, essential tremor, and dystonia, plus emerging applications for epilepsy and obsessive-compulsive disorder. German outpatient neuromodulation in Bavaria and North Rhine-Westphalia lacks dedicated reimbursement codes for next-generation systems, creating ambulatory surgical center expansion opportunities.
- Rehabilitation:Post-stroke motor recovery and spinal cord injury functional restoration through functional electrical stimulation.
- Cognitive Enhancement:Non-invasive neuromodulation for attention, memory, and executive function optimization in healthy populations.
Chronic pain commands the dominant revenue pool; rehabilitation is expanding most quickly as regulatory pathways for severe paralysis indications mature.
End User:
Customer type determines sales cycle length and regulatory burden. Hospitals and research institutions require extensive clinical evidence and GMP manufacturing compliance, while home care channels prioritize usability and remote monitoring capabilities.
- Hospitals:Tertiary care centers and academic medical centers performing implantation surgeries and managing complex neuromodulation cases. US integrated delivery networks in California and Texas now mandate standardized platforms across multiple facilities, displacing physician preference item procurement and concentrating vendor authority in value analysis committees.
- Research Institutions:Universities and national laboratories conducting preclinical and early clinical trials for novel neural interfaces. These buyers tolerate longer regulatory timelines and experimental device exemptions, sourcing from specialized manufacturers with ISO 13485 quality systems and FDA master file documentation.
- Clinics:Ambulatory surgical centers and specialty neurology practices performing device programming and non-invasive treatments.
- Home Care:Patient-managed transcutaneous stimulation and emerging closed-loop adaptive systems with remote clinician oversight.
Hospitals generate the highest absolute revenue; home care is gaining share fastest as closed-loop algorithms enable personalized parameter adjustment without clinical intervention.
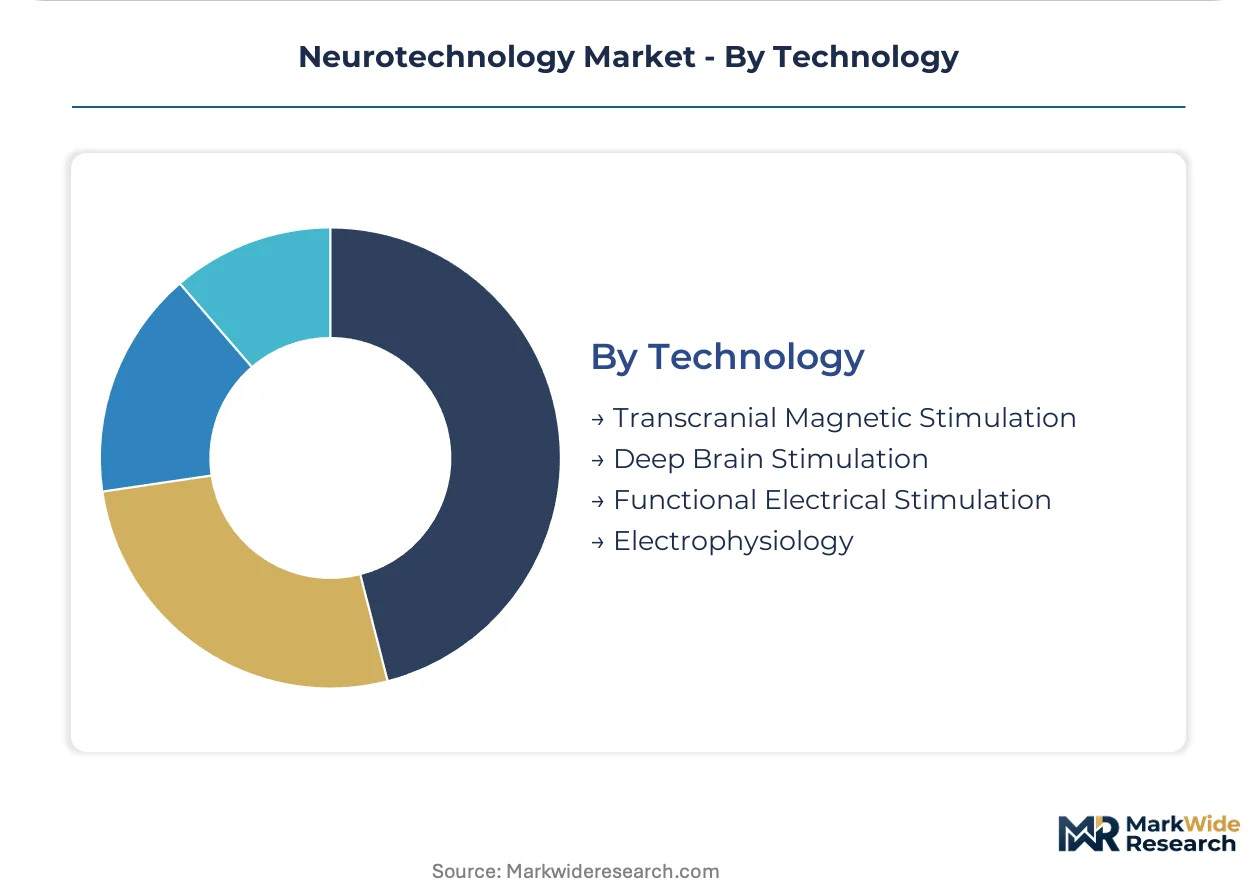
Technology:
Application context distinguishes invasive from non-invasive modalities. Deep brain stimulation and electrophysiology require surgical infrastructure and specialized neurosurgical training, while transcranial magnetic stimulation deploys through outpatient psychiatry and pain clinics.
- Deep Brain Stimulation:Surgically implanted electrodes targeting subcortical structures with programmable pulse generators, operating at 2-4V amplitude and 60-185Hz frequency ranges. German hospital systems and US academic centers lead implant volumes; EU MDR clinical evidence requirements extend conformity assessment timelines by 12-18 months for novel platforms.
- Electrophysiology:Intraoperative neural monitoring and diagnostic recording systems for epilepsy localization and functional mapping. Demand concentrates in Japanese epilepsy surgery centers leveraging PMDA Sakigake priority review for novel monitoring arrays with no domestic precedent.
- Transcranial Magnetic Stimulation:Non-invasive magnetic coil systems inducing cortical depolarization for depression and chronic pain, threatening market share for surgical implants in select indications.
- Functional Electrical Stimulation:Surface or percutaneous electrode activation of peripheral nerves and muscles for motor restoration.
Deep brain stimulation retains the largest installed base; electrophysiology shows the steepest expansion trajectory as graphene-based electrode arrays displace conventional silicon substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement groups in the United States, Germany, and Japan concentrate demand for implantable neurotechnology systems. Reimbursement frameworks in these markets determine whether next-generation platforms achieve commercial scale or remain confined to research budgets.
United States
Integrated delivery networks in California and Texas mandate standardized neuromodulation platforms across multiple facilities, displacing physician preference item procurement. FDA breakthrough device designation accelerates review timelines for novel brain-computer interfaces targeting severe paralysis. Boston and San Francisco academic medical centers pilot graphene-based electrode arrays for epilepsy monitoring.
Germany
Statutory health insurance reimbursement for chronic pain and movement disorders supports spinal cord stimulation and deep brain stimulation volumes. EU MDR clinical evidence requirements extend conformity assessment timelines by 12-18 months for active implantable devices. Bavaria and North Rhine-Westphalia ambulatory surgical centers lack dedicated reimbursement codes for next-generation systems.
Japan
PMDA Sakigake framework offers priority review for neurotechnology with no domestic precedent, redirecting early commercialization strategies toward Tokyo and Osaka hospital networks. Epilepsy surgery centers in these cities drive demand for novel electrophysiology monitoring arrays. METI funding programs support domestic electrode materials development.
South Korea
MFDS regulatory pathways for implantable neural interfaces are converging with US FDA standards, enabling parallel submission strategies for device manufacturers. Seoul-based materials specialists supply thin-film electrode arrays to global device integrators. Government-backed neurotechnology research clusters in Daejeon accelerate process development.
Switzerland
Swissmedic maintains accelerated review pathways for breakthrough neuromodulation devices, attracting European commercialization headquarters. Zurich and Geneva academic hospitals participate in multinational clinical trials for closed-loop adaptive stimulation systems. Precision manufacturing ecosystems in Basel support biocompatible coating process development.
Neurotechnology Market Competitive Environment
Player mix skews toward venture-backed neurotechnology specialists with deep materials science capabilities. The competitive terrain separates established neuromodulation device manufacturers from emerging brain-computer interface platforms. Two strategic archetypes dominate: vertically integrated surgical robotics developers and specialized electrode materials suppliers. M&A activity concentrates on electrode coating technologies and adaptive algorithm portfolios.
Among US-based neural interface developers, Neuralink, Synchron, and Paradromics occupy distinct positions within the invasive implant ecosystem. Neuralink represents the surgical robotics-integrated archetype with in-house electrode fabrication capabilities. Synchron exemplifies the endovascular deployment approach that circumvents open craniotomy requirements. Paradromics anchors the high-channel-count data acquisition segment. These three companies collectively illustrate the technology pathway divergence shaping competitive positioning in chronic implant applications.
| Leading Market Players |
|---|
| Synchron |
| INBRAIN Neuroelectronics |
| Neuralink |
| Ceribell |
| Insightec |
| Science Corporation |
| Neurable |
| Neuromod Devices |
| Paradromics |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for platinum-iridium electrode materials lock in supply access for implantable device manufacturers while anchoring cost visibility against South African and Russian refining volatility. These contracts insulate procurement budgets from spot market swings that disrupt smaller competitors lacking balance sheet depth for strategic raw material reserves.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate electrode material procurement, passing commodity volatility through to device manufacturers while capping processor margins. Pricing stratifies across premium graphene-based arrays, standard platinum-iridium configurations, and economy-tier silicon substrates differentiated by signal resolution and biocompatibility certification grade. Cost compression in standard-tier neurostimulation devices is intensifying because Japanese and South Korean materials suppliers are expanding thin-film manufacturing capacity. Academic medical centers show least price sensitivity given grant-funded research budgets, while ambulatory surgical centers in German outpatient settings face acute budget constraints from statutory health insurance reimbursement caps.
Supply Chain Analysis
Strategic stockpiling of platinum-iridium alloys prevails among tier-one device manufacturers, while just-in-time inventory management characterizes smaller electrode coating specialists with limited working capital. Supply concentrates in South Africa for platinum-iridium refining, Japan and South Korea for thin-film electrode fabrication, and the United States for pulse generator assembly. Raw material dependencies span noble metal alloys, biocompatible polymer substrates, and precision-machined titanium enclosures. Single-source vulnerability in South African refining capacity creates structural exposure to export restriction risk. Distribution runs through specialized medical device distributors with GMP-certified warehousing and direct-to-hospital logistics for implantable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurotechnology sits in early-cycle expansion as FDA breakthrough designations compress clinical validation timelines and accelerate hospital procurement committee engagement with brain-computer interface platforms.
For Market Incumbents: Compound installed base advantages by deepening backward integration into electrode materials and surgical robotics while accelerating EU MDR technical documentation to preempt conformity assessment delays. Threat from endovascular deployment platforms demands defensive patent portfolio investment in minimally invasive neural access. Priority lever sits with closed-loop algorithm development to differentiate against non-invasive neuromodulation alternatives. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers the most penetrable regulatory pathway for severe paralysis indications, enabling accelerated coverage discussions with CMS and private payers. White-space targets cluster in German ambulatory surgical centers lacking dedicated reimbursement codes for next-generation spinal cord stimulation, and in Japanese epilepsy surgery centers seeking novel electrophysiology monitoring arrays under PMDA Sakigake priority review. Go-to-market angle should emphasize value-based contracting with integrated delivery networks in California and Texas health systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrode materials specialists with captive supply relationships to multiple device integrators, generating predictable offtake streams across product development cycles. Long-term viability over a multi-year horizon hinges on regulatory pathway clarity and reimbursement code assignment velocity. Acquisition target archetype combines graphene-based electrode IP with ISO 13485 manufacturing infrastructure. Signal to watch is CMS transitional pass-through payment expiration timelines for breakthrough device categories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for novel neuromodulation platforms targeting severe paralysis indications. |
| EU MDR Conformity Assessment | Extends timelines for active implantable devices, demanding front-loaded pivotal trials and early authorized representative structures. |
| Hospital System Partnership | California and Texas integrated delivery networks now mandate standardized platforms across multiple facilities. |
| Software Companion Development | Closed-loop adaptive algorithms enable personalized stimulation parameter adjustment without clinician intervention. |
| Reimbursement Strategy | CMS transitional pass-through payments create temporary budget capture windows before standard coding assignment. |
Study Parameters
A spread of perspectives from neurosurgeons, hospital value analysis committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions for procurement behavior and technology adoption timelines. Primary interview insights combined with secondary validation from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up demand modeling across therapy areas and end-user segments triangulated against top-down market sizing from device shipment data and materials supplier revenue disclosures.
Segmentation dimensions modeled span product type, therapy area, end user, and technology modality across the analysis window. Analytical framework incorporates impedance-matched electrode interface specifications, pulse generator current ranges, and biocompatibility certification tiers as industry-specific forecast inputs. CAGRs derive from regression analysis of historical implant volumes against reimbursement code expansion and regulatory pathway maturation.
Decision-makers should treat outputs as directional under assumptions of stable platinum-iridium supply and continued CMS pass-through payment availability; material deviation would warrant model refresh. Revision becomes warranted when FDA breakthrough designation velocity or EU MDR notified body capacity constraints cross thresholds that alter commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Capsulotomy Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Urology Guidewires Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
External Nasal Dilator Market
Medical Devices
External Pacemakers Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
North America Arthroscopy Devices Market