
 Steroid Releasing Implant Market | 2026-2036
Steroid Releasing Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Steroid Releasing Implant Market Analytics
Specialty ophthalmology centers is redrawing procurement patterns for steroid releasing implants as hospital outpatient departments cede share to standalone retina clinics. Zoetis leverages its veterinary implant heritage to cross-apply polymer matrix expertise into human ocular applications. EyePoint Pharma anchors its position through proprietary micro-insert technology that extends drug release kinetics beyond conventional depot formulations. Ocular Therapeutix competes with hydrogel-based platforms designed for intracanalicular delivery in anterior segment disease.
Steroid releasing implants are polymer- or lipid-based drug delivery systems engineered to release corticosteroids at controlled rates over weeks to months, typically incorporating dexamethasone, triamcinolone, or fluocinolone acetonide into biodegradable matrices such as PLGA or non-biodegradable reservoirs with rate-controlling membranes. These devices serve to maintain therapeutic drug concentrations at target tissues while minimizing systemic exposure and dosing frequency. Biodegradable implants capture the dominant share of new product development as surgeons prioritize elimination of removal procedures, though non-biodegradable sustained-release devices retain stronghold positions in chronic retinal conditions requiring multi-year therapy. Intravitreal injection dominates delivery mode utilization in ocular applications, while subcutaneous injection leads in chronic pain and inflammatory disorder management where depot formulations reduce opioid dependency.
FDA, EMA, and PMDA each enforce distinct biocompatibility and sterilization validation requirements that lengthen development cycles but elevate barriers to commoditization. The EU MDR and FDA 510(k) pathways for combination products demand extensive clinical evidence for novel polymer degradation profiles, favoring incumbents with established regulatory dossiers. Stakeholders must monitor evolving pharmacovigilance obligations for sustained-release corticosteroids, particularly regarding intraocular pressure elevation and cataractogenesis signals that could trigger restricted labeling or reimbursement scrutiny.
Market Dynamics
Sustained-release polymer engineering is compressing dosing intervals from quarterly to biennial administration, forcing manufacturers to rebuild validation protocols around extended degradation kinetics rather than incremental formulation tweaks.
Growth Catalysts
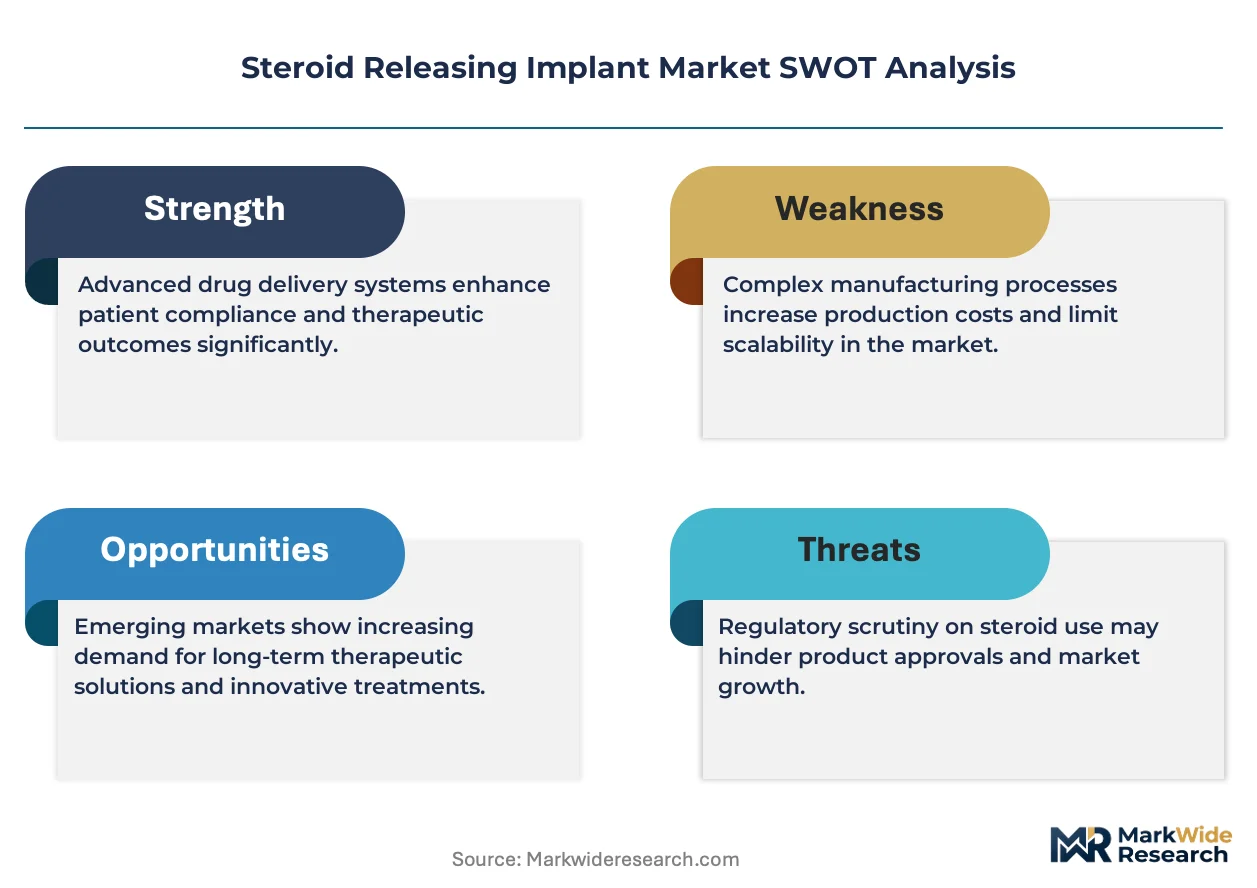
- EU MDR biocompatibility mandates:Stricter material validation requirements for combination products are filtering out commodity competitors and elevating dossier quality across the sterile implant category.
- Retina specialty clinic proliferation:Standalone ophthalmology centers in the United States and Germany are building captive surgical volume that absorbs high-unit-cost implants without hospital procurement friction.
- PLGA matrix refinement:Advances in lactide-glycolide copolymer degradation control enable zero-order release kinetics that match chronic disease pharmacology.
Market Restraints
- Silicone oil excipient concentration:Three suppliers dominate pharmaceutical-grade silicone raw material, creating input vulnerability for non-biodegradable reservoir implants.
- FDA 510(k) clinical evidence thresholds:Novel polymer degradation profiles trigger PMA-equivalent data demands that extend development timelines by eighteen to thirty-six months.
- Intravitreal anti-VEGF substitution:Ranibizumab and aflibercept depot formulations compete for macular edema cases where steroid-induced intraocular pressure elevation is contraindicated.
Strategic Opportunities
- Japan's aging surgical population:PMDA reimbursement pathways for sustained-release uveitis therapy remain underpenetrated relative to procedural volume potential.
- Intracanalicular anterior segment delivery:Hydrogel-based platforms address dry eye and allergic conjunctivitis outside the crowded retinal therapeutics space.
- Outcome-based contracting with German sickness funds:Risk-sharing arrangements for steroid implant efficacy against reoperation rates create preference pull through statutory reimbursement.
Industry Challenges
- Polymer characterization expertise scarcity:Analytical chemists capable of validating complex degradation profiles command compensation premiums that strain mid-cap development budgets.
- ISO 10993 biological evaluation harmonization:Divergent FDA and EMA interpretations of cytotoxicity and sensitization endpoints force duplicate testing campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steroid Releasing Implant Market |
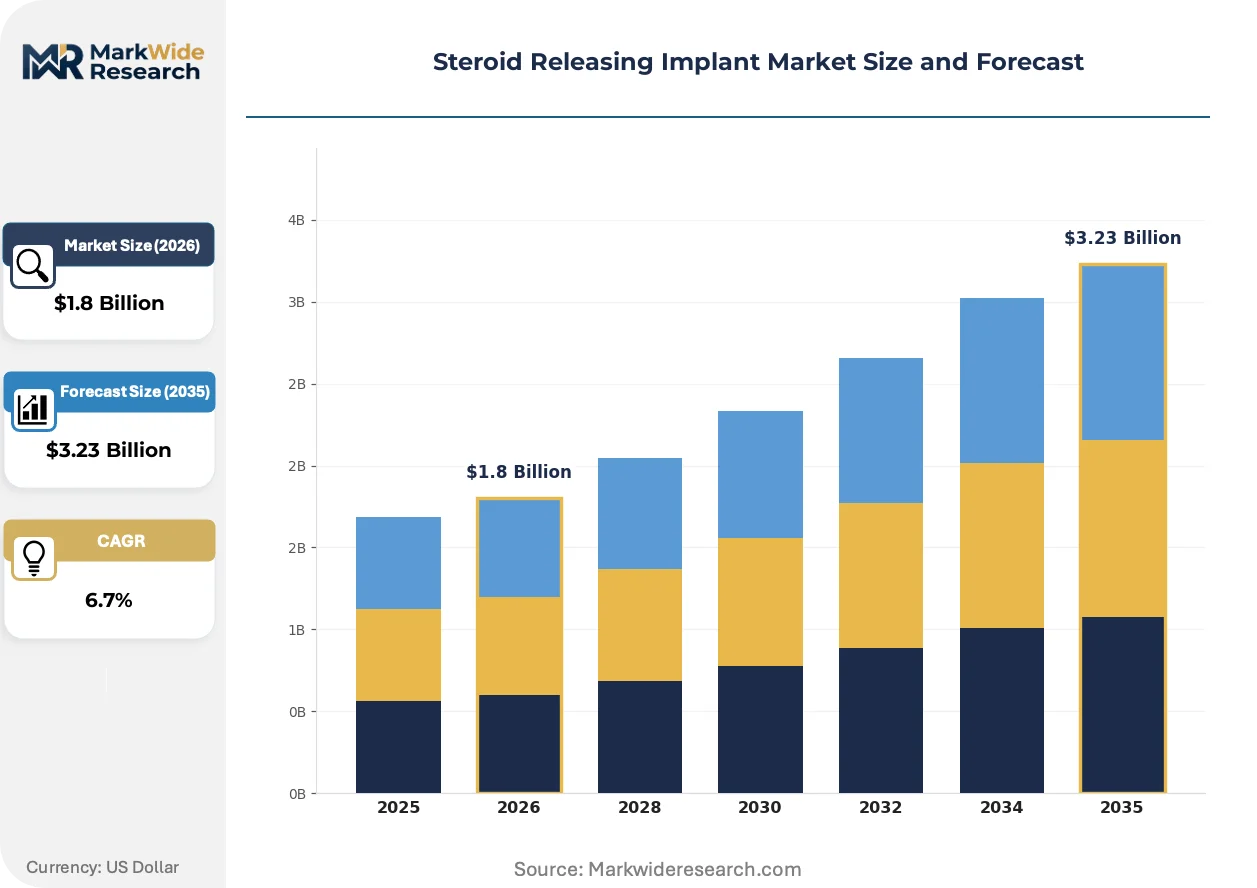
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Implants, Non-Biodegradable Implants, Sustained-release Devices, Matrix Systems Delivery Mode: Subcutaneous Injection, Intra-articular Injection, Intravitreal Injection, Transdermal Patch End User: Hospitals, Clinics, Specialty Centers, Research Institutions Therapy Area: Chronic Pain, Inflammatory Disorders, Dermatological Conditions, Ocular Diseases |
| Companies Covered | Zoetis, Elanco, Pfizer, Novartis, GSK, Merck, AstraZeneca, Ocular Therapeutix, EyePoint Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steroid Releasing Implant Market Evolving Landscape
Biodegradable matrix engineering and intravitreal delivery refinement are converging to eliminate explantation procedures while tightening pharmacokinetic control over corticosteroid tissue exposure.
Micro-insert fabrication is miniaturizing dexamethasone delivery vehicles below 3mm length thresholds. Retina specialists in United States metropolitan markets are adopting these devices for branch retinal vein occlusion cases previously managed by larger depot formulations. The technology is miniaturizing surgical incision requirements and compressing operating room time allocations per procedure.
EMA's 2023 MDR guidance on implantable device sterility assurance levels has elevated terminal sterilization validation requirements for European market access. Manufacturers must now demonstrate ten-to-the-minus-six sterility assurance across novel polymer matrices. German notified bodies are interpreting this most stringently, delaying CE marking timelines for biodegradable implant candidates.
Standalone retina clinics are consolidating purchasing authority away from hospital outpatient departments. United States-based specialty ophthalmology centers now negotiate direct manufacturer contracts that bypass group purchasing organization intermediaries. This channel migration is most visible in Texas and Florida markets where certificate-of-need restrictions on ambulatory surgery centers have loosened.
Steroid Releasing Implant Market Segmentation
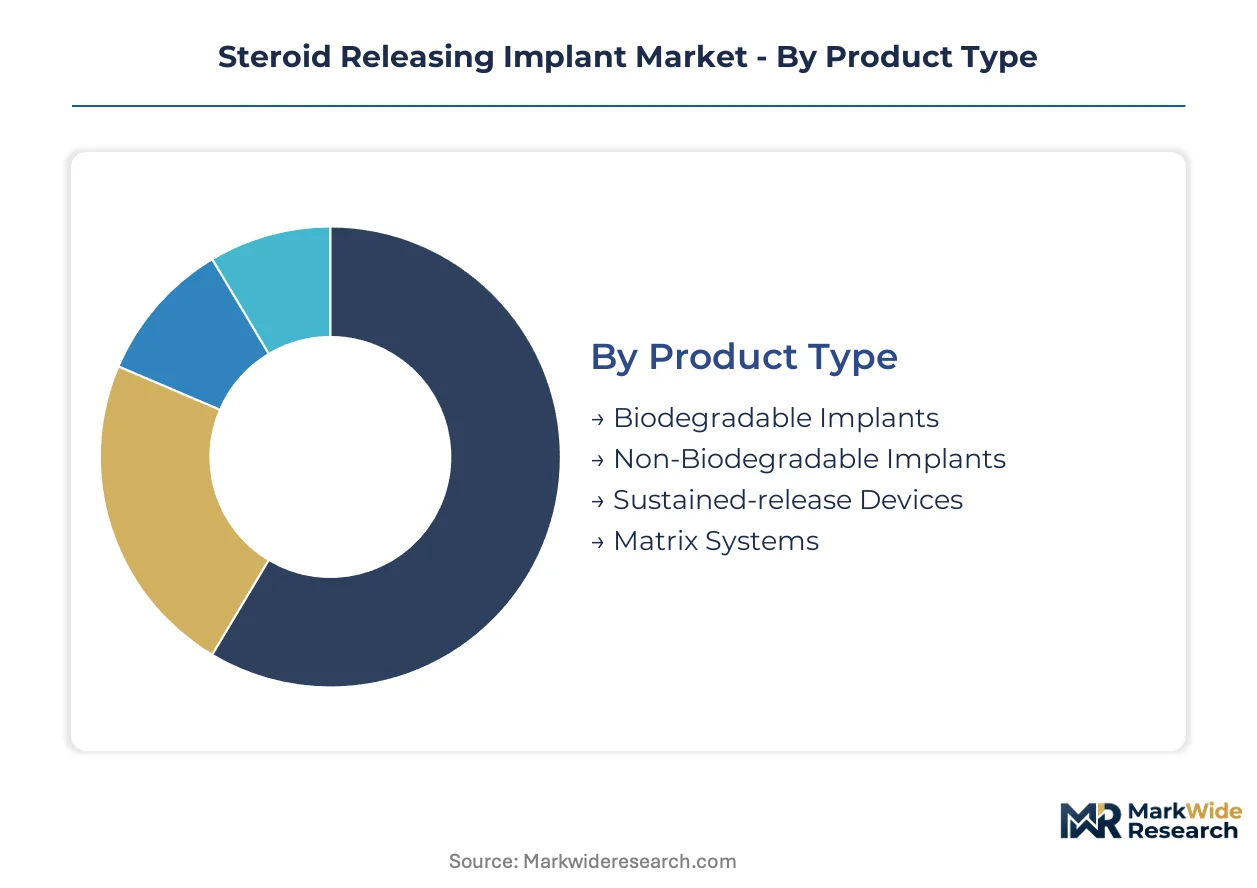
Steroid releasing implant manufacturers navigate divergent substitution pressures across product architectures and delivery modes. Segmentation clarity determines which formulations withstand anti-VEGF encroachment versus those vulnerable to depot injection alternatives.
Product Type:
Biodegradable formulations face intensifying competition from sustained-release biologics in macular edema, while non-biodegradable reservoirs confront removal-procedure aversion among retina specialists.
- Biodegradable Implants:PLGA and polycaprolactone matrices degrade through hydrolysis, eliminating explantation. Demand concentrates in United States metropolitan retina clinics where surgeons prioritize single-procedure outcomes and reduced operating room utilization. FDA 510(k) pathways for novel lactide-glycolide ratios now demand extended degradation kinetic data that extends validation timelines.
- Non-Biodegradable Implants:Silicone oil reservoirs with rate-controlling membranes permit multi-year corticosteroid release for chronic uveitis. Germany's statutory sickness funds reimburse these devices preferentially for bilateral intermediate uveitis requiring bilateral implantation, where removal complexity is offset by extended therapeutic duration. EMA MDR sterility assurance mandates have tightened terminal validation requirements for European market access.
- Sustained-release Devices:Reservoir-based systems with diffusion-controlled membranes.
- Matrix Systems:Homogeneous polymer-drug dispersions without membrane barriers.
Biodegradable implants retain volume leadership; non-biodegradable implants hold the steepest expansion curve in chronic uveitis maintenance therapy.
Delivery Mode:
Route selection determines reimbursement tiering and procedural venue economics, with intravitreal administration commanding premium positioning against subcutaneous alternatives in pain management.
- Intravitreal Injection:Direct vitreous cavity placement via pars plana approach. United States standalone retina clinics absorb the highest procedural volumes for diabetic macular edema and retinal vein occlusion, bypassing hospital outpatient department procurement friction. PMDA reimbursement pathways in Japan remain underpenetrated relative to aging surgical population potential.
- Subcutaneous Injection:Depot formulations for chronic pain and inflammatory disorders. Germany's ambulatory pain centers utilize these devices to reduce opioid dependency in lumbar radiculopathy, with statutory sickness funds covering triamcinolone acetonide microsphere formulations under diagnosis-related group carve-outs.
- Intra-articular Injection:Joint space delivery for osteoarthritis and inflammatory arthropathies.
- Transdermal Patch:Percutaneous corticosteroid absorption for localized dermatological conditions.
Intravitreal injection dominates value capture; subcutaneous delivery is expanding most quickly in chronic pain management outside ophthalmology.
End User:
Procurement authority migration from hospital systems to standalone facilities is redistributing volume across venue types with divergent pricing tolerance and contract structures.
- Specialty Centers:United States retina clinics in Texas and Florida negotiate direct manufacturer contracts, bypassing group purchasing organization intermediaries. These venues prioritize micro-insert technologies that compress operating room time and enable higher surgical throughput.
- Hospitals:Academic medical centers retain complex case referrals requiring combined surgical procedures.
- Clinics:Community ophthalmology practices with limited surgical suites.
- Research Institutions:Clinical trial sites for novel polymer degradation profiles.
Specialty centers are gaining share fastest; hospitals retain volume leadership in complex bilateral cases.
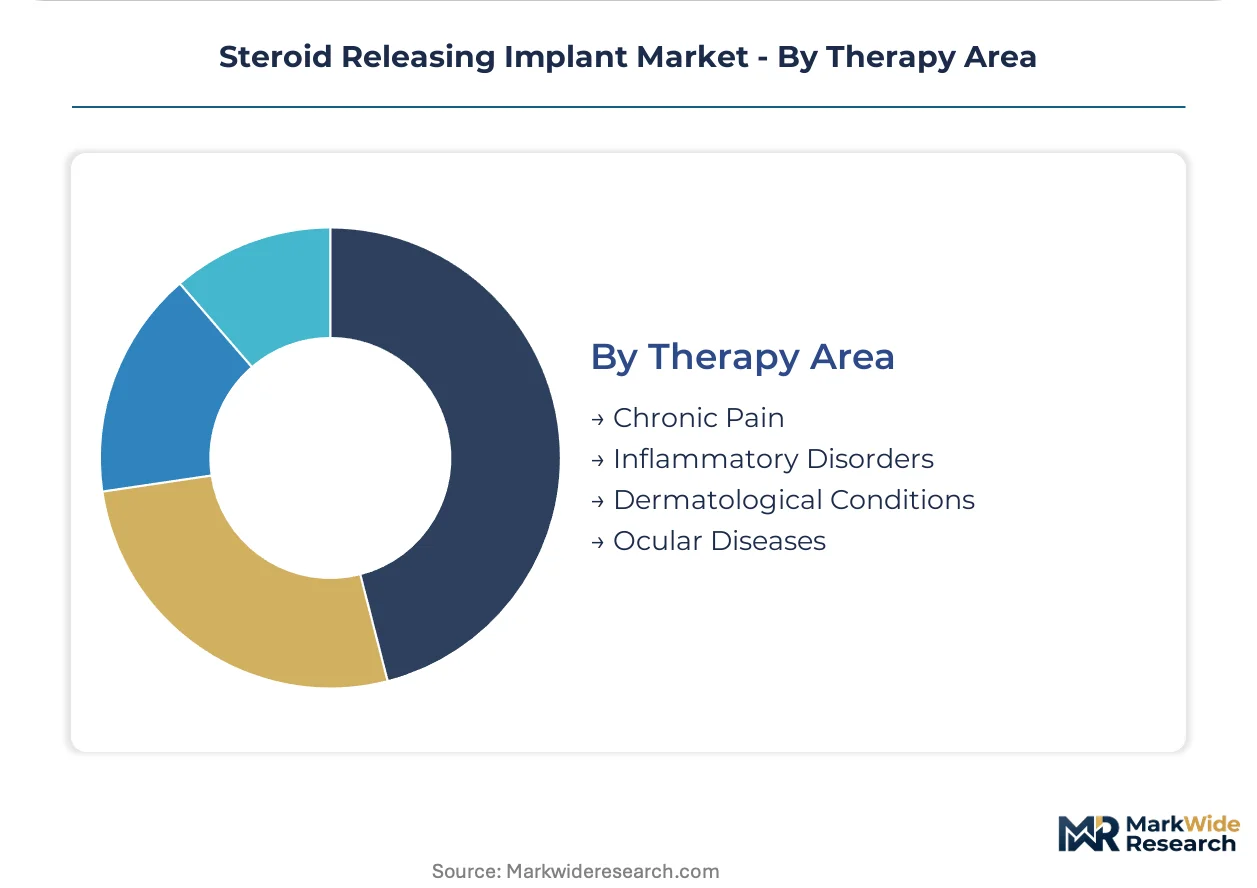
Therapy Area:
Disease-specific reimbursement pathways and competitive therapeutic alternatives segment opportunity by clinical indication, with ocular applications commanding premium positioning against commoditized pain management.
- Ocular Diseases:Macular edema, uveitis, and diabetic retinopathy indications. United States retina specialists adopt dexamethasone micro-inserts for branch retinal vein occlusion, displacing larger depot formulations. Ranibizumab and aflibercept sustained-release formulations compete directly for cases where steroid-induced intraocular pressure elevation is contraindicated.
- Chronic Pain:Lumbar radiculopathy and complex regional pain syndrome. Germany's integrated care contracts for chronic pain favor subcutaneous triamcinolone depots as opioid-sparing alternatives, with outcome-based pricing tied to reoperation rate reductions.
- Inflammatory Disorders:Rheumatoid arthritis and inflammatory bowel disease localized manifestations.
- Dermatological Conditions:Localized psoriasis and lichen planus requiring prolonged corticosteroid exposure.
Ocular diseases retain volume leadership; chronic pain holds the steepest expansion curve in European integrated care contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer characterization expertise clusters in Germany and the United States, where regulatory validation infrastructure supports complex implant development. FDA and EMA biocompatibility mandates are redrawing competitive access across national boundaries.
United States
Standalone retina clinics in Texas and Florida absorb the highest procedural volumes for dexamethasone micro-inserts, bypassing hospital outpatient department procurement friction. FDA 510(k) pathways for novel lactide-glycolide ratios now demand extended degradation kinetic data. Greater Boston anchors polymer engineering talent pools that feed validation protocols for biodegradable matrices.
Germany
Statutory sickness funds reimburse non-biodegradable silicone oil reservoir implants preferentially for bilateral intermediate uveitis. EMA MDR sterility assurance mandates have tightened terminal validation requirements, with German notified bodies interpreting guidance most stringently. Bavaria's medical technology cluster concentrates analytical chemists capable of complex degradation profile validation.
Japan
PMDA reimbursement pathways for sustained-release uveitis therapy remain underpenetrated relative to aging surgical population potential. METI industrial policy supports domestic polymer matrix refinement through targeted R&D subsidies. Kanto region retina specialists are adopting micro-insert technologies that compress operating room time allocations.
Switzerland
Swissmedic combination product oversight elevates dossier quality requirements for European market access. Basel's pharmaceutical manufacturing corridor hosts sterile implant production facilities serving EMA-regulated markets. The country's precision polymer engineering heritage supports zero-order release kinetics development.
United Kingdom
London-based specialty ophthalmology centers negotiate direct manufacturer contracts that bypass group purchasing organization intermediaries. MHRA post-Brexit regulatory alignment with EMA MDR maintains biocompatibility validation standards. The Southeast corridor concentrates clinical trial sites for novel polymer degradation profiles.
Steroid Releasing Implant Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing established regulatory dossiers and polymer engineering capabilities. The vendor base stratifies across three tiers: integrated pharmaceutical majors with combination product expertise, mid-cap ophthalmology specialists with proprietary delivery platforms, and veterinary-to-human crossover players leveraging polymer matrix heritage. M&A activity targets micro-insert fabrication capabilities, while strategic partnerships concentrate on extended-release validation data sharing.
Among diversified pharmaceutical conglomerates, Novartis and Pfizer exemplify scale-driven archetypes with combination product infrastructure spanning multiple therapeutic areas. EyePoint Pharma and Ocular Therapeutix occupy positions within the ophthalmology specialist tier, representing proprietary delivery technology approaches. Zoetis anchors the veterinary-to-human crossover segment, leveraging animal health implant heritage.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Pfizer |
| Novartis |
| GSK |
| Merck |
| AstraZeneca |
| Ocular Therapeutix |
| EyePoint Pharma |
| Others |
Value Network & Pricing Analysis
Polymer engineering scale economies in Germany and the United States establish cost floors that filter out commodity competitors while concentrating margin capture among validated manufacturers. FDA and EMA biocompatibility dossier requirements elevate fixed validation costs, compressing mid-tier pricing flexibility and tethering price floors to regulatory compliance investment recovery cycles.
Pricing Analysis
Volume-discount tiering structures separate premium biodegradable micro-inserts from standard depot formulations and economy-tier pain management depots. Price differentiation rests on FDA 510(k) clearance tier and PLGA degradation profile certification, with German sickness funds negotiating outcome-based rebates for bilateral uveitis cases. Cost compression in subcutaneous pain management depots is intensifying as opioid-sparing mandates expand addressable volume. Hospital outpatient departments exhibit highest price sensitivity due to GPO-negotiated ceilings, while standalone retina clinics absorb premium positioning for operating-room-time savings.
Supply Chain Analysis
Germany and the United States anchor pharmaceutical-grade PLGA polymer production, with Switzerland hosting sterile finishing operations for EMA-regulated markets. Raw material dependencies center on lactide-glycolide monomer feedstocks and pharmaceutical-grade silicone oil for non-biodegradable reservoirs. Single-source vulnerability concentrates in silicone oil excipient supply, where three suppliers dominate global pharmaceutical-grade output. Distribution runs through direct manufacturer contracts with standalone specialty clinics, bypassing traditional hospital GPO intermediaries in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steroid releasing implants present a service-attach opportunity where procedural training and implantation certification programs expand recurring revenue faster than device hardware sales. Post-implantation monitoring services and pressure-management protocols for intraocular elevation represent the fastest-growing after-sales layer.
For Market Incumbents: Shield regulatory dossier advantages by accelerating PMA-equivalent data generation for novel lactide-glycolide ratios ahead of FDA 510(k) threshold escalations. Deepen backward integration into PLGA polymer production to capture margin compression from raw material suppliers and secure degradation profile customization capabilities against emerging biologic depot competitors.
For New Entrants and Emerging Players: Differentiate on intracanalicular anterior segment delivery platforms that bypass crowded retinal therapeutics spaces. Target Japan's underpenetrated PMDA reimbursement pathways for sustained-release uveitis therapy, where aging surgical population potential exceeds current procedural volume. Lead with hydrogel-based platform demonstrations to retina specialists in Kanto region academic medical centers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ophthalmology specialists with proprietary micro-insert fabrication capabilities and established surgeon training networks. Long-term viability over the next decade hinges on biodegradability engineering expertise and regulatory validation infrastructure rather than commodity formulation scale. Watch for EMA MDR sterility assurance interpretation divergence across German notified bodies as an inflection signal for European market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Advancement | Accelerated clearance for novel PLGA degradation profiles compresses competitive launch windows against depot biologics. |
| Surgeon Training Network Expansion | Captive education programs at Texas and Florida standalone clinics lock in procedural volume and device preference. |
| Polymer Matrix Backward Integration | In-house lactide-glycolide production secures supply continuity and enables proprietary release kinetics customization. |
| PMDA Reimbursement Strategy | Early engagement with Japan's statutory price listing process unlocks aging-population procedural volume potential. |
| Outcome-Based Contracting | Risk-sharing arrangements with German sickness funds tie implant reimbursement to reoperation rate reductions. |
Research Methodology
The analysis maps biodegradable implants, non-biodegradable reservoirs, and hydrogel-based delivery platforms, each validated through retina specialists, polymer engineering directors, hospital procurement managers, and regulatory affairs leads. Primary interviews with United States-based standalone clinic administrators and German sickness fund contract negotiators combined with secondary triangulation against FDA 510(k) filings, EMA MDR submission databases, PMDA reimbursement bulletins, and hospital GPO contract disclosures. Bottom-up procedure volume estimates and top-down manufacturer capacity assessments were cross-referenced for convergence.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product architecture, delivery mode, end-user venue type, and therapy area regulatory cluster. CAGRs were derived from procedure volume trajectories and pricing trend synthesis. Forecast inputs incorporated PLGA degradation kinetic validation timelines and EMA MDR sterility assurance interpretation variance across notified bodies.
Material uncertainties — regulatory threshold escalations, silicone oil supply disruptions, and anti-VEGF depot formulation approvals — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and surgeon adoption curves for micro-insert miniaturization. Recalibration cycles align with material shifts in FDA 510(k) evidence requirements and EMA MDR guidance interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
India Hemostats Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Critical Care Devices Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Hemodynamic Flow Alteration Devices Market
Medical Devices
Passive Prosthetics Market