
 Data Acquisition Card Market | 2026-2036
Data Acquisition Card Market Size, Share, and Industry Trends Forecast 2026-2036
Data Acquisition Card Market Analysis
Asset-light leasing models for high-channel-count systems is rewriting competitive dynamics in the Data Acquisition Card Market. National Instruments Corporation leverages its software-defined instrumentation platform to sustain recurring revenue from research laboratories. Keysight Technologies anchors its position through precision calibration services tied to instrumentation hardware. Advantech Co. Ltd. specializes in ruggedized embedded form factors for factory-floor deployments.
A data acquisition card is a printed circuit assembly that converts analog sensor signals into digital data through analog-to-digital converters with sampling rates ranging from kilohertz to gigahertz, enabling measurement, logging, and real-time analysis in industrial and scientific environments. Analog Cards retain the largest installed base due to legacy compatibility with thermocouple and strain-gauge sensor networks, though Mixed-Signal Cards capture expanding margin pools where single-instrument consolidation reduces system footprint. PXI modular chassis deployments dominate aerospace and defense test benches, while USB interfaces penetrate academic settings where benchtop portability outweighs channel density requirements.
FCC Part 15 emissions standards constrain signal integrity design for Ethernet-connected cards deployed near radio-frequency equipment, while EU RoHS substance restrictions govern solder and coating material selection for cards sold into European manufacturing end users. ISO/IEC 17025 calibration traceability requirements shape procurement criteria for metrology-grade installations in automotive and telecommunications laboratories. Stakeholders must weigh modular upgrade paths against integrated platform commitments as sensor bandwidth requirements diverge across end-use verticals.
Market Dynamics
PCIe-based data acquisition modules are compressing deployment timelines for electric powertrain validation systems as automotive OEMs face tightened EPA emissions testing protocols. This interface standardization is redistributing margin pools away from proprietary chassis architectures toward software-defined instrumentation stacks.
Growth Catalysts
- EPA Protocol Stringency:Tightened emissions validation requirements for electric powertrains are expanding channel-count requirements in automotive test cells.
- Industrial Automation Density:Germany's manufacturing cluster is consolidating sensor networks onto single-card mixed-signal architectures to reduce footprint.
- ISO/IEC 17025 Traceability:Metrology-grade calibration mandates in telecommunications laboratories are extending replacement cycles for certified instrumentation.
Market Restraints
- Input Cost Volatility:Analog-to-digital converter silicon from concentrated foundry sources creates margin pressure on mid-range card portfolios.
- Technical Bandwidth Ceiling:Coaxial signal integrity limits constrain gigahertz-sampling cards deployed in high-density PXI chassis configurations.
- Regulatory Friction:FCC Part 15 emissions compliance adds engineering overhead for Ethernet-connected cards operating near radio-frequency equipment.
Strategic Opportunities
- Underpenetrated Academic Segment:USB-interfaced portable systems are capturing benchtop replacement cycles in university research settings where channel density requirements remain modest.
- Technology Convergence:Edge computing architectures are embedding data acquisition functions directly onto factory-floor sensor nodes, bypassing centralized chassis.
- Asset-Light Leasing Models:High-channel-count system rentals are penetrating aerospace program development cycles where capital deployment flexibility outweighs ownership economics.
Industry Challenges
- Specialized Talent Scarcity:Mixed-signal hardware-software integration expertise remains concentrated among legacy test equipment engineering pools.
- Certification Timeline Compression:EU RoHS substance documentation requirements are extending qualification cycles for European manufacturing deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Acquisition Card Market |
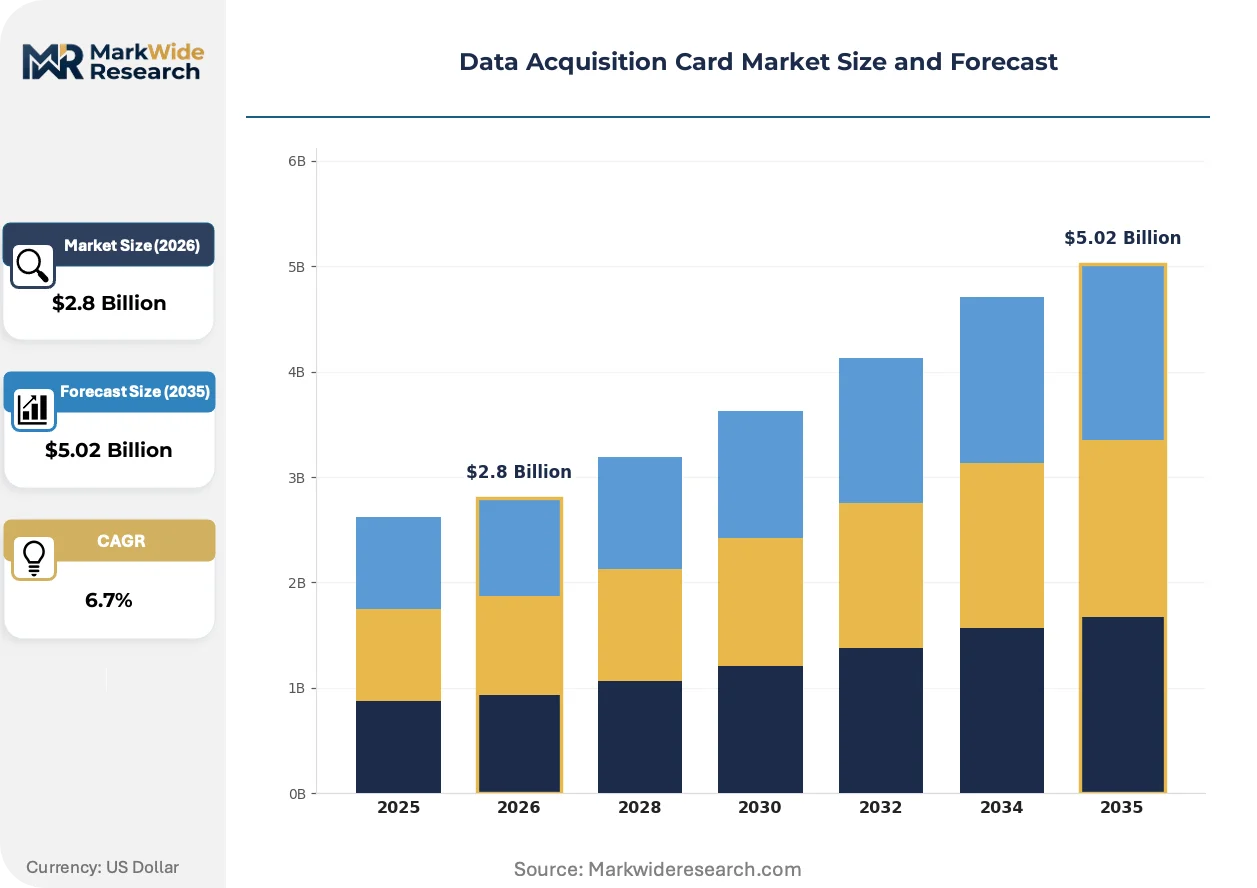
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Cards, Digital Cards, Mixed-Signal Cards, Communication Cards Technology: USB, PCIe, PXI, Ethernet End User: Academic Institutions, Manufacturing, Telecommunications, Automotive Form Factor: Standalone, Embedded, Module, Rack-Mounted |
| Companies Covered | National Instruments Corporation, Keysight Technologies, Advantech Co. Ltd., Measurement Computing Corporation, ADLINK Technology, Yokogawa Electric Corporation, Teledyne Technologies, Siemens AG, AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Acquisition Card Market Emerging Trajectories
Software-defined instrumentation architectures are dissolving the boundary between hardware acquisition layers and analytics platforms. This convergence is compressing traditional vendor moats built on proprietary firmware ecosystems.
Time-sensitive networking over Ethernet is rendering obsolete deterministic data transport protocols that previously required dedicated backplane architectures. Automotive validation engineers in Michigan and Stuttgart are adopting IEEE 802.1AS-synchronized cards for distributed powertrain test rigs. This shift is collapsing the premium historically commanded by chassis-based synchronization modules.
EU RoHS substance restrictions are governing solder alloy selection and conformal coating chemistry for cards sold into European manufacturing end users. ECHA substance of very high concern listings are forcing reformulation of legacy tin-lead alternatives. German industrial automation purchasers now require full material disclosure documentation ahead of calibration system procurement.
Research laboratories are unbundling hardware acquisition from software licensing, creating preference for modular cards with open driver architectures. National Instruments and Keysight are responding with subscription-tier analytics platforms decoupled from hardware commitments. This pattern is most visible in US National Laboratory procurement cycles where multi-vendor interoperability reduces vendor lock-in risk.
Data Acquisition Card Market Segmentation
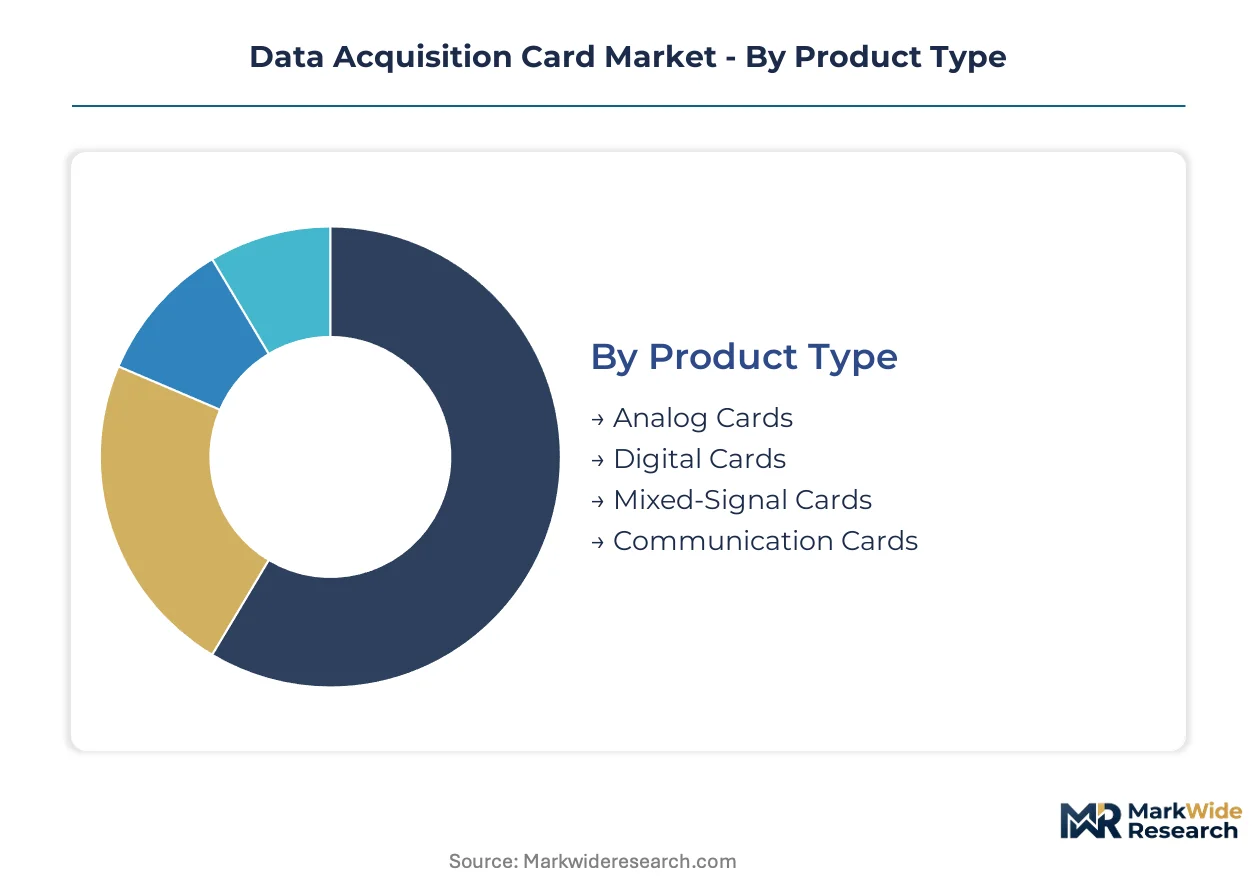
Segmentation in the Data Acquisition Card Market reveals how interface standards, deployment environments, and performance tiers fragment procurement patterns. Engineers select cards based on synchronization requirements, channel density, and thermal constraints rather than generic specifications.
Product Type:
Cost tiers separate legacy-compatible hardware from consolidated mixed-signal architectures.
- Analog Cards:These assemblies condition continuous voltage signals from thermocouples and strain gauges through dedicated front-end circuitry. Automotive test cells in Michigan and Stuttgart retain these cards for powertrain thermal mapping under EPA validation protocols. Analog Cards hold installed capacity. Mixed-Signal Cards are rotating up the share rankings.
- Mixed-Signal Cards:Single-instrument consolidation combines analog-to-digital and digital-to-analog conversion on unified PCIe or PXI modules. Germany's industrial automation cluster favors these for factory-floor sensor network consolidation where footprint reduction outweighs per-channel cost premiums.
- Digital Cards:Specialized modules capture discrete logic states and pulse trains from encoder and switch arrays.
- Communication Cards:Protocol-specific interfaces translate industrial fieldbus and automotive Ethernet frames into acquisition system backplanes.
Analog Cards dominate replacement cycles. Mixed-Signal Cards are climbing the fastest.
Technology:
Interface selection hinges on latency tolerance, cable reach, and chassis modularity requirements.
- PCIe:Direct motherboard integration delivers deterministic latency below 10 microseconds for closed-loop control applications. Electric powertrain validation engineers specify these modules for dynamometer feedback loops where EPA emissions test protocols demand sub-millisecond response.
- PXI:Chassis-based modular architecture supports synchronized multi-card triggering through dedicated backplane triggers. Aerospace test benches in Toulouse and Seattle deploy PXI for vibration analysis where channel counts exceed 256 per rack.
- USB:Bus-powered portability suits academic benchtop environments where mobility outweighs aggregate throughput.
- Ethernet:IEEE 802.1AS time-sensitive networking enables distributed acquisition nodes across factory floors without proprietary cabling.
PCIe captures automotive validation spend. Ethernet is gaining share fastest in greenfield industrial deployments.
End User:
Customer type determines calibration rigor, channel density, and procurement cycle length.
- Automotive:Powertrain validation laboratories require ISO/IEC 17025 traceable calibration chains for EPA emissions certification. Test cells in Detroit and Wolfsburg specify high-channel-count PCIe modules for electric motor efficiency mapping.
- Manufacturing:Quality control and process monitoring drive demand for ruggedized embedded cards with extended temperature specifications. German automation OEMs prioritize RoHS-compliant solder alloys and full material disclosure documentation.
- Academic Institutions:Research laboratories favor USB-interfaced portable systems for teaching and prototype validation where capital budgets constrain channel expansion.
- Telecommunications:Metrology-grade installations demand calibration certificates with NIST-traceable uncertainty budgets for RF component characterization.
Automotive holds certification-driven replacement volume. Manufacturing is rotating up the share rankings through Industry 4.0 sensor densification.
Form Factor:
Physical integration depth separates benchtop flexibility from embedded permanence.
- Embedded:DIN-rail or PCB-mount cards integrate directly into OEM equipment without external enclosures. Factory automation builders in Bavaria specify these for machine control cabinets where space constraints eliminate standalone chassis.
- Module:Slot-compatible cards for PXI or proprietary chassis enable field upgrade paths without system replacement. Aerospace program managers favor modular procurement for long-duration test campaigns where channel requirements evolve.
- Standalone:Self-enclosed units with integrated power supplies suit distributed monitoring without host PC proximity.
- Rack-Mounted:19-inch chassis cards consolidate high-density acquisition for central data centers and telecommunications test floors.
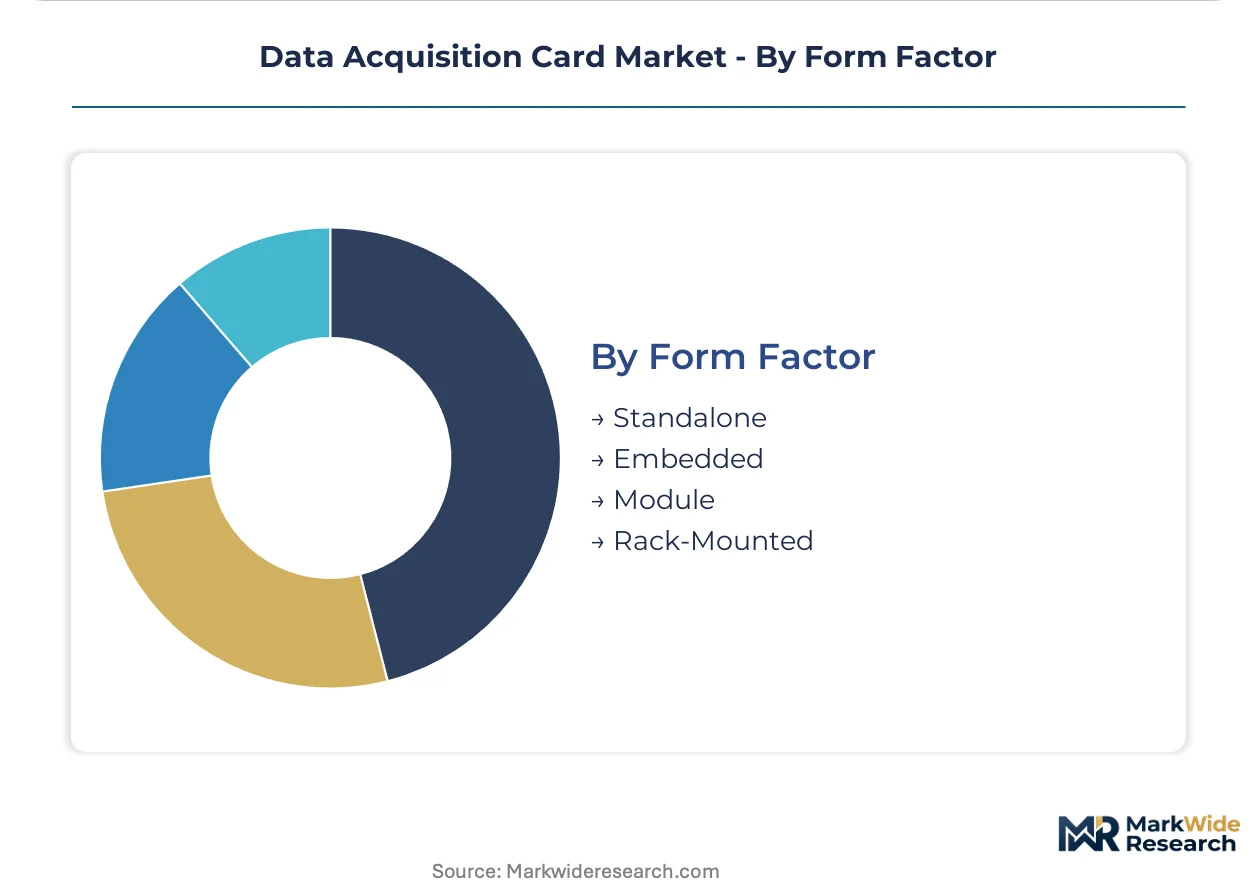
Embedded dominates new machine builds. Module form factors are expanding most quickly in aerospace development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German calibration-intensive procurement while US automotive validation labs absorb channel-count premiums. Japanese precision manufacturers extract margin through metrology-grade traceability requirements. Chinese industrial automation clusters compress pricing through localized PCIe module production.
United States
EPA emissions validation protocols for electric powertrains drive high-channel-count PCIe module procurement in Detroit and Michigan test corridors. NHTSA safety certification requirements extend calibration cycles for instrumentation hardware. Automotive OEM validation centers in Ann Arbor specify sub-millisecond latency modules for dynamometer feedback loops.
Germany
Industrial automation sensor densification and factory-floor consolidation fuel mixed-signal card demand across Bavarian manufacturing clusters. EU RoHS substance restrictions govern solder alloy selection and material disclosure documentation. Calibration system procurement in Stuttgart prioritizes ISO/IEC 17025 traceable chains for automotive powertrain efficiency mapping.
China
MIIT industrial digitization directives accelerate edge-computing sensor node deployment in Yangtze River Delta manufacturing zones. GB standards for electromagnetic compatibility constrain Ethernet-connected card designs near radio-frequency equipment. Shenzhen-based automation OEMs specify ruggedized embedded form factors for machine control cabinet integration.
Japan
METI precision manufacturing initiatives sustain metrology-grade installation demand in Nagoya and Osaka industrial corridors. JIS calibration standards enforce NIST-traceable uncertainty budgets for RF component characterization laboratories. Yokogawa Electric Corporation anchors domestic supply relationships through precision instrumentation service networks.
Data Acquisition Card Market Vendor Landscape
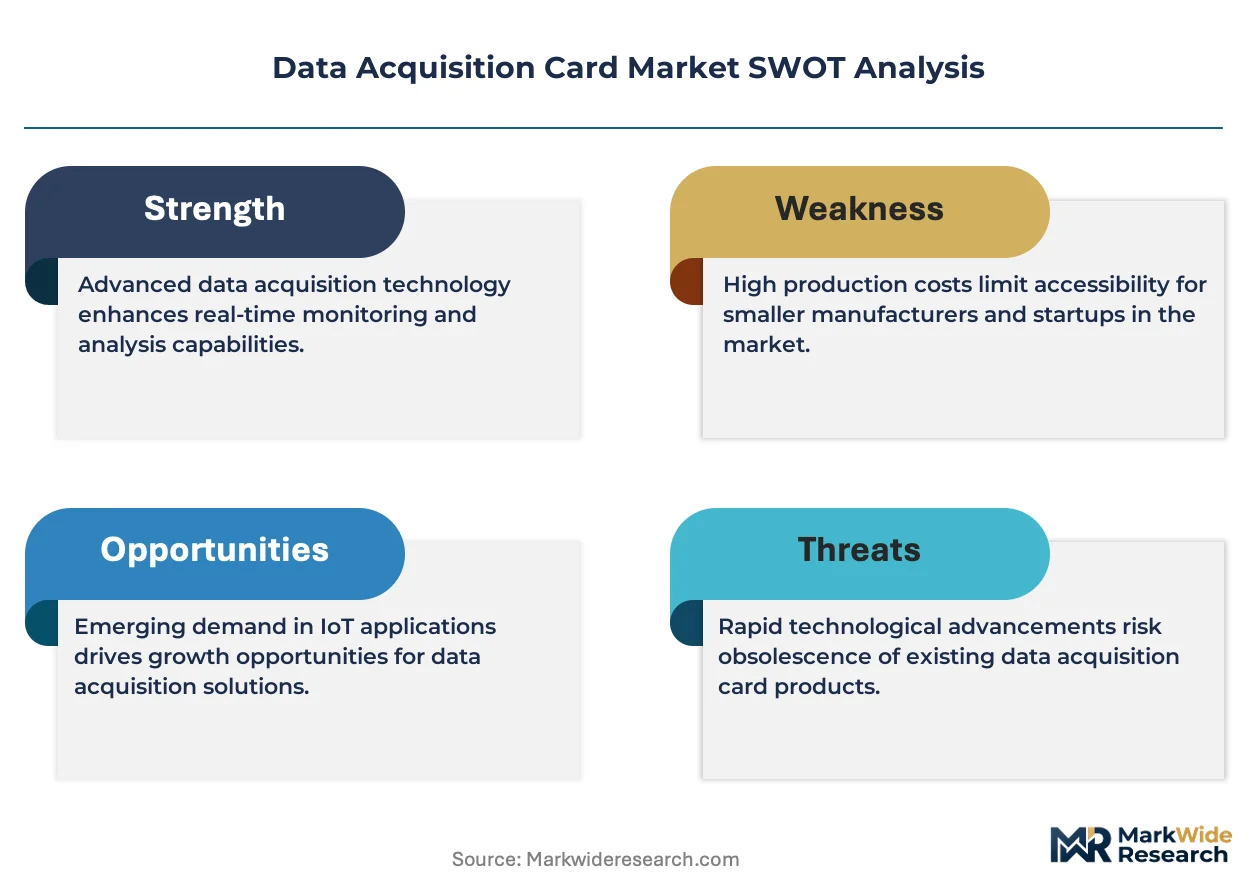
Platform integrators command the system tier; component specialists sit upstream supplying analog-to-digital converter modules and signal conditioning subassemblies. The vendor base stratifies across three tiers: chassis-based modular platform providers, software-defined instrumentation stacks, and ruggedized embedded form factor fabricators. Consolidation pressure concentrates among mid-range card portfolios where analog-to-digital converter silicon sourcing creates margin compression. Strategic moves cluster on technology licensing partnerships and geographic expansion into underpenetrated academic segments.
Among platform integrators, National Instruments Corporation and Keysight Technologies exemplify the software-defined instrumentation archetype where recurring analytics licensing decouples from hardware commitments. Advantech Co. Ltd. occupies the ruggedized embedded tier, anchoring factory-floor deployments through DIN-rail and PCB-mount form factors. These three companies collectively represent the competitive vectors reshaping procurement patterns across automotive validation, industrial automation, and telecommunications metrology verticals.
| Leading Market Players |
|---|
| National Instruments Corporation |
| Keysight Technologies |
| Advantech Co. Ltd. |
| Measurement Computing Corporation |
| ADLINK Technology |
| Yokogawa Electric Corporation |
| Teledyne Technologies |
| Siemens AG |
| AMETEK Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese analog-to-digital converter foundries determines both tiered pricing spreads across certification grades and the geographic shape of upstream procurement networks. This concentration forces tiered pricing stratification across premium metrology-grade, standard industrial-grade, and economy academic-grade levels while tethering supply security to semiconductor fabrication capacity allocation decisions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels where ISO/IEC 17025 calibration traceability and PCIe interface performance stratify quotations. Price differentiation centers on certification grade and channel density scale, with metrology-grade installations commanding substantial premiums over benchtop USB alternatives. Pricing pressure stems from analog-to-digital converter silicon cost volatility concentrated in Taiwanese foundries, compressing margins on mid-range card portfolios. Academic institutions exhibit highest price sensitivity due to capital budget constraints, while automotive validation laboratories absorb premiums for sub-millisecond latency specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for Ethernet-connected card assemblies and embedded form factor production. Manufacturing concentrates in Taiwan for precision ADC silicon, China for PCB fabrication and final assembly, and Germany for calibration system integration. Raw material dependencies include high-purity copper for signal integrity layers, specialized solder alloys compliant with EU RoHS restrictions, and conformal coating chemistries free of ECHA substances of very high concern. Distribution runs through direct OEM procurement channels for high-volume automotive contracts and specialized instrumentation distributors for academic and research laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Acquisition Card Market is entering a cyclical recovery phase as automotive electrification programs accelerate powertrain validation spend and industrial automation clusters consolidate sensor networks onto unified acquisition platforms.
For Market Incumbents: Entrench software-defined instrumentation moats through recurring analytics licensing decoupled from hardware commitments, while deepening backward integration into precision ADC module design to offset foundry pricing volatility. Prioritize calibration service network expansion in Stuttgart and Detroit to capture ISO/IEC 17025-driven replacement cycles.
For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated academic segment through USB-interfaced portable systems with open driver architectures that reduce vendor lock-in risk. Target university research laboratories in the US National Laboratory system with subscription-tier analytics platforms. Pursue a channel partnership strategy with specialized instrumentation distributors rather than direct OEM sales.
For Investors and Strategic Acquirers: EPA emissions protocol stringency reshapes the acquisition landscape toward calibration-intensive service capabilities and high-channel-count PCIe module specialists. Frame long-term viability around 5-10 year automotive electrification program timelines where electric powertrain validation demands sustained instrumentation investment. Target acquisition archetypes: software-defined instrumentation stacks with recurring revenue profiles. Watch for IEEE 802.1AS time-sensitive networking adoption rates as inflection indicators for chassis-based synchronization module displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Instrumentation Platform | Recurring analytics licensing from National Instruments decouples revenue from hardware replacement cycles. |
| Precision Calibration Service Network | Keysight's ISO/IEC 17025 traceable chains capture automotive powertrain efficiency mapping contracts in Stuttgart. |
| Ruggedized Embedded Form Factor Expansion | Advantech's DIN-rail and PCB-mount cards penetrate Bavarian machine control cabinet integration. |
| Time-Sensitive Networking Integration | IEEE 802.1AS-synchronized Ethernet cards collapse premiums for chassis-based synchronization in Michigan test rigs. |
| Asset-Light Leasing Model | High-channel-count system rentals penetrate aerospace program development cycles where capital flexibility outweighs ownership. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC instrument manufacturer filings, EU regulatory substance databases, and automotive OEM procurement disclosures. Primary interviews engaged test equipment engineering directors, automotive validation laboratory managers, industrial automation procurement leads, and academic research facility administrators. Secondary validation drew from EPA emissions protocol documentation, ISO/IEC calibration standard repositories, and semiconductor foundry capacity reports. Bottom-up channel checks across PXI chassis deployments and PCIe module shipments triangulate against top-down instrumentation market sizing.
Forecast inputs incorporate interface technology adoption curves, end-use vertical channel density requirements, and regional regulatory compliance timelines across the analysis window. Segmentation dimensions modeled include product type tier, interface standard, form factor integration depth, and end-user calibration rigor. CAGRs derive from installed base replacement cycle analysis and greenfield deployment pipeline assessment. Electric powertrain validation program timelines and industrial sensor network densification rates inform trajectory assumptions.
Stress conditions across analog-to-digital converter foundry capacity allocation, EPA protocol amendment timelines, and EU RoHS substance restriction expansions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding automotive electrification spend persistence and industrial automation capital deployment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Europe PCB Market
Electronic Components
Hydrogen Thyratron Market
Electronic Components
Electronic Wipe Market
Electronic Components
Global Suction Tube Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Crystal Oscillators Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Power Resistor Market
Electronic Components
Cordless Phone Battery Market
Electronic Components
Digital Isolator Market
Electronic Components
USB Wall Charger Market