
 Fuse Bases Market | 2026-2036
Fuse Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Fuse Bases Market Analysis
The capability gap between vertically integrated manufacturers and assembly-only suppliers is collapsing as raw material volatility and precision molding requirements reshape entry economics. Eaton leverages captive ceramic compounding and in-house metallization to sustain margin stability across high-voltage fuse block lines. Siemens anchors its European position through DIN-rail-integrated fuse holder systems purpose-built for industrial control panels. Mersen competes on specialized graphite-composite fuse bases that tolerate extreme thermal cycling in semiconductor fabrication facilities.
A fuse base is a mechanical support structure that secures a fuse element within an electrical circuit, typically manufactured from thermoset plastics, engineered ceramics, or metal alloys rated for specific dielectric strength and thermal endurance. Its primary purpose is to maintain precise contact pressure, ensure safe arc quenching during fault interruption, and enable tool-free replacement in distribution panels and switchgear assemblies. Ceramic fuse bases command premium positioning in medium-voltage industrial applications where arc-track resistance and dimensional stability under thermal shock determine service life. Plastic fuse holders dominate volume production for low-voltage consumer electronics and appliance protection, though margin pools are thinning as commodity polyamide compounds face cost pressure. Panel mount installation types retain the largest revenue share across utility and infrastructure end uses, while PCB mount configurations are gaining traction in power electronics and renewable energy inverter designs.
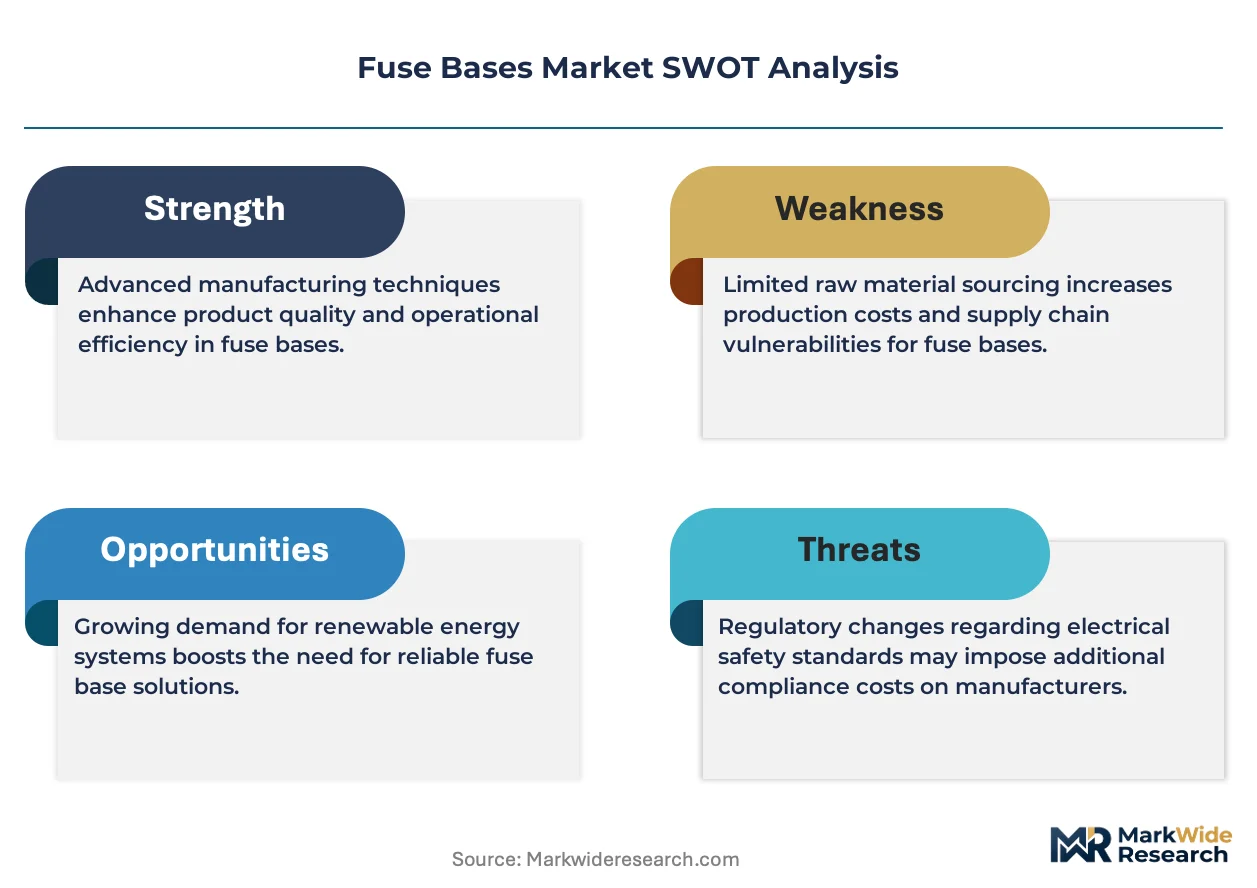
UL 248 and IEC 60269 standards govern fuse base construction, testing protocols, and regional market access, with UL certification mandatory for North American electrical distribution equipment and IEC compliance required across European Union member states. The EPA's emerging rules on per- and polyfluoroalkyl substances are pressuring manufacturers to reformulate certain high-performance plastic compounds used in arc-resistant fuse housings. China's GB standards and NMPA-aligned quality supervision protocols add a third certification layer for suppliers serving state grid tenders and rail infrastructure projects. Stakeholders must monitor how evolving fire-safety regulations and material restriction frameworks in multiple jurisdictions will reshape supplier qualification timelines and testing cost structures.
Market Dynamics
Raw material volatility and precision molding requirements are collapsing the capability gap between vertically integrated manufacturers and assembly-only suppliers, reshaping entry economics across fuse base production.
Growth Catalysts
- IEC 60269 Standard Harmonization:Tighter certification requirements in European Union member states are consolidating demand around qualified suppliers capable of multi-jurisdictional compliance.
- Grid Modernization Infrastructure:Utility-scale distribution panel upgrades across Germany and the United States are accelerating replacement cycles for medium-voltage ceramic fuse bases.
- Electric Vehicle Manufacturing Clusters:High-voltage battery protection requirements in China's automotive production zones are pulling specialized fuse holder designs into volume production.
Market Restraints
- Ceramic Raw Material Concentration:Alumina and zirconia supply concentrates in Chinese processing facilities, exposing European and North American molders to freight cost volatility and tariff exposure.
- EPA PFAS Restrictions:Emerging rules on per- and polyfluoroalkyl substances are forcing reformulation of arc-resistant thermoplastic compounds used in high-performance fuse housings.
- Commodity Polyamide Cost Pressure:Standard plastic fuse holders face margin compression as base resin prices fluctuate with petrochemical feedstock markets.
Strategic Opportunities
- Renewable Energy Inverter Integration:PCB mount fuse configurations are penetrating solar and wind power electronics as converter densities increase.
- India PLI Scheme Alignment:Domestic manufacturing incentives for electrical equipment are creating localized supply opportunities for fuse base producers serving state grid tenders.
- Semiconductor Fabrication Thermal Cycling:Graphite-composite fuse bases tolerating extreme temperature swings address unmet demand in cleanroom power distribution systems.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Simultaneous UL 248, IEC 60269, and GB standard compliance extends product qualification cycles by 8-14 months.
- Precision Metallization Skill Scarcity:In-house contact plating and conductive surface engineering capabilities remain concentrated among legacy European and Japanese suppliers.
- Legacy Panel Integration Complexity:DIN-rail and chassis-mount fuse holders must maintain mechanical compatibility with decades-old switchgear footprints while delivering modern arc-quenching performance.
Report Scope
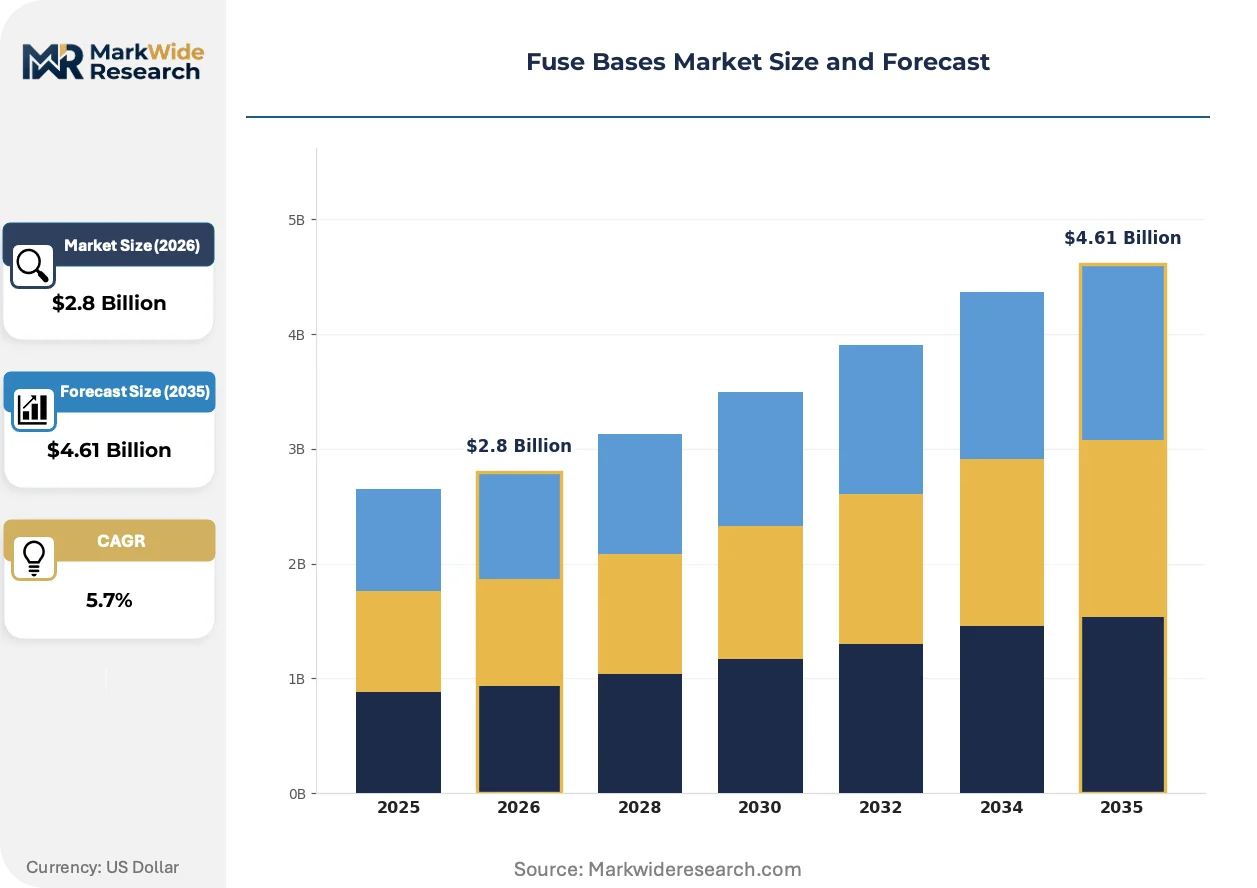
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuse Bases Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuse Holders, Fuse Blocks, Fuse Clips, Fuse Accessories Material: Plastic, Metal, Ceramic, Composite Installation Type: Panel Mount, Surface Mount, PCB Mount, Inline Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Eaton, Siemens, Littelfuse, Schneider Electric, Mersen, EFEN GmbH, Socomec Group, DF Electric, Pronutec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuse Bases Market Emerging Trajectories
Material science advances and regulatory tightening are converging to elevate performance specifications across fuse base categories while compressing acceptable qualification timelines for new product introductions.
Engineered ceramic compounds with tailored dielectric strength and thermal shock resistance are supplanting conventional alumina formulations in medium-voltage industrial applications. Semiconductor fabrication facilities and heavy-motor control centers are adopting these materials fastest. The shift is compressing acceptable service life metrics and forcing commodity ceramic suppliers toward specialty compounding partnerships.
REACH substance restrictions and RoHS material declarations are tightening disclosure requirements for plastic fuse housing formulations across European industrial supply chains. Compounders must now document full material content down to 0.1% threshold concentrations. Automotive and appliance OEMs serving EU markets are accelerating qualification of halogen-free thermoplastic alternatives.
Direct procurement relationships between fuse base specialists and renewable energy inverter OEMs are displacing traditional electrical distributor intermediaries in high-reliability segments. Tier-one solar and wind equipment manufacturers now specify custom PCB mount configurations through engineering collaboration rather than catalog selection. This pattern concentrates most visibly in German and Danish offshore wind supply chains.
Fuse Bases Market Segmentation
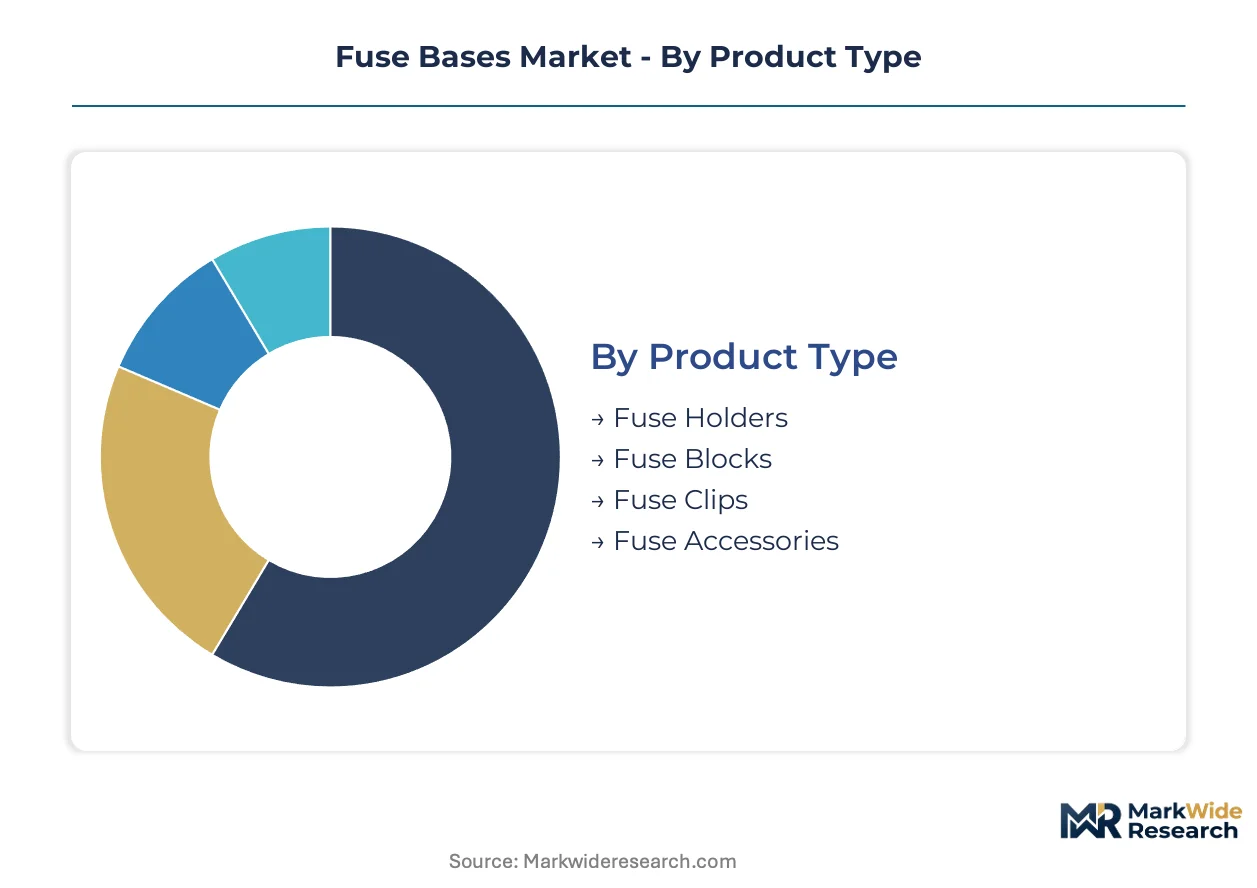
Segmentation in fuse bases reflects divergent technical requirements across industrial automation, automotive electrification, and grid infrastructure end uses. Each dimension—product architecture, material composition, mounting geometry, and electrical rating—carries distinct procurement patterns and margin structures that reshape supplier positioning.
Product Type:
Domestic production clusters in Germany and China dominate fuse holder and fuse block supply, while fuse clips and accessories draw more heavily from export-oriented Southeast Asian assembly operations.
- Fuse Holders:Enclosed housings with integrated contact springs designed for tool-free fuse replacement in distribution panels. Demand concentrates in Germany's industrial automation corridor where DIN-rail integration and IP20 finger-safety specifications dominate procurement criteria.
- Fuse Blocks:Modular terminal assemblies supporting multiple fuse positions in switchgear assemblies. China's electric vehicle manufacturing zones are pulling specialized high-voltage block designs into volume production as battery pack protection requirements tighten.
- Fuse Clips:Spring-retention contacts for chassis-mounted fuse installation.
- Fuse Accessories:Covers, indicators, and busbar adapters completing fuse base systems.
Fuse blocks hold the largest share; momentum sits with fuse holders as DIN-rail standardization expands beyond European borders.
Material:
Cost tier stratification separates commodity thermoplastics from engineered ceramics, with metal alloys and graphite composites occupying intermediate premium positioning.
- Ceramic:Engineered alumina and zirconia compounds rated for arc-track resistance and thermal shock endurance in medium-voltage industrial applications. Semiconductor fabrication facilities in Japan and South Korea specify these formulations for cleanroom power distribution where dimensional stability under thermal cycling determines service life.
- Plastic:Polyamide and thermoset molding compounds dominating low-voltage consumer electronics and appliance protection. REACH substance restrictions and EPA PFAS rules are forcing reformulation of arc-resistant thermoplastic formulations across European and North American supply chains.
- Metal:Brass and copper alloy fuse bases with machined contact surfaces for high-current industrial switchgear.
- Composite:Graphite-polymer blends tolerating extreme temperature swings in heavy-motor control centers.
Ceramic commands the highest unit economics; plastic maintains volume leadership though margin pools are thinning.
Installation Type:
Application geometry dictates procurement channel—utility and infrastructure buyers favor panel mount through electrical distributors, while power electronics OEMs source PCB mount configurations through direct engineering collaboration.
- Panel Mount:Chassis-integrated fuse bases secured through screw or snap-fit mechanisms in distribution panels and switchgear enclosures. Utility-scale grid modernization programs across the United States and Germany are accelerating replacement cycles for these configurations.
- PCB Mount:Surface-soldered fuse holders for printed circuit board integration in power electronics. Renewable energy inverter OEMs in Denmark and Germany now specify custom PCB mount geometries through direct procurement relationships rather than catalog selection.
- Surface Mount:Low-profile fuse bases for compact electronic assemblies.
- Inline:Cable-integrated fuse holders for harness protection in automotive and appliance applications.
Panel mount retains the largest revenue base; PCB mount is climbing the fastest as converter densities increase in solar and wind power electronics.
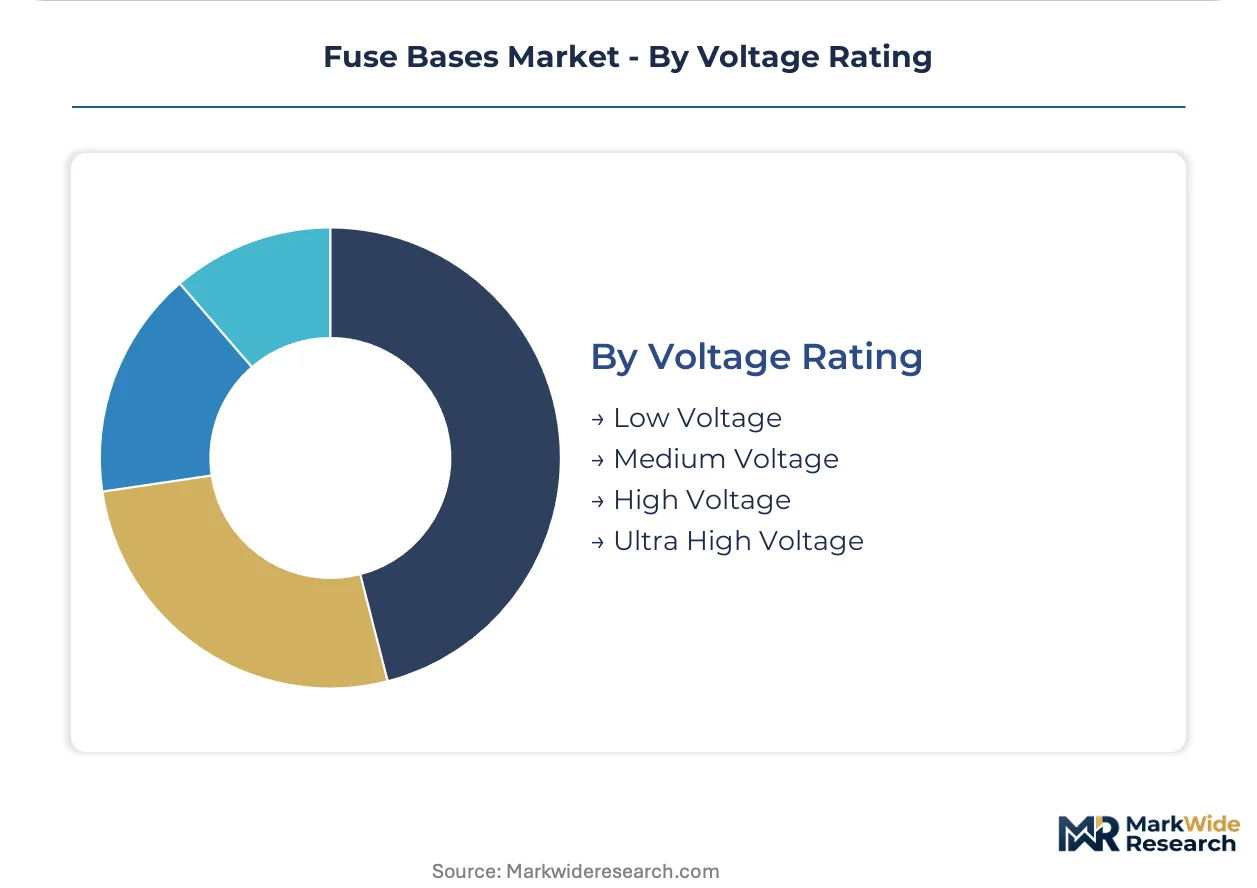
Voltage Rating:
Customer type bifurcation separates mass-market low-voltage supply from engineered medium and high-voltage segments requiring specialized certification and metallization capabilities.
- Medium Voltage:Fuse bases rated for distribution-level interruption in industrial motor control and substation applications. IEC 60269 standard harmonization is consolidating European demand around qualified suppliers capable of multi-jurisdictional compliance for these ratings.
- Low Voltage:Consumer electronics, appliance, and automotive fuse bases below 1kV rating. India's PLI scheme for electrical equipment is creating localized supply opportunities for producers serving state grid tenders in this category.
- High Voltage:Battery pack and traction system protection in electric vehicle manufacturing.
- Ultra High Voltage:Specialized fuse bases for transmission infrastructure and grid-scale energy storage.
Low voltage dominates unit shipments; medium voltage captures the steepest expansion trajectory as industrial automation and grid modernization programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's electric vehicle manufacturing zones exhibit the lowest price elasticity, absorbing premium fuse base specifications for high-voltage battery protection. German industrial automation purchasers show moderate sensitivity, prioritizing DIN-rail integration and multi-jurisdictional certification over unit cost minimization. India's state grid tenders operate at the highest elasticity, with domestic PLI scheme beneficiaries competing aggressively on landed cost.
United States
Utility-scale distribution panel upgrades accelerate replacement cycles for medium-voltage ceramic fuse bases. EPA PFAS restrictions force reformulation of arc-resistant thermoplastic compounds in fuse housings. Texas and California grid modernization programs concentrate procurement volumes for panel mount configurations serving substation infrastructure.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg drive DIN-rail-integrated fuse holder specifications for control panel applications. IEC 60269 standard harmonization consolidates demand around qualified suppliers capable of multi-jurisdictional compliance. Offshore wind supply chains in northern coastal states specify custom PCB mount geometries through direct engineering collaboration.
China
Electric vehicle manufacturing clusters in Shanghai and Guangdong pull specialized high-voltage fuse block designs into volume production. NMPA-aligned quality supervision protocols add certification layers for suppliers serving state grid tenders and rail infrastructure projects. Yangtze River Delta semiconductor fabrication facilities specify graphite-composite fuse bases for cleanroom power distribution.
Japan
Semiconductor fabrication facilities in Kyushu and Kansai regions demand engineered ceramic fuse bases with dimensional stability under thermal cycling. METI industrial standards govern fuse base construction and testing protocols for domestic market access. Tokyo-Osaka industrial corridors concentrate precision metallization capabilities for contact plating and conductive surface engineering.
India
Domestic manufacturing incentives under the PLI scheme for electrical equipment create localized supply opportunities for fuse base producers. BIS certification requirements and CEA grid codes shape product qualification timelines for state grid tenders. Maharashtra and Gujarat industrial zones concentrate assembly operations for low-voltage plastic fuse holders serving appliance and automotive markets.
Fuse Bases Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across fuse base production. Vertically integrated manufacturers with captive ceramic compounding and in-house metallization capabilities command premium positioning in medium-voltage industrial segments. Assembly-only suppliers compete on volume throughput for standardized low-voltage plastic configurations. Three archetypes dominate: integrated material-compounders, precision metallization specialists, and scale-driven contract manufacturers. Competitive moves concentrate on strategic partnerships for raw material security and portfolio diversification into renewable energy inverter specifications.
Within the integrated material-compounder tier, Eaton and Mersen exemplify archetypes combining upstream ceramic control with downstream fuse base engineering. Siemens GmbH anchors European positioning through DIN-rail system integration. These three occupy positions where captive supply chains and multi-jurisdictional certification capabilities create defensive moats against commodity competition.
| Leading Market Players |
|---|
| Eaton |
| Siemens |
| Littelfuse |
| Schneider Electric |
| Mersen |
| EFEN GmbH |
| Socomec Group |
| DF Electric |
| Pronutec |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Chinese alumina and zirconia processing facilities shapes both supply concentration and price floors across ceramic fuse base tiers. European molders face freight cost volatility and tariff exposure that compress margins on medium-voltage industrial configurations, while assembly-only suppliers in Southeast Asia compete on volume throughput for standardized plastic holders.
Pricing Analysis
After-sales service contracts and technical support agreements drive lifetime value for integrated manufacturers with captive ceramic compounding capabilities. Three-tier pricing structure across premium, standard, and economy levels separates DIN-rail-integrated systems from commodity panel mount configurations. Cost compression in plastic fuse holders is intensifying because REACH substance restrictions and EPA PFAS rules force reformulation of arc-resistant thermoplastic compounds. State grid tenders in India exhibit the highest price sensitivity, while semiconductor fabrication facilities in Japan and South Korea absorb premium specifications with minimal elasticity.
Supply Chain Analysis
China dominates alumina and zirconia processing for engineered ceramic fuse bases, while Germany anchors precision metallization capabilities for contact plating and conductive surface engineering. Raw material dependencies rest on alumina and zirconia supply from Chinese facilities, polyamide and thermoset compounds from petrochemical feedstock markets, and brass and copper alloys for high-current industrial switchgear. Tariff exposure and freight cost volatility present structural risks for European and North American molders. Distribution runs through electrical distributors for utility and infrastructure buyers, while power electronics OEMs source PCB mount configurations through direct engineering collaboration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuse bases market represents an early-cycle expansion story. Grid modernization programs across Germany and the United States accelerate replacement cycles for medium-voltage ceramic configurations, while electric vehicle manufacturing clusters in China pull specialized high-voltage designs into volume production.
For Market Incumbents: Consolidate defensive positioning through backward integration into captive ceramic compounding and in-house metallization capabilities. Capacity addition in India's PLI scheme-aligned manufacturing zones addresses emerging localized supply opportunities. Certification investment for simultaneous UL 248, IEC 60269, and GB standard compliance creates barriers against assembly-only competitors.
For New Entrants and Emerging Players: After-sales technical support and rapid customization services present entry vectors where integrated incumbents under-serve mid-tier industrial automation buyers. India's state grid tenders offer the most penetrable geography given aggressive landed cost competition among PLI beneficiaries. A go-to-market angle anchored in halogen-free thermoplastic alternatives addresses REACH and RoHS disclosure requirements across European supply chains.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with multi-jurisdictional certification capabilities and captive raw material control. Long-term viability rests on defensive moats against commodity competition in medium-voltage industrial segments. The signal to monitor is direct procurement relationship formation between fuse base specialists and renewable energy inverter OEMs displacing traditional distributor intermediaries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Compounding | Captive alumina and zirconia supply insulates margin stability against Chinese processing concentration. |
| Multi-Jurisdictional Certification Investment | Simultaneous UL 248, IEC 60269, and GB compliance extends product qualification cycles but locks out competitors. |
| Direct Procurement Relationships with Inverter OEMs | Engineering collaboration with Danish and German offshore wind suppliers displaces distributor intermediaries. |
| Halogen-Free Thermoplastic Reformulation | REACH substance restrictions and EPA PFAS rules force disclosure documentation down to 0.1% thresholds. |
| Localized Manufacturing in PLI-Aligned Zones | India's domestic incentives for electrical equipment create supply opportunities for state grid tenders. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IEC and UL standard documentation, customs and trade data for ceramic raw material flows, and SEC filings from electrical equipment manufacturers. Primary interviews engaged plant engineers at semiconductor fabrication facilities, procurement leads at renewable energy inverter OEMs, distribution channel partners serving utility infrastructure, and technical R&D directors at ceramic compounders. Bottom-up triangulation across product type, material composition, and installation geometry segments validates top-down market sizing.
Segmentation dimensions modeled include product architecture, material composition, mounting geometry, and voltage rating across the projection horizon. CAGRs derive from penetration curve analysis for PCB mount configurations in power electronics and replacement cycle acceleration for panel mount installations in grid modernization programs. Industry-specific forecast inputs incorporate IEC 60269 standard harmonization timelines and electric vehicle battery pack protection requirement trajectories.
Underlying assumptions cover grid modernization program continuity, ceramic raw material supply stability, and regulatory restriction implementation pace, with deviation risk concentrated in tariff policy shifts and PFAS rule enforcement timelines. Recalibration cycles align with material shifts in renewable energy inverter procurement patterns and semiconductor fabrication facility expansion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Coaxial Coupler Market
Electronic Components
Capacitor Kits Market
Electronic Components
AC Adapter Market
Electronic Components
VPX SBC Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Audio DSP Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Encoder Market
Electronic Components
Frequency Control and Timing Devices Market
Electronic Components
USB Wall Charger Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Data Bus Market
Electronic Components
Astable Multivibrator Market