
 Dark Beer Market | 2026-2036
Dark Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Beer Market Analysis
The EU Green Deal is decoupling dark beer production from conventional carbon-intensive malting. Heineken leverages vertical integration across European barley belts to secure low-carbon malt supply. Carlsberg Breweries anchors its competitive position through advanced water-recovery systems at Danish facilities. Anheuser-Busch InBev competes via manufacturing scale that compresses per-unit energy across multi-brand dark beer portfolios.
Dark beer encompasses roasted-malt beverages with color ratings exceeding 25 SRM, produced through kilned or roasted barley additions that generate chocolate, coffee, and caramel flavor compounds for commercial consumption. Stout dominates volume through established Irish and American craft lineages, while Porter captures premium margin pools among connoisseurs seeking historical recipe authenticity. Schwarzbier maintains steady German demand, though Dunkel shows faster growth in North American craft channels where lager education expands.
Germany's BfR evaluates acrylamide thresholds in roasted malts, while the FDA enforces gluten-labeling standards that shape formulation choices for US-export dark beers. The EU's CSRD extends emissions disclosure to mid-tier breweries, tightening access for non-compliant imports. Stakeholders must monitor evolving malt-roasting regulations that could force capital retooling or geographic sourcing shifts without warning.
Market Dynamics
The EU Green Deal's brewing sustainability mandates are forcing capital retooling across malting operations, with carbon accounting requirements now extending to mid-tier breweries through the CSRD disclosure framework.
Growth Catalysts
- EU Green Deal compliance:Mandatory emissions disclosure is accelerating brewery investment in low-carbon malt sourcing and energy recovery systems.
- Craft connoisseur demand:Premium positioning around barrel-aged stouts and historical porter recipes is commanding margin premiums in specialty channels.
- German lager education:North American craft distributors are expanding Dunkel and Schwarzbier portfolios as consumer familiarity with dark lager styles deepens.
Market Restraints
- Acrylamide threshold uncertainty:Germany's BfR evaluates roasted malt safety limits that could force reformulation or sourcing shifts without warning.
- Barley belt concentration:Low-carbon malt supply concentrates in vertically integrated European grain corridors, limiting options for independent breweries.
- Gluten-labeling friction:FDA enforcement of allergen standards complicates US export formulations for traditional wheat-inclusive dark beer styles.
Strategic Opportunities
- Water-stressed brewing regions:Advanced water-recovery technologies open positioning in drought-affected production zones where efficiency differentiates supply security.
- Historical recipe authenticity:Porter's documented 18th-century brewing records enable heritage marketing that commands connoisseur premiums.
- Carbon border adjustments:EU import tariffs on carbon-intensive goods create competitive shelter for compliant European dark beer producers.
Industry Challenges
- Malting skill scarcity:Specialized knowledge in low-carbon kiln operation and roast profile control concentrates among aging European technicians.
- CSRD compliance timeline:Mid-tier breweries face compressed reporting deadlines for Scope 3 emissions across agricultural supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Beer Market |
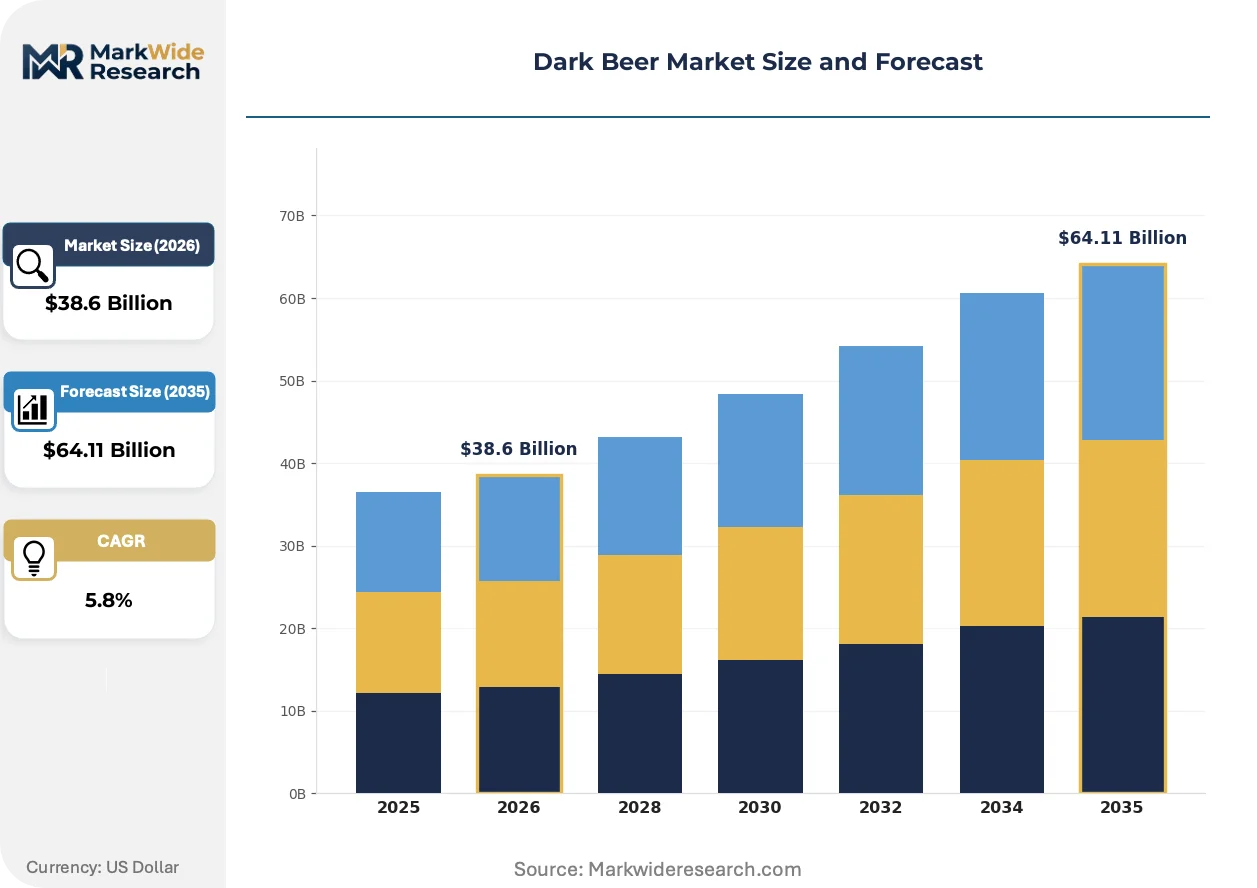
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stout, Porter, Dunkel, Schwarzbier Distribution Channel: Retail Stores, Online, Bars, Breweries Customer Type: Craft Beer Enthusiasts, Casual Drinkers, Connoisseurs, Event Attendees Price Tier: Premium, Mid-Range, Economy, Luxury |
| Companies Covered | Carlsberg Breweries, Kirin Holdings, Anheuser-Busch InBev, The Boston Beer Company, Asahi Group Holdings, Diageo, Molson Coors, Stone Brewing, Heineken, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Beer Market Emerging Trajectories
Dark beer production is converging around precision kilning technology and sustainability-verified sourcing, with regulatory pressure and craft authenticity demands reshaping competitive requirements simultaneously.
Precision kilning control systems are integrating machine-learning roast profile optimization to stabilize color ratings above 25 SRM while minimizing acrylamide formation. German and Czech maltsters are deploying these systems most aggressively to preempt BfR threshold enforcement. The technology is integrating quality consistency with regulatory risk mitigation across premium dark beer portfolios.
CSRD emissions disclosure mandates are extending sustainability reporting to breweries below previous turnover thresholds, tightening capital access for non-compliant imports. Mid-tier European producers face accelerated audit requirements for agricultural supply chains. Irish stout exporters and American craft porter specialists are restructuring EU market entry strategies around third-party carbon verification.
Direct-to-connoisseur subscription channels are displacing traditional three-tier distribution for limited barrel-aged releases. American craft enthusiasts now source vintage-dated stouts through producer-managed allocation systems rather than retail. This pattern concentrates in coastal metropolitan markets where education around dark beer style taxonomy has matured fastest.
Dark Beer Market Segmentation
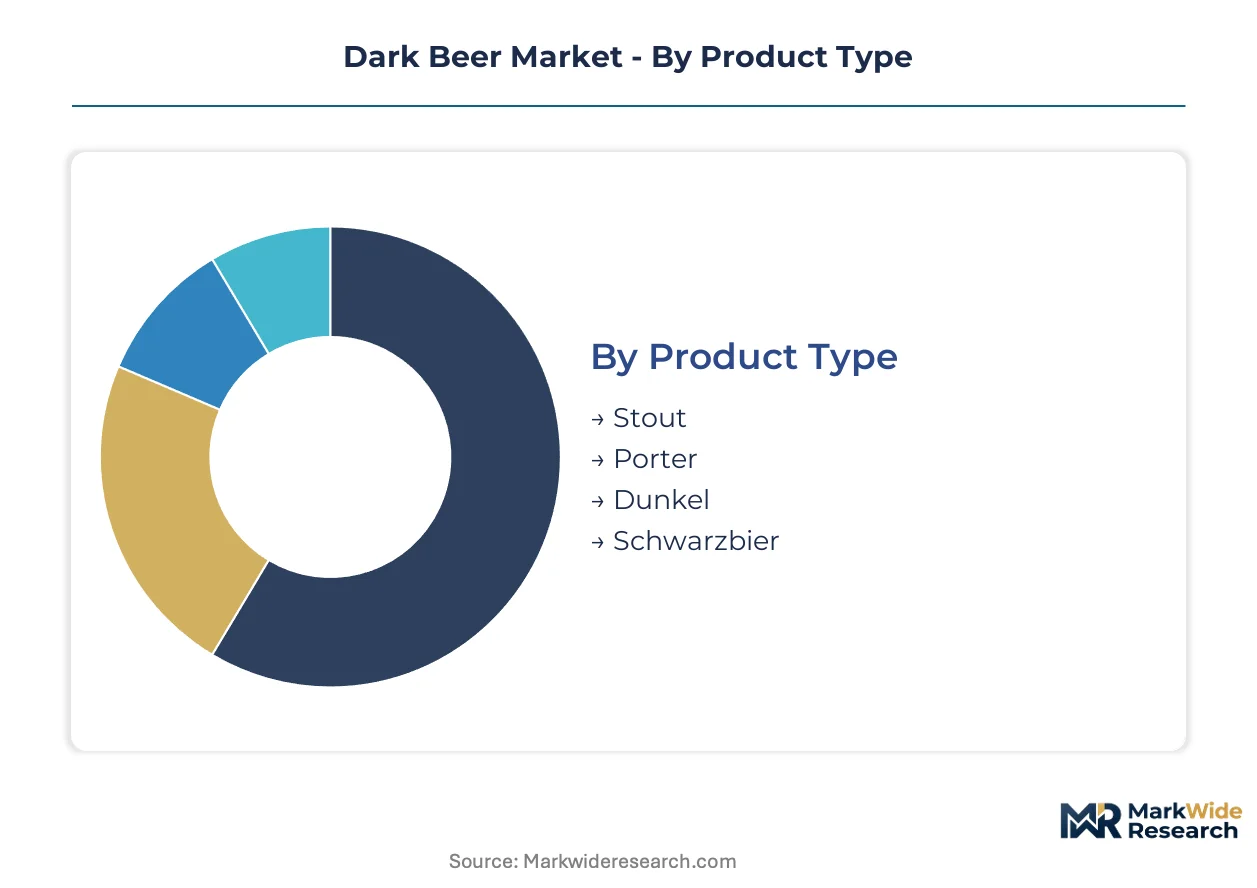
Dark beer segmentation reveals divergent margin architectures across product categories and channel strategies. The volume-premium split determines capital allocation between mass-market efficiency plays and craft authenticity investments.
Product Type:
Volume leadership concentrates in established stout lineages, while premium expansion flows through historical recipe categories commanding connoisseur pricing power.
- Stout:Roasted barley formulations above 25 SRM deliver coffee and chocolate flavor compounds through kilned malt additions. Demand concentrates in Ireland and American craft corridors where barrel-aging programs anchor limited-release calendars.
- Porter:Historical 18th-century brewing documentation enables heritage positioning among authenticity-seeking consumers. Growth is accelerating in North American specialty channels where distributors emphasize style education.
- Dunkel:Munich-style dark lager with melanoidin-rich malt profiles.
- Schwarzbier:German black lager tradition maintaining steady Reinheitsgebot-compliant production.
Mature deployment sits with Stout. Newer deployment is concentrated in Porter.
Distribution Channel:
Channel strategy reflects the tension between three-tier regulatory compliance and direct-to-consumer margin capture in specialty segments.
- Retail Stores:Off-premise volume concentration for standard-strength dark lagers and mainstream stout portfolios. Shelf placement competition intensifies as craft SKUs proliferate in conventional grocery.
- Online:Subscription allocation systems for vintage-dated barrel-aged releases now dominate limited porter and imperial stout distribution. Coastal metropolitan markets show fastest platform adoption.
- Bars:Draft program differentiation through rotating dark beer handles.
- Breweries:Taproom direct sales capturing margin from tasting-room visitors.
Scale advantages concentrate in Retail Stores. Margin expansion is accelerating through Online.
Customer Type:
Customer segmentation maps directly to pricing architecture, with knowledge depth determining willingness to pay for provenance and production method transparency.
- Craft Beer Enthusiasts:Style taxonomy fluency drives demand for limited releases and experimental roast profiles. This segment commands producer investment in educational content and vertical tasting formats.
- Connoisseurs:Historical authenticity requirements and vintage-dated vertical collections define purchasing behavior. Allocation systems and membership tiers structure access to rare barrel-aged portfolios.
- Casual Drinkers:Approachable dark lager introductions.
- Event Attendees:Festival and tasting event trial conversion.
Volume concentration rests with Casual Drinkers. Premium deployment is deepening among Connoisseurs.
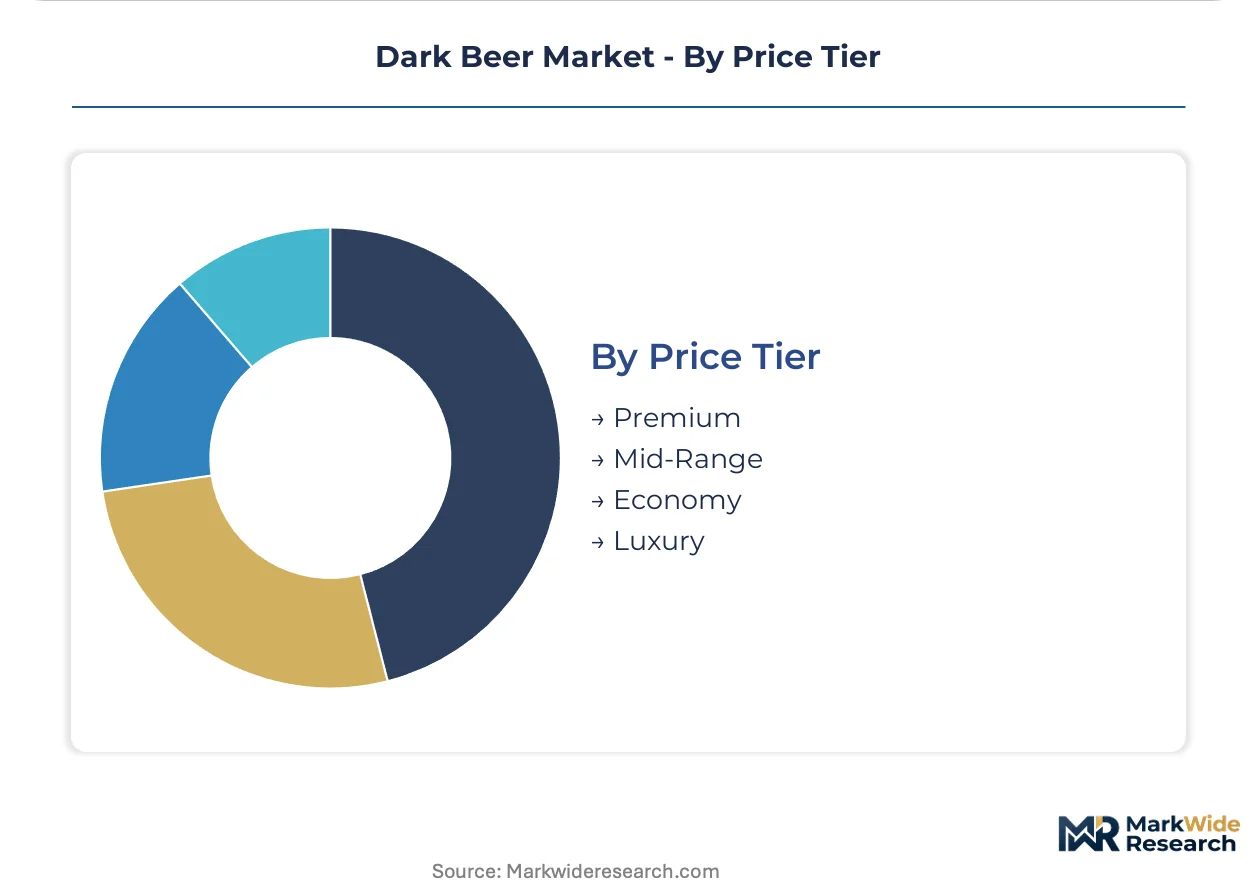
Price Tier:
Price architecture stratifies across production method certification, ingredient provenance, and release scarcity rather than conventional quality signaling.
- Premium:Craft positioning with transparent malt sourcing and small-batch production claims. CSRD-compliant carbon accounting now differentiates this tier in European markets.
- Luxury:Extended barrel-aging, vintage dating, and allocation scarcity create price inelasticity among collector segments. Direct-to-consumer channels capture margin that three-tier distribution forecloses.
- Mid-Range:Regional craft brands competing on accessibility.
- Economy:Mass-market dark lager price points.
Mainstream volume anchors in Mid-Range. Steepest expansion trajectory is concentrating in Luxury.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European dark beer innovation through its Reinheitsgebot heritage and melanoidin-rich Dunkel production corridors. The city's brewing cluster integrates traditional kilning methods with precision roast control systems demanded by modern sustainability frameworks.
Germany
German craft enthusiasts drive demand for Schwarzbier and barrel-aged Baltic porters in Berlin and Hamburg specialty channels. The BfR evaluates acrylamide thresholds in roasted malts, forcing maltsters toward machine-learning kiln optimization. Bavaria's Munich-Upper Palatinate corridor concentrates precision malting facilities serving both domestic brewers and export markets.
United States
American connoisseurs command premium pricing for vintage-dated imperial stouts through direct-to-consumer allocation systems. The FDA enforces gluten-labeling standards that complicate traditional wheat-inclusive porter formulations. Coastal metropolitan markets in California and Oregon anchor the fastest-growing subscription channels for limited barrel-aged releases.
Ireland
Irish stout heritage sustains volume leadership through established dry stout lineages with roasted barley formulations. The EU's CSRD extends emissions disclosure requirements to mid-tier breweries exporting into continental markets. Dublin's brewing cluster maintains competitive positioning through carbon accounting integration across agricultural supply chains.
Japan
Japanese consumers demonstrate growing fluency with dark lager style taxonomy, particularly Dunkel and Czech-inspired tmavé varieties. METI guidelines on food manufacturing sustainability shape malt sourcing transparency requirements for import portfolios. Tokyo and Osaka metropolitan areas concentrate specialty beer bars driving style education and premium pricing acceptance.
United Kingdom
British craft distributors emphasize historical porter authenticity through 18th-century recipe documentation and heritage marketing. REACH compliance obligations affect roasted malt import specifications from continental European suppliers. London's brewing cluster integrates sustainability verification with traditional London porter revival programs targeting connoisseur segments.
Dark Beer Market Vendor Landscape
The competitive structure tilts toward multinational brewing conglomerates with diversified dark beer portfolios spanning stout, porter, and dark lager categories. These scale-driven players compress per-unit energy costs across multi-brand manufacturing networks. Three strategic archetypes dominate: vertically integrated malt-to-glass operators, craft authenticity specialists, and regional dark lager traditionalists. Competitive moves concentrate on sustainability certification acquisition and direct-to-consumer channel development for limited releases.
Among multinational brewing conglomerates, Anheuser-Busch InBev, Heineken, and Carlsberg Breweries exemplify the scale-driven archetype. These companies occupy positions defined by manufacturing breadth and carbon accounting integration across European operations. Heineken represents backward integration into low-carbon barley belts, while Carlsberg Breweries anchors competitive positioning through water-recovery infrastructure. Anheuser-Busch InBev sits within the portfolio diversification tier, leveraging cross-brand manufacturing efficiency.
| Leading Market Players |
|---|
| Carlsberg Breweries |
| Kirin Holdings |
| Anheuser-Busch InBev |
| The Boston Beer Company |
| Asahi Group Holdings |
| Diageo |
| Molson Coors |
| Stone Brewing |
| Heineken |
| Others |
Supply Flow & Price Mechanics
Barley futures pricing on the Euronext exchange cascades through European malting corridors into three-tier pricing structure across premium, standard, and economy levels. Maltsters pass kilning energy costs to brewers, who then stratify finished dark beer pricing by carbon-accounting compliance tier and roast-profile certification.
Pricing Analysis
Value-based pricing anchored to CSRD compliance certification separates premium dark beer tiers from standard formulations. Price differentiation rests on melanoidin concentration thresholds and barrel-aging vintage documentation, with German Reinheitsgebot-compliant products commanding brand premiums. Cost compression in economy lagers intensifies as vertically integrated multinationals squeeze per-unit energy across multi-brand portfolios. Casual drinkers exhibit highest price sensitivity, while connoisseurs demonstrate inelastic demand for allocation-scarce barrel-aged releases.
Supply Chain Analysis
Single-source vulnerability sits with specialty roasted malt supply concentrated in Bavaria and Bohemia. Raw material dependencies center on spring barley varieties, beechwood-smoked malts, and virgin oak cooperage. Tariff exposure runs through EU carbon border adjustment mechanisms threatening non-compliant import competitiveness. Distribution runs through three-tier wholesale networks for standard portfolios, while direct-to-consumer subscription platforms capture margin from limited releases in coastal metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dark beer production is transitioning from conventional kilning to machine-learning roast optimization systems that preempt regulatory acrylamide thresholds. Precision kilning technology is displacing legacy manual malt roasting across European facilities.
For Market Incumbents: Hedge against BfR threshold enforcement by accelerating precision kilning deployment across Bavarian and Czech malting assets. Lock in backward integration into low-carbon barley belts before CSRD disclosure mandates tighten capital access for non-compliant supply chains. Prioritize water-recovery infrastructure investments to defend positioning in drought-affected production zones.
For New Entrants and Emerging Players: Capture white-space opportunity in direct-to-connoisseur subscription channels for vintage-dated barrel-aged porters. Target coastal metropolitan markets in California and Oregon where style education has matured fastest. Enter through heritage recipe authenticity positioning enabled by documented 18th-century brewing records.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European craft breweries with incomplete CSRD compliance infrastructure in Germany and Ireland. Long-term viability hinges on carbon accounting integration across agricultural supply chains. Watch for BfR acrylamide threshold enforcement as inflection indicator triggering forced capital retooling and consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Kilning Technology Deployment | Machine-learning roast optimization preempts BfR regulatory enforcement while stabilizing color ratings above 25 SRM. |
| CSRD Compliance Certification | Carbon accounting disclosure secures capital access and competitive shelter under EU border adjustment mechanisms. |
| Direct-to-Consumer Subscription Launch | Producer-managed allocation systems capture margin foreclosed by traditional three-tier distribution in specialty segments. |
| Heritage Recipe Documentation | Authenticated 18th-century brewing records enable premium positioning among connoisseur segments seeking historical authenticity. |
| Water-Recovery Infrastructure Investment | Advanced recycling systems differentiate supply security in drought-affected brewing regions facing climate stress. |
Methodological Framework
Multi-period observation of malt pricing indices, kilning technology adoption rates, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with master brewers, malting facility operations directors, specialty beer distributors, and craft brewery founders. Secondary validation drew from EU CSRD disclosure databases, BfR safety evaluation registers, FDA gluten-labeling guidance documents, and Euronext agricultural commodity settlement data. Bottom-up volume modeling across product categories triangulated with top-down value projections from trade flow analysis.
Segment-weighting approaches distributed value proportionally across stout, porter, Dunkel, and Schwarzbier categories, with further stratification by distribution channel and customer knowledge tier. CAGRs were derived from trend extrapolation anchored in historical volume trajectories and regulatory implementation timelines. Forecast inputs incorporated precision kilning capital expenditure cycles, barley belt climate yield variability, and connoisseur segment subscription platform adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BfR acrylamide threshold enforcement timing and EU carbon border adjustment rate calibration. Deviation in German regulatory stringency or barley harvest yields would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
East Africa Alcoholic Beverages Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market